
 Optical Spectrum Analyzer (OSA) Market | 2026-2036
Optical Spectrum Analyzer (OSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Spectrum Analyzer (OSA) Market Analytics
Equipment leasing and project-based financing is tilting competitive dynamics toward vendors with asset-light service models. EXFO leverages its rental fleet and calibration infrastructure to sustain recurring revenue in North American telecom test labs. Yokogawa Test & Measurement Corporation anchors its position through in-house production of precision diffraction gratings and detectors. Keysight Technologies competes by extending software-defined measurement architectures that reduce hardware refresh cycles for enterprise buyers.
An optical spectrum analyzer measures power distribution across wavelength, typically resolving 0.01 nm or finer in the 600–1700 nm range using diffraction-grating or interferometric detection to characterize lasers, amplifiers, and filters. Bench-top systems dominate R&D and manufacturing floors where absolute accuracy and multi-channel parallelism justify capital expenditure, while portable units capture field deployment and maintenance workflows in telecommunications and aerospace sectors. Wavelength scanning technology leads installed base volumes, though Fourier transform architectures are displacing conventional approaches in high-resolution coherent communications testing where polarization-mode dispersion analysis matters.
FCC equipment authorization rules shape electromagnetic compatibility requirements for instruments deployed in US telecom infrastructure, while the EU AI Act and CE marking under the Radio Equipment Directive constrain autonomous measurement features in European-bound products. China's GB standards and MIIT type-approval processes govern spectral accuracy claims for instruments sold into domestic 5G buildouts. Stakeholders must monitor how calibration traceability requirements evolve across FDA-regulated biomedical photonics applications and semiconductor metrology chains.
Market Dynamics
Telecom carriers in Japan and South Korea are accelerating 5G backhaul deployment, multiplying demand for inline spectral verification systems that can validate coherent optical links at production scale.
Growth Catalysts
- 5G backhaul buildouts:Japanese and South Korean telecom carriers are expanding fiber optic test equipment procurement to support dense small-cell networks and data center interconnects.
- F-Gas Regulation compliance:The European Union's tightening requirements for electronic test instruments are forcing manufacturers to redesign cooling and sealing systems, creating replacement demand for certified equipment.
- Inline manufacturing verification:Optical component factories across China's eastern seaboard now require spectral verification at every production stage, embedding analyzers directly into process lines.
Market Restraints
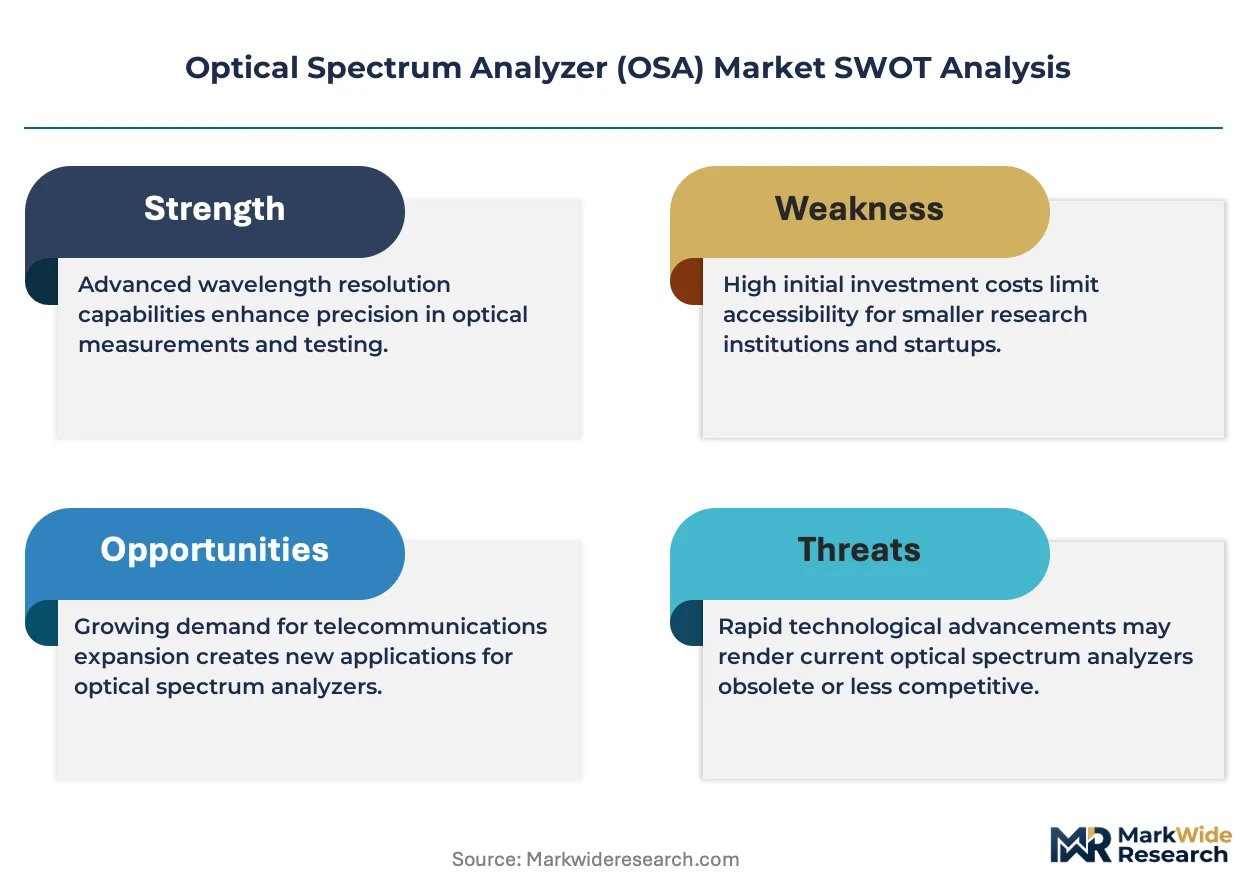
- Precision optics supply concentration:Diffraction gratings and InGaAs detectors rely on a concentrated supplier base in Germany and Japan, exposing procurement to single-source fragility.
- Capital intensity of Fourier transform architectures:High-resolution interferometric systems require stabilized reference lasers and precision mechanics that inflate unit costs versus conventional grating-based designs.
- CE marking timeline friction:The Radio Equipment Directive's conformity assessment procedures add 4-6 months to European market entry for instruments with embedded software-defined measurement features.
Strategic Opportunities
- Biomedical photonics expansion:FDA-regulated surgical laser systems and flow cytometry instruments require calibrated spectral traceability that bench-top analyzers can provision as a service.
- Equipment-as-a-service models:North American telecom test labs are migrating from capital purchase to rental and calibration-inclusive contracts, favoring vendors with distributed service infrastructure.
- Semiconductor metrology integration:Silicon photonics foundries need wafer-level spectral testing, creating demand for compact Fourier transform modules that slot into automated probe stations.
Industry Challenges
- Calibration technician scarcity:Traceability to national standards demands specialists trained in interferometric methods and laser safety protocols that few vocational programs currently teach.
- Legacy system integration:Field-deployed portable units must communicate with existing network management platforms through proprietary protocols that vary by carrier, complicating software architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Spectrum Analyzer (OSA) Market |
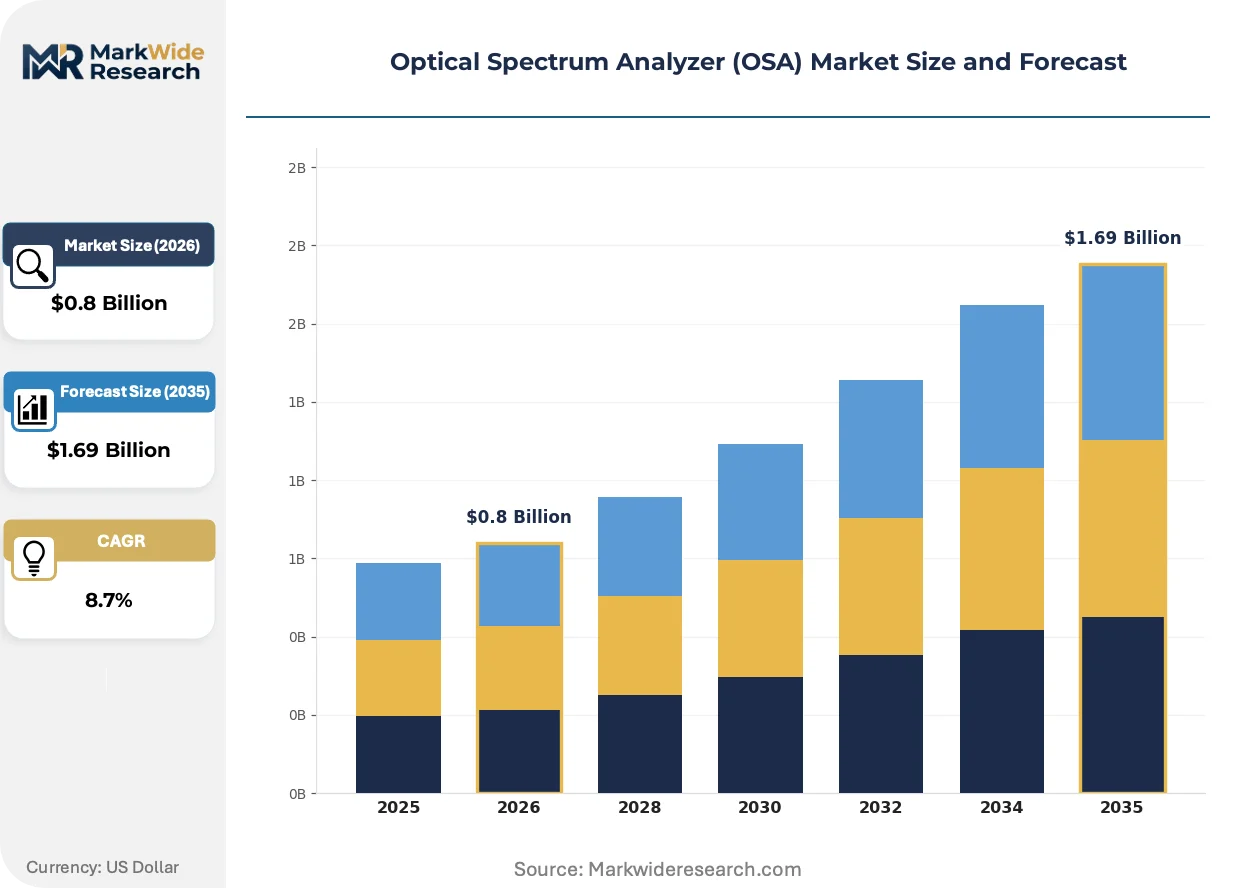
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Portable, Handheld, Network Technology: Optical Interferometry, Fourier Transform, ADC-based, Wavelength Scanning End User: Telecommunications, Aerospace, Research Labs, Manufacturing Application: Device Characterization, Spectral Analysis, Optical Measurement, Communication Testing |
| Companies Covered | EXFO, Thorlabs, Yokogawa Test & Measurement Corporation, Luna Innovations, Coherent Corp., Keysight Technologies, Anritsu Corporation, Quantifi Photonics, VIAVI Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Spectrum Analyzer (OSA) Market Evolving Landscape
Fourier transform architectures are collapsing the performance gap between bench-top laboratory systems and portable field instruments, compressing hardware refresh cycles and reshaping vendor competitive strategies.
Coherent detection with digital signal processing is collapsing the wavelength resolution limitations that constrained conventional scanning-grating designs. Telecom equipment manufacturers in Japan and South Korea are embedding these modules into production-line test heads. The technology is collapsing the distinction between R&D-grade and manufacturing-grade instrumentation, enabling single-platform deployment across both environments.
The EU AI Act's risk classification framework for autonomous measurement functions is forcing instrument vendors to segregate software architectures. European-bound products now require human-in-the-loop validation for self-calibration routines that US and Asian variants execute automatically. High-resolution coherent communications testing equipment faces the steepest compliance burden, with manufacturers submitting updated technical documentation to notified bodies in Germany and France.
Service unbundling is fragmenting the traditional capital-sale model. North American enterprise buyers now procure analyzers through project-based financing that separates hardware, software licenses, and calibration services into distinct contract streams. This pattern concentrates among data center operators and cloud infrastructure providers, who treat spectral verification as an operational expense rather than a fixed asset.
Optical Spectrum Analyzer (OSA) Market Segmentation
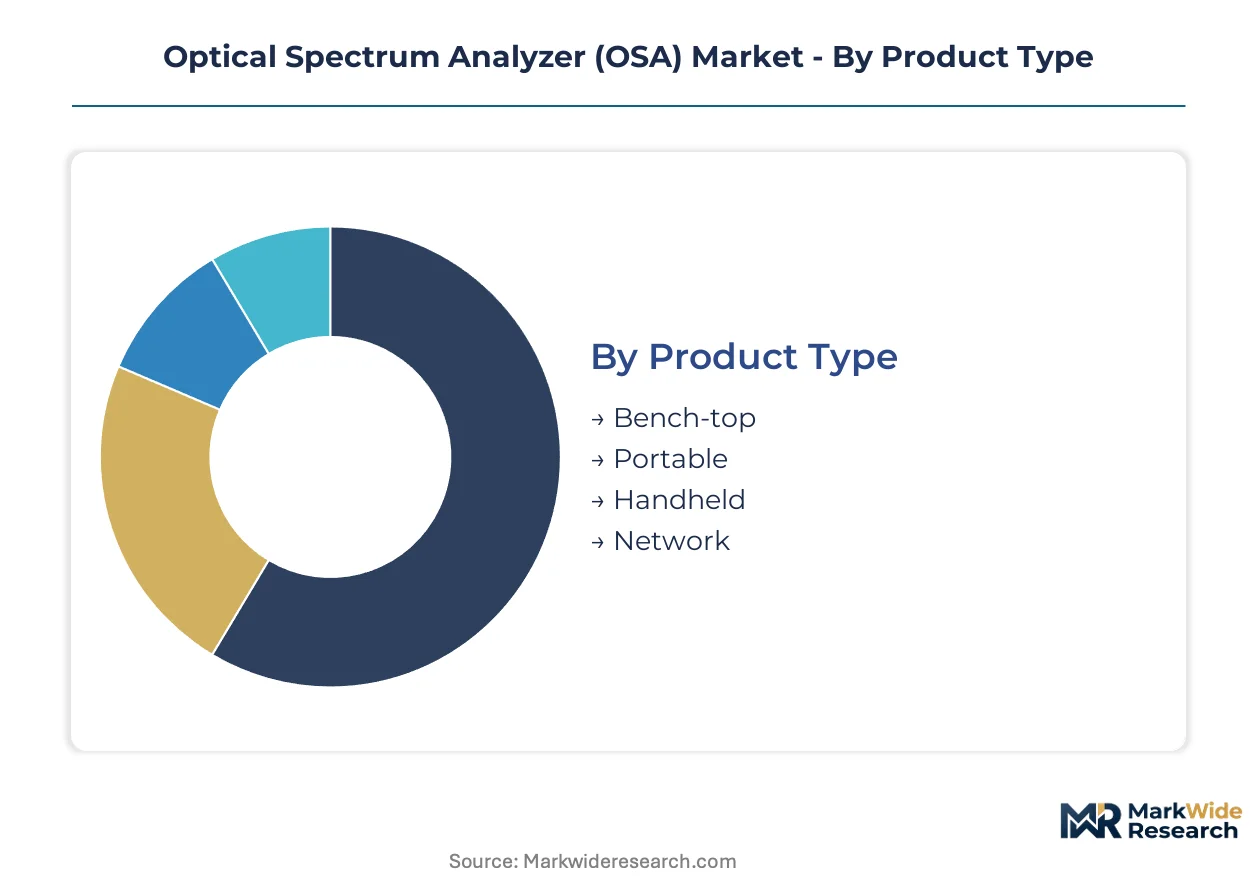
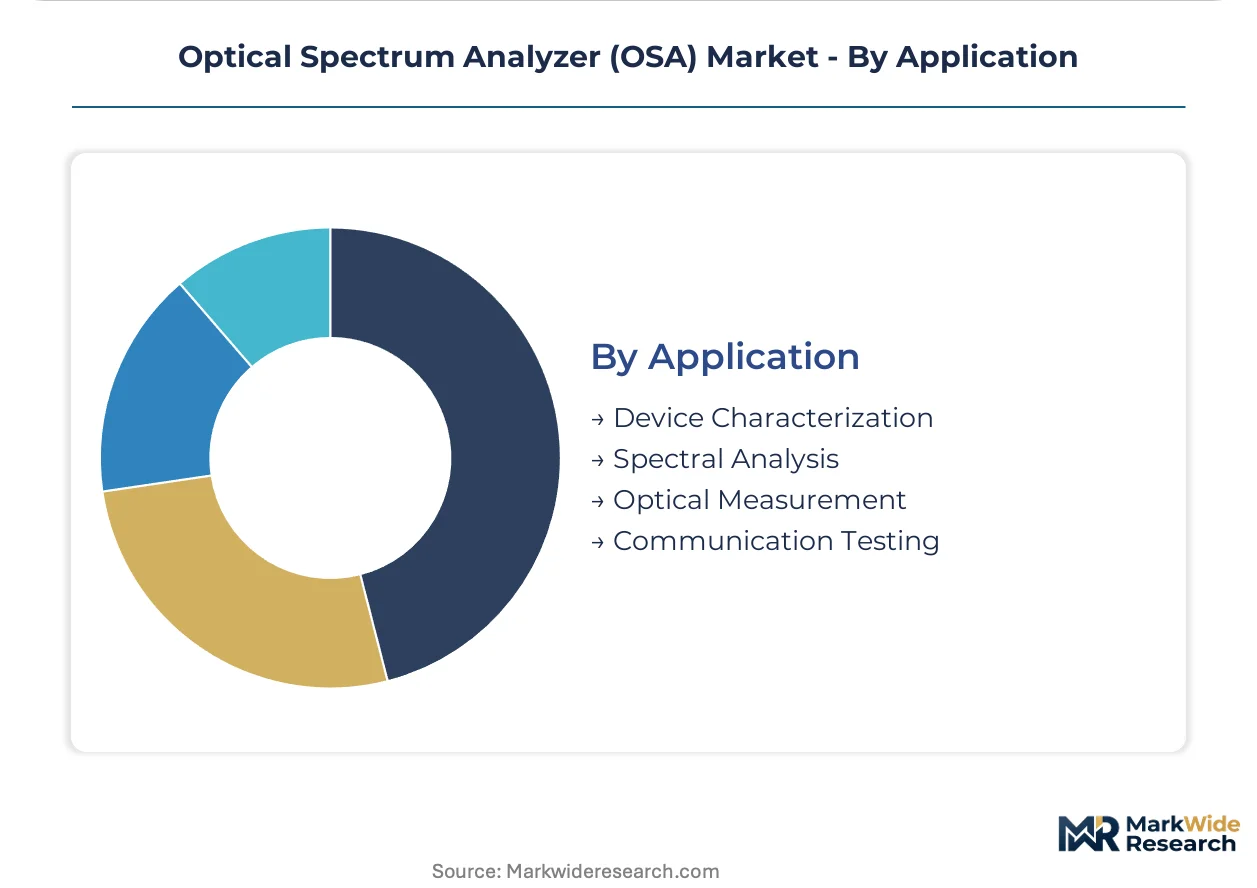
Segmentation in the OSA market determines procurement patterns across radically different use environments. Bench-top systems demand decade-long calibration contracts, while portable units require rapid field-service turnaround. Technology choices lock buyers into specific vendor ecosystems, shaping lifetime cost structures and upgrade pathways.
Product Type:
After-sales-service intensity varies dramatically by form factor, with bench-top systems requiring scheduled interferometer alignment and portable units needing rapid battery and optical connector replacement programs.
- Bench-top:Laboratory-grade systems employ stabilized reference lasers and precision diffraction gratings resolving 0.01 nm. Demand concentrates in China's eastern seaboard optical component factories, where inline spectral verification at every production stage mandates absolute accuracy and multi-channel parallelism. These installations justify capital expenditure through multi-year metrology service contracts.
- Portable:Battery-powered units with reduced resolution trade laboratory precision for field mobility. Japanese and South Korean telecom carriers deploy these for 5G backhaul validation, where technicians must verify coherent optical links across dense small-cell networks without laboratory infrastructure.
- Handheld:Compact devices prioritize ergonomic design and simplified interfaces for rapid fiber troubleshooting. Aerospace maintenance crews in defense and commercial aviation sectors use these for avionics optical link verification during line maintenance.
- Network:Rack-mounted systems integrate directly into telecommunications infrastructure for continuous monitoring. European carriers facing F-Gas Regulation compliance pressures favor these for automated environmental and performance logging.
Bench-top holds the largest share; momentum sits with portable systems as field deployment accelerates.
Technology:
Architecture selection determines both upfront capital requirements and the pace of hardware obsolescence, with coherent detection methods collapsing traditional performance tiering.
- Wavelength Scanning:Conventional diffraction-grating approaches dominate installed base volumes through proven reliability and lower unit costs. Manufacturing floors across China's optical component clusters rely on these for production-line spectral verification where polarization-mode dispersion analysis remains secondary.
- Fourier Transform:Interferometric architectures achieve superior resolution through stabilized reference lasers and precision mechanics. Telecom equipment manufacturers in Japan and South Korea embed these modules into production-line test heads for coherent communications validation.
- Optical Interferometry:Direct interference measurement enables sub-picometer resolution for specialized metrology applications. Semiconductor foundries deploying silicon photonics wafer-level testing favor this approach for automated probe station integration.
- ADC-based:Direct digitization architectures reduce analog component count and enable software-defined measurement flexibility. North American data center operators exploring equipment-as-a-service models show climbing interest in these reprogrammable platforms.
Wavelength scanning retains volume leadership; Fourier Transform architectures are expanding most quickly as coherent communications testing demands intensify.
End User:
Customer type dictates specification priorities, with telecommunications buyers emphasizing field durability and research laboratories demanding traceable calibration chains to national standards.
- Telecommunications:Carriers and equipment manufacturers require instruments validating dense wavelength division multiplexing systems and coherent optical links. Japanese and South Korean 5G backhaul buildouts multiply procurement of both portable field units and rack-mounted network analyzers.
- Research Labs:Academic and government facilities prioritize absolute accuracy, multi-channel parallelism, and documented traceability to national metrology institutes. These buyers sustain demand for highest-tier bench-top systems with comprehensive calibration service agreements.
- Manufacturing:Optical component and semiconductor producers embed analyzers directly into process lines. China's eastern seaboard manufacturing clusters drive volume for inline verification systems that reject non-conforming parts without production interruption.
- Aerospace:Defense contractors and commercial aviation maintenance providers demand ruggedized portable units meeting electromagnetic compatibility requirements under FCC equipment authorization rules for avionics optical link testing.
Telecommunications commands the largest installed base; manufacturing applications are gaining share fastest as inline process integration spreads.
Application:
Use case determines the balance between measurement speed and analytical depth, with production environments favoring rapid pass-fail testing and R&D settings requiring comprehensive parameter extraction.
- Device Characterization:Comprehensive measurement of laser linewidth, side-mode suppression ratio, and relative intensity noise. Optical component factories in China deploy automated test heads for wafer-level and packaged-device validation.
- Communication Testing:Validation of bit error rates, optical signal-to-noise ratios, and dispersion penalties in coherent transmission systems. Japanese and South Korean telecom equipment manufacturers concentrate demand here for 400G and 800G interface development.
- Spectral Analysis:Broadband power distribution measurement across C-band and L-band for amplifier and filter qualification. Research laboratories and certification bodies maintain demand for highest-resolution implementations.
- Optical Measurement:General-purpose power and wavelength verification for installation and maintenance workflows. Field technicians across North American carrier networks use portable implementations for fiber plant commissioning.
Device characterization holds the largest share; communication testing shows the steepest expansion trajectory as data rates advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in optical spectrum analyzers tilt toward net-import positions in Europe and North America, while East Asian manufacturing clusters supply precision components to assembly operations worldwide. Currency volatility and shipping cost fluctuations are redirecting procurement decisions toward regional calibration service networks.
United States
FCC equipment authorization rules govern electromagnetic compatibility for instruments deployed in telecom infrastructure, driving procurement from certified test labs. Data center operators in Northern Virginia and Dallas-Fort Worth are expanding rental fleets for spectral verification of coherent optical links. The concentration of cloud infrastructure providers in these metros sustains demand for equipment-as-a-service contracts.
China
MIIT type-approval processes govern spectral accuracy claims for instruments sold into domestic 5G buildouts, tightening compliance documentation requirements. Optical component factories across the Yangtze River Delta now embed inline analyzers at every production stage. Shanghai and Suzhou manufacturing clusters drive volume for wavelength scanning systems that reject non-conforming parts without line interruption.
Japan
METI industrial standards shape precision instrument specifications for domestic and export markets, particularly for coherent communications testing. Telecom carriers in Tokyo and Osaka are accelerating 5G backhaul deployment, multiplying demand for portable field units. Yokohama-based equipment manufacturers embed Fourier transform modules into production-line test heads for 400G and 800G interface validation.
Germany
The EU F-Gas Regulation and CE marking under the Radio Equipment Directive constrain autonomous measurement features, adding 4-6 months to conformity assessment timelines. Stuttgart and Munich precision optics suppliers concentrate diffraction grating production for the European installed base. These suppliers face single-source fragility exposure as demand concentrates from instrument assemblers across the continent.
South Korea
MFDS-equivalent telecom equipment certification and national 5G deployment targets are expanding fiber optic test equipment procurement from domestic and foreign vendors. Seoul and Busan carrier networks are validating dense small-cell backhaul with portable analyzers. Pangyo Techno Valley hosts equipment manufacturers integrating coherent detection modules for export to Japanese and Southeast Asian markets.
Optical Spectrum Analyzer (OSA) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling precision optics supply. The vendor base spans three tiers: diversified test and measurement conglomerates with calibration service networks, mid-scale instrument specialists with regional distribution, and precision component fabricators supplying diffraction gratings and detectors. Consolidation pressure concentrates at the system level, while upstream component supply remains fragmented across German and Japanese specialists. Competitive moves center on strategic partnerships for calibration infrastructure and technology licensing for coherent detection architectures.
Among diversified test and measurement providers, EXFO and Keysight Technologies exemplify platform integrators with rental fleet and software-defined measurement capabilities. Yokogawa Test & Measurement Corporation anchors the precision instrument tier through in-house production of critical optical components. These three entities represent distinct competitive archetypes: service-integrated leasing models, software-hardware convergence strategies, and vertical control over precision subsystems.
| Leading Market Players |
|---|
| EXFO |
| Thorlabs |
| Yokogawa Test & Measurement Corporation |
| Luna Innovations |
| Coherent Corp. |
| Keysight Technologies |
| Anritsu Corporation |
| Quantifi Photonics |
| VIAVI Solutions |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese diffraction grating suppliers determines both pricing tier spreads and supply chain shape, compressing margins for instrument assemblers while inflating premium-tier bench-top system costs. This concentration forces vendors to absorb procurement volatility or pass it through to buyers locked into multi-year calibration contracts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on NIST-traceable calibration chains and CE marking under the Radio Equipment Directive, while economy tiers compete on unit cost for field-portable units. Cost compression in the standard tier intensifies because Fourier transform architectures require stabilized reference lasers that inflate bill-of-materials. Data center operators exploring equipment-as-a-service models show the lowest price sensitivity, whereas Chinese optical component factories drive hard volume negotiations for inline verification systems.
Supply Chain Analysis
Precision InGaAs detector feedstock draws from concentrated fabrication facilities in Germany and Japan, with secondary sourcing from South Korean compound semiconductor foundries. Critical inputs include lithographically patterned diffraction gratings, hermetic sealing ceramics, and stabilized He-Ne reference lasers. Single-source vulnerability in grating replication tooling exposes assemblers to 4-6 month lead time extensions when primary suppliers face capacity constraints. Distribution runs through authorized calibration service networks that maintain regional metrology traceability, with direct OEM procurement gaining share among high-volume manufacturing buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the OSA landscape as service unbundling separates hardware, software, and calibration into distinct contract streams, creating niches for specialized players in each layer.
For Market Incumbents: Entrench defensive positions by deepening captive supply of precision diffraction gratings through backward integration into German and Japanese optics specialists, countering substitute threats from ADC-based software-defined architectures. Expand calibration infrastructure density across North American telecom test labs to lock in recurring revenue against emerging rental-fleet competitors. For New Entrants and Emerging Players: Underpenetration in biomedical photonics service contracts offers the most penetrable white-space target, with FDA-regulated surgical laser manufacturers requiring traceable spectral verification that incumbent bench-top vendors currently underserve. Target silicon photonics foundries with compact Fourier transform modules designed for automated probe station integration, leveraging project-based financing structures to bypass capital-sale barriers. For Investors and Strategic Acquirers: The EU AI Act's risk classification framework for autonomous measurement functions reshapes the acquisition landscape, elevating compliance-capable assets above pure technology plays. Five-to-ten year viability favors precision component fabricators with in-house grating production and established notified body relationships. Watch for MIIT type-approval timeline acceleration in China as an inflection signal for domestic market entry premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Distributed service networks capture recurring revenue from North American telecom test labs migrating to rental models. |
| Precision Optics Backward Integration | In-house diffraction grating production insulates Yokogawa from German supplier concentration risks. |
| Software-Defined Measurement Platform | Keysight's reprogrammable architectures reduce hardware refresh cycles for enterprise data center buyers. |
| Inline Manufacturing Verification Integration | Embedding analyzers into Chinese optical component process lines locks in volume procurement contracts. |
| Biomedical Photonics Service Launch | FDA-regulated surgical laser traceability requirements open premium service tiers for bench-top vendors. |
Research Methodology
Cross-validation between primary interviews with instrument engineering directors, telecom test lab managers, semiconductor metrology leads, and calibration service technicians and secondary validation through SEC filings of listed test and measurement conglomerates, MIIT type-approval databases, EU notified body technical documentation, and Japanese METI industrial standards publications anchors the qualitative findings. Bottom-up demand modeling from end-user procurement patterns triangulates against top-down market sizing from vendor revenue disclosures.
Calibration against historical shipment data across the projection horizon ensures analytical framework robustness. Segmentation dimensions modeled include product form factor, detection architecture, end-user industry vertical, and regional regulatory cluster. CAGRs derive from slope analysis of technology adoption curves and replacement cycle compression in coherent communications testing. Forecast inputs incorporate F-Gas Regulation compliance cost pass-through assumptions and 5G backhaul deployment trajectories from Japanese and South Korean carrier capital expenditure disclosures.
Practitioners should monitor revision triggers including CE marking timeline extensions under the Radio Equipment Directive, InGaAs detector supply disruptions from German or Japanese fabrication facilities, and MIIT spectral accuracy standard updates for early signals of forecast deviation. Cross-checking against FCC equipment authorization filing volumes and EU notified body submission rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Digital Cinema Lens Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Global Optical Imaging System Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Optical Encoder Market
Optical Components
North America Optical Film Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Objective Lens Market
Optical Components
Night Vision Tubes Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Optical Cross Connect Market
Optical Components
Photosensitive Glass Market