
 Optical Modulators Market | 2026-2036
Optical Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Modulators Market Analysis
The EU F-Gas Regulation is consolidating demand for low-power, thermally efficient optical modulator architectures across European telecommunications infrastructure. Lumentum Holdings Inc. leverages its vertically integrated indium phosphide platform to sustain leadership in high-speed coherent transmission modules. Coherent Corp. anchors North American supply through its broad lithium niobate and semiconductor laser portfolio. Fujitsu Optical Components Ltd. dominates Japanese domestic markets with precision manufacturing for submarine cable systems.
An optical modulator varies the amplitude, phase, or polarization of a light carrier wave to encode information, typically operating at wavelengths near 1310 nm or 1550 nm with bandwidths exceeding 50 GHz in leading designs. Its primary commercial purpose is enabling high-capacity fiber-optic communication by converting electrical data streams into optical signals with minimal power consumption and distortion. Lithium niobate modulators retain the largest installed base for long-haul coherent links where electro-optic coefficient stability matters most. Phase modulation technology is gaining share in quantum computing applications where superposition state fidelity demands precise optical control. Electro-optic modulators occupy the fastest-expanding margin pool as silicon photonics integration reduces packaging cost and footprint.
The U.S. FCC spectrum policies and Japan's METI energy efficiency standards for telecom equipment are shaping product roadmaps by mandating reduced thermal budgets and interoperable optical interfaces. REACH compliance in Europe restricts certain dopants and substrate coatings, forcing material substitutions in thin-film lithium niobate processes. China's MIIT dual carbon goals and GB standards for data center power usage effectiveness are filtering into procurement specifications for modulator-equipped transceivers. Stakeholders must monitor how divergent efficiency certifications across these jurisdictions fragment qualification timelines and whether unified test protocols emerge from IEC working groups before committing to single-source platform strategies.
Market Dynamics
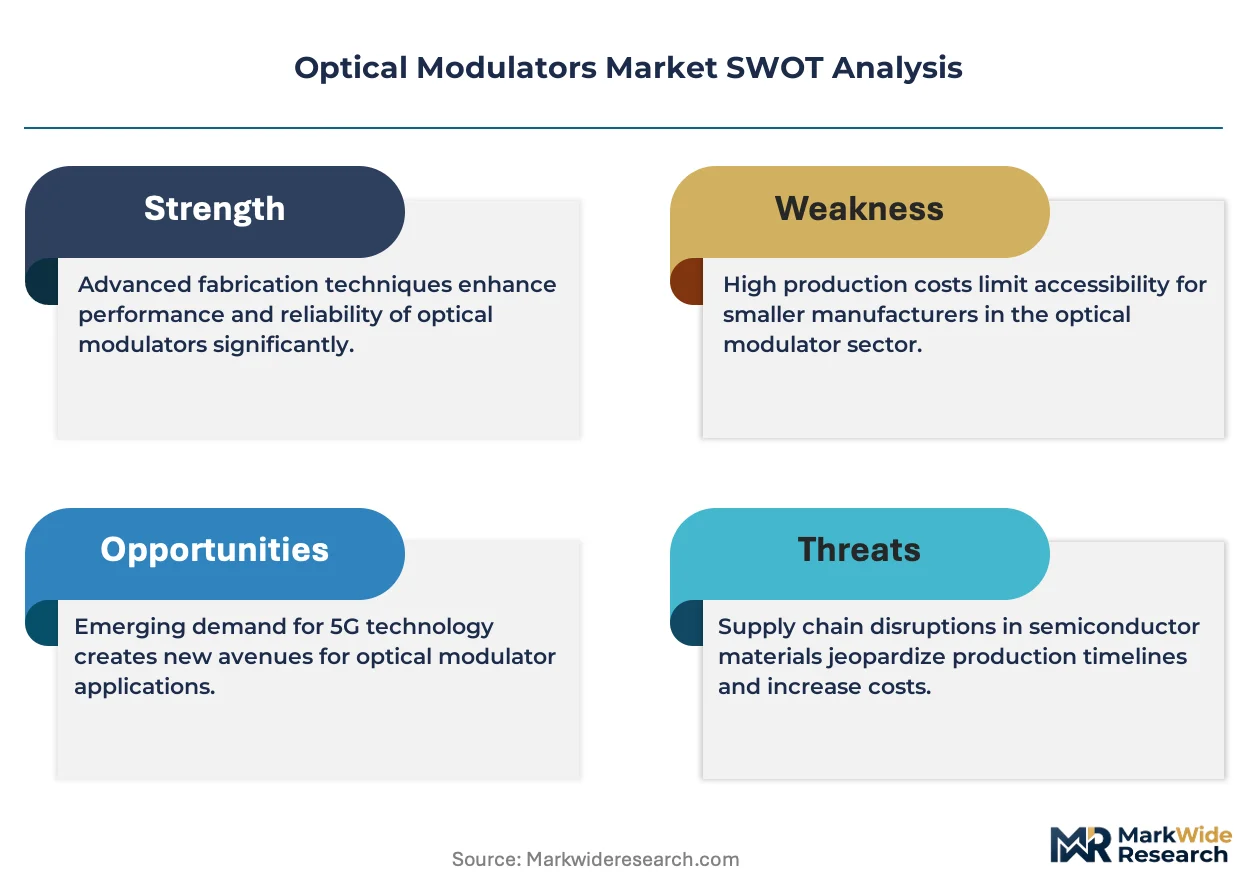
Silicon photonics integration is compressing modulator packaging costs while EU F-Gas Regulation mandates force thermal efficiency redesigns across European telecom infrastructure.
Growth Catalysts
- Hyperscale Data Center Expansion:Cloud operators in Germany, Japan, and the United States are deploying coherent optical interconnects at unprecedented density to support AI training clusters.
- EU F-Gas Regulation:Phase-down schedules for fluorinated gases are accelerating procurement of low-power electro-optic modulators in telecommunications backbone networks.
- Thin-Film Lithium Niobate:Advances in wafer-scale processing are extending bandwidth capabilities beyond 100 GHz for next-generation coherent links.
Market Restraints
- Indium Phosphide Supply Concentration:III-V semiconductor foundry capacity concentrates in East Asian contract manufacturers, creating single-source vulnerability for high-speed modulator chips.
- REACH Compliance Costs:ECHA restrictions on tantalum and niobium compounds force material substitutions in thin-film electrode deposition, extending qualification timelines.
- Thermal Management Complexity:Dense wavelength-division multiplexing architectures require active cooling subsystems that consume 15-25% of transceiver power budgets.
Strategic Opportunities
- Quantum Computing Interfaces:National quantum programs in the United States, Germany, and Japan are sourcing precision phase modulators for photonic qubit control systems.
- Co-Packaged Optics:Integration of modulator dies directly adjacent to switch ASICs eliminates retimer components and reduces electrical trace losses.
- Japan METI Efficiency Standards:Mandatory power usage effectiveness targets for telecom equipment create preference for thermally efficient modulator architectures in NTT and KDDI procurement.
Industry Challenges
- Photonic Packaging Talent Scarcity:Active alignment of fiber-to-chip interfaces requires specialized technicians; training pipelines lag demand in Germany, Japan, and the United States.
- Multi-Jurisdiction Certification Burden:Divergent efficiency test protocols between FCC, METI, and EU standardization bodies fragment product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Modulators Market |
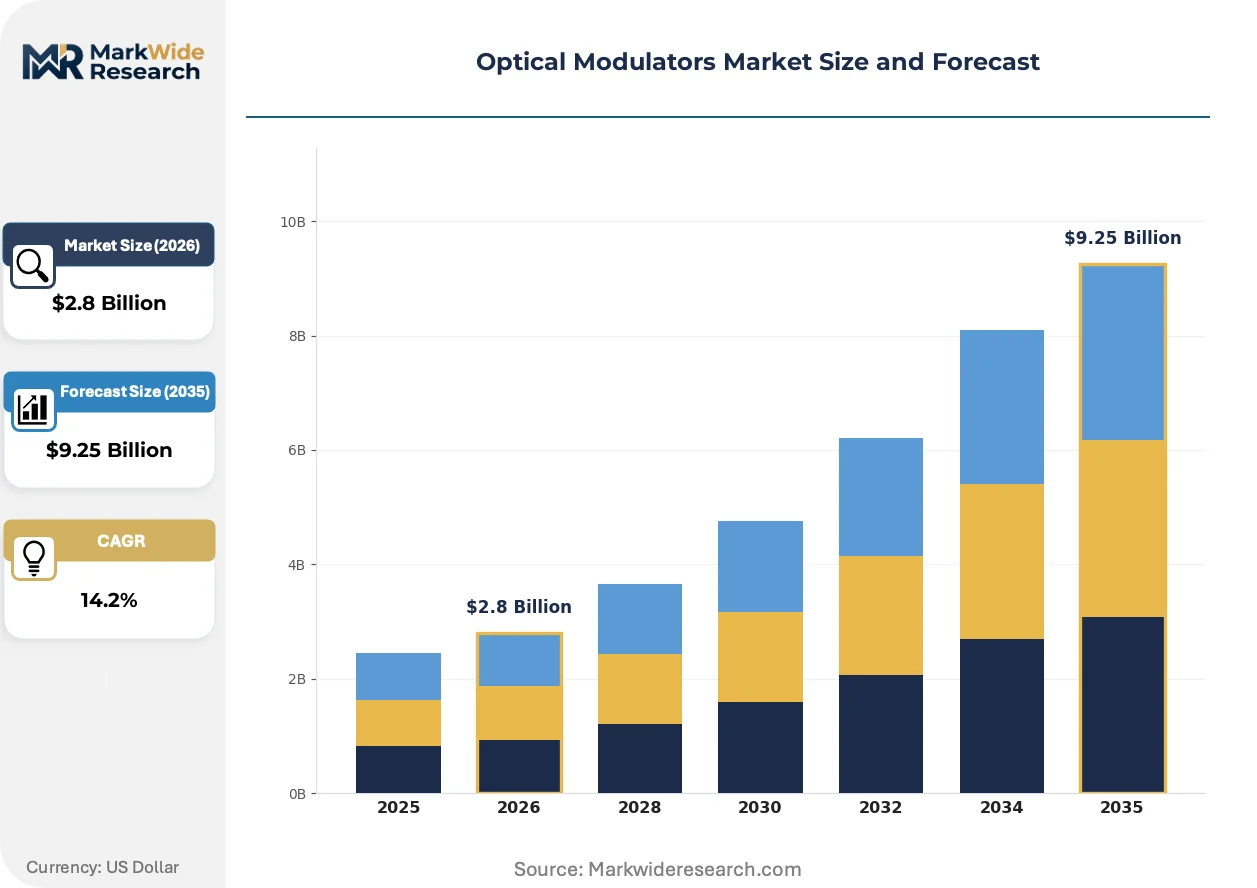
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EAM, Lithium Niobate Modulators, Acousto-Optic Modulators, Electro-Optic Modulators Technology: Analog Modulation, Digital Modulation, Phase Modulation, Intensity Modulation End User: Telecommunications Service Providers, Data Centers, Aerospace, Research Laboratories Application: Optical Communication, Signal Processing, Light Measurement, Quantum Computing |
| Companies Covered | Gooch and Housego PLC, HyperLight Corporation, Lumentum Holdings Inc., HC Photonics Corp., AA Opto-Electronic SAS, Fujitsu Optical Components Ltd., Coherent Corp., II-VI Inc., Thorlabs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Modulators Market Emerging Trajectories
Three concurrent shifts are reshaping optical modulator architecture: silicon photonics platforms are absorbing discrete component functions, sustainability mandates are rewriting thermal design rules, and procurement centralization is compressing vendor qualification cycles.
Thin-film lithium niobate on insulator is integrating electro-optic modulation with CMOS-compatible wafer processing. Hyperscale data center operators in the United States and Germany are adopting this platform for 800G coherent transceivers. The technology is integrating previously separate modulator and driver functions into single-die solutions, collapsing packaging cost structures.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent cooling architectures out of telecom infrastructure. ECHA compliance deadlines are accelerating design transitions to passive thermal management in outdoor optical line terminals. German network operators Deutsche Telekom and Vodafone are specifying fan-less modulator modules for street cabinet deployments.
Hyperscale buyers are consolidating optical transceiver procurement through direct vendor relationships rather than traditional systems integrators. Amazon Web Services, Microsoft Azure, and Google Cloud are establishing technical qualification programs that bypass incumbent distributor channels. This pattern concentrates most visibly in the United States, where three buyers account for majority share of 400G+ coherent port demand.
Optical Modulators Market Segmentation
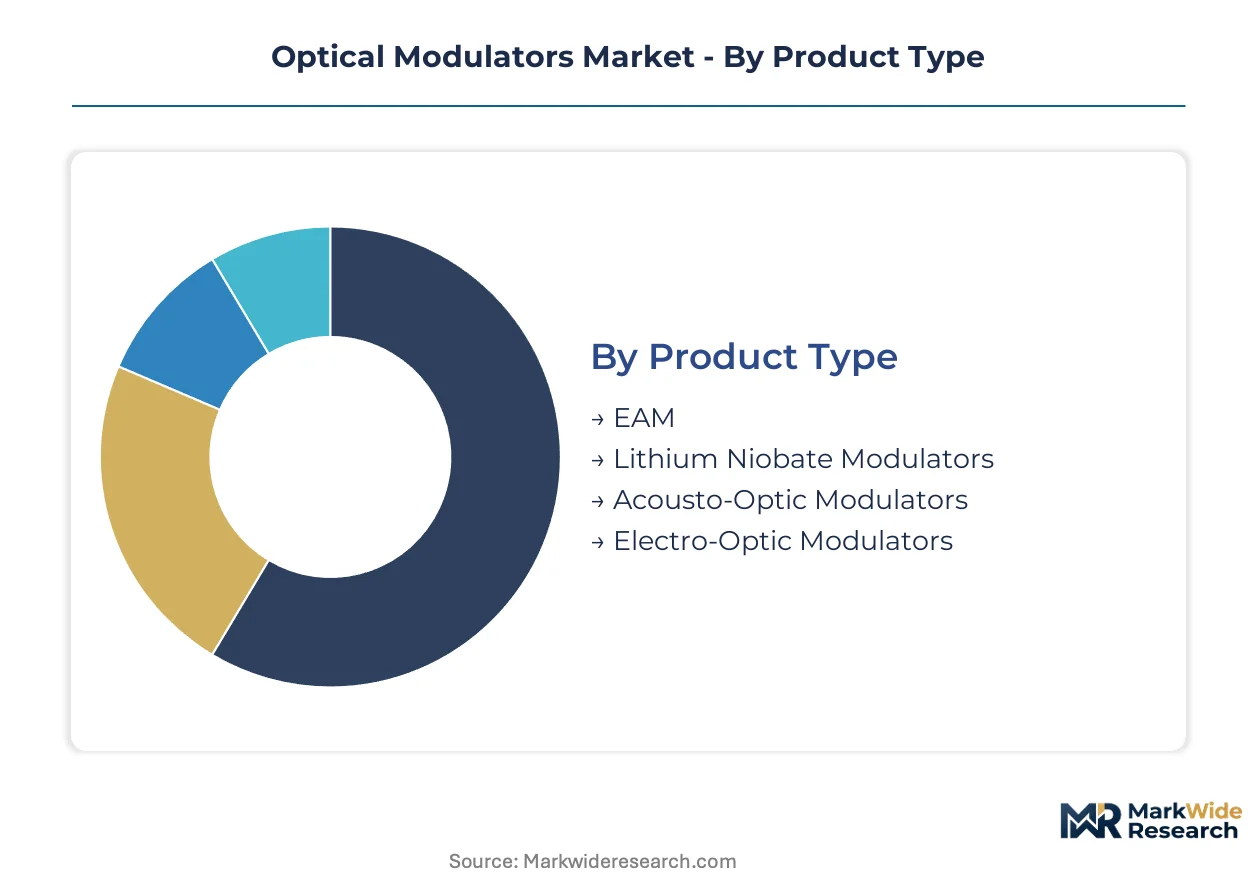
Optical modulator procurement patterns diverge sharply across product architectures and end-use environments. Specification requirements for coherent transmission differ fundamentally from quantum control applications, fragmenting vendor qualification pathways and pricing structures.
Product Type:
Material platforms determine bandwidth ceiling, thermal budget, and integration compatibility with silicon photonics foundries.
- Lithium Niobate Modulators:Thin-film lithium niobate on insulator delivers electro-optic coefficients exceeding 30 pm/V with wafer-scale CMOS compatibility. Deutsche Telekom and NTT specify this platform for 800G coherent transceiver deployments where thermal stability under outdoor temperature swings matters.
- Electro-Optic Modulators:Silicon-organic hybrid and pure silicon architectures leverage existing 300mm foundry infrastructure, collapsing packaging costs through monolithic driver integration. Google Cloud and Microsoft Azure procurement teams prioritize these for co-packaged optics programs in United States hyperscale facilities.
- EAM:Electro-absorption modulators monolithically integrate with DFB lasers on indium phosphide substrates for compact 100G/400G pluggable formats.
- Acousto-Optic Modulators:Piezoelectric transducers impose traveling acoustic waves on crystal substrates, serving spectrum analyzer and laser tuning applications in research laboratories.
Lithium niobate leads on scale; electro-optic modulators lead on momentum.
Technology:
Modulation format selection trades off spectral efficiency against DSP complexity and power consumption in transceiver designs.
- Phase Modulation:QPSK and 16-QAM formats encode data in optical phase states, demanding precise bias control but delivering superior receiver sensitivity. Submarine cable systems operated by NEC and SubCom specify these for trans-Pacific routes where amplifier spacing drives power budgets.
- Digital Modulation:Discrete symbol mapping enables forward error correction integration and simplified receiver architectures. Coherent DSP ASICs from Broadcom and Marvell process these formats in 400G/800G data center interconnects.
- Analog Modulation:Continuous amplitude or phase variation supports RF-over-fiber antenna remoting and cable television distribution networks.
- Intensity Modulation:Direct on-off keying dominates short-reach links below 10 km where cost sensitivity outweighs spectral efficiency requirements.
Phase modulation dominates long-haul revenue; digital modulation is climbing the fastest in data center port counts.
End User:
Buyer technical sophistication and volume concentration reshape vendor sales motions and support infrastructure.
- Data Centers:Hyperscale operators consolidate optical transceiver procurement through direct vendor qualification programs, bypassing traditional systems integrators. Amazon Web Services, Microsoft Azure, and Google Cloud account for majority share of 400G+ coherent port demand in United States facilities.
- Telecommunications Service Providers:Deutsche Telekom, NTT, and Verizon maintain stringent thermal efficiency specifications under EU F-Gas Regulation and Japan METI standards, favoring fan-less outdoor cabinet designs.
- Research Laboratories:National quantum programs in Germany, Japan, and the United States source precision phase modulators for photonic qubit control with lot sizes below 100 units.
- Aerospace:Satellite optical inter-satellite links demand radiation-hardened modulator assemblies with qualification cycles exceeding five years.
Data centers lead on volume concentration; telecommunications providers lead on specification stringency.
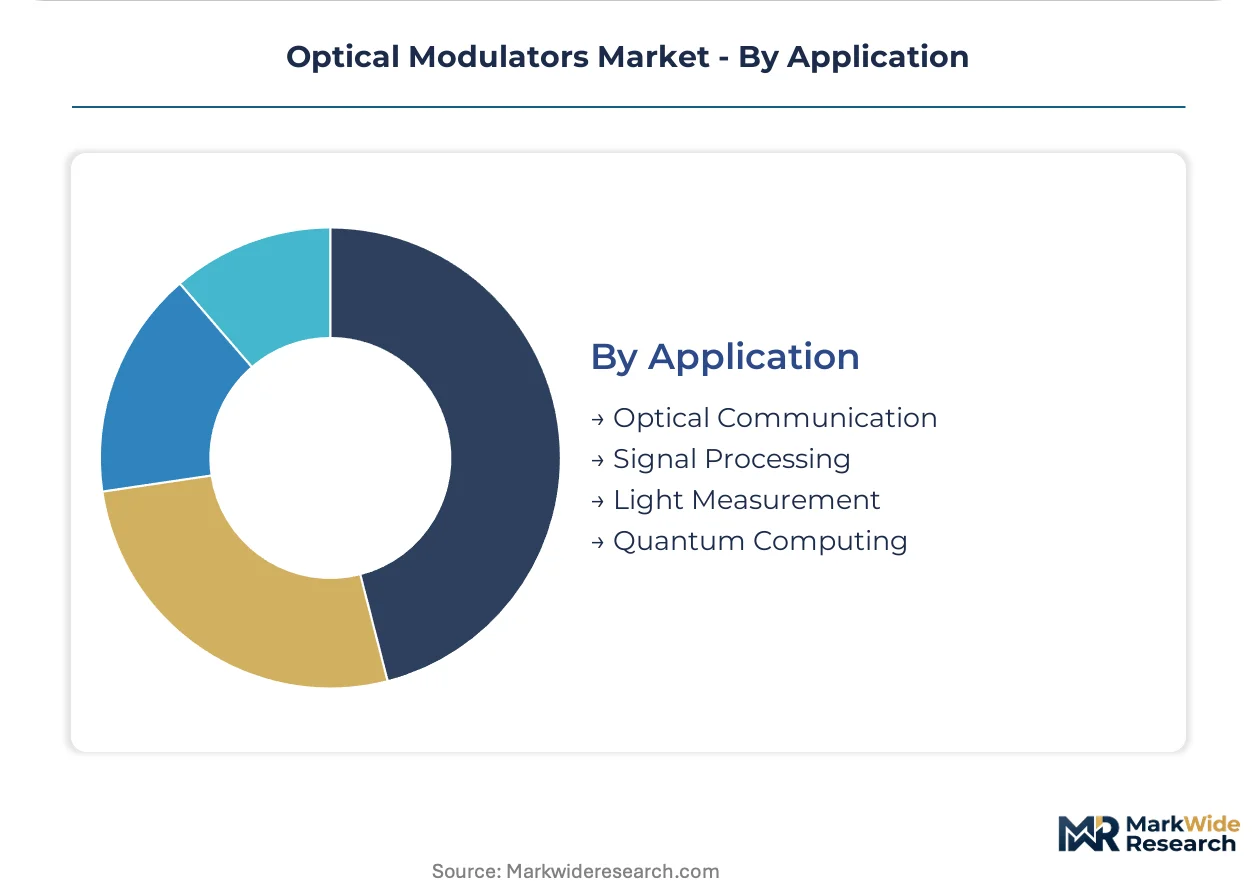
Application:
Use case performance requirements span six orders of magnitude in bit-error-rate tolerance and operating temperature range.
- Optical Communication:Fiber-optic transmission systems from metro access to submarine cables constitute the commercial foundation, with coherent 800G ZR+ standards defining current procurement specifications.
- Quantum Computing:Photonic qubit manipulation demands phase stability below 0.1% with cryogenic compatibility, filtering vendor pools to specialized suppliers serving national laboratory programs.
- Signal Processing:Microwave photonic filters and analog-to-digital conversion subsystems deploy modulators in radar and electronic warfare platforms.
- Light Measurement:Spectroscopy and interferometry instruments leverage acousto-optic and electro-optic modulation for wavelength selection and phase-sensitive detection.
Optical communication leads on revenue scale; quantum computing shows the steepest expansion trajectory in funded program dollars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical modulator manufacturing traces its commercial lineage to Bell Labs innovations in the 1970s, with subsequent scaling concentrated in German precision optics clusters and Japanese semiconductor foundries before silicon photonics integration shifted investment patterns toward United States hyperscale data center corridors.
United States
Hyperscale cloud operators in Ashburn, Virginia and Hillsboro, Oregon are deploying 800G coherent transceivers at density levels exceeding 100,000 ports per facility. FCC spectrum efficiency mandates are tightening thermal budgets for outdoor optical line terminals. The Santa Clara photonics cluster anchors silicon photonics foundry capacity serving Google Cloud and Microsoft Azure procurement programs.
Germany
Deutsche Telekom and Vodafone are specifying fan-less modulator modules for street cabinet deployments under outdoor temperature swings from -40°C to +65°C. The EU F-Gas Regulation is accelerating phase-out of refrigerant-dependent cooling architectures in telecom infrastructure. The Berlin-Brandenburg corridor hosts precision manufacturing for thin-film lithium niobate wafer processing.
Japan
NTT and KDDI procurement teams are mandating power usage effectiveness targets under METI efficiency standards for telecom equipment. National quantum programs in Tsukuba and Osaka are sourcing cryogenic-compatible phase modulators for photonic qubit control systems. The Kanto region concentrates submarine cable component manufacturing for trans-Pacific routes.
China
MIIT dual carbon goals are filtering into data center procurement specifications for modulator-equipped transceivers with power usage effectiveness below 1.3. The Yangtze River Delta hosts III-V semiconductor foundry capacity for electro-absorption modulator integration. GB standards for optical interconnects are tightening interoperability requirements in hyperscale facilities.
South Korea
Samsung Electronics and SK Hynix are integrating silicon photonics modulators into co-packaged optics for AI training clusters in the Seoul Capital Area. The national semiconductor strategy is allocating foundry subsidies toward 300mm silicon photonics wafer processing. Busan-Ulsan harbors specialized packaging capacity for fiber-to-chip active alignment.
Optical Modulators Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material platform specialization and thermal efficiency certification tiers. The vendor base organizes around three strategic archetypes: vertically integrated indium phosphide platforms, thin-film lithium niobate specialists, and silicon photonics foundry partners. Competitive positioning hinges on qualification speed with hyperscale cloud operators and compliance breadth across EU F-Gas, Japan METI, and FCC thermal efficiency regimes. Dominant moves include strategic partnerships with coherent DSP ASIC suppliers and geographic expansion into German and Japanese telecom procurement channels.
Within the vertically integrated platform tier, Lumentum Holdings Inc. and Coherent Corp. occupy positions defined by captive III-V semiconductor manufacturing and broad lithium niobate portfolios respectively. Fujitsu Optical Components Ltd. anchors the precision manufacturing archetype for submarine cable systems. These three entities exemplify how material platform control and regional certification depth determine vendor selection in telecommunications backbone procurement.
| Leading Market Players |
|---|
| Gooch and Housego PLC |
| HyperLight Corporation |
| Lumentum Holdings Inc. |
| HC Photonics Corp. |
| AA Opto-Electronic SAS |
| Fujitsu Optical Components Ltd. |
| Coherent Corp. |
| II-VI Inc. |
| Thorlabs Inc. |
| Others |
Supply Flow & Price Mechanics
Indium phosphide wafer pricing indices cascade through III-V semiconductor foundry contracts into three distinct modulator cost tiers. Buyers in Germany and Japan absorb premium thermal-efficiency certifications, while United States hyperscale operators negotiate volume-driven standard-tier contracts for silicon photonics platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Premium tiers command substantial markups for EU F-Gas Regulation compliance and Japan METI efficiency certification, while standard tiers serve qualified hyperscale procurement programs. Cost compression in economy-tier pluggable transceivers is intensifying because Chinese III-V foundry capacity is expanding electro-absorption modulator supply. Data center operators exhibit the highest price sensitivity, demanding per-port cost reductions through co-packaged optics integration, whereas submarine cable systems prioritize phase stability over unit economics.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor hubs to German telecom infrastructure sites is amplifying landed cost differentials between regional supply chains. Manufacturing concentrates in Taiwan, Japan, and the United States, with Taiwan anchoring III-V foundry capacity for indium phosphide modulator chips, Japan hosting precision lithium niobate wafer processing, and the United States scaling silicon photonics integration. The supply chain rests on tantalum and niobium compound feedstocks subject to REACH restrictions, plus specialized photonic packaging equipment with limited vendor pools. Single-source vulnerability concentrates in East Asian contract foundries for high-speed electro-optic chips. Distribution runs through direct vendor relationships with hyperscale cloud operators, bypassing traditional systems integrator channels in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU F-Gas Regulation phase-down schedules forcing thermal efficiency redesigns that consolidate procurement around certified suppliers.
For Market Incumbents: To counter silicon photonics displacement of discrete modulator architectures, deepen captive III-V semiconductor manufacturing in Taiwan and Japan while accelerating thin-film lithium niobate certification for EU F-Gas compliant outdoor deployments. Prioritize co-packaged optics partnerships with switch ASIC suppliers to defend socket position in hyperscale data centers. For New Entrants and Emerging Players: Launch via specialized foundry partnerships serving national quantum programs in Germany, Japan, and the United States where precision phase modulator demand outruns established supply. Target cryogenic-compatible photonic qubit control systems where lot sizes below 100 units filter out volume-scale competitors. Position through direct technical qualification with NTT and Deutsche Telekom procurement teams seeking fan-less outdoor cabinet solutions. For Investors and Strategic Acquirers: Asymmetric upside sits with thin-film lithium niobate specialists possessing wafer-scale processing IP and EU thermal efficiency certifications. Five-to-ten-year viability hinges on qualification speed with hyperscale cloud operators rather than installed base scale. Monitor IEC working group progress toward unified test protocols as the inflection signal for platform consolidation bets.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Packaged Optics Integration | Eliminates retimer components and reduces electrical trace losses for Google Cloud and Microsoft Azure procurement programs. |
| Thin-Film Lithium Niobate Scale-Up | Extends bandwidth beyond 100 GHz for Deutsche Telekom and NTT 800G coherent transceiver specifications. |
| EU F-Gas Compliance Certification | Unlocks fan-less outdoor cabinet deployments for Vodafone and Deutsche Telekom street infrastructure. |
| Quantum Program Partnership | Secures precision phase modulator supply contracts with Tsukuba and Osaka national laboratory networks. |
| Silicon Photonics Foundry Expansion | Collapses packaging costs through monolithic driver integration for United States hyperscale facility demand. |
Methodological Framework
Bottom-up data center and telecommunications procurement modeling reconciled against top-down III-V semiconductor foundry output tracking forms the analytical core of this study. Primary interviews with optical transceiver procurement managers, photonic packaging engineers, coherent DSP ASIC product directors, and telecom network planning officers combined with secondary validation from FCC spectrum policy filings, Japan METI efficiency standard disclosures, EU ECHA restriction updates, and hyperscaler capex commitment announcements. Trade data from German customs authorities and United States import records provided cross-reference points for lithium niobate wafer and indium phosphide chip flow volumes.
Historical trendline analysis of coherent port deployment densities across German, Japanese, and United States facilities established baseline growth patterns. The projection framework segments by material platform, modulation technology, end-use environment, and application requirement, with CAGRs derived from elasticity modeling against data center buildout announcements and submarine cable system procurement timelines. Forecast inputs include silicon photonics wafer start projections from foundry equipment orders and quantum computing program budget appropriations from national research agencies.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in China MIIT dual carbon enforcement timelines and potential REACH expansion to additional tantalum compounds. Forecasts reflect documented assumptions about hyperscale cloud operator consolidation patterns and coherent DSP ASIC vendor roadmaps. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Prism Coupler Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Fluorophore Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Europe Optical Film Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Display Optical Film Market
Optical Components
CVD Sic Ring Market
Optical Components
Optical Sensor Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Diode Laser Module Market
Optical Components
Photomask Pellicle Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Erbium Oxide Market