
 Global Optical Fiber Preform Market | 2026-2036
Global Optical Fiber Preform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Fiber Preform Market Outlook
Data center interconnect demand is recalibrating the optical fiber preform procurement priorities of telecom operators and IT companies worldwide. Corning Incorporated leverages its proprietary OVD process to sustain manufacturing scale across North American and Asian production nodes. Yangtze Optical Fibre and Cable Joint Stock Limited Company anchors supply security for Chinese domestic 5G and submarine cable projects through captive precursor sourcing. Prysmian Group differentiates via vertical control over both preform drawing and cable integration, spanning European and Latin American markets.
An optical fiber preform is a cylindrical glass structure, typically composed of high-purity silica with germania (GeO2) doped core layers, manufactured through modified chemical vapor deposition (MCVD) or outside vapor deposition (OVD) processes to achieve precise refractive index profiles before fiber drawing. Silica preform dominates current output volumes due to established telecom infrastructure replacement cycles, while GeO2 preform captures expanding margin pools from high-bandwidth data communication applications requiring low-attenuation single-mode fiber. The application split reveals telecommunication as the mature revenue base, with data communication emerging as the fastest-growing demand vector driven by hyperscale cloud facility expansion.
The U.S. FCC broadband equity programs and China's MIIT dual carbon standards shape product efficiency mandates and market access conditions for preform manufacturers. Japan's METI supports domestic fiber-optic supply chain resilience through targeted industrial technology certifications. Stakeholders must monitor evolving energy-efficiency compliance thresholds and deposition technology substitution risks as regulatory frameworks tighten across major producing jurisdictions.
Market Dynamics
China's MIIT dual carbon goals and the EU Green Deal are tightening energy-efficiency standards for silica deposition processes, forcing preform manufacturers to retool MCVD and OVD furnaces or face exclusion from public procurement tenders in the world's two largest fiber deployment markets.
Growth Catalysts
- Submarine cable deployments:Transoceanic bandwidth expansion by telecom operators anchors demand for ultra-low-attenuation single-mode fiber preforms with germania-doped cores.
- 5G backhaul densification:China's MIIT infrastructure mandates accelerate fiber-to-the-antenna procurement cycles across tier-1 and tier-2 municipalities.
- Data center interconnect buildouts:Hyperscale cloud operators in the United States and Japan are recalibrating preform specifications toward high-count ribbon fiber compatibility.
Market Restraints
- High-purity silica supply concentration:Synthetic silica precursor production clusters in Japan and Germany, creating single-source vulnerability for MCVD process operators.
- Germanium cost volatility:GeO2 dopant prices fluctuate with semiconductor recycling markets, compressing margins on specialty single-mode preforms.
- EU F-Gas Regulation compliance:Fluorine-based etching chemistries face phase-down schedules, forcing process requalification costs on European deposition equipment.
Strategic Opportunities
- India's BharatNet rural fiberization:The CEA's rural electrification-fiber convergence programs create greenfield demand for cost-optimized multimode preforms.
- Silicon photonics integration:Convergence of optical preform drawing with semiconductor packaging is opening co-packaged optics applications in AI training clusters.
- Japan's METI supply chain resilience incentives:Domestic precursor stockpiling subsidies offer captive sourcing advantages for qualified preform manufacturers.
Industry Challenges
- Specialized furnace engineering talent:MCVD and OVD thermal process optimization requires scarce expertise in high-temperature gas flow dynamics.
- Extended qualification timelines:Submarine cable consortiums demand multi-year preform lot consistency validation before volume procurement authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Fiber Preform Market |
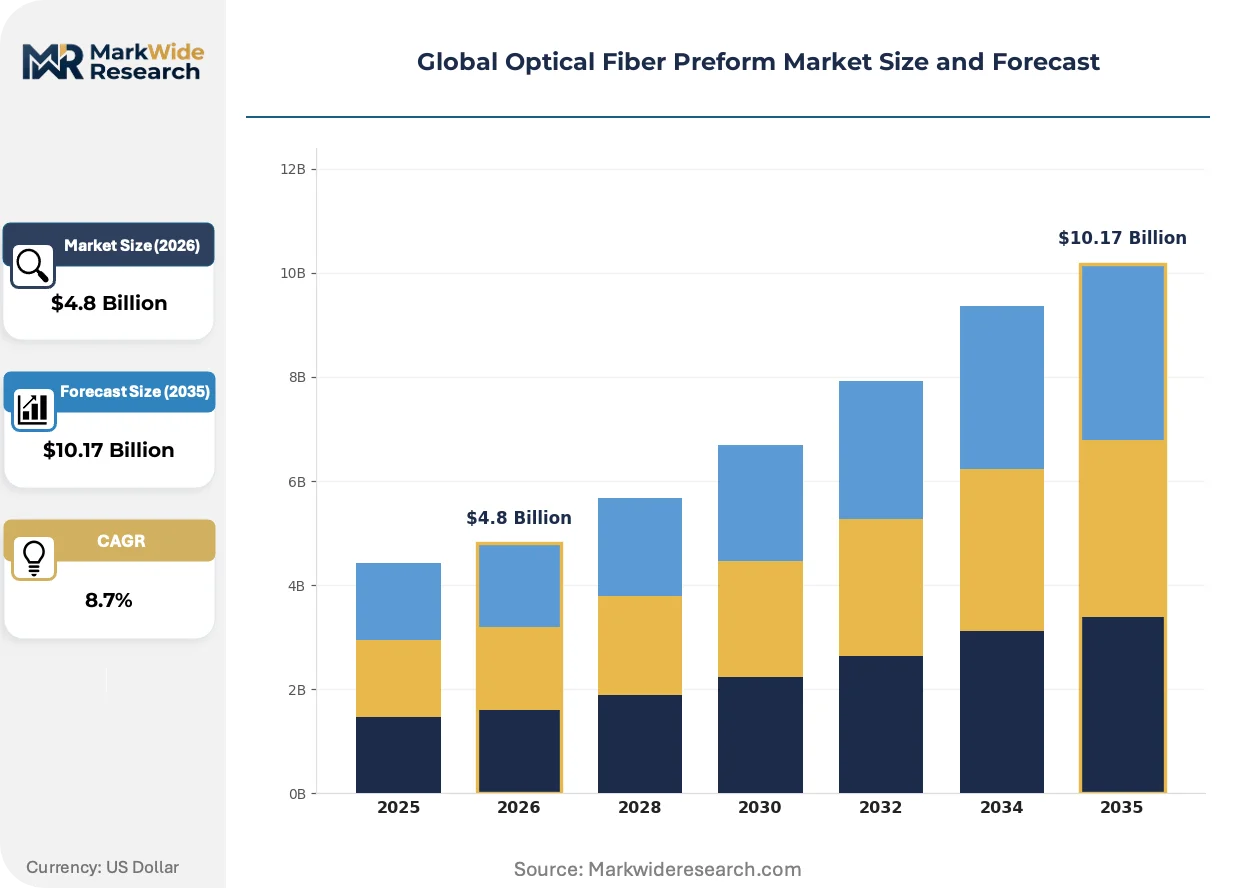
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Preform, GeO2 Preform, Al2O3 Preform, Others Application: Telecommunication, Data Communication, Medical Devices, Aerospace Delivery Mode: Direct Sales, Distributors, Online Sales, Retail End User: Telecom Operators, IT Companies, Research Institutions, Manufacturers |
| Companies Covered | Corning Incorporated, Prysmian Group, Yangtze Optical Fibre and Cable Joint Stock Limited Company, Sumitomo Electric Industries, Fujikura Ltd, Hengtong Group, Shin-Etsu Chemical, Furukawa Electric, OFS Fitel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Fiber Preform Market Strategic Shifts
Plasma-assisted deposition technologies and AI-driven process control systems are compressing refractive index tolerance bands while regulatory carbon accounting is reshaping furnace energy sourcing decisions across major production nodes.
Plasma-enhanced chemical vapor deposition (PECVD) for preform core layering is electrifying precision in germania dopant distribution. Hyperscale data center operators in the United States are specifying PECVD-derived preforms for coherent transmission compatibility. This technology is electrifying competitive positioning by enabling sub-0.1 dB/km attenuation specifications that vapor-phase axial deposition cannot match.
The EU Green Deal's carbon border adjustment mechanism tightens embodied emissions disclosure for imported silica preforms. European deposition facilities must document renewable energy shares in furnace operations or face tariff penalties. Submarine cable projects with EU public funding components are now requiring ISO 14064-compliant carbon footprint certification from preform suppliers.
Direct procurement contracts between hyperscale cloud operators and preform manufacturers are disintermediating traditional cable-integrated distributors. Amazon Web Services and Microsoft Azure are establishing multi-year offtake agreements with Yangtze Optical Fibre and Corning for captive capacity reservation. This pattern concentrates most visibly in the United States, where data center construction permits are increasingly bundled with fiber supply security documentation.
Global Optical Fiber Preform Market Segmentation
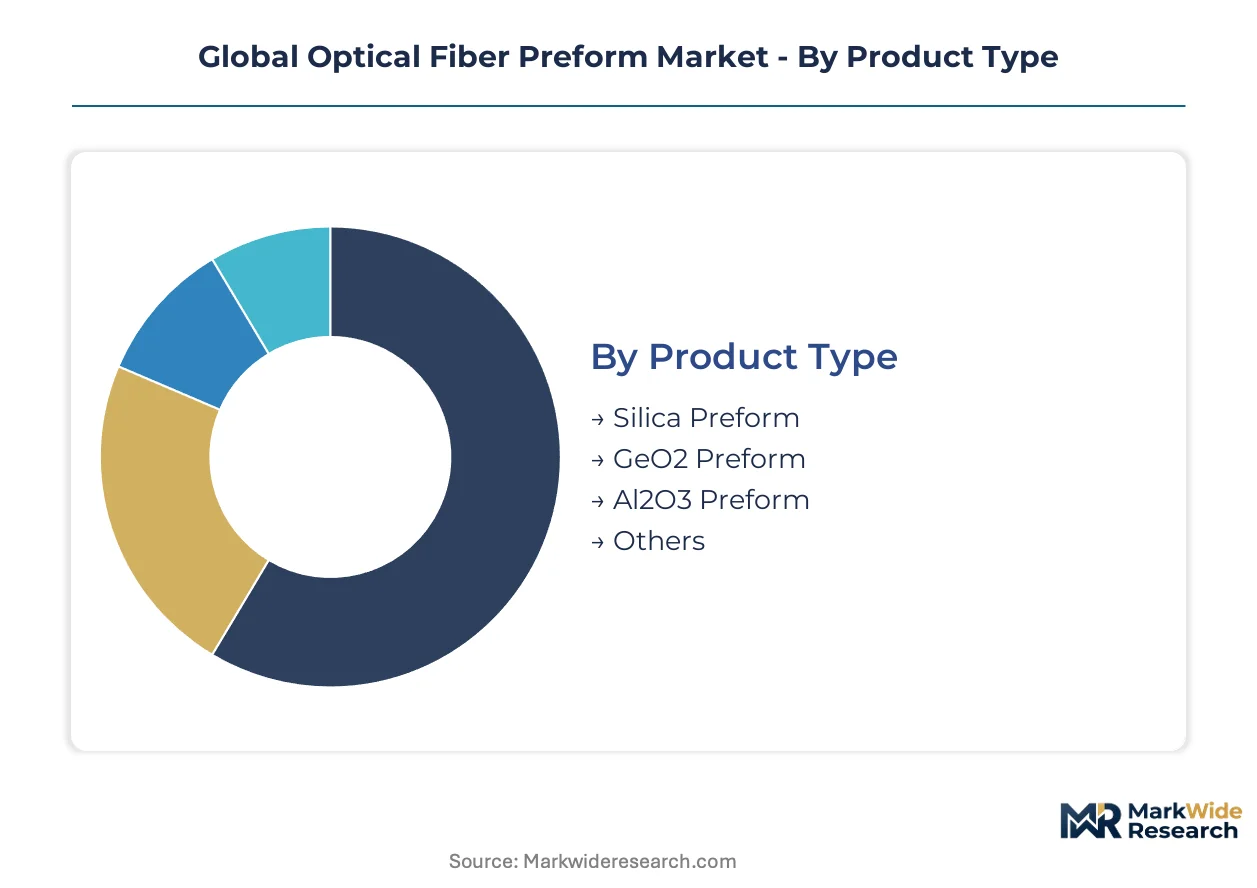
Optical fiber preform segmentation reveals how manufacturing specifications, procurement channels, and end-use requirements fragment supply strategies across deployment scenarios. Technology leadership in deposition processes and dopant chemistry differentiates margin capture between commodity telecom infrastructure and premium data communication applications.
Product Type:
Refractive index engineering through core dopant selection determines transmission performance thresholds and furnace process compatibility across deposition methods.
- Silica Preform:High-purity silicon dioxide structures manufactured via MCVD or OVD processes dominate volume production for standard single-mode and multimode fiber. Demand concentrates in China's 5G backhaul buildouts and U.S. rural broadband equity programs where cost efficiency outweighs ultra-low attenuation requirements.
- GeO2 Preform:Germania-doped core layers elevate refractive index contrast to enable sub-0.2 dB/km attenuation specifications critical for transoceanic submarine cables. Procurement volumes from Japan's NTT and U.S. hyperscale operators are climbing fastest as coherent transmission reaches 800G and beyond.
- Al2O3 Preform:Alumina-doped variants serve specialty fiber applications requiring thermal stability in harsh environments.
- Others:Fluorine-doped and rare-earth doped preforms address dispersion compensation and amplifier applications.
Mature deployment sits with Silica Preform. Newer deployment is concentrated in GeO2 Preform.
Application:
Bandwidth intensity and latency tolerance separate volume procurement patterns between established telecom replacement cycles and emerging data center interconnect specifications.
- Telecommunication:Legacy infrastructure replacement and 5G fronthaul anchor baseline demand across tier-1 through tier-3 markets. China's MIIT infrastructure mandates and India's BharatNet rural fiberization sustain procurement continuity despite margin compression from commoditized specifications.
- Data Communication:Hyperscale cloud facility expansion in the United States and Japan is recalibrating preform specifications toward high-fiber-count ribbon compatibility and reduced bend loss. Co-packaged optics integration for AI training clusters is opening adjacent demand vectors.
- Medical Devices:Biocompatible fiber bundles for endoscopic imaging and laser surgery require specialized preform purity certifications.
- Aerospace:Radiation-hardened and lightweight fiber assemblies for satellite interconnect and avionics command limited but high-margin volumes.
Telecommunication captures installed base revenue. Data Communication is expanding most quickly.
Delivery Mode:
Procurement channel selection reflects customer scale, technical specification complexity, and supply security requirements across deployment timelines.
- Direct Sales:Multi-year offtake agreements between preform manufacturers and hyperscale cloud operators or submarine cable consortiums dominate high-volume, specification-critical procurement. Amazon Web Services and Microsoft Azure contracts with Yangtze Optical Fibre and Corning exemplify this channel's concentration.
- Distributors:Regional cable integrators and mid-tier telecom operators rely on inventory-buffered channels for standardized preform specifications with shorter lead time requirements.
- Online Sales:E-procurement platforms serve research institutions and small-batch manufacturers requiring rapid sample acquisition.
- Retail:Limited to aftermarket repair quantities and educational laboratory supplies.
Direct Sales commands premium contract values. Distributors handle fragmented regional demand.
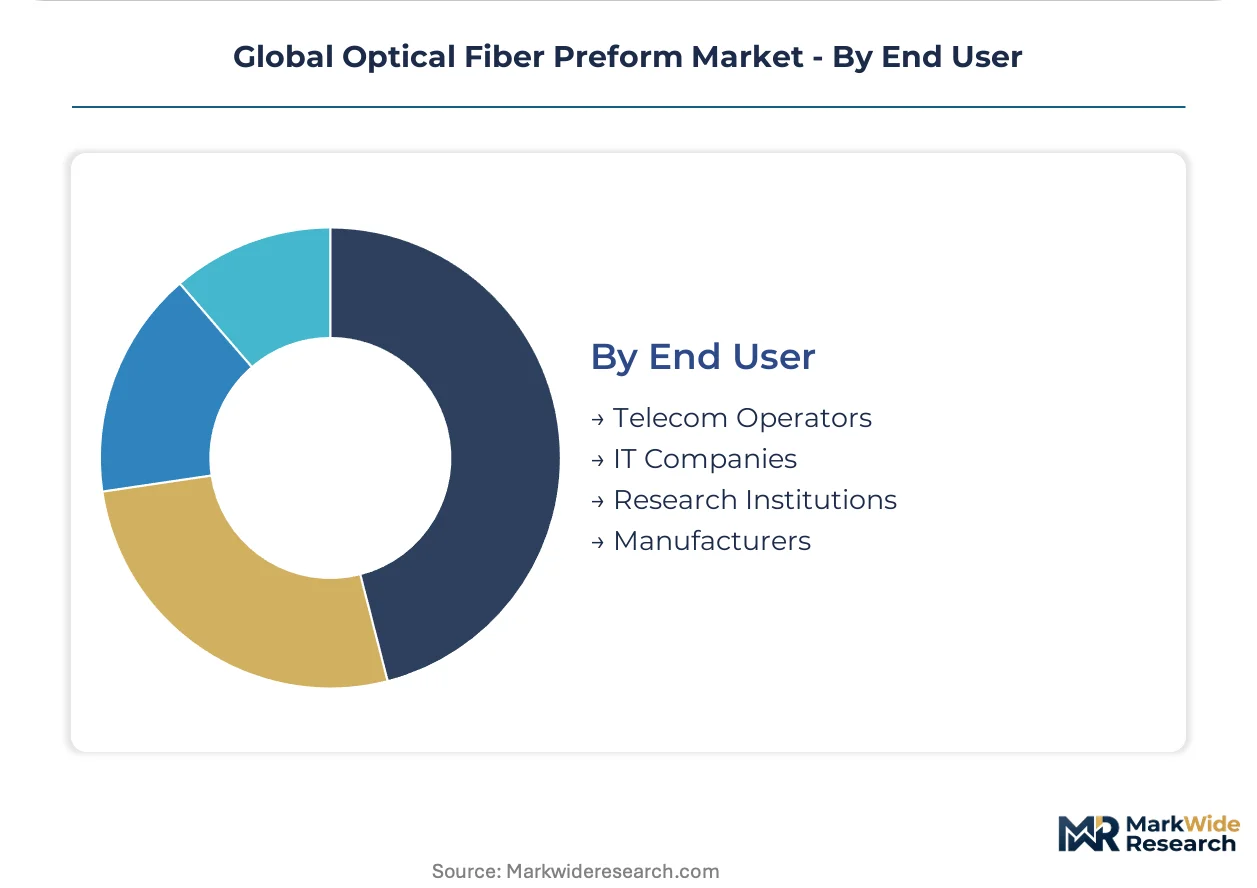
End User:
Technical sophistication and volume scale separate procurement approaches between infrastructure deployers and manufacturing intermediaries.
- Telecom Operators:China Mobile, Verizon, and Deutsche Telekom drive standardized single-mode volume through centralized procurement with stringent lot consistency requirements.
- IT Companies:Hyperscale operators specify custom preform geometries for data center interconnect, bypassing traditional cable-integrated distributors through direct manufacturer relationships.
- Research Institutions:Universities and national laboratories source specialty doped preforms for photonics research and prototype validation.
- Manufacturers:Cable integrators and OEMs purchase preforms for captive drawing operations, particularly in Japan and Germany where supply chain resilience incentives apply.
Telecom Operators anchor volume procurement. IT Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta special economic zone concentrates preform manufacturing capacity through clustered precursor supply chains and bonded logistics infrastructure serving both domestic 5G deployments and export-oriented submarine cable projects.
China
MIIT infrastructure mandates for 5G backhaul densification drive procurement volumes across tier-1 and tier-2 municipalities. The dual carbon goals tighten energy-efficiency standards for MCVD and OVD furnace operations, forcing retooling investments. Wuhan anchors domestic supply security through captive precursor sourcing for Yangtze Optical Fibre and state-backed deployment programs.
United States
FCC broadband equity programs recalibrate procurement priorities toward rural fiberization and data center interconnect buildouts. The Inflation Reduction Act provisions incentivize domestic clean energy sourcing for deposition furnace operations. North Carolina's Research Triangle hosts Corning's OVD process manufacturing nodes serving hyperscale cloud operator direct contracts.
Japan
METI supply chain resilience subsidies support domestic precursor stockpiling and industrial technology certifications for fiber-optic manufacturing. NTT's transoceanic bandwidth expansion anchors demand for ultra-low-attenuation single-mode preforms. The Kanto region clusters synthetic silica precursor production with Sumitomo Electric and Fujikura drawing operations.
Germany
The EU Green Deal's carbon border adjustment mechanism tightens embodied emissions disclosure requirements for imported silica preforms. ECHA REACH compliance and F-Gas Regulation phase-down schedules force process requalification on European deposition equipment. Berlin-Brandenburg hosts Prysmian's vertical integration of preform drawing with cable integration for European and Latin American markets.
India
CEA rural electrification-fiber convergence programs under BharatNet create greenfield demand for cost-optimized multimode preforms. TRAI infrastructure sharing guidelines accelerate fiber-to-the-home deployment timelines across tier-2 and tier-3 cities. Gujarat's industrial corridor attracts cable integrators establishing captive drawing operations for domestic procurement.
Global Optical Fiber Preform Market Competitive Environment
Top-tier vendors anchor direct sales channels with hyperscale operators and submarine cable consortiums, while mid-tier fabricators compete through regional distributor networks and standardized telecom specifications. The market structure concentrates around deposition process specialization and vertical control over precursor supply. Three archetypes dominate: integrated silica-cable operators, specialty germania-doped preform specialists, and captive suppliers for domestic infrastructure programs. Competitive moves center on capacity reservation agreements with cloud operators and furnace energy sourcing certifications for EU market access.
Among Asia-Pacific-based fabricators, Yangtze Optical Fibre and Cable Joint Stock Limited Company and Sumitomo Electric Industries occupy positions within the integrated operator archetype, while Corning Incorporated exemplifies the multinational specialty tier with proprietary process differentiation. These three anchors represent distinct geographic and technological positioning strategies across the preform value chain.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Yangtze Optical Fibre and Cable Joint Stock Limited Company |
| Sumitomo Electric Industries |
| Fujikura Ltd |
| Hengtong Group |
| Shin-Etsu Chemical |
| Furukawa Electric |
| OFS Fitel |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and family-owned mid-caps in Japan anchor supply discipline through captive precursor stockpiling, translating upstream control into pricing power during silica feedstock volatility. This ownership pattern concentrates procurement leverage among state-linked operators while forcing private competitors into long-term offtake concessions.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with hyperscale cloud operators paying contract premiums for guaranteed capacity reservation while spot buyers absorb inventory risk. Price differentiation hinges on ISO 14064 carbon certification tier and volume scale commitments. Cost compression in economy-tier silica preforms is intensifying because Chinese state-backed operators are flooding tier-2 municipality procurement. Telecom operators prove most price-sensitive, whereas submarine cable consortiums prioritize attenuation performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through multi-year capacity reservation agreements, bypassing traditional cable-integrated distributors. Manufacturing concentrates in China, Japan, and Germany, with synthetic silica precursor production clustering in the Kanto region and the Rhine-Ruhr corridor. The supply chain rests on high-purity silicon tetrachloride, germanium dioxide, and specialty furnace refractories. Single-source vulnerability in synthetic silica feedstock from Shin-Etsu Chemical and Heraeus operations creates chokepoint exposure. Distribution runs through vertically integrated cable manufacturers for telecom infrastructure and direct manufacturer relationships for data center interconnect.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical fiber preform market is consolidating around a vertical-integration race, with deposition process control and captive precursor sourcing emerging as the decisive margin levers.
For Market Incumbents: Hedge against PECVD technology substitution by securing intellectual property positions in plasma-assisted deposition while expanding OVD furnace capacity in North Carolina's Research Triangle to serve FCC-mandated rural fiberization. State-backed Chinese competitors are compressing margins on standardized silica preforms through subsidized energy sourcing.
For New Entrants and Emerging Players: India's BharatNet rural electrification-fiber convergence programs open a window for cost-optimized multimode preform manufacturing through joint ventures with Gujarat-based cable integrators. Target CEA-funded tier-2 city deployments with stripped-down specifications and localized furnace operations to bypass established distributor networks.
For Investors and Strategic Acquirers: Direct procurement contract announcements between Amazon Web Services and Yangtze Optical Fibre are the leading indicator that hyperscale cloud operators are consolidating supplier relationships around carbon-certified deposition capacity. Focus acquisition screening on mid-tier German fabricators with EU Green Deal-compliant furnace energy sourcing and existing METI technology certifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Sourcing | Captive supply of synthetic silica reduces exposure to Shin-Etsu Chemical and Heraeus pricing volatility. |
| Plasma-Enhanced Deposition Scale-Up | PECVD capacity expansion enables sub-0.1 dB/km specifications for coherent 800G transmission. |
| Carbon Certification Program | ISO 14064 compliance secures access to EU-funded submarine cable procurement tenders. |
| Long-Term Offtake Agreement | Multi-year contracts with Microsoft Azure and AWS lock in capacity utilization against spot price erosion. |
| Geographic Manufacturing Footprint | North Carolina OVD nodes position suppliers for Inflation Reduction Act clean energy incentives. |
Study Parameters
SEC 10-K filings, ECHA REACH registration databases, and MIIT industrial policy directives formed the secondary backbone, cross-referenced with primary interviews spanning preform manufacturing executives, hyperscale cloud procurement officers, and submarine cable consortium technical directors. Bottom-up and top-down triangulation validated volume estimates against customs trade data and furnace capacity disclosures.
The analytical lens combined bottom-up segmentation modeling with top-down macro constraint checks across the projection horizon. Segmentation dimensions included dopant chemistry tier, deposition process technology, end-use application intensity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and net new deployment pipelines. Forecast inputs incorporated MIIT 5G infrastructure mandate timelines and FCC broadband equity program disbursement schedules.
Caveats apply where germanium price volatility, EU F-Gas Regulation phase-down acceleration, or PECVD technology cost curves could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Raman Amplifier Market
Optical Components
Diode Laser Module Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Machine Vision Light Source Market
Optical Components
Co-Packaged Optics Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Optical Cross Connect Market
Optical Components
Global Adaptive Optics Market
Optical Components
Passive Optical Component Market
Optical Components
Optical Fiber Array Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
CMP Polishing Machine Market
Optical Components
Global Optical Network Hardware Market