
 Polarizer Film Market | 2026-2036
Polarizer Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polarizer Film Market Analysis
EU REACH substance restrictions on halogenated compounds is rebalancing the cost-of-entry calculus for polarizer film suppliers serving European display manufacturers. Nitto Denko leverages its captive iodine-doping expertise to sustain margin structures despite compliance investments. Sumitomo Chemical anchors supply security through backward integration into polyvinyl alcohol resin production. BenQ Materials competes on optical clarity specifications for premium notebook panels.
Polarizer film is a birefringent optical component typically manufactured by stretching polyvinyl alcohol sheets doped with iodine or dichroic dyes, then laminating them between cellulose acetate or polycarbonate protective substrates to convert unpolarized light into linearly polarized output for controlled display transmission. Linear polarizers dominate volume flows into LCD television and monitor panels where extinction ratio performance determines contrast specifications. Circular polarizers represent the fastest-growing product type as automotive OLED and quantum-dot displays require anti-reflective circular polarization for sunlight readability. Polyvinyl alcohol-based films retain the deepest margin pools due to established coating infrastructure and iodine-doping process maturity.
Japan's METI enforces JIS standards on optical film dimensional stability that constrain supplier qualification timelines for precision display applications. South Korea's MFDS and the country's national environmental regulator impose hazardous substance reporting on polarizer film adhesives and protective films used in medical display devices. China's SAMR administers GB standards for electronic display component recyclability that affect material selection in polarizer film stack designs. Stakeholders must monitor how divergent regional chemical compliance regimes fragment raw material sourcing strategies.
Market Dynamics
Automotive display integration is compressing qualification timelines for polarizer film suppliers as curved OLED panels demand circular polarization with anti-reflective coatings. OEM procurement teams now specify optical clarity thresholds that exceed legacy television benchmarks.
Growth Catalysts
- Automotive OLED Adoption:Dashboard and pillar-to-pillar screen configurations require circular polarizers with quarter-wave retardation layers. Tier-1 display integrators in South Korea's Gyeonggi Province cluster are scaling dedicated coating lines for this specification.
- EU REACH Compliance Investments:Halogenated compound restrictions are creating a two-tier supplier base. Firms with captive iodine-doping capabilities capture premium panel contracts while non-compliant vendors exit European medical display supply chains.
- China's Dual Carbon Mandate:SAMR-administered GB standards for electronic component recyclability are accelerating solvent-free adhesive development in polarizer film stack designs. Domestic material suppliers are qualifying cellulose acetate alternatives with lower carbon footprints.
Market Restraints
- Iodine Supply Concentration:Chilean and Japanese iodine refiners control over 70% of global feedstock for PVA-doping processes. Price volatility in this input directly compresses margin structures for non-integrated polarizer film manufacturers.
- JIS Dimensional Stability Requirements:Japan's METI enforces tight thermal expansion coefficients that extend supplier qualification timelines to 18-24 months. This creates a structural barrier for new entrants targeting precision display applications.
- Quantum Dot Display Substitution:Self-emissive QD-OLED panels reduce reliance on external polarization layers for contrast enhancement. Samsung Display and LG Display are redirecting capex toward QD-OLED capacity in South Korea.
Strategic Opportunities
- Medical Display Certification Gap:South Korea's MFDS hazardous substance reporting requirements for adhesives and protective films remain underpenetrated by Chinese suppliers. Early compliance investments open procurement channels into diagnostic imaging panel supply chains.
- Sunlight-Readable Automotive Integration:Circular polarizer demand for head-up displays and mirror-replacement cameras is outpacing dedicated coating capacity. Firms with retardation film lamination expertise can wedge into this white space.
- Polyvinyl Alcohol Resin Backward Integration:Captive PVA production secures margin pools and insulates against iodine-doping process disruptions. Sumitomo Chemical's resin-to-film model demonstrates the structural advantage.
Industry Challenges
- Optical Coating Talent Scarcity:Precision retardation layer deposition requires rare combinations of polymer chemistry and thin-film physics expertise. South Korea's display component cluster faces acute competition for these specialists from semiconductor equipment firms.
- Multi-Regulatory Compliance Parallel Processing:Simultaneous qualification against Japan's JIS standards, EU REACH substance restrictions, and China's GB recyclability mandates stretches technical documentation teams. Certification timeline misalignment risks contract loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polarizer Film Market |
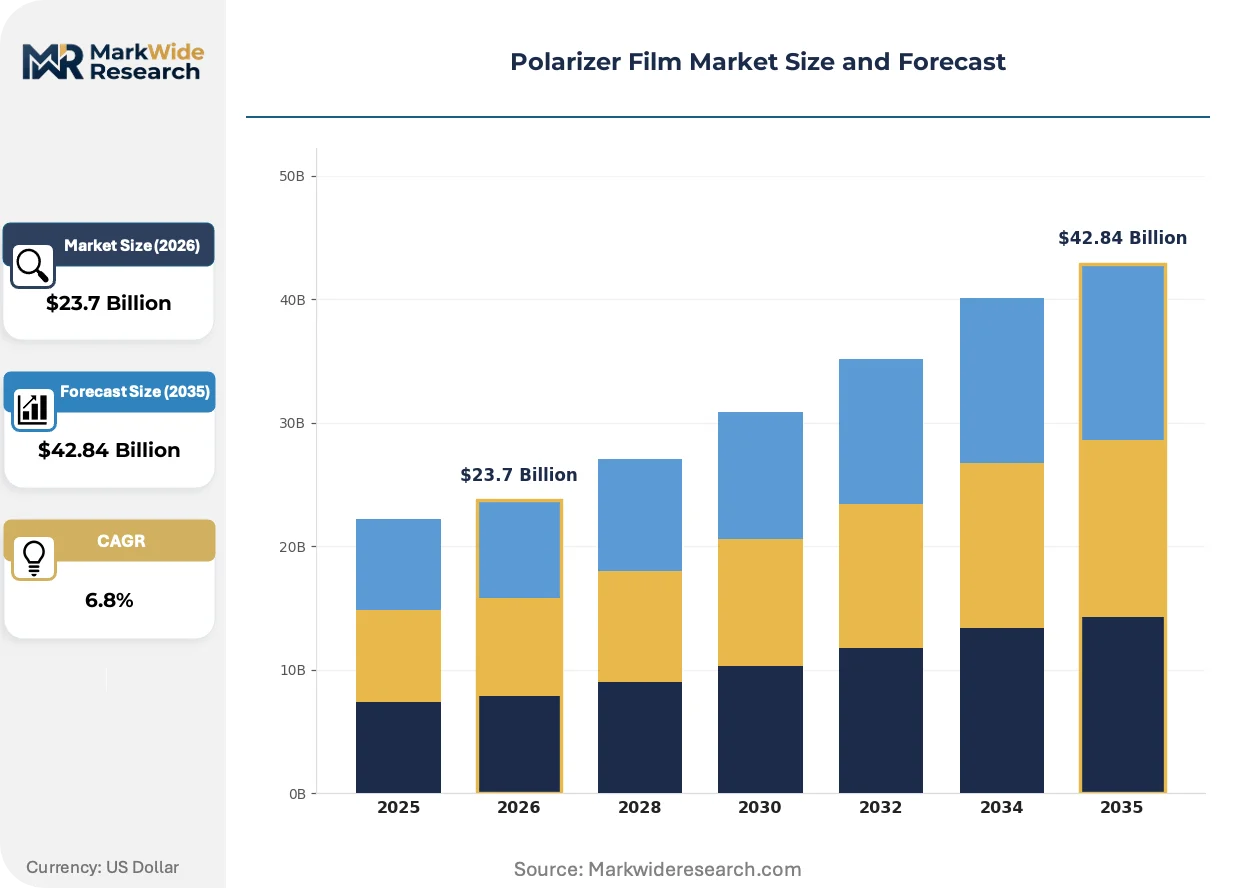
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
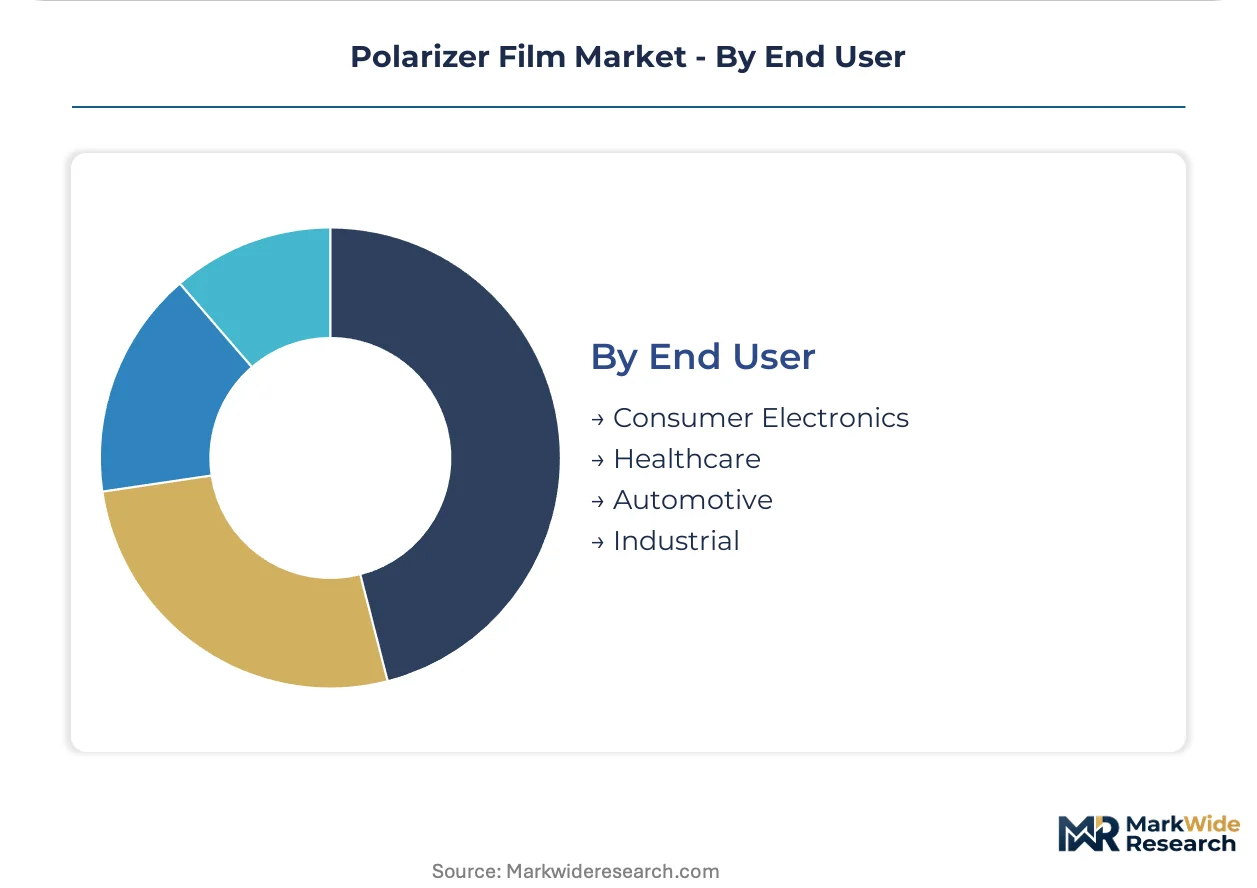
| Segmentation | Product Type: Linear Polarizers, Circular Polarizers, Color Polarizers, Specialty Polarizers Application: Display Devices, Optical Instruments, Photography, Automotive Displays Material: Polyvinyl Alcohol, Cellulose Acetate, Polycarbonate, Others End User: Consumer Electronics, Healthcare, Automotive, Industrial |
| Companies Covered | BenQ Materials, SAPO, Nitto Denko, SDI, Optimax, Sumitomo Chemical, Hengmei Optoelectronics, CMMT, Shanjin Optoelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polarizer Film Market Emerging Trajectories
Wet-coating process innovation is reshaping how polarizer films achieve optical performance thresholds. Suppliers are abandoning legacy solvent-intensive methods in favor of aqueous formulations that align with tightening chemical compliance regimes.
Water-based iodine-doping systems are electrifying cost structures in high-volume LCD panel supply chains. Chinese polarizer film manufacturers in Anhui and Jiangsu provinces are retrofitting coating lines to eliminate volatile organic compound emissions. This transition compresses operating expenditure for suppliers serving domestic television OEMs while satisfying MEE enforcement of dual carbon goals.
EU REACH substance restrictions on halogenated flame retardants are forcing reformulation of protective film substrates. Cellulose triacetate suppliers are accelerating qualification of phosphorus-based alternatives that maintain dimensional stability under JIS thermal cycling tests. Medical display manufacturers in Germany and the Netherlands face the steepest reformulation timelines as ECHA enforcement intensifies for adhesives in patient-facing equipment.
Automotive procurement teams are consolidating supplier bases around firms with integrated circular polarizer capabilities. Tier-1 integrators now specify single-source accountability for quarter-wave retardation films, anti-reflective coatings, and pressure-sensitive adhesives. This concentration is most visible in South Korea, where Hyundai Mobis and Samsung SDI are reducing qualified vendor lists from twelve to four for next-generation cockpit display programs.
Polarizer Film Market Segmentation

Polarizer film procurement patterns diverge sharply across technical specifications and end-use requirements. Each segmentation dimension reveals distinct margin structures and qualification barriers that reshape supplier competitive positioning.
Product Type:
Buyers differentiate primarily by optical performance thresholds and coating complexity rather than unit cost.
- Linear Polarizers:Manufactured by stretching polyvinyl alcohol sheets doped with iodine or dichroic dyes to achieve high extinction ratios. LCD television and monitor panel manufacturers in South Korea's Gyeonggi Province cluster dominate procurement volumes, though quantum-dot display substitution is eroding long-term contract security.
- Circular Polarizers:Combine linear polarizers with quarter-wave retardation films to convert unpolarized light into circular polarization. Automotive OLED procurement for dashboard and pillar-to-pillar configurations is accelerating fastest, with Tier-1 integrators specifying anti-reflective coating bundles that exceed legacy television benchmarks.
- Color Polarizers:Incorporate dyed substrates for wavelength-selective polarization control.
- Specialty Polarizers:Engineered for extreme temperature or mechanical stress environments.
Linear polarizers lead volumes today; circular polarizers are gaining share fastest.
Application:
End-use specifications determine coating line investments and regulatory compliance burdens.
- Display Devices:Television, monitor, and mobile panel applications demand high-volume production with tight optical clarity tolerances. Chinese domestic OEMs are consolidating procurement around aqueous coating suppliers that satisfy MEE enforcement of dual carbon goals.
- Automotive Displays:Curved OLED and head-up display configurations require circular polarization with quarter-wave retardation precision. Hyundai Mobis and Samsung SDI are reducing qualified vendor lists from twelve to four for next-generation cockpit programs.
- Optical Instruments:Laboratory and measurement equipment requires dimensional stability under JIS thermal cycling protocols.
- Photography:Camera filter applications prioritize scratch-resistant protective substrates.
Display devices absorb the majority of production capacity; automotive displays command the steepest expansion trajectory.
Material:
Substrate chemistry dictates backward integration economics and iodine-doping process compatibility.
- Polyvinyl Alcohol:Dominates high-volume flows due to established stretching infrastructure and iodine-doping maturity. Sumitomo Chemical's captive resin production demonstrates how upstream control secures margin pools against Chilean and Japanese iodine refiner concentration.
- Cellulose Acetate:Serves as the primary protective substrate laminated to PVA cores. EU REACH restrictions on halogenated flame retardants are forcing phosphorus-based reformulation for medical display manufacturers in Germany and the Netherlands.
- Polycarbonate:Offers superior impact resistance for automotive and industrial applications.
- Others:Emerging biodegradable alternatives under qualification for China's GB recyclability mandates.
Polyvinyl alcohol anchors current production; cellulose acetate alternatives are climbing fastest on regulatory pressure.
End User:
Customer procurement sophistication ranges from commodity volume tenders to multi-year qualification partnerships.
- Consumer Electronics:Television and smartphone OEMs drive the deepest volume pools with aggressive cost-down schedules. Chinese manufacturers in Anhui and Jiangsu provinces are retrofitting coating lines to eliminate volatile organic compound emissions.
- Automotive:OEM procurement teams now specify optical clarity thresholds exceeding legacy benchmarks, compressing supplier qualification timelines to 12-18 months for circular polarizer integration.
- Healthcare:Diagnostic imaging panel manufacturers face South Korea's MFDS hazardous substance reporting requirements for adhesives and protective films.
- Industrial:Machine vision and automation applications demand extended operational temperature ranges.
Consumer electronics commands absolute volume; automotive is expanding most quickly on display integration intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical coating specialists concentrate in South Korea's Gyeonggi Province, where Hyundai Mobis and Samsung SDI compress supplier qualification timelines for circular polarizer integration. Japan's METI enforces JIS dimensional stability standards that extend technical documentation cycles. China's MEE enforces dual carbon goals through GB standards for electronic component recyclability.
China
Domestic television OEMs in Anhui and Jiangsu provinces are retrofitting coating lines to eliminate volatile organic compound emissions. SAMR-administered GB standards for electronic display component recyclability accelerate solvent-free adhesive development in polarizer film stack designs. The Yangtze River Delta cluster hosts aqueous iodine-doping system qualification programs for high-volume LCD panel supply chains.
Japan
Precision display applications demand tight thermal expansion coefficients that extend supplier qualification timelines to 18-24 months. METI enforces JIS standards on optical film dimensional stability that constrain new market entry. Chubu region manufacturers leverage captive iodine-doping expertise to sustain margin structures despite compliance investments.
South Korea
Automotive OLED procurement for dashboard and pillar-to-pillar configurations accelerates circular polarizer demand fastest. MFDS hazardous substance reporting requirements affect adhesives and protective films used in medical display devices. The Gyeonggi Province display component cluster scales dedicated coating lines for quarter-wave retardation specifications.
Germany
Medical display manufacturers face steep reformulation timelines as ECHA enforcement intensifies for adhesives in patient-facing equipment. EU REACH substance restrictions on halogenated flame retardants force phosphorus-based alternatives for cellulose triacetate protective substrates. Bavaria-based diagnostic imaging panel producers consolidate procurement around compliant coating suppliers.
United States
Automotive procurement teams specify optical clarity thresholds exceeding legacy television benchmarks for head-up display integration. EPA enforcement of volatile organic compound emissions affects coating line investments for domestic polarizer film manufacturers. Michigan and Ohio automotive clusters drive circular polarizer qualification for mirror-replacement camera systems.
Polarizer Film Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive resin production and specialized optical film manufacturers with precision coating expertise. Three archetypes dominate: diversified materials conglomerates controlling upstream polyvinyl alcohol resin supply, dedicated optical film specialists with iodine-doping process maturity, and emerging Chinese manufacturers retrofitting aqueous coating lines for domestic volume. Capacity expansion and backward integration into raw material production represent the dominant competitive moves.
Among Japanese chemical conglomerates, Nitto Denko and Sumitomo Chemical exemplify the integrated archetype through in-house control of critical input supply chains. BenQ Materials occupies a position among Taiwan-based specialists competing on optical clarity specifications for premium notebook panels. SDI represents the Korean tier-1 integrator category consolidating qualified vendor lists for next-generation cockpit display programs. These three anchors demonstrate how geographic concentration of optical coating talent reinforces structural barriers for new entrants.
| Leading Market Players |
|---|
| BenQ Materials |
| SAPO |
| Nitto Denko |
| SDI |
| Optimax |
| Sumitomo Chemical |
| Hengmei Optoelectronics |
| CMMT |
| Shanjin Optoelectronics |
| Others |
Supply Flow & Price Mechanics
Tier-1 automotive display integrators in South Korea's Gyeonggi Province cluster command project-based long-term offtake contracts that bundle circular polarizer specifications with anti-reflective coating services. This buyer concentration shifts pricing power toward suppliers with integrated quarter-wave retardation capabilities while squeezing margin structures for non-integrated vendors serving commodity LCD panel contracts.
Pricing Analysis
Unbundled component sales dominate legacy LCD television supply chains while bundled optical clarity packages capture premium positioning in automotive OLED procurement. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified precision grades from general-purpose specifications. Cost compression in standard-tier linear polarizers is intensifying because Chinese manufacturers in Anhui and Jiangsu provinces are retrofitting aqueous coating lines to eliminate volatile organic compound emissions. Consumer electronics OEMs drive the steepest price sensitivity; medical display manufacturers exhibit the least due to MFDS hazardous substance reporting compliance requirements.
Supply Chain Analysis
Regional distribution centers in South Korea's Gyeonggi Province, Japan's Chubu region, and China's Yangtze River Delta form a hub-and-spoke pattern that feeds precision coating lines. Manufacturing draws from Chilean and Japanese iodine refiners controlling over seventy percent of global PVA-doping feedstock, Sumitomo Chemical's captive polyvinyl alcohol resin production, and cellulose acetate protective substrate suppliers. Single-source vulnerability in iodine supply concentration presents acute exposure to price volatility and geopolitical disruption. Distribution runs through Tier-1 display integrator consolidation programs that reduce qualified vendor lists from twelve to four for next-generation cockpit display programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polarizer film procurement represents a geographic-arbitrage play where South Korea's MFDS hazardous substance reporting requirements impose compliance costs that Chinese suppliers can undercut by qualifying solvent-free adhesive alternatives for domestic medical display contracts.
For Market Incumbents: Acquire aqueous iodine-doping system expertise to defend margin structures against Chinese manufacturers retrofitting coating lines for MEE dual carbon enforcement. Secure captive polyvinyl alcohol resin production to insulate against Chilean and Japanese iodine refiner concentration. Prioritize JIS dimensional stability certification investments to extend structural barriers for new entrants targeting precision display applications. For New Entrants and Emerging Players: Water-based coating technology for circular polarizer integration offers the most penetrable wedge into automotive OLED supply chains where Tier-1 integrators face acute coating capacity constraints. Target South Korea's medical display certification gap where MFDS hazardous substance reporting requirements remain underpenetrated by Chinese suppliers. Lead with solvent-free adhesive qualification programs that satisfy SAMR-administered GB standards for electronic component recyclability. For Investors and Strategic Acquirers: Chemical conglomerates with captive resin production are the most active acquirer in this space, seeking to replicate Sumitomo Chemical's upstream control model. Long-term viability hinges on automotive display integration intensity outpacing quantum-dot display substitution. Acquisition target archetype: specialized optical film manufacturers with precision retardation layer deposition expertise and existing JIS qualification timelines. The signal to watch is Hyundai Mobis and Samsung SDI vendor list consolidation velocity for next-generation cockpit programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVA Resin | Captive supply of polyvinyl alcohol insulates margin structures against iodine feedstock volatility. |
| Aqueous Coating Line Retrofit | Elimination of volatile organic compound emissions satisfies MEE enforcement of China's dual carbon goals. |
| JIS Dimensional Stability Certification | METI-enforced thermal expansion standards extend structural barriers for precision display applications. |
| Circular Polarizer Capacity Expansion | Quarter-wave retardation coating lines capture automotive OLED procurement from Gyeonggi Province integrators. |
| Solvent-Free Adhesive Development | SAMR-administered GB standards for recyclability accelerate qualification for domestic medical display supply chains. |
Methodological Framework
Bottom-up display device modeling reconciled against top-down polarizer film production tracking forms the analytical core of this study. Primary interviews with optical coating specialists, Tier-1 display integrator procurement teams, polyvinyl alcohol resin plant managers, and MEE regulatory enforcement officers combined with secondary validation from customs trade data, SEC 10-K filings of diversified chemical conglomerates, METI JIS standard documentation, and ECHA REACH substance restriction updates. Triangulation across these sources isolates volume flows by product type, application, and end-use qualification tier.
Input-output matrices map iodine-doping process capacity, coating line utilization rates, and automotive OEM procurement schedules across the projection horizon. Segmentation dimensions modeled include linear versus circular polarizer product types, display device versus automotive display applications, polyvinyl alcohol versus cellulose acetate material chemistries, and consumer electronics versus healthcare end-user procurement sophistication. CAGRs derive from regression analysis of historical capacity expansion patterns against automotive display integration intensity forecasts. Industry-specific inputs include quantum-dot display substitution rates and EU REACH halogenated compound restriction enforcement timelines.
The model holds under sustained automotive OLED adoption and stable iodine feedstock availability; deviation in quantum-dot display substitution velocity or Chilean refiner supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions regarding JIS qualification timeline stability and SAMR GB standard implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Waveguide Phase Shifter Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Ellipsometer Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Objective Lens Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Passive Optical Component Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Infrared Filter Market
Optical Components
Optical Position Sensors Market
Optical Components
Raman Amplifier Market