
 Optical Instruments and Lenses Market | 2026-2036
Optical Instruments and Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Instruments and Lenses Market Outlook
Specialized distributor networks for scientific instrumentation is reconfiguring as direct-to-researcher digital platforms capture volume previously routed through regional dealers. Carl Zeiss AG leverages its captive glassworks in Oberkochen to sustain premium positioning in semiconductor metrology optics. Nikon Corporation anchors Japanese supply chains for lithography-grade fluorite crystals, while Thorlabs Inc. competes aggressively on modular photonics kits for university laboratories.
Optical instruments and lenses encompass precision-engineered transparent media—typically silica, fluorite, or engineered polymers with surface accuracies below λ/20—that manipulate electromagnetic radiation through refraction, reflection, or diffraction for imaging, measurement, or signal transmission. These components require sub-micron polishing, ion-beam figuring, and thin-film coating processes to achieve specified wavefront errors for industrial deployment. Cameras and microscopy systems generate the largest revenue pools, though thermal imaging technology captures expanding margins from defense and industrial automation budgets. Medical imaging applications concentrate demand for high-NA objectives in histopathology and ophthalmic diagnostics.
The US FDA governs diagnostic optical devices through 510(k) premarket pathways, while the EU MDR imposes stricter clinical evidence requirements on ophthalmic instruments sold in member states. Japan's METI coordinates national R&D consortia for extreme-ultraviolet lithography optics, directly shaping supplier qualification timelines. Stakeholders must monitor which regulatory jurisdiction certifies first for next-generation computational imaging platforms, as that approval sequence typically determines subsequent market access negotiations.
Market Dynamics
Semiconductor lithography systems are compressing wavelength tolerances below 13.5nm for high-NA EUV production, forcing optical suppliers to reconfigure polishing and metrology workflows around atomic-scale surface accuracy requirements.
Growth Catalysts
- Advanced node lithography:Chipmakers at 2nm and below require hyper-NA objectives with wavefront errors below 0.1nm RMS, pulling precision glass and fluorite demand through specialized supply chains.
- F-Gas Regulation phase-down:The EU's tightening fluorinated gas controls for lens manufacturing are accelerating investment in alternative etching chemistries and closed-loop process gas recovery systems.
- Computational imaging platforms:Histopathology digitization and AI-augmented diagnostics in the US and Japan are concentrating procurement for high-NA microscope objectives with integrated sensor arrays.
Market Restraints
- Fluorite crystal supply concentration:Japanese and Chinese suppliers control lithography-grade calcium fluoride blank production, creating single-source vulnerability for EUV objective manufacturers.
- Helium-3 neutron detection diversion:Defense and scientific imaging applications face competing demand from quantum computing cryogenics, pressuring thermal neutron imaging lens availability.
- REACH substance restrictions:The EU's evolving candidate list for SVHCs threatens lead oxide and cadmium-containing optical glasses used in radiation-hardened space optics.
Strategic Opportunities
- India laboratory modernization:The country's PLI scheme for scientific instrumentation is opening tender volumes for modular optical microscopy systems previously supplied through import channels.
- Direct-to-researcher platforms:Digital procurement portals are capturing university and startup volume from regional distributor networks, compressing channel margins but expanding addressable accounts.
- SWIR imaging convergence:Integration of short-wave infrared sensors with conventional visible optics is creating new application space for industrial automation and agricultural monitoring.
Industry Challenges
- Ion-beam figuring technician scarcity:Sub-nanometer surface correction requires operators trained on proprietary equipment from a shrinking pool of experienced practitioners in Germany and Japan.
- 510(k) premarket pathway compression:The US FDA's evolving substantial equivalence standards for diagnostic ophthalmic devices are extending clearance timelines and requiring expanded clinical datasets.
- Legacy metrology integration:New computational optics platforms must interface with hospital PACS and laboratory LIMS infrastructure built on decades-old software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Instruments and Lenses Market |
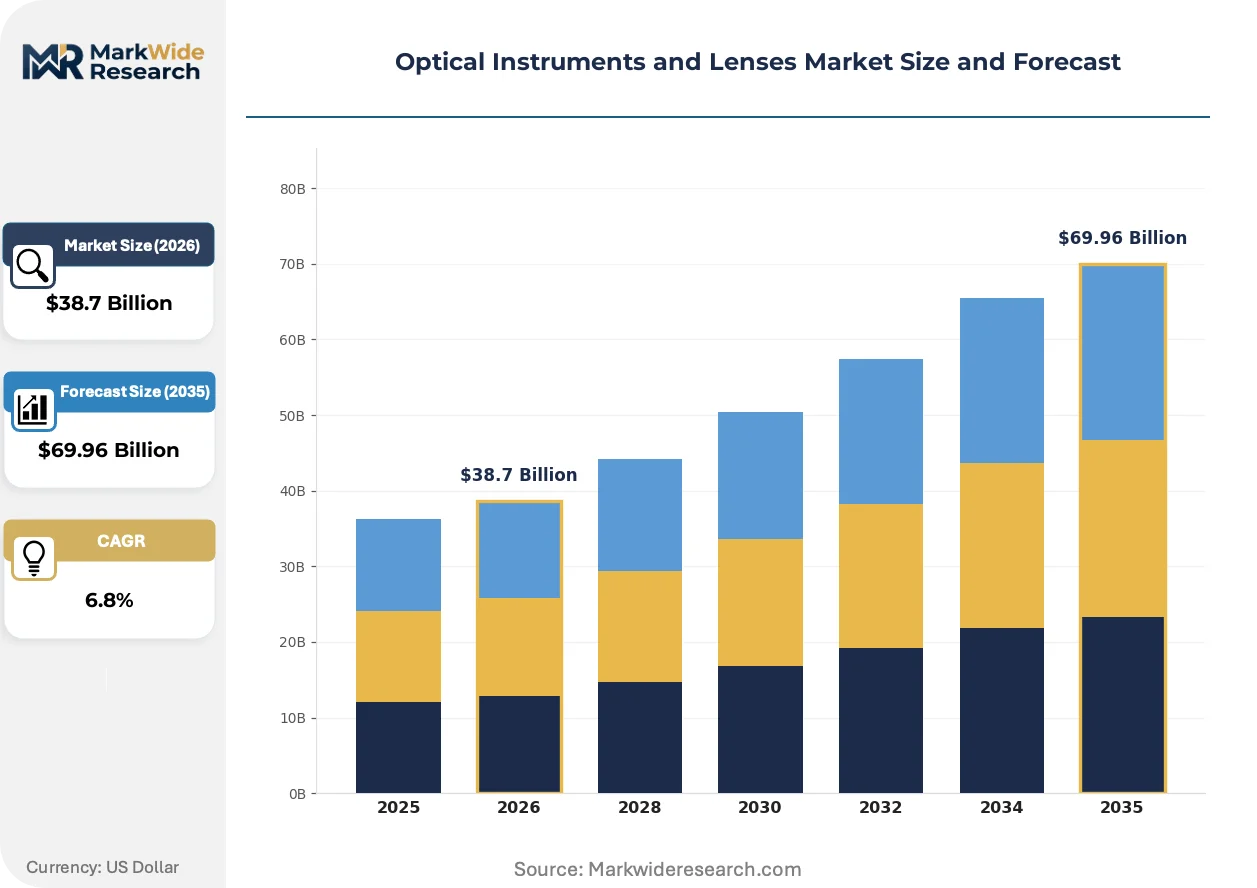
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Microscopes, Telescopes, Projectors Application: Medical Imaging, Scientific Research, Photography, Surveillance End User: Hospitals, Educational Institutions, Professional Photographers, Government Agencies Technology: Digital, Analog, High-Speed, Thermal |
| Companies Covered | Canon Inc., Nikon Corporation, Carl Zeiss AG, ZEISS International, Olympus Corporation, Thorlabs Inc., Edmund Optics, Sunny Optical Technology (Group) Company Limited, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Instruments and Lenses Market Strategic Shifts
Freeform surface manufacturing and computational aberration correction are dissolving the traditional trade-off between optical complexity and assembly precision, enabling designs previously excluded by cost or volume constraints.
Metalens arrays fabricated through semiconductor-compatible lithography are collapsing the size and cost barriers for polarization-selective and chromatic-aberration-corrected imaging in smartphone and automotive LiDAR modules. Tier-one automotive suppliers in Germany and South Korea are qualifying these flat optics for cabin-monitoring and surround-view systems at production volumes exceeding ten million units annually. The structural consequence is compressing demand for conventional molded glass aspheres in sub-20mm aperture applications.
The EU F-Gas Regulation's phased reduction of sulfur hexafluoride and perfluorocarbon emissions is compelling lens manufacturers to retrofit etching and cleaning processes with fluorine-nitrogen mixtures or plasma-based alternatives. German and French optical houses are reporting 15-30% process revalidation costs as they recertify surface quality on modified production lines. Semiconductor lithography optics face the steepest compliance burden given their reliance on fluorinated chemistry for final surface treatment.
University procurement offices are consolidating optical instrumentation purchases through shared-services organizations, displacing departmental autonomy in vendor selection with centralized framework agreements. Thorlabs, Edmund Optics, and niche photonics distributors are responding with configurable kit pricing and extended payment terms tailored to institutional purchasing cycles. This concentration is most visible in US Research-1 universities and UK Russell Group institutions where capital equipment budgets have shifted to cloud-style subscription models for high-end microscopy platforms.
Optical Instruments and Lenses Market Segmentation
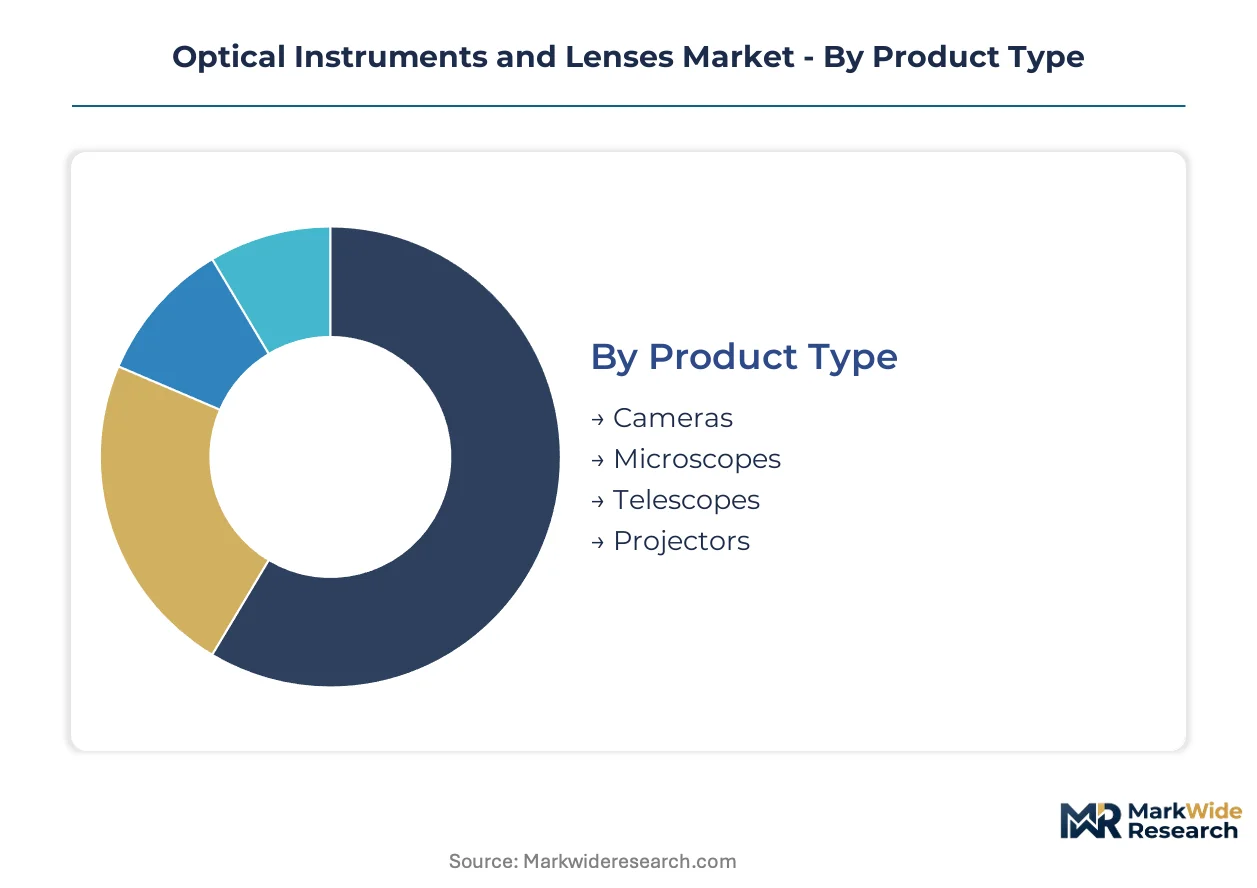
Segmentation in optical instruments and lenses reveals how technical specifications, institutional procurement patterns, and imaging modalities fragment addressable demand across radically different value chains and certification requirements.
Product Type:
Mature hardware categories dominate installed base revenue while emerging form factors capture specification-driven replacement cycles.
- Cameras:Image sensors paired with precision-engineered lens assemblies span industrial machine vision to consumer electronics. Demand concentrates in smartphone module supply chains from South Korea and China, driven by computational photography integration requiring tighter optical-sensor alignment tolerances.
- Microscopes:Compound and stereoscopic systems with objectives corrected for chromatic and spherical aberration serve histopathology and materials science. German and Japanese manufacturers anchor high-NA objective production for semiconductor metrology and clinical diagnostics, pulled by digitization mandates in hospital pathology departments.
- Telescopes:Astronomical and terrestrial observation systems with large-aperture primary mirrors. Research observatories in Chile and Hawaii drive demand for adaptive optics-equipped instruments.
- Projectors:Digital light processing and liquid-crystal-on-silicon engines for cinema and corporate presentation. Corporate and education procurement in India and Southeast Asia sustains volume for lamp-based and solid-state illumination systems.
Cameras handle the majority of throughput; microscopes are climbing the fastest on share as clinical digitization accelerates.
Application:
End-use concentration determines margin structure, with regulated medical applications commanding premium pricing over consumer and security deployments.
- Medical Imaging:Ophthalmic diagnostics, endoscopy, and surgical microscopy requiring FDA 510(k) or EU MDR certification. German optical houses supply cataract surgery microscopes to hospital systems in the US and Japan, constrained by extended clearance timelines for AI-augmented diagnostic platforms.
- Scientific Research:Laboratory and field instrumentation for physics, biology, and chemistry. University shared-services procurement in the UK and US is consolidating vendor relationships, compressing margins for modular photonics suppliers.
- Photography:Professional and enthusiast imaging systems. Japanese manufacturers dominate interchangeable-lens camera production for wedding and commercial studios.
- Surveillance:Fixed and pan-tilt-zoom cameras for perimeter security and traffic monitoring. Chinese integrators supply thermal-visible fusion systems to Middle Eastern infrastructure projects.
Medical imaging commands the steepest price premiums; scientific research is expanding most quickly as national laboratory budgets recover.
End User:
Procurement authority centralization is reconfiguring channel economics across institutional buyer categories.
- Hospitals:Integrated delivery networks and academic medical centers with capital equipment committees. US health systems are shifting high-end microscopy to subscription service models, displacing outright purchase.
- Educational Institutions:Universities and secondary schools with framework agreements through shared-services organizations. Thorlabs and Edmund Optics compete for modular kit contracts with extended payment terms aligned to fiscal year cycles.
- Professional Photographers:Independent studios and agency contractors with brand-loyal equipment refresh patterns. Wedding and commercial segments in Italy and Brazil sustain medium-format digital back demand.
- Government Agencies:Defense, space, and environmental monitoring departments with security-cleared supply chains. NASA and ESA procurement specifications drive radiation-hardened optical glass development.
Hospitals represent the largest addressable spend; educational institutions are gaining share fastest through consolidated procurement platforms.
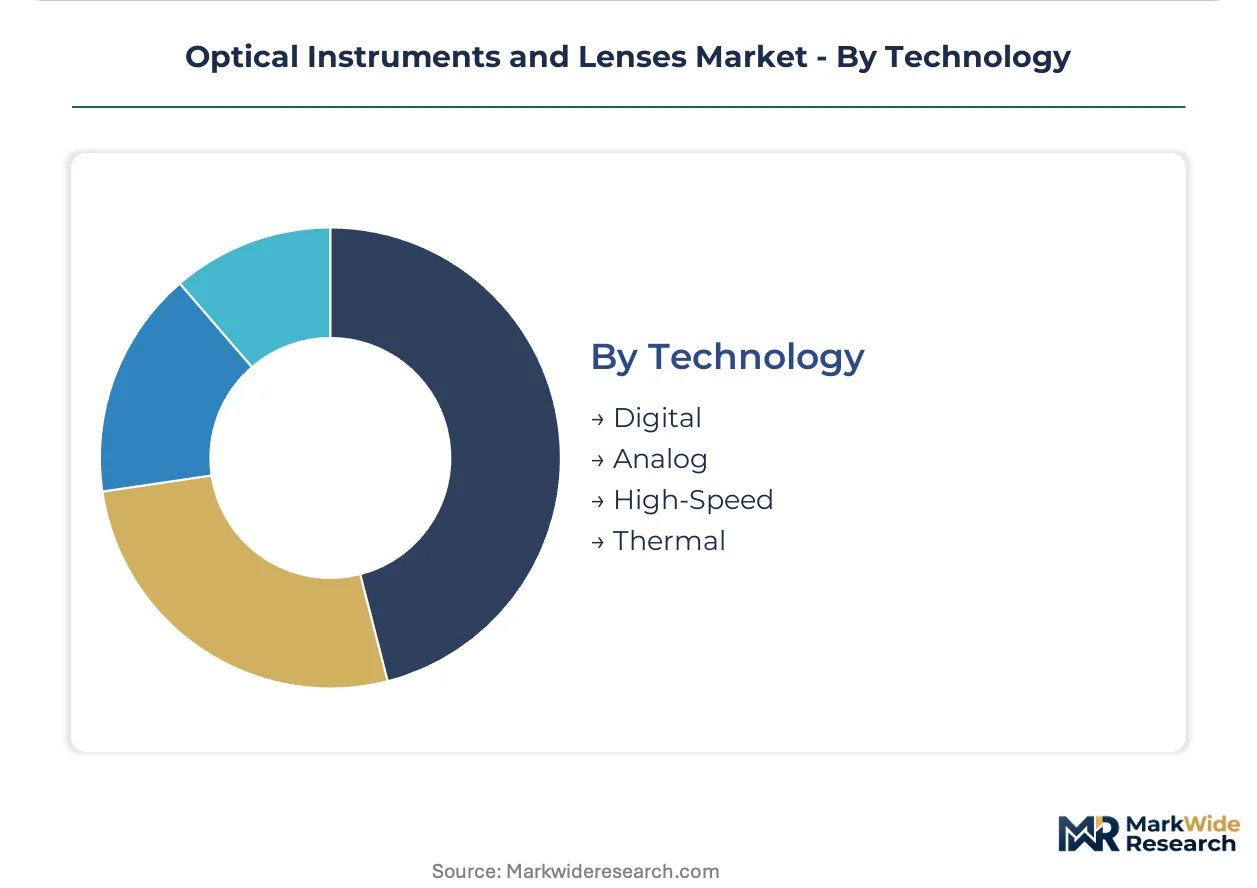
Technology:
Imaging modality determines semiconductor content, thermal management requirements, and software integration complexity.
- Digital:CMOS and CCD sensor-based systems with embedded signal processing. Smartphone and automotive LiDAR module demand from Germany and South Korea is pulling metalens qualification for sub-20mm aperture applications.
- Analog:Film-based capture and purely optical viewing systems. Niche preservation in fine-art photography and astronomical observation sustains specialty coating and precision polishing demand.
- High-Speed:Frame rates exceeding 10,000 fps for ballistic, combustion, and microfluidic analysis. Automotive crash testing facilities in Michigan and Stuttgart drive specialized camera rental and purchase cycles.
- Thermal:Infrared detectors for SWIR, MWIR, and LWIR wavebands. Defense and industrial automation budgets in the US and Israel are expanding uncooled microbolometer deployment for perimeter security.
Digital technology captures the dominant revenue share; thermal imaging is the fastest mover on share as industrial automation penetrates agricultural and predictive maintenance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA governs diagnostic optical devices through 510(k) premarket pathways in the United States, while multiple jurisdictions compete to certify next-generation computational imaging platforms first.
United States
Hospital systems and semiconductor fabs drive precision optics procurement. The FDA's evolving substantial equivalence standards extend clearance timelines for AI-augmented ophthalmic diagnostics. Michigan and Arizona host automotive crash-testing facilities that sustain specialized high-speed camera demand.
Germany
Automotive LiDAR module manufacturers and scientific instrument makers anchor consumption. The EU F-Gas Regulation compels lens manufacturers to retrofit etching processes with fluorine-nitrogen mixtures. Oberkochen and Jena concentrate captive glassworks and ion-beam figuring capacity for lithography-grade components.
China
Smartphone module supply chains and precision glass blank production dominate activity. The country's national industrial regulator enforces dual carbon goals that reshape polishing process energy profiles. Yangtze River Delta clusters control fluorite crystal supply chains for high-NA optical components.
Japan
Chipmakers scaling advanced node production and university research laboratories pull specialized demand. METI coordinates national R&D consortia for extreme-ultraviolet lithography optics, directly shaping supplier qualification timelines. Nagoya and Osaka anchor lithography-grade fluorite crystal supply chains.
India
National laboratory budget recoveries and university modernization programs expand procurement. The PLI scheme for scientific instrumentation opens tender volumes for modular optical microscopy systems. Bengaluru and Hyderabad concentrate shared-services organizations consolidating vendor relationships.
Optical Instruments and Lenses Market Competitive Environment
Vertically integrated conglomerates and specialized modular suppliers split the market into distinct competitive spheres. Consolidation concentrates around captive glassmaking capacity and lithography-grade fluorite sourcing. Three archetypes dominate: precision glassworks with in-house polishing, modular photonics kit assemblers, and semiconductor metrology specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure atomic-scale surface accuracy capabilities.
Among Japanese fabricators, Nikon Corporation occupies a position within the lithography-grade materials tier. German specialists exemplify vertically integrated precision manufacturing, with Carl Zeiss AG representing the captive glassworks archetype. Thorlabs Inc. sits within the modular photonics supplier category, competing for university and startup procurement through digital platforms.
| Leading Market Players |
|---|
| Canon Inc. |
| Nikon Corporation |
| Carl Zeiss AG |
| ZEISS International |
| Olympus Corporation |
| Thorlabs Inc. |
| Edmund Optics |
| Sunny Optical Technology (Group) Company Limited |
| Hoya Corporation |
| Others |
Value Chain & Pricing Dynamics
Oberkochen's captive glassworks capacity determines pricing power for lithography-grade objectives, as German optical houses translate atomic-scale surface accuracy capabilities into premium positioning against modular competitors.
Pricing Analysis
Geographic price spreads between German captive manufacturers and Asian modular suppliers exceed three-to-one for high-NA microscope objectives. Three-tier pricing structure across premium lithography, certified medical, and economy educational tiers reflects certification grade and fluorite crystal sourcing. Cost compression in university procurement segments is intensifying because shared-services organizations consolidate vendor relationships. Research laboratories exhibit highest price sensitivity; semiconductor fabs show lowest due to yield-critical specifications.
Supply Chain Analysis
Export-control regimes limiting extreme-ultraviolet lithography equipment flows to Chinese chipmakers are reshaping fluorite crystal allocation patterns. Supply concentrates in Japan and China for lithography-grade calcium fluoride blanks, with German ion-beam figuring capacity providing finishing. Raw material dependencies rest on synthetic silica, rare-earth polishing compounds, and helium-3 for neutron detection optics. Single-source vulnerability in Japanese fluorite sourcing creates structural risk. Distribution runs through direct-to-researcher digital platforms and regional scientific instrument dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational imaging platforms and metalens integration are disrupting century-old optical manufacturing economics, with the EU F-Gas Regulation accelerating process revalidation costs for incumbents.
For Market Incumbents: Insulate lithography-grade positioning through backward integration into synthetic fluorite crystal growth, as Japanese and Chinese suppliers tighten export licensing. Lock hospital system procurement through subscription service models that displace outright capital purchase. Priority lever: secure ion-beam figuring technician pipelines through apprenticeship partnerships with Jena and Nagoya technical institutes.
For New Entrants and Emerging Players: Build out SWIR imaging convergence applications for agricultural automation and predictive maintenance, where industrial buyer specifications remain fluid. India's PLI scheme for scientific instrumentation offers the most penetrable geography, with tender volumes shifting from import channels to local assembly. Go-to-market angle: configurable modular kits with extended payment terms aligned to university fiscal cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive glassworks with in-house polishing capabilities over modular assemblers exposed to commodity glass pricing. Long-term viability hinges on atomic-scale metrology differentiation rather than volume scale. Acquisition target archetype: specialized ion-beam figuring shops with proprietary surface correction algorithms. Signal to watch: FDA 510(k) clearance velocity for AI-augmented ophthalmic diagnostics as inflection indicator for computational imaging platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fluorite Crystal Growth | Backward integration into synthetic calcium fluoride blanks reduces Japanese supply-chain vulnerability for EUV objective manufacturers. |
| Direct-to-Researcher Platform Expansion | Digital procurement portals capture university volume from regional dealers, compressing margins but expanding account reach. |
| Metalens Qualification for Automotive LiDAR | Semiconductor-compatible lithography enables flat-optics deployment in German and South Korean cabin-monitoring systems. |
| F-Gas Regulation Process Retrofit | Fluorine-nitrogen mixture adoption in etching workflows recertifies surface quality for EU lithography optics compliance. |
| Subscription Service Model Conversion | US hospital systems shift high-end microscopy to cloud-style agreements, displacing outright capital equipment purchase. |
Study Parameters
Desk research of SEC filings from precision optics manufacturers, EU regulatory submissions under F-Gas and MDR frameworks, and Japanese METI R&D consortium disclosures preceded structured interviews with ion-beam figuring technicians, hospital biomedical engineers, semiconductor metrology directors, and university procurement officers. Secondary validation drew from customs trade data for fluorite crystal flows, patent filings in freeform surface manufacturing, and GPO contract databases for hospital capital equipment. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Assumptions held fixed include EU F-Gas Regulation phase-down timelines and FDA 510(k) substantial equivalence standards; variables tested included Chinese dual carbon goal enforcement intensity and Indian PLI scheme uptake rates. The analytical framework segmented by product type, application, end user, and technology across the analysis window, with CAGRs derived from fitted growth curves against historical procurement patterns. Forecast inputs incorporated semiconductor node transition schedules and university shared-services consolidation trajectories.
Sensitivities concentrate around fluorite export licensing changes and FDA clearance timeline extensions for AI-augmented diagnostics. Forecasts reflect documented assumptions on lithography wavelength compression rates and metalens qualification velocity. Material shifts in EU regulatory stringency or Chinese precision glass blank allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Global Optical Measurement Market
Optical Components
Global Tunable Filter Market
Optical Components
Europe Tunable Laser Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Duplication Disc Market
Optical Components
100G Optical Transceivers Market
Optical Components
Acousto Optic Devices Market
Optical Components
Polarizer Film Market
Optical Components
Faraday Rotator Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Microchannel Plates Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market