
 Global Hybrid Photonic Integrated Circuit Market | 2026-2036
Global Hybrid Photonic Integrated Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hybrid Photonic Integrated Circuit Market Intelligence
Demand from hyperscale data centers for high-speed interconnects is collapsing the traditional dominance of telecom operators in the component value chain. Intel Corporation leverages its extensive semiconductor fabrication capabilities to advance silicon photonics. Broadcom Inc. dominates the pluggable optics segment with its comprehensive portfolio. Ayar Labs specializes in optical I/O solutions, targeting chip-to-chip communication.
A hybrid photonic integrated circuit combines multiple semiconductor materials, such as Indium Phosphide for light generation and Silicon for light guiding, onto a single substrate. This approach enables the conversion of electrical data signals into optical signals for high-speed, low-power data transmission. Indium Phosphide-based components lead in performance-critical applications, while silicon photonics offers scalability for high-volume data communication. Lidar systems represent the fastest-growing application, driven by automotive and industrial automation needs.
Data transmission standards set by bodies like the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) influence component specifications. The EU's Restriction of Hazardous Substances (RoHS) directive governs material composition, impacting manufacturing processes. Vendor selection increasingly hinges on the ability to navigate these disparate international standards while managing supply chain complexity.
Market Dynamics
The escalating data traffic within hyperscale data centers, driven by artificial intelligence workloads, represents the central structural force in the market. This pressure compels a fundamental technology shift from traditional electrical interconnects to power-efficient, high-bandwidth hybrid photonic integrated circuits.
Growth Catalysts
- Heterogeneous Integration:Combining Indium Phosphide for light generation with Silicon for waveguiding on a single substrate enhances performance and reduces power consumption, accelerating adoption in high-speed transceivers for data centers.
- AI Infrastructure in China:National initiatives and the expansion of domestic cloud providers create sustained demand for high-bandwidth optical components, directly influencing production volumes for next-generation 800G and 1.6T modules.
- Automotive Lidar Advancement:The development of autonomous driving systems requires high-performance, cost-effective Lidar, creating a new volume market for hybrid photonic circuits outside of traditional data communication applications.
Market Restraints
- Indium Phosphide Wafer Cost:The high cost and constrained supply of high-quality Indium Phosphide (InP) wafers, the primary material for lasers and modulators, limit production scalability and present a significant cost barrier.
- Thermal Management Complexity:Integrating active, heat-producing components like lasers with passive silicon photonics introduces significant thermal challenges, impacting long-term device reliability and limiting on-chip power density.
- Complex Fabrication Processes:Manufacturing requires precise, sub-micron alignment and bonding of dissimilar materials, a process that suffers from lower yields compared to standard CMOS fabrication, increasing the effective cost per functional device.
Strategic Opportunities
- Co-Packaged Optics:Moving optical engines closer to processing units like CPUs and GPUs offers a pathway to drastically reduce latency and power consumption, creating a new architecture for future data center switches and servers.
- Quantum Computing Interconnects:The need for cryogenic optical links to control and read out qubits in quantum computers opens a specialized, high-value application for hybrid photonic circuits designed to operate at extremely low temperatures.
- EU Green Deal Incentives:European Union policies promoting energy efficiency in data centers could accelerate the adoption of power-saving photonic solutions, creating a preferential market for components with superior watts-per-gigabit performance.
Industry Challenges
- Multidisciplinary Skill Gaps:A scarcity of engineers with combined expertise in semiconductor physics, optical design, and high-frequency packaging slows product development cycles and limits the ability of firms to scale design teams effectively.
- Lack of Design and Test Standards:The absence of universally accepted standards for testing and qualifying hybrid circuits complicates interoperability between components from different vendors and increases validation time for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hybrid Photonic Integrated Circuit Market |
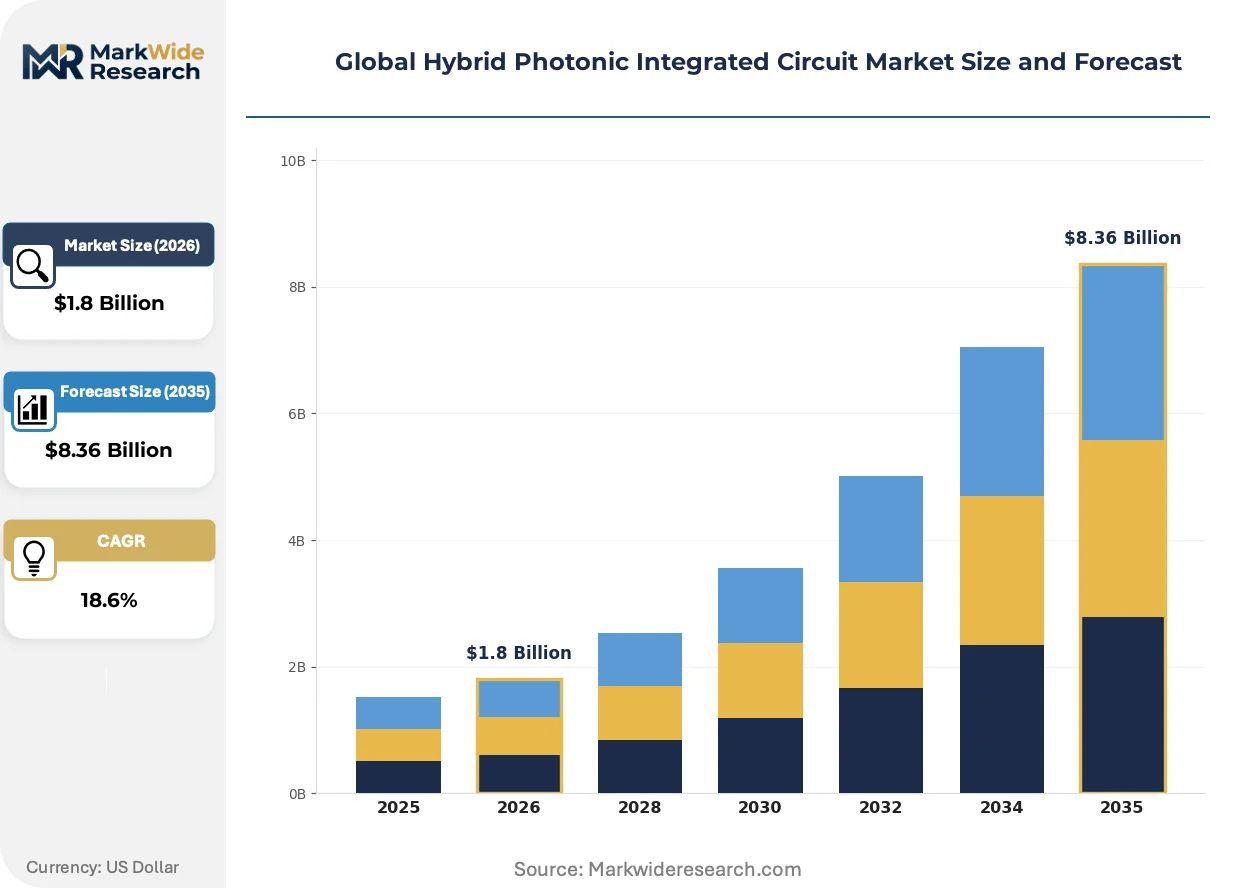
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Photonics, Indium Phosphide, Silicon Nitride, Polymer Photonics Technology: Heterogeneous Integration, Monolithic Integration, Flip-Chip Bonding, Die-to-Wafer Bonding Application: Data Communication, Optical Sensors, Telecommunications, Lidar Systems End User: Telecom Operators, Hyperscale Data Centers, Consumer Electronics Manufacturers, Aerospace & Defense |
| Companies Covered | Marvell Technology, Cisco Systems, Intel Corporation, GlobalFoundries, MACOM, Broadcom Inc., Coherent Corp., Ayar Labs, Lumentum Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hybrid Photonic Integrated Circuit Market Strategic Shifts & Innovations
The convergence of electronics and photonics onto a single substrate is defining the market's trajectory. This deep integration enables new device architectures and challenges established data transmission paradigms within both high-performance computing and advanced sensing systems.
Wafer-level optics technology enables the fabrication of lenses and other micro-optical elements directly on the semiconductor wafer. Hyperscale data center operators and automotive Lidar manufacturers are driving its adoption for high-volume, low-cost assembly. This approach is miniaturizing the final package size and automating the alignment process, which has historically been a major bottleneck in optical component manufacturing.
China's Ministry of Industry and Information Technology (MIIT) is promoting domestic standards for high-speed optical interfaces as part of its national AI and cloud computing strategies. This policy directly influences component specifications for transceivers used by major Chinese cloud service providers. Consequently, component suppliers must adapt their products to meet these MIIT-backed standards to access the country's large and expanding market.
A significant behavioral shift is occurring where hyperscale data center operators engage directly with component designers, bypassing traditional system integrators. This disintermediation allows them to co-design custom photonic integrated circuits tailored to their specific network architectures and AI accelerator hardware. This trend is most prominent in the United States, where large cloud companies dictate specifications for next-generation optical input/output solutions.
Global Hybrid Photonic Integrated Circuit Market Segmentation
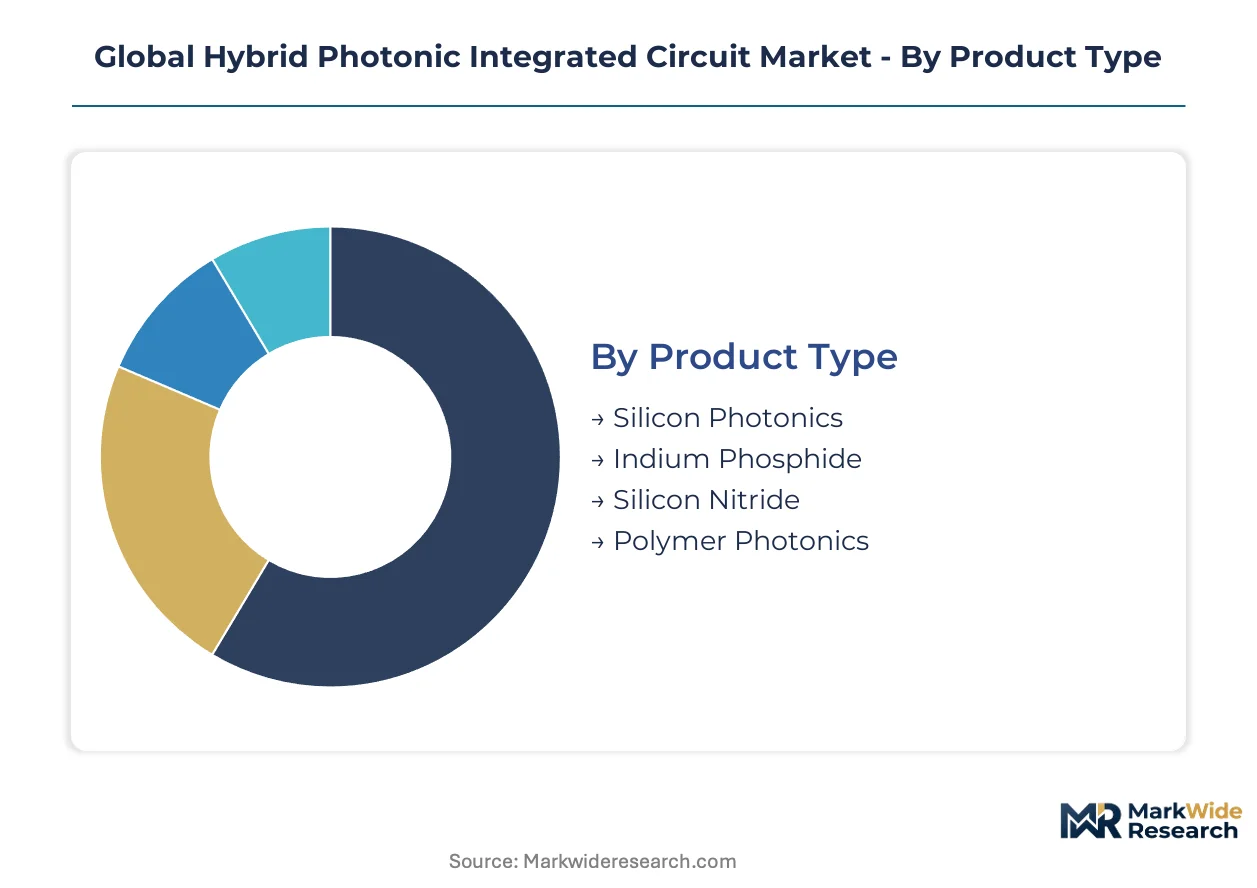
The Global Hybrid Photonic Integrated Circuit market is diverse, necessitating granular segmentation to understand its varied demand drivers and technological underpinnings. Analyzing distinct product types, integration technologies, applications, and end-user profiles reveals specific growth pockets and competitive battlegrounds. This breakdown highlights where innovation is most concentrated.
Product Type:
The product type segment faces distinct substitution pressures, particularly as cost-effective alternatives emerge for certain performance tiers.
- Indium Phosphide:This material excels in high-power and high-speed optical signal generation due to its direct bandgap properties. Demand is concentrating in performance-critical applications like 800G and 1.6T transceivers for hyperscale data centers, where its superior electro-optical conversion efficiency is paramount.
- Silicon Photonics:Utilizing silicon as a waveguide platform, this technology enables high-volume manufacturing leveraging established CMOS processes. Its scalability makes it indispensable for high-bandwidth data communication within data centers, where cost-effectiveness and integration density are key drivers.
- Silicon Nitride:Offering ultra-low loss and high power handling, silicon nitride is gaining traction in quantum computing interconnects and advanced sensing applications requiring high optical power.
- Polymer Photonics:These circuits provide flexibility and ease of integration onto various substrates, finding applications in cost-sensitive, short-reach interconnects and disposable sensor platforms.
Silicon Photonics anchors the volume base while Indium Phosphide gains share at the steepest rate in performance-critical segments.
Technology:
Different integration technologies address varying performance requirements and manufacturing complexities across diverse applications.
- Heterogeneous Integration:This approach combines dissimilar materials, such as Indium Phosphide and Silicon, on a single substrate to leverage the strengths of each. Demand is driven by the need for high-performance optical engines in next-generation data center interconnects, where power efficiency and bandwidth are critical.
- Monolithic Integration:Fabricating all optical and electronic components from a single material system simplifies manufacturing processes and reduces parasitic losses. This technology is crucial for compact, low-cost solutions in high-volume consumer electronics and short-reach optical transceivers.
- Flip-Chip Bonding:This method precisely aligns and connects active optical components to passive waveguide circuits, facilitating high-density packaging.
- Die-to-Wafer Bonding:This technique enables the integration of individual chips onto a larger wafer, offering scalability for advanced photonic devices.
The evolution towards Heterogeneous Integration reflects the industry's drive for enhanced performance and functional versatility.
Application:
Applications are segmented by their strategic importance and the sheer volume of data they process or the precision they demand.
- Data Communication:This segment encompasses high-speed optical links within data centers, local area networks, and enterprise IT infrastructure. Hyperscale data centers in the United States and China represent a significant demand concentration, driven by AI and machine learning workloads requiring massive bandwidth.
- Lidar Systems:Used for 3D mapping and object detection, Lidar systems are critical for autonomous vehicles and industrial automation. The automotive sector, particularly in Germany and Japan, is driving demand for compact, high-performance, and cost-effective hybrid photonic circuits for next-generation Lidar sensors.
- Optical Sensors:These devices detect physical quantities using light, finding use in medical diagnostics, environmental monitoring, and structural health assessment.
- Telecommunications:This segment involves long-haul and metropolitan area networks, requiring robust and high-capacity optical transmission solutions for global connectivity.
While Data Communication remains foundational, Lidar Systems applications are creating significant new market opportunities outside traditional IT infrastructure.
End User:
End users exhibit distinct procurement behaviors and technology adoption curves, influencing product development cycles and market penetration.
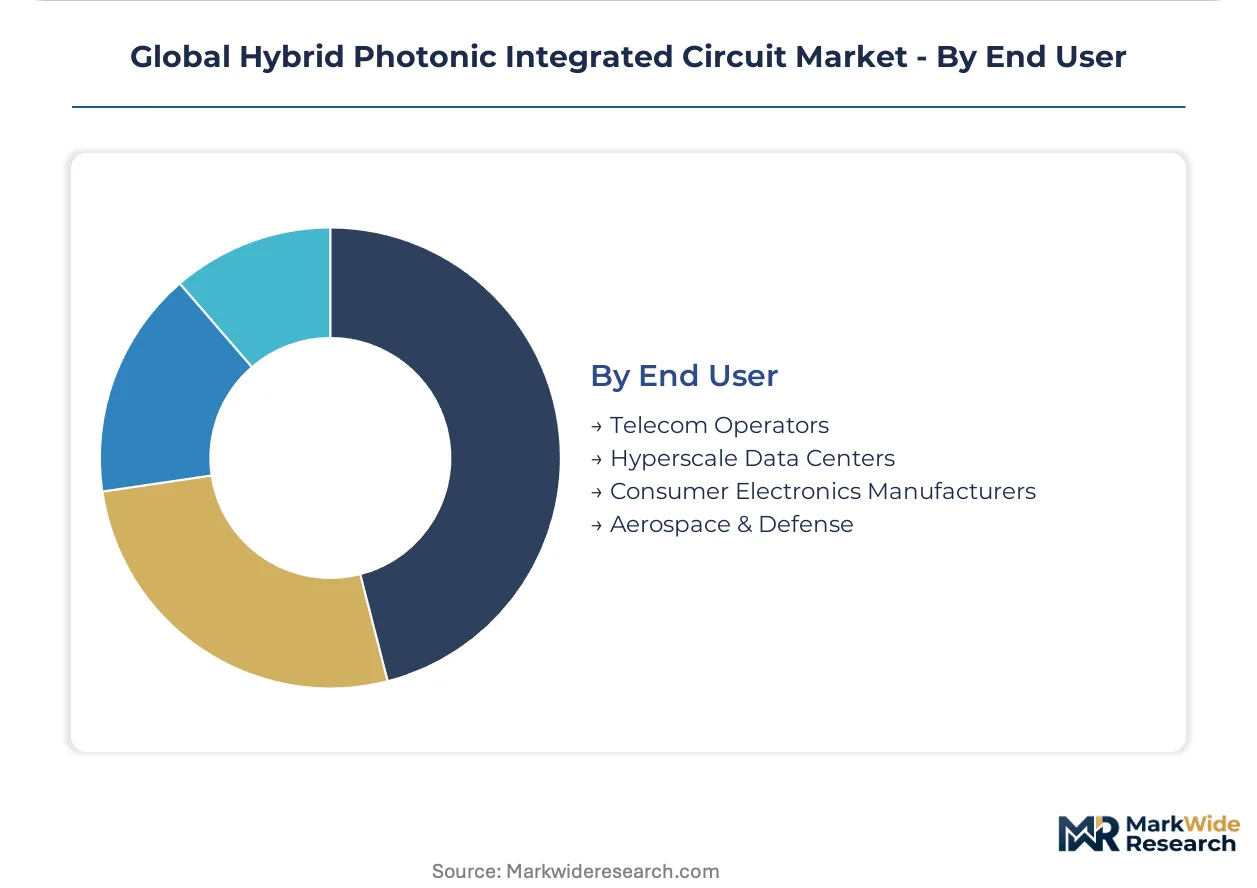
- Hyperscale Data Centers:These operators, primarily located in the United States and China, are direct purchasers of advanced photonic components for their AI and cloud computing infrastructure. Their focus is on power efficiency, latency reduction, and custom co-packaged optics solutions.
- Telecom Operators:Traditional telecom providers require highly reliable and robust optical components for long-haul and metro networks. Their purchasing decisions are often influenced by established standards and long-term infrastructure investment cycles.
- Consumer Electronics Manufacturers:This segment demands high-volume, low-cost integrated photonic solutions for applications such as augmented reality devices and compact sensors.
- Aerospace & Defense:High-reliability, ruggedized photonic circuits are crucial for secure communication, navigation, and sensing in extreme environments.
The shift in demand from Telecom Operators to Hyperscale Data Centers reflects evolving data infrastructure priorities and AI workload growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chain concentration for hybrid photonic integrated circuits increasingly centers on regions with advanced semiconductor manufacturing capabilities. The United States, with its established technology giants and innovative startups, drives significant advancements in core photonic components. This geographic focus ensures a robust ecosystem for next-generation optical solutions.
United States
United States demand for hybrid photonic circuits stems from hyperscale data centers requiring custom co-packaged optics for AI workloads. The US Federal Communications Commission (FCC) influences component specifications for high-speed data transmission. Silicon Valley in California hosts numerous design centers and cloud operators driving optical I/O innovation.
China
China's market expansion is driven by national AI infrastructure projects and domestic cloud service providers needing 800G and 1.6T modules. The Ministry of Industry and Information Technology (MIIT) promotes domestic standards for high-speed optical interfaces. The Yangtze River Delta region concentrates major cloud providers and optical module manufacturing.
Germany
Germany's automotive sector drives demand for compact, high-performance Lidar systems essential for autonomous driving and industrial automation. Kraftfahrt-Bundesamt (KBA) regulations influence safety and performance standards for these automotive components. Baden-Württemberg is a hub for automotive R&D and Lidar technology development.
Japan
Japan's interest in hybrid photonic circuits centers on advanced Lidar systems for robotics, industrial automation, and next-generation automotive applications. The Ministry of Economy, Trade and Industry (METI) supports initiatives for advanced manufacturing and photonics research. The Tokyo metropolitan area houses key robotics and sensor development companies.
Netherlands
Netherlands benefits from EU Green Deal incentives promoting energy efficiency in data centers, accelerating power-saving photonic solutions. The EU's Restriction of Hazardous Substances (RoHS) directive governs material composition for components. Eindhoven has a strong photonics research and manufacturing ecosystem, fostering component innovation.
Global Hybrid Photonic Integrated Circuit Market Key Industry Players
Concentration sits with large, integrated semiconductor companies that leverage extensive fabrication capabilities to advance silicon photonics. The market structure exhibits a tiered consolidation, with established technology firms alongside specialized optical I/O innovators. Strategic partnerships between chip designers and optical component manufacturers are common, particularly for next-generation co-packaged optics. Firms pursue technology licensing and capacity expansion to secure market position and address evolving data center needs.
Within the integrated semiconductor giant archetype, Intel Corporation, a US-based entity, exemplifies the leveraging of extensive fabrication capabilities to advance silicon photonics. Broadcom Inc., also a US-based company, occupies a leading position among specialized optics leaders, particularly in the high-volume pluggable optics segment crucial for hyperscale data centers. Ayar Labs, another US-based firm, represents the innovative optical I/O solutions archetype, focusing on chip-to-chip communication requirements. These players collectively anchor distinct segments of the hybrid photonic integrated circuit market, influencing technology development and adoption.
| Leading Market Players |
|---|
| Marvell Technology |
| Cisco Systems |
| Intel Corporation |
| GlobalFoundries |
| MACOM |
| Broadcom Inc. |
| Coherent Corp. |
| Ayar Labs |
| Lumentum Holdings |
Cost & Logistics Intelligence
Indium Phosphide wafer substitution with Silicon for waveguiding reshapes manufacturing geography and pricing economics. This shift balances high-performance material costs with scalable silicon fabrication.
Pricing Analysis
The EU's Restriction of Hazardous Substances (RoHS) directive dictates the pricing tier structure for compliant hybrid photonic circuits. Per-unit transactional pricing dominates for standard modules, while contract-based long-term offtake agreements characterize custom co-packaged optics solutions. Price differentiation stems from performance tiers, such as 800G versus 1.6T transceivers, and the level of customization required by hyperscale data centers. Pricing pressure intensifies for high-volume, standard components due to fierce competition among suppliers. Consumer electronics manufacturers exhibit the highest price sensitivity, whereas hyperscale data centers show lower sensitivity for bespoke, performance-critical components.
Supply Chain Analysis
Strategic stockpiling of critical Indium Phosphide wafers contrasts with just-in-time delivery for high-volume silicon-based components. Geographic supply concentration centers on China for optical module assembly, the United States for advanced silicon photonics design, and the Netherlands for specialized component manufacturing. The supply chain relies on high-quality Indium Phosphide wafers and specialized optical components. Single-source vulnerability for Indium Phosphide remains a structural risk, impacting production scalability. Distribution runs through direct channels for hyperscale data centers, while specialized distributors serve telecommunications and automotive sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid photonic integrated circuit market reflects a significant buyer-power shift, driven by the consolidation of purchasing influence within hyperscale data centers.
For Market Incumbents:Fortify core intellectual property in Indium Phosphide and silicon photonics through targeted R&D. Leverage extensive fabrication capabilities in the United States to scale 1.6T module production. Deepen vertical integration into co-packaged optics to mitigate latency threats. Invest in certification for FCC and MIIT standards.
For New Entrants and Emerging Players:Lead with specialized optical I/O solutions for chip-to-chip communication, targeting AI accelerator hardware. The automotive Lidar segment in Germany and Japan offers a penetrable market. Focus co-design partnerships with hyperscale data center operators. Emphasize superior watts-per-gigabit performance for EU Green Deal alignment.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with vertically integrated mid-cap specialists focused on niche, performance-critical applications. Target firms with strong intellectual property in Indium Phosphide material science or advanced heterogeneous integration. The 5-10 year window shows sustained demand from AI and quantum computing. Watch for commercialization of cryogenic optical links for quantum computing interconnects.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Indium Phosphide Wafer Capacity | Addresses supply constraints, enhancing scalability for performance-critical 1.6T transceivers. |
| Develop Co-Packaged Optics Architectures | Reduces latency and power for hyperscale data centers by integrating optical engines closer to CPUs. |
| Standardize Lidar System Interfaces | Facilitates broader automotive adoption, driven by demand from German and Japanese manufacturers. |
| Invest in Silicon Nitride Fabrication | Supports high optical power applications like quantum computing interconnects and advanced sensing. |
| Partner with Chinese Cloud Providers | Ensures MIIT compliance and secures access to China's expanding AI infrastructure market. |
Research Approach
A standing panel of optical engineers, data center architects, automotive Lidar developers, and MIIT policy advisors provided ongoing calibration. This approach combined primary interviews with industry stakeholders and secondary validation from diverse sources. We triangulated insights from SEC 10-K filings, industry association reports, academic journals, and government technology roadmaps. Both bottom-up and top-down analyses were employed to ensure data integrity.
Outputs were consistently validated against external benchmarks and peer-reviewed studies for robustness over the projection horizon. The analytical framework modeled segmentation across product type, integration technology, application, end-user, and regional demand. Compound Annual Growth Rates derived from historical trends and projected advancements. Key forecast inputs included AI workload growth and Lidar system cost curves.
Forecasts assume regulatory continuity in US FCC and China MIIT regimes; material policy shifts would require re-modeling. These projections reflect documented assumptions, acknowledging risks like geopolitical trade tensions or rapid material science breakthroughs. Revision becomes warranted when these conditions cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transmitter Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
100G Optical Transceivers Market
Optical Components
North America Laser Diode Market
Optical Components
North America Optical Film Market
Optical Components
Optical Sensor Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Optical Encoder Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Global Optical Diode Market
Optical Components
Laser Photomask Market
Optical Components
Optical Transceiver Market
Optical Components
Europe Scintillator Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Display Optical Film Market