
 Flip-Chip VCSEL Market | 2026-2036
Flip-Chip VCSEL Market Size, Share, and Industry Trends Forecast 2026-2036
Flip-Chip VCSEL Market Foresight
Flip-chip bonding is tilting VCSEL packaging away from wire-bonded architectures toward lower parasitic inductance and improved thermal dissipation. Lumentum Holdings Inc. leverages its vertical integration from epitaxy to module assembly to control cost structures. Coherent Corp. sustains R&D intensity in multi-junction VCSEL arrays for high-power applications. ams OSRAM anchors European supply security through its Austrian fabrication complex.
A flip-chip VCSEL mounts the epitaxial structure face-down onto a submount or interposer via solder bumps or copper pillars, enabling direct electrical contact and superior heat extraction compared to topside wire bonding. The device emits perpendicular to the substrate surface through a distributed Bragg reflector cavity typically operating at 850 nm or 940 nm wavelengths for optical data links and proximity sensing. Multi-mode VCSELs dominate data communications revenue streams due to established multimode fiber infrastructure in hyperscale data centers. Single-mode VCSELs capture expanding margin pools in LiDAR and coherent sensing architectures where spectral purity governs range precision. Beam steering technology segments attract automotive supplier investment as solid-state LiDAR displaces mechanical scanning modules.
FCC equipment authorization rules govern VCSEL integration into consumer electronics sold in the United States, while FDA laser product performance standards classify emission safety tiers for facial recognition and biometric applications. The EU AI Act and GDPR create compliance layers for 3D sensing deployments in public spaces and retail analytics, constraining hardware design choices. Stakeholders must monitor divergence between U.S. and European regulatory timelines for autonomous vehicle LiDAR certification, as asynchronous approval pathways fragment product roadmaps and capital allocation priorities.
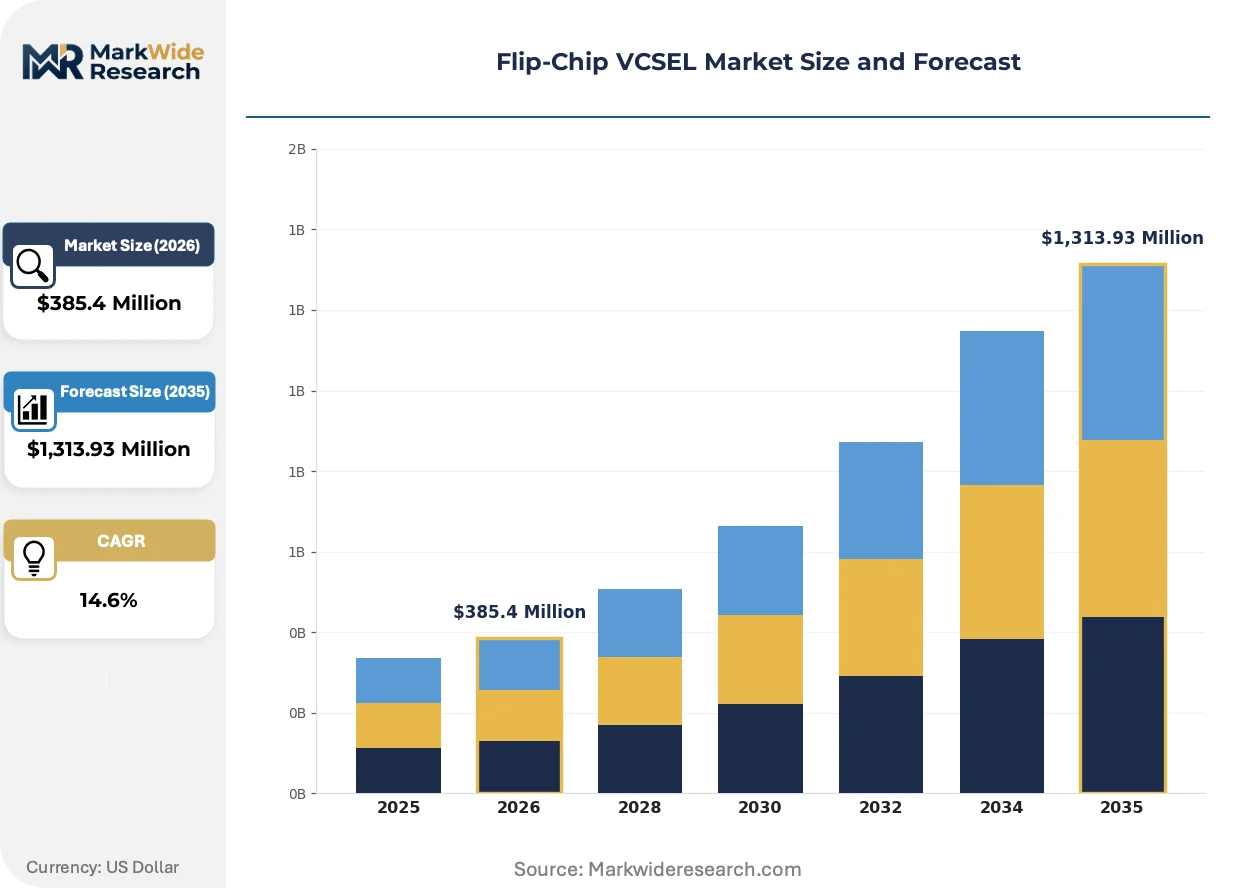
Market Dynamics
Flip-chip bonding architectures are displacing wire-bonded VCSEL packaging across data communications and sensing applications, driven by thermal performance requirements in hyperscale data centers and 3D sensing modules.
Growth Catalysts
- Data center fiber infrastructure:Multi-mode VCSEL deployment accelerates inside hyperscale facilities requiring 400G/800G optical interconnects. Cloud operators prioritize flip-chip packages for reduced power dissipation.
- RoHS material compliance:EU restrictions on hazardous substances in electronics force solder bump metallurgy innovations. Lead-free interconnect solutions unlock European consumer electronics access.
- 3D sensing module integration:Smartphone and automotive LiDAR programs demand compact emitter arrays. Face recognition and in-cabin monitoring systems specify flip-chip thermal footprints.
Market Restraints
- III-V epitaxy wafer costs:Gallium arsenide substrate pricing volatility constrains foundry margins. Raw material concentration in East Asian refining operations amplifies supply risk.
- Flip-chip assembly yield sensitivity:Sub-micron bump alignment tolerances limit high-volume manufacturing scale. Defect rates in solder reflow processes exceed wire-bonded alternatives.
- FDA laser classification friction:Facial recognition hardware faces extended safety certification timelines. Biometric application clearances delay consumer product launches.
Strategic Opportunities
- Underpenetrated industrial sensing:Machine vision and automated inspection systems in Germany and Japan specify single-mode VCSEL sources. Factory automation retrofits create replacement demand cycles.
- EU AI Act compliance hardware:Biometric deployment restrictions in public spaces favor privacy-preserving sensing architectures. Anonymous crowd analytics systems require specialized emitter configurations.
- Co-packaged optics convergence:Silicon photonics integration with VCSEL arrays enables optical I/O density at switch ASIC proximity. Hyperscale network equipment vendors specify co-packaged transceiver modules.
Industry Challenges
- Assembly technician scarcity:Precision flip-chip bonding requires specialized equipment operation skills. Workforce development lags behind installation base expansion in Southeast Asian contract manufacturing.
- Automotive LiDAR qualification cycles:AEC-Q102 stress testing and ISO 26262 functional safety certification extend development timelines. Solid-state beam steering modules face 18-24 month validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip-Chip VCSEL Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,313.93 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Single-Mode VCSEL, Multi-Mode VCSEL, Tunable VCSEL, High-Power VCSEL Technology: Direct Modulation, External Modulation, Wavelength Division Multiplexing, Beam Steering Application: 3D Sensing, Data Communications, LiDAR Systems, Augmented Reality, Industrial Automation End User Industry: Consumer Electronics, Telecommunications, Automotive Suppliers, Aerospace Systems |
| Companies Covered | Lumentum Holdings Inc., Coherent Corp., ams OSRAM, TRUMPF Photonic Components, Broadcom Inc., Vertilite, Vixar, TT Electronics, Leonardo Electronics US Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip-Chip VCSEL Market Shifts & Advancements
Multi-junction VCSEL architectures and heterogeneous integration techniques are compressing cost-per-watt metrics while expanding addressable power ranges. Thermal management innovations now determine competitive positioning.
Photonic integrated circuits with embedded VCSEL arrays are collapsing the boundary between emitter and interposer functions. Co-packaged optical I/O vendors at hyperscale data center switch suppliers specify these architectures for 51.2 Tbps switch generations. The technology is collapsing module count and assembly labor content per bandwidth unit.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases in semiconductor manufacturing are forcing process chemistry transitions. Etching and cleaning operations in III-V foundries face reformulated solvent requirements. Austrian and German fabrication complexes accelerate plasma-based dry process adoption to maintain production continuity.
Specification-driven procurement now dominates optical transceiver purchasing. Hyperscale operators publish detailed multi-source agreements with open reference designs. North American cloud infrastructure deployment schedules increasingly dictate foundry capacity allocation and qualification priorities.
Flip-Chip VCSEL Market Segmentation
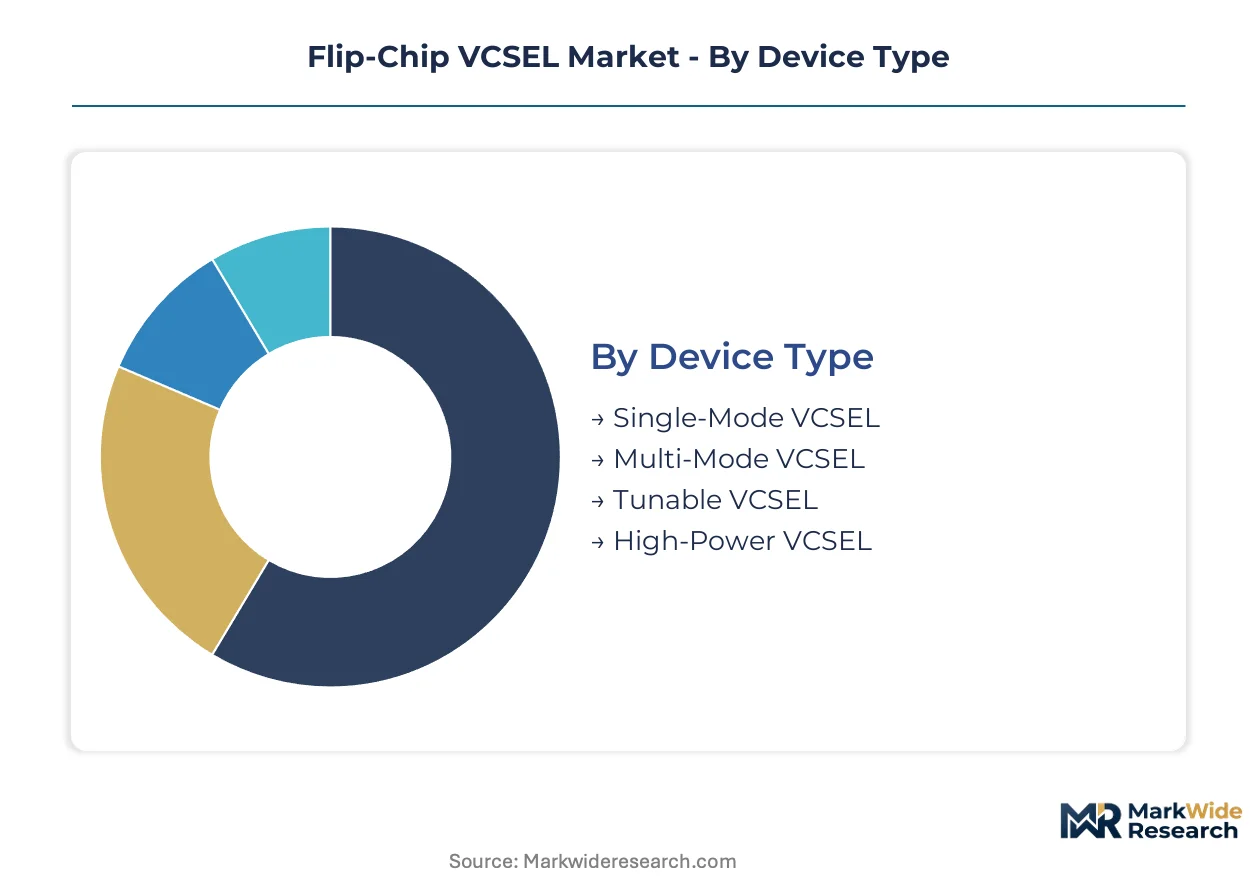
Flip-chip VCSEL architectures serve divergent performance requirements across optical interconnects and sensing modalities. Device geometry, modulation technique, and thermal footprint dictate package selection for each deployment context. The segmentation framework reveals how foundry capacity allocates across bandwidth-intensive data centers and precision-ranging automotive systems.
Device Type:
Use-case spectrum spans low-power proximity detection through high-irradiance illumination modules.
- Multi-Mode VCSEL:These emitters support multiple transverse optical modes simultaneously, enabling higher output power at reduced coherence length. Hyperscale data centers in the United States and China specify multi-mode arrays for 400G/800G short-reach optical interconnects where fiber dispersion tolerance outweighs spectral purity requirements. Cloud operator procurement volumes dominate foundry output allocation.
- Single-Mode VCSEL:Single longitudinal mode operation delivers sub-nanometer linewidth essential for coherent detection architectures. Automotive LiDAR programs in Germany and Japan require single-mode sources for frequency-modulated continuous-wave ranging systems where beat-note precision determines depth resolution. AEC-Q102 qualification timelines constrain supplier selection.
- Tunable VCSEL:Wavelength-agile cavities enable swept-source optical coherence tomography and fiber Bragg grating interrogation systems. Medical device OEMs specify MEMS-tunable variants for ophthalmic imaging platforms.
- High-Power VCSEL:Multi-junction epitaxial stacks concentrate optical output for industrial heating and laser pumping applications. Materials processing systems in Japan integrate kilowatt-class arrays for selective laser sintering.
The dominant share belongs to Multi-Mode VCSEL, while Single-Mode VCSEL is closing the gap fastest.
Technology:
Modulation architecture determines power consumption, spectral efficiency, and assembly complexity tradeoffs.
- Direct Modulation:Current-driven intensity modulation eliminates external optical components, minimizing package footprint and cost structure. Consumer electronics 3D sensing modules in China and South Korea specify directly modulated 940 nm emitters for structured light projection. MIIT electromagnetic compatibility standards govern rise-time specifications.
- Beam Steering:Optical phased arrays and liquid crystal metasurfaces enable solid-state angular scanning without mechanical rotation. Automotive Tier-1 suppliers in Germany and the United States integrate beam-steered VCSEL arrays for next-generation LiDAR platforms. NHTSA autonomous vehicle guidance documents shape performance validation protocols.
- External Modulation:Electro-absorption modulators preserve VCSEL linewidth while enabling higher extinction ratios. Telecommunications infrastructure vendors specify externally modulated sources for 10 km+ reach applications.
- Wavelength Division Multiplexing:Multiple VCSEL wavelengths multiplexed onto single fiber multiply aggregate bandwidth without additional physical lanes. Hyperscale switch vendors evaluate coarse WDM arrays for co-packaged optical I/O density.
Direct Modulation commands volume leadership, though Beam Steering is expanding most quickly as solid-state LiDAR displaces mechanical scanners.
Application:
Functional requirements differentiate bandwidth-centric communications from precision-ranging sensing modalities.
- Data Communications:Optical transceivers for data center spine-leaf architectures represent the foundational revenue base. Multi-mode fiber infrastructure in hyperscale facilities across the United States, Ireland, and Singapore specifies 850 nm flip-chip arrays for 100 meter reach links. Open Compute Project specifications standardize form factors and thermal interfaces.
- 3D Sensing:Structured light and time-of-flight modules enable facial authentication and spatial mapping. Smartphone OEMs in China and South Korea consume high-volume emitter arrays for front-facing biometric systems. GDPR Article 9 processing restrictions in Europe constrain deployment in public surveillance contexts.
- LiDAR Systems:Frequency-modulated and amplitude-modulated ranging architectures specify single-mode sources with precise wavelength stability. Automotive qualification programs in Germany and Japan extend development cycles for AEC-Q102 compliance.
- Industrial Automation:Machine vision and precision measurement systems specify VCSEL illumination for consistent contrast generation. Factory automation retrofits in Japan and Germany create replacement demand for aging laser diode sources.
- Augmented Reality:Near-eye display systems and depth-sensing hand tracking specify compact emitter arrays with minimal thermal footprint. Meta and Apple hardware roadmaps drive custom VCSEL development programs.
Data Communications retains volume dominance, yet 3D Sensing is gaining share fastest as automotive and industrial ranging applications multiply.
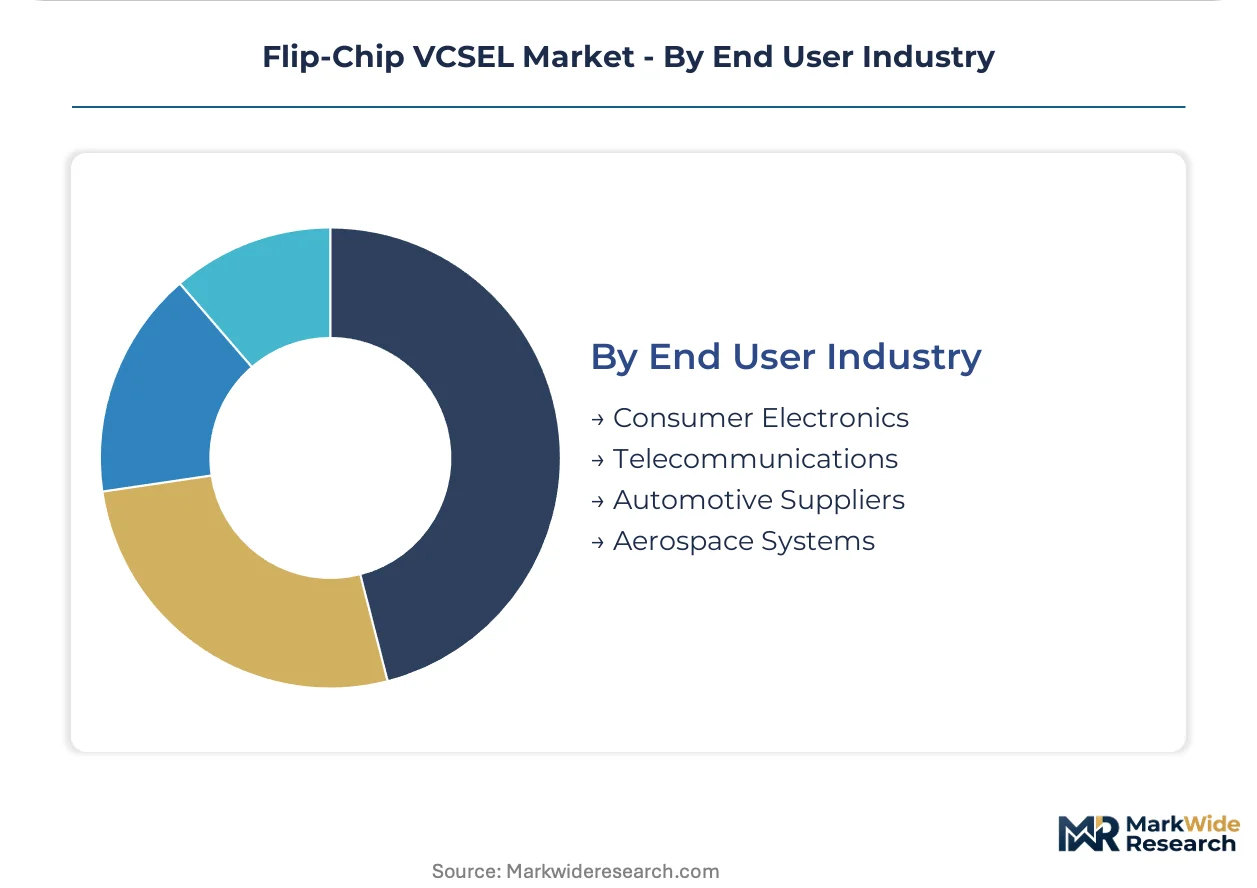
End User Industry:
Customer concentration and procurement power vary substantially across verticals.
- Consumer Electronics:Smartphone and wearable OEMs specify high-volume, cost-optimized emitter arrays with stringent size constraints. Supply agreements with Apple, Samsung, and Chinese handset vendors dominate capacity allocation cycles.
- Automotive Suppliers:Tier-1 LiDAR module manufacturers require AEC-Q102 qualified sources with 15-year operational lifetime guarantees. Bosch, Continental, and Denso qualification programs extend foundry engagement timelines.
- Telecommunications:Optical transceiver vendors source standard-compliant sources for enterprise and carrier network applications. IEEE 802.3 standards compliance governs wavelength and modulation specifications.
- Aerospace Systems:Satellite optical inter-satellite links and avionics sensing specify radiation-hardened and extended-temperature variants. NASA and ESA mission requirements drive custom qualification protocols.
Consumer Electronics holds the dominant share, while Automotive Suppliers are climbing the fastest as LiDAR penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports flip-chip VCSEL components to data center operators in the United States and automotive LiDAR integrators in Germany. East Asian manufacturing clusters dominate wafer fabrication and assembly operations.
United States
Hyperscale cloud operators in Virginia and Oregon deploy 400G/800G optical interconnects requiring flip-chip thermal footprints. FCC equipment authorization rules govern VCSEL integration into consumer biometric hardware. Silicon Valley and Austin fabrication facilities focus on co-packaged optical I/O development for next-generation switch architectures.
China
Smartphone OEMs in Shenzhen and Dongguan consume high-volume 940 nm emitter arrays for facial recognition systems. NMPA and MIIT jointly oversee optoelectronic component standards and electromagnetic compatibility certification. Yangtze River Delta foundries concentrate III-V epitaxy capacity serving domestic and export demand.
Germany
Automotive Tier-1 suppliers specify AEC-Q102 qualified single-mode sources for solid-state LiDAR platforms. EU F-Gas Regulation restricts fluorinated process gases in III-V foundry operations. Bavarian fabrication complexes accelerate plasma-based dry etching adoption to maintain production continuity.
Japan
Industrial automation OEMs in Osaka and Nagoya integrate VCSEL illumination for machine vision inspection systems. METI standards govern laser product safety classifications for factory deployment. Kyushu-based epitaxy houses supply multi-junction arrays for materials processing applications.
South Korea
Consumer electronics conglomerates in Suwon and Seoul source compact emitter arrays for wearable biometric sensors. MFDS and RRA administer laser safety and electromagnetic compatibility approvals. Pangyo technology corridor hosts module assembly operations linking foundry output to handset supply chains.
Flip-Chip VCSEL Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent customer segments. The vendor base separates into consolidated epitaxy-to-module integrators and specialized component suppliers serving niche qualification requirements. Three archetypes dominate: vertically integrated optical component houses, pure-play VCSEL foundries, and diversified semiconductor conglomerates with photonics divisions. Capacity expansion in East Asian assembly operations and strategic partnerships for automotive qualification programs constitute the primary competitive moves.
Among North American optical component houses, Lumentum Holdings Inc. and Broadcom Inc. occupy positions spanning epitaxy through transceiver integration. Coherent Corp. exemplifies the diversified laser technology archetype with photonics capabilities extending beyond VCSEL specialization. These three entities represent the channel-controlling tier where backward integration into wafer fabrication and captive supply of critical materials determine cost structures and customer lock-in.
| Leading Market Players |
|---|
| Lumentum Holdings Inc. |
| Coherent Corp. |
| ams OSRAM |
| TRUMPF Photonic Components |
| Broadcom Inc. |
| Vertilite |
| Vixar |
| TT Electronics |
| Leonardo Electronics US Inc. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta foundry clusters concentrate III-V epitaxy capacity, translating wafer-level bottlenecks directly into pricing leverage for multi-mode VCSEL arrays serving hyperscale data center procurement.
Pricing Analysis
400G/800G generation pricing gaps widen against legacy 100G/200G tiers, while next-generation co-packaged optical I/O modules command substantial premiums. Three-tier pricing structure across AEC-Q102 automotive-qualified, industrial-grade, and consumer-grade tiers separates certification investment levels. Cost compression in consumer-grade emitters is intensifying because smartphone OEMs consolidate supplier panels. Automotive suppliers exhibit least price sensitivity due to 15-year reliability guarantees and qualification lock-in.
Supply Chain Analysis
ASE Technology, Amkor Technology, and JCET hold dominant flip-chip assembly capacity for VCSEL packaging. Taiwan, China, and South Korea concentrate wafer fabrication and bumping operations. Gallium arsenide substrates and indium phosphide interposers constitute critical input dependencies. Single-source vulnerability in East Asian gallium refining amplifies disruption risk. Distribution runs through direct foundry relationships with hyperscale operators and Tier-1 automotive module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flip-chip VCSEL architectures represent high-growth disruption as solid-state LiDAR displaces mechanical scanning and EU AI Act compliance reshapes biometric hardware specifications.
For Market Incumbents: Pre-empt margin erosion in consumer-grade emitters by accelerating AEC-Q102 qualification pipelines for automotive single-mode arrays. Lock in gallium arsenide substrate offtake agreements to defend cost structures against raw material concentration in Chinese refining operations. Captive epitaxy capacity at Austrian and German fabrication complexes anchors European supply security against tariff exposure. For New Entrants and Emerging Players: Industrial automation retrofits in Japan and Germany present underpenetrated demand for machine vision illumination modules. Target privacy-preserving sensing architectures for EU AI Act-compliant crowd analytics systems. Partner with Pangyo corridor module assemblers to bypass direct foundry qualification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a photonics consolidation play because heterogeneous integration with silicon photonics will collapse discrete component margins and favor epitaxy-to-module integrators. Target pure-play VCSEL foundries with established AEC-Q102 qualification records. Watch NHTSA autonomous vehicle LiDAR guidance updates as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q102 Qualification Acceleration | Automotive Tier-1 supplier lock-in with Bosch and Continental extends engagement timelines. |
| Co-Packaged Optics Integration | Hyperscale switch vendors at 51.2 Tbps generations specify VCSEL-silicon photonics convergence. |
| Multi-Junction Epitaxy Scale-Up | Materials processing OEMs in Japan integrate kilowatt-class arrays for selective laser sintering. |
| EU F-Gas Regulation Compliance | Bavarian fabrication complexes accelerate plasma dry etching to maintain production continuity. |
| Beam Steering Module Development | Solid-state LiDAR platforms at German automotive suppliers displace mechanical scanning architectures. |
Research Methodology
The analysis maps multi-mode data communications, single-mode LiDAR, and 3D sensing biometric segments, each validated through VCSEL foundry operations directors, optical transceiver procurement managers, Tier-1 automotive module engineers, and hyperscale data center network architects. Primary interview findings triangulate against SEC 10-K filings, IEEE 802.3 standards documentation, NHTSA autonomous vehicle guidance, EU AI Act regulatory texts, and hyperscaler capital expenditure disclosures. Bottom-up unit economics and top-down market sizing converge across the analysis window.
Assumptions hold cloud infrastructure deployment schedules, AEC-Q102 qualification timelines, and EU F-Gas Regulation compliance trajectories as fixed parameters while varying automotive LiDAR penetration rates and co-packaged optics adoption curves. Segmentation models device type, technology modulation architecture, application modality, and end-user industry concentration. CAGRs derive from installed base replacement cycles and bandwidth demand elasticity across hyperscale facilities.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified semiconductor conglomerates or sudden NMPA export restriction shifts would shift outcomes. Quarterly review of hyperscale operator procurement announcements, AEC-Q102 qualification completion rates, and gallium arsenide substrate spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Display Optical Film Market
Optical Components
North America Photonic Sensors Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Global Optical Measurement Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Liquid Light Guides Market
Optical Components
Spectroradiometers Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Optical Transceiver Market
Optical Components
Liquid Lenses Market
Optical Components
Optical Position Sensors Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
VCSEL for Data Communication Market