
 Optical Waveguide Market | 2026-2036
Optical Waveguide Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Waveguide Market Outlook
ISO 9001 and Telcordia GR-1221 qualification cycles is bifurcating the supplier landscape between qualified incumbents and aspirants. Corning Incorporated leverages its vertically integrated fused silica supply chain to sustain premium positioning in glass waveguide substrates. Fujikura Ltd. dominates submarine-grade fiber deployments through its proprietary vapor-phase axial deposition technology. Molex LLC differentiates via precision connectorization and active optical cable assembly expertise.
An optical waveguide is a physical structure that confines and guides electromagnetic radiation in the optical spectrum through total internal reflection, typically fabricated from doped silica glass with core-cladding refractive index differentials of 0.3-1.0% or silicon-on-insulator platforms with sub-micron waveguide dimensions. These structures transmit data, images, or sensor signals with minimal loss across telecommunications backbones, medical endoscopes, and LiDAR systems. Glass waveguides command the largest revenue pool due to entrenched telecom infrastructure, while silicon waveguides represent the fastest expansion vector as foundries scale 300mm photonic integrated circuit wafers. Fiber optics technology anchors current volume, though integrated optics is displacing discrete components in co-packaged optics and optical compute interconnects.
FCC broadband deployment mandates and FDA laser safety classifications (21 CFR 1040.10) shape product specifications and market access for optical waveguide systems in the United States. ECHA REACH restrictions on heavy-metal dopants and EU RoHS substance limits constrain material choices for European-sourced components. China's GB/T fiber optic standards and NMPA medical device registrations govern import qualification protocols. Stakeholders must monitor foundry capacity allocation between electronic and photonic silicon, as wafer availability determines which integration architectures scale economically.
Market Dynamics
Silicon photonics integration is compressing component counts and reshaping competitive boundaries between discrete fiber-optic suppliers and semiconductor foundries. This structural shift redistributes value capture toward wafer-scale manufacturing ecosystems.
Growth Catalysts
- Data Center Interconnect Scaling:Hyperscale cloud operators in the United States and China are deploying co-packaged optics to reduce electrical interconnect power budgets. This pulls demand for silicon waveguide platforms.
- REACH Chemical Compliance:ECHA restrictions on heavy-metal dopants are accelerating substitution toward germanium-doped silica cores. European component suppliers are retooling deposition processes to maintain market access.
- LiDAR Sensor Miniaturization:Automotive OEMs are specifying integrated photonic chips for solid-state LiDAR. Silicon nitride waveguides enable tighter bend radii than conventional fiber in these sensor packages.
Market Restraints
- Foundry Capacity Allocation:TSMC and GlobalFoundries prioritize electronic CMOS over photonic SOI wafers. Photonic integrated circuit tape-outs face 6-9 month queue delays during semiconductor upcycles.
- Rare Earth Dopant Concentration:Erbium and ytterbium supply for fiber amplifiers concentrates in Chinese processing facilities. Western amplifier manufacturers face input cost volatility and dual-use export screening.
- Thermal Management Limitations:Silicon waveguides exhibit two-photon absorption at optical powers above 100 milliwatts. High-power telecom applications remain locked to glass fiber architectures.
Strategic Opportunities
- Quantum Photonics Integration:Cryogenic-compatible silicon nitride waveguides are enabling quantum key distribution modules. Foundries in Germany and the Netherlands are qualifying low-loss processes for this emerging application.
- Medical Endoscope Channel Shift:Disposable single-use endoscopes are bypassing traditional sterilization service providers. OEMs are sourcing polymer waveguide bundles directly from contract manufacturers in Malaysia and Vietnam.
- FCC Rural Broadband Mandates:The Broadband Equity Access and Deployment program requires fiber-to-the-home for 8.5 million unserved locations. This creates dedicated demand pools for ribbon cable and passive optical network splitters.
Industry Challenges
- Photonics-Process Engineer Scarcity:Compound annual graduation rates for integrated photonics specialists lag foundry expansion plans by 40 percent. Universities in California, Massachusetts, and Eindhoven are scaling apprenticeship programs with industry co-funding.
- Telcordia GR-1221 Certification Timelines:Environmental stress screening for submarine-grade fiber requires 24-month qualification cycles. Aspirant suppliers cannot bid transoceanic cable projects until completing this gating process.
- Legacy SONET Infrastructure Interoperability:Incumbent telecom operators in Japan and Germany maintain synchronous optical network equipment. New coherent pluggable transceivers must support obsolete line coding to secure upgrade contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Waveguide Market |
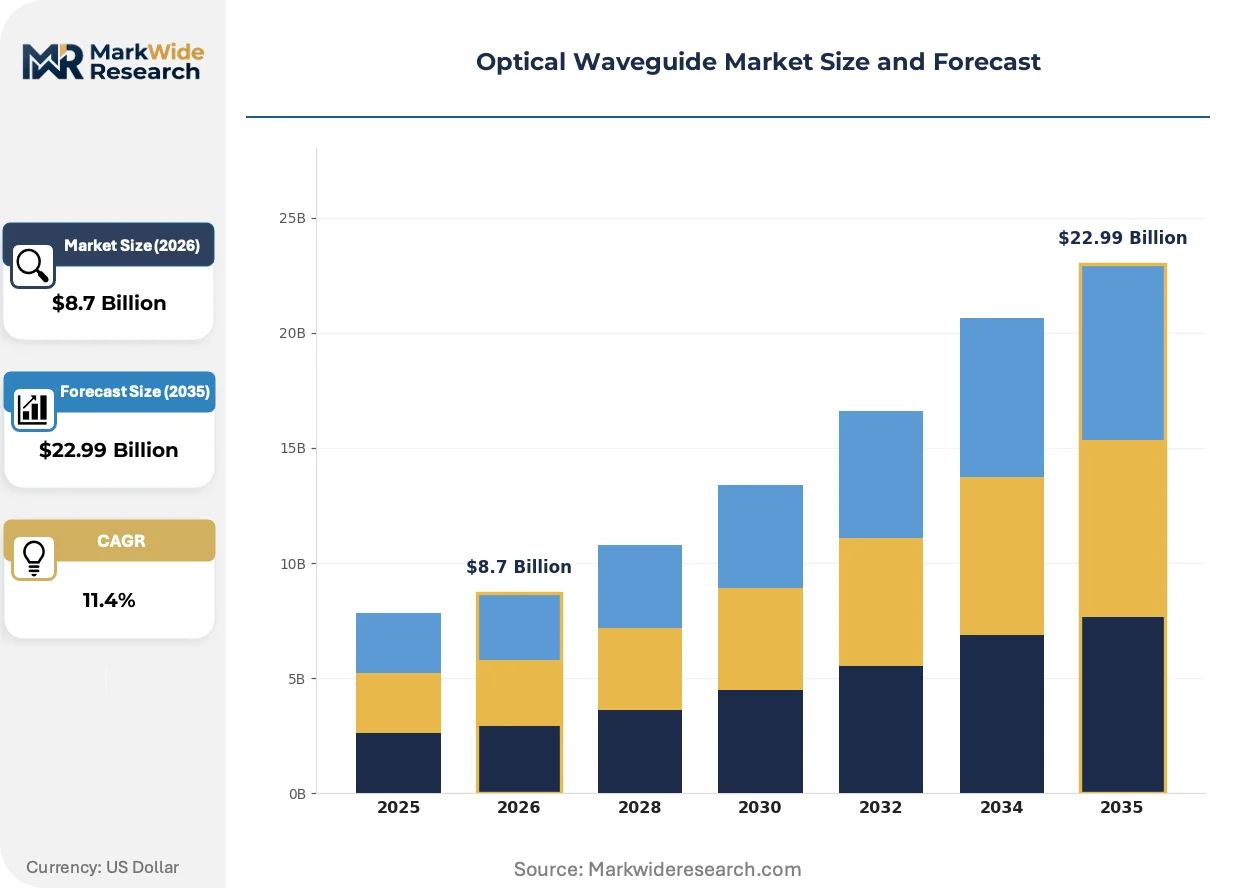
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Waveguides, Plastic Waveguides, Silicon Waveguides, Photonic Crystal Waveguides End User: Telecommunications, Consumer Electronics, Medical Devices, Automotive Technology: Integrated Optics, Fiber Optics, Micro-Optics, Nonlinear Optics Application: Sensors, Data Communication, Imaging Systems, Signal Processing |
| Companies Covered | Fujikura Ltd., Molex LLC, Corning Incorporated, OFS Fitel, JDS Uniphase Corporation, Sumitomo Electric Industries, Ltd., TE Connectivity, NTT Electronics, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Waveguide Market Strategic Shifts
Waveguide manufacturing is bifurcating between precision glass drawing for established telecom infrastructure and semiconductor lithography for emerging compute interconnects. This divergence is fragmenting supplier capabilities and certification requirements.
Co-packaged optics is decomposing traditional transceiver-discrete laser assemblies into chiplets bonded directly to switch ASICs. Cloud operators at 400G and 800G signaling rates are specifying these architectures to eliminate retimer power. The structural consequence is compressing margins for standalone transceiver vendors while expanding foundry serviceable addressable market.
ECHA REACH Annex XVII updates are restricting perfluorinated compounds in fiber coating chemistries. European cable manufacturers are qualifying UV-curable acrylate alternatives with comparable microbending performance. Submarine cable projects with EU content rules are most affected, with some suppliers dual-sourcing coatings to maintain fleet flexibility.
Hyperscale buyers are consolidating optical component procurement through direct foundry relationships rather than module vendor intermediaries. Microsoft, Amazon Web Services, and Google are issuing photonic process design kits to secure dedicated capacity. This behavior is most visible in the United States, where cloud capital expenditure concentration enables volume commitments that override traditional distribution channels.
Optical Waveguide Market Segmentation
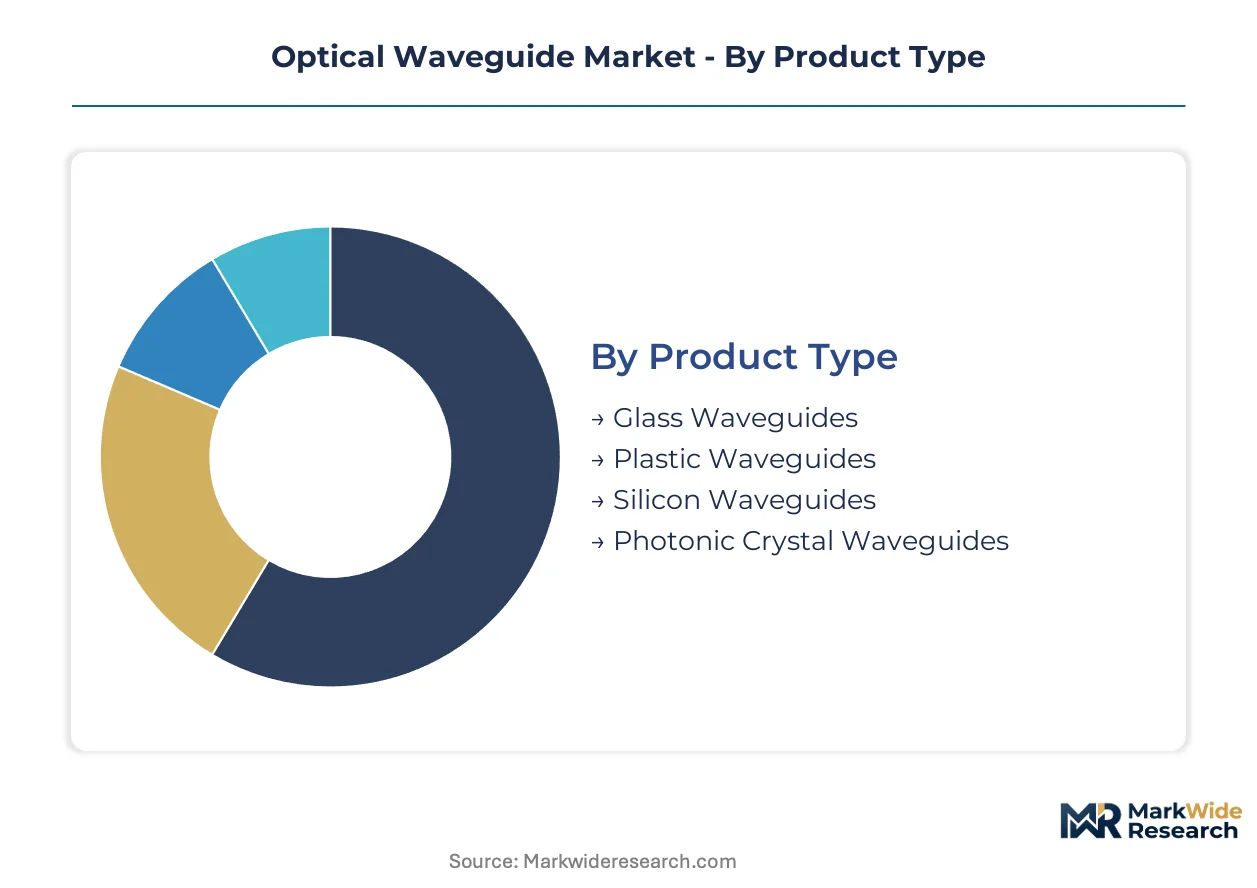
Optical waveguide architectures diverge sharply between legacy telecom infrastructure and emerging photonic integrated circuits. Segment boundaries are blurring as silicon foundries absorb functions previously served by discrete fiber assemblies.
Product Type:
Substitution pressure from silicon photonics is reshaping the material hierarchy, with semiconductor-compatible platforms displacing legacy glass in high-density interconnects.
- Glass Waveguides:Fabricated from doped silica with core-cladding index differentials of 0.3-1.0%, these structures dominate submarine cable and long-haul fiber deployments. Corning and Fujikura control fused silica supply chains that feed telecom infrastructure buildouts in the United States and China.
- Silicon Waveguides:Sub-micron dimensions on SOI wafers enable co-packaged optics for hyperscale data centers. TSMC and GlobalFoundries capacity allocation determines which integration architectures scale economically.
- Plastic Waveguides:Polymer substrates serve disposable medical endoscopes and short-reach consumer applications where cost trumps optical loss performance.
- Photonic Crystal Waveguides:Periodic dielectric structures enable tight light confinement for quantum photonics and sensing applications at research-scale volumes.
Glass Waveguides retain volume leadership; Silicon Waveguides hold the steepest expansion curve.
End User:
Procurement concentration among hyperscale cloud operators is compressing margins for traditional telecom suppliers while expanding foundry-addressable demand.
- Telecommunications:Submarine cable projects and fiber-to-the-home deployments sustain demand for qualified glass fiber. FCC rural broadband mandates in the United States create dedicated demand pools for ribbon cable and passive optical network infrastructure.
- Consumer Electronics:Active optical cables for virtual reality headsets and high-speed peripheral interconnects pull plastic and silicon waveguide volumes. Meta and Apple specification changes ripple through Asian contract manufacturers.
- Medical Devices:Single-use endoscopes are bypassing sterilization service providers. OEMs source polymer waveguide bundles directly from Malaysian and Vietnamese contract manufacturers.
- Automotive:Solid-state LiDAR specifications favor silicon nitride waveguides for tighter bend radii than conventional fiber. German and Chinese automotive OEMs drive qualification timelines.
Telecommunications retains volume leadership; Automotive holds the steepest expansion curve.
Technology:
Manufacturing process maturity determines which platforms can absorb capital investment for volume scaling.
- Fiber Optics:Vapor-phase axial deposition and modified chemical vapor deposition anchor current production volumes. Telcordia GR-1221 qualification cycles gate entry to submarine-grade deployments.
- Integrated Optics:Photonic integrated circuits on 300mm wafers displace discrete components in co-packaged optics. Foundry capacity constraints limit expansion during semiconductor upcycles.
- Micro-Optics:Precision lenslet arrays and beam-shaping elements serve sensor packaging and medical imaging at moderate volumes.
- Nonlinear Optics:Frequency conversion and parametric amplification remain confined to specialty research and defense applications with limited commercial scale.
Fiber Optics retains volume leadership; Integrated Optics holds the steepest expansion curve.
Application:
Performance requirements fragment the supplier base between precision glass drawing and semiconductor lithography capabilities.
- Data Communication:Hyperscale cloud operators at 400G and 800G signaling rates specify co-packaged optics to eliminate retimer power. Microsoft, Amazon Web Services, and Google issue photonic process design kits to secure dedicated foundry capacity.
- Sensors:Silicon nitride and silicon photonics platforms enable solid-state LiDAR and biochemical detection. Automotive OEMs in Germany and China drive miniaturization roadmaps.
- Imaging Systems:Coherent fiber bundles transmit images in medical endoscopes and industrial borescopes. FDA 21 CFR 1040.10 laser safety classifications shape product specifications in the United States.
- Signal Processing:Optical computing and microwave photonics remain pre-commercial despite laboratory demonstrations of matrix multiplication and filtering functions.
Data Communication retains volume leadership; Sensors holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC rural broadband mandates in the United States are creating dedicated demand pools for fiber-to-the-home infrastructure. Germany's ECHA REACH restrictions on heavy-metal dopants are accelerating substitution toward germanium-doped silica cores. China's GB/T fiber optic standards govern import qualification protocols for foreign component suppliers.
United States
Hyperscale cloud operators in Northern Virginia and Oregon are deploying co-packaged optics at 400G and 800G signaling rates. The FCC Broadband Equity Access and Deployment program requires fiber-to-the-home for 8.5 million unserved locations. Corning Incorporated leverages its vertically integrated fused silica supply chain from New York state to sustain premium positioning in glass waveguide substrates.
China
Domestic foundries are scaling 300mm photonic integrated circuit wafers for data center interconnect applications. NMPA medical device registrations govern import qualification protocols for foreign waveguide suppliers. The Yangtze River Delta cluster hosts concentration of fiber optic manufacturing serving both telecom infrastructure and export markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are specifying silicon nitride waveguides for solid-state LiDAR sensor miniaturization. ECHA REACH Annex XVII updates restrict perfluorinated compounds in fiber coating chemistries. Foundries in Dresden and Munich are qualifying low-loss processes for quantum photonics integration applications.
Japan
Incumbent telecom operators maintain synchronous optical network equipment requiring backward-compatible coherent pluggable transceivers. METI industrial standards shape domestic procurement specifications for submarine-grade fiber deployments. The Chubu region around Nagoya hosts precision glass drawing facilities serving medical endoscope and industrial sensor applications.
South Korea
Memory semiconductor manufacturers in Gyeonggi Province are integrating silicon photonics for high-bandwidth chip-to-chip interconnects. The country's national telecommunications regulator enforces technical standards for 5G fronthaul fiber deployments. Seoul-based research institutes are advancing nonlinear optics applications for optical signal processing.
Optical Waveguide Market Competitive Environment
Listed leaders compete with private specialists across qualification tiers and manufacturing scale. The supplier landscape bifurcates between Telcordia GR-1221 qualified incumbents and aspirants facing 24-month environmental stress screening cycles. Three archetypes dominate: vertically integrated glass substrate producers, precision connectorization specialists, and semiconductor foundry-dependent photonic integrated circuit suppliers. Competitive moves concentrate on foundry capacity allocation negotiations and REACH-compliant material substitution partnerships.
Among Japanese fabricators, Fujikura Ltd. and Sumitomo Electric Industries, Ltd. exemplify the submarine-grade fiber tier where proprietary vapor-phase axial deposition technology anchors market positioning. Corning Incorporated represents the vertically integrated archetype with captive fused silica supply chains. Molex LLC occupies a position within the connectorization and active optical cable assembly specialization tier. These three entities collectively illustrate how qualification credentials and manufacturing depth stratify competitive access across telecom infrastructure and hyperscale data center demand pools.
| Leading Market Players |
|---|
| Fujikura Ltd. |
| Molex LLC |
| Corning Incorporated |
| OFS Fitel |
| JDS Uniphase Corporation |
| Sumitomo Electric Industries, Ltd. |
| TE Connectivity |
| NTT Electronics |
| Prysmian Group |
| Others |
Value Chain & Pricing Dynamics
Germanium-doped silica substitution for legacy heavy-metal dopants under ECHA REACH Annex XVII simultaneously relocates deposition process expertise toward European suppliers and compresses input cost differentials between REACH-compliant and legacy formulations. This material transition redistributes pricing power toward vertically integrated fused silica producers while eroding margins for component assemblers dependent on spot-market rare earth sourcing.
Pricing Analysis
Certification level creates the primary spread between Telcordia GR-1221 qualified submarine-grade fiber and unqualified aspirant supply. Three-tier pricing structure across qualified premium, pre-qualified standard, and unqualified economy levels reflects 24-month environmental stress screening cycles. Cost compression in standard tiers intensifies because hyperscale cloud operators consolidate procurement through direct foundry relationships. Telecom infrastructure buyers exhibit lowest price sensitivity due to network reliability requirements, while consumer electronics OEMs drive aggressive unit cost negotiations.
Supply Chain Analysis
Photonic integrated circuit tape-outs face 6-9 month queue delays as inventory buffers deplete during semiconductor upcycles. Manufacturing gravity centers on the United States for hyperscale data center demand, China for fiber optic volume production, and Germany for automotive LiDAR qualification. Raw material flows draw from Japanese precision glass drawing equipment, Chinese rare earth processing facilities, and Dutch lithography systems. Single-source vulnerability concentrates in erbium and ytterbium supply for fiber amplifiers. Distribution runs through qualified cable assembly partners for telecom infrastructure and direct foundry relationships for cloud operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent glass waveguide manufacturers face substitution defense against silicon photonics integration in data center interconnects, requiring strategic repositioning toward applications where optical power handling and submarine reliability specifications sustain competitive differentiation.
For Market Incumbents: Consolidate captive fused silica supply chains through backward integration into New York state and North Carolina deposition facilities. Accelerate Telcordia GR-1221 qualification cycles for aspirant product lines to defend submarine cable market access against Japanese vapor-phase axial deposition specialists. Prioritize R&D investment in high-power tolerant glass architectures where silicon two-photon absorption limitations persist.
For New Entrants and Emerging Players: Post-sterilization service gaps in disposable medical endoscopes present direct sourcing opportunities for polymer waveguide bundle contract manufacturers. Target Malaysian and Vietnamese production clusters where OEMs bypass traditional sterilization intermediaries. Pursue FDA 21 CFR 1040.10 laser safety certification as the go-to-market angle for imaging system market entry.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors qualified incumbent glass substrate producers with submarine cable order backlogs over unqualified aspirants. Long-term viability over the next decade hinges on exposure to FCC rural broadband deployment timelines and automotive LiDAR miniaturization roadmaps. Watch foundry capacity allocation announcements between electronic CMOS and photonic SOI wafers as the primary inflection indicator for silicon photonics substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Substitution | ECHA Annex XVII compliance secures European market access for submarine cable suppliers. |
| Photonic Process Design Kit Development | Microsoft and Amazon Web Services direct engagement overrides traditional distribution channels. |
| Submarine-Grade Fiber Qualification | Telcordia GR-1221 certification gates bidding on transoceanic cable projects. |
| Silicon Nitride Process Qualification | Automotive OEM specifications in Bavaria enable solid-state LiDAR sensor miniaturization. |
| Single-Use Endoscope Channel Development | Malaysian contract manufacturers capture OEM sourcing bypassing sterilization services. |
Study Parameters
Cross-validation between primary interviews with fiber optic plant managers and secondary analysis of FCC broadband deployment filings anchors the qualitative findings. The research combined discussions with submarine cable procurement officers, photonic foundry process engineers, medical device OEM sourcing leads, and automotive Tier 1 sensor specialists. Secondary validation drew from ECHA REACH substance restriction updates, Telcordia GR qualification documentation, SEC hyperscaler capital expenditure disclosures, and NMPA medical device registration databases. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Sensitivity analysis tested forecast robustness across foundry capacity allocation scenarios and rare earth supply disruption assumptions. The analytical framework segmented volume and value across product type, end user, technology, and application dimensions throughout the projection horizon. CAGRs derived from historical trajectory analysis adjusted for technology substitution elasticity. Industry-specific inputs included coherent pluggable transceiver deployment rates and FCC Broadband Equity Access and Deployment program obligation timelines.
Forecasts assume regulatory continuity in ECHA REACH enforcement and FCC rural broadband mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Machine Vision Light Source Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Optical Lens Edger Market
Optical Components
Quartz Glass Substrate Market
Optical Components
Pancake Optical Module Market
Optical Components
Photomask Pellicle Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Portable Lenses Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
South Korea Optical Detector Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Bio-Optics Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market