
 US Lithium Niobate Modulator Market | 2026-2036
US Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
US Lithium Niobate Modulator Market Insights
Equipment leasing and photonics-as-a-service models is reconfiguring capital deployment for mid-tier buyers entering high-speed optical networks. Lumentum Operations LLC leverages vertical integration across III-V materials to sustain wafer-level cost discipline. iXblue Group anchors its position through specialized defense and quantum sensing channels. Fujitsu Optical Components Ltd competes via manufacturing scale in Asia-Pacific supply nodes serving US demand.
A lithium niobate modulator is an electro-optic device fabricated from LiNbO₃ crystal substrates that converts electrical signals into optical phase or amplitude modulation through the Pockels effect, typically operating at wavelengths near 1550 nm with bandwidths exceeding 40 GHz. These devices enable high-fidelity signal encoding in coherent optical communication systems, fiber-optic sensing arrays, and microwave photonic processors. Mach-Zehnder modulators occupy the dominant share of product-type revenue due to their maturity in long-haul telecommunications, while integrated photonics platforms represent the fastest-expanding technology dimension as silicon nitride hybridization reduces drive-voltage requirements. Defense end users command premium pricing for radiation-hardened and wide-temperature variants, whereas data center interconnect applications are scaling volume through standardized form factors.
FCC spectrum allocation rulings and NIST calibration standards jointly shape product certification requirements for devices deployed in federal communications infrastructure. The CHIPS and Science Act directs DOE and DOD funding toward domestic lithium niobate thin-film foundries, tightening supply-chain security protocols for strategic photonics components. Stakeholders must monitor how BIS export control expansions on advanced lithography equipment affect thin-film lithium niobate fabrication capacity inside US borders.
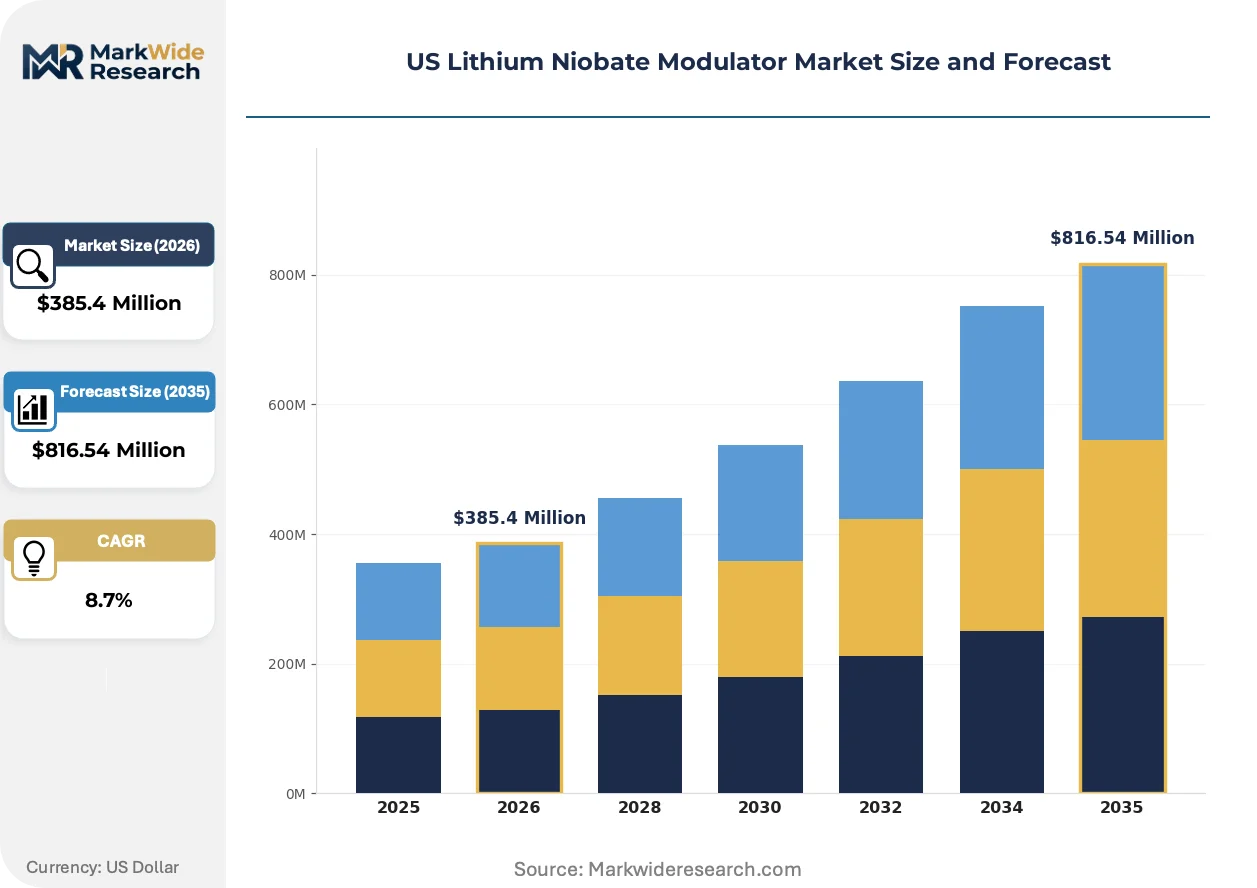
Market Dynamics
Thin-film lithium niobate fabrication is restructuring competitive economics by collapsing drive-voltage requirements and enabling wafer-scale integration previously unattainable with bulk crystal architectures. This substrate transition is redistributing manufacturing advantage toward domestic foundries qualifying under federal security protocols.
Growth Catalysts
- CHIPS and Science Act funding:DOE and DOD capital allocations are accelerating domestic thin-film lithium niobate foundry construction, creating captive supply for strategic photonics components.
- Data center interconnect buildout:Hyperscale cloud operators in Northern Virginia and Oregon are standardizing 800G coherent transceivers requiring low-Vπ modulators.
- Quantum sensing procurement:National laboratory networks are issuing multi-year purchase agreements for cryogenic-compatible lithium niobate phase modulators.
Market Restraints
- Bulk crystal supply concentration:High-purity lithium niobate boule production concentrates among Japanese and Chinese crystal growers, exposing US modulator fabricators to input price volatility.
- Thin-film etching equipment access:BIS export controls on advanced lithography tools constrain domestic deep-UV patterning capacity for sub-micron electrode geometries.
- Silicon photonics substitution:CMOS-compatible silicon modulators are capturing short-reach data center links below 10 km, compressing addressable volume for lithium niobate alternatives.
Strategic Opportunities
- Defense prime integration:Raytheon and Lockheed Martin are qualifying domestic lithium niobate modulators for satellite lasercom terminals, creating premium-priced demand insulated from commercial cycles.
- Photonics-as-a-service leasing:Mid-tier telecom operators are adopting equipment rental models for coherent DWDM upgrades, reducing upfront capital barriers.
- Silicon nitride hybridization:Heterogeneous integration with low-loss waveguide platforms is opening microwave photonic signal processing applications in electronic warfare systems.
Industry Challenges
- Thin-film process engineer scarcity:Domestic talent pipelines lack depth in lithium niobate-on-insulator wafer bonding and diamond saw dicing, forcing fabs to poach from compound semiconductor sectors.
- NIST calibration bottlenecks:Extended lead times for electro-optic coefficient traceability certification are delaying product qualification for federal procurement vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Lithium Niobate Modulator Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-Pull Modulator, Mach-Zehnder Modulator, Dual-Drive Modulator, Substrate Modulator End User: Telecommunications, Consumer Electronics, Defense, Research Institutions Application: Optical Communication, Signal Processing, Data Center Interconnect, Sensing Technology: Fiber-optic, Integrated Photonics, Electro-Optic, Wireless Transmission |
| Companies Covered | iXblue Group, Lumentum Operations LLC, Fujitsu Optical Components Ltd, HyperLight Corporation, THORLABS, Gooch & Housego plc, EOSPACE, Inc., Fabrinet Inc., Liobate Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Lithium Niobate Modulator Market Trends and Innovations
Wafer-scale integration and heterogeneous material platforms are collapsing the traditional separation between discrete modulator components and full photonic integrated circuits. This convergence is compressing development cycles and redistributing value capture across the supply chain.
Bulk lithium niobate modulators with machined crystal substrates and wire-bonded electrodes are rendering obsolete for coherent transceiver applications above 400G. Cloud data center operators are transitioning procurement specifications to thin-film platforms during 800G deployment cycles. The structural consequence is margin compression for legacy crystal processing equipment and captive demand for ion-slice wafer bonding tools.
FCC Part 15 unintentional radiator rulings are tightening electromagnetic interference certification for photonic subassemblies deployed in federal communications infrastructure. Equipment vendors must demonstrate compliance with revised emission limits in the 1-18 GHz band. Defense and civilian satellite ground stations represent the most affected segment, with primes accelerating pre-compliance testing to avoid program delays.
Leasing structures are displacing outright purchase for metro and regional network operators upgrading to coherent 100G-400G wavelengths. Equipment financiers are bundling modulator-based transponders with maintenance and software-defined provisioning. This shift is most visible among competitive local exchange carriers in Texas and the Midwest seeking to conserve balance-sheet capacity for fiber route expansion.
US Lithium Niobate Modulator Market Segmentation
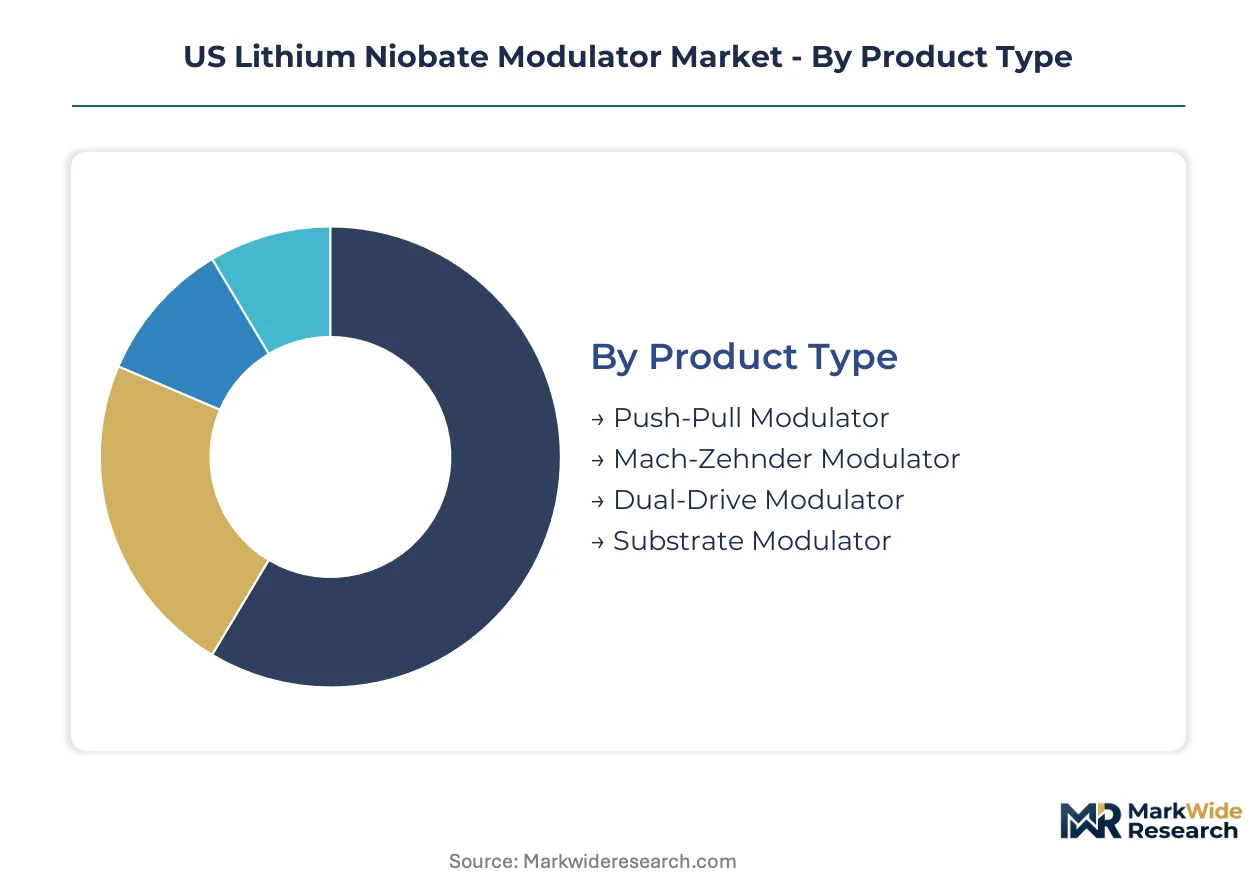
Segmentation in the US lithium niobate modulator market reveals how device specifications align with divergent performance requirements across telecommunications infrastructure, defense systems, and quantum research applications. Understanding these partitions exposes where thin-film fabrication investments concentrate versus where bulk crystal architectures retain commercial viability.
Product Type:
The use-case spectrum spans from high-bandwidth coherent transmission to compact sensing arrays, with electrode geometry and drive-voltage requirements determining architectural selection.
- Mach-Zehnder Modulator:Interferometric designs split and recombine optical paths to encode phase information through differential electrode excitation. Long-haul fiber routes between Northern Virginia and Oregon hyperscale facilities specify these devices for 800G coherent transceivers, though bulk substrate variants face displacement pressure from thin-film alternatives.
- Dual-Drive Modulator:Separate RF inputs on each interferometer arm enable chirp-free operation and enhanced linearity for advanced modulation formats. Defense procurement for satellite lasercom terminals at Raytheon and Lockheed Martin favors these configurations for radiation-hardened spaceborne links.
- Push-Pull Modulator:Symmetric electrode arrangements reduce drive-voltage requirements through constructive field interaction.
- Substrate Modulator:Direct crystal modulation without waveguide patterning serves specialized spectroscopic and metrology instruments.
Established volume favors Mach-Zehnder configurations; emerging adoption favors Dual-Drive architectures.
End User:
Customer type segmentation tracks how procurement authority distributes between federal funding streams, commercial capital cycles, and research grant mechanisms.
- Telecommunications:Tier-1 carriers and cloud operators in California's Silicon Valley and Boston's Route 128 corridor drive standardization of low-Vπ modulators for coherent DWDM upgrades. CHIPS Act foundry incentives are reshaping domestic supply security for this vertical.
- Defense:Prime contractors qualify modulators against MIL-STD-883 environmental screens and ITAR transfer protocols. Wide-temperature variants for electronic warfare systems command pricing premiums insulated from commercial silicon photonics substitution.
- Consumer Electronics:Minimal direct penetration; lithium niobate devices remain cost-prohibitive for mass-market optical interconnects.
- Research Institutions:National laboratory networks issue multi-year purchase agreements for cryogenic-compatible phase modulators in quantum sensing arrays.
Defense procurement maintains margin stability; research institutional demand is expanding most quickly.
Application:
Functional deployment contexts separate high-volume data transmission from specialized signal conditioning and environmental monitoring.
- Optical Communication:Coherent transceiver subassemblies modulate carrier phase and amplitude to maximize spectral efficiency across installed fiber plant. Metro and regional network operators in Texas and the Midwest are adopting equipment leasing models to conserve capital for route expansion.
- Data Center Interconnect:Hyperscale facilities standardize 800G form factors requiring sub-2V drive voltages achievable only through thin-film lithium niobate platforms.
- Signal Processing:Microwave photonic processors leverage electro-optic bandwidth for analog RF filtering in electronic warfare architectures.
- Sensing:Fiber-optic acoustic and seismic arrays deploy phase modulators for interferometric detection in perimeter security and geophysical survey applications.
Optical communication retains installed base dominance; data center interconnect offers the steepest expansion trajectory.
Technology:
Platform architecture segmentation captures the transition from discrete component assembly toward heterogeneous photonic integration.
- Integrated Photonics:Thin-film lithium niobate bonded to silicon dioxide enables wafer-scale patterning of sub-micron waveguides and electrodes. DOE and DOD capital allocations are accelerating domestic foundry construction for this platform.
- Electro-Optic:Direct Pockels effect modulation without resonant enhancement provides broadband operation across C- and L-bands.
- Fiber-optic:Bulk crystal devices with machined substrates and wire-bonded electrodes are rendering obsolete for coherent applications above 400G.
- Wireless Transmission:Free-space optical links for satellite and terrestrial lasercom deploy compact modulator packages with thermal management for atmospheric turbulence compensation.
Fiber-optic legacy platforms retain service revenue; integrated photonics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's Silicon Valley and Boston's Route 128 corridor, while procurement leverage fragments across Texas and the Midwest where leasing models dominate capital deployment.
California
Hyperscale cloud operators in Northern California drive standardization of 800G coherent transceivers requiring sub-2V drive voltages. FCC Part 15 rulings tighten electromagnetic interference certification for photonic subassemblies deployed in federal communications infrastructure. The Bay Area cluster anchors thin-film lithium niobate foundry construction accelerated by CHIPS Act DOE capital allocations.
Massachusetts
Quantum sensing procurement from national laboratory networks issues multi-year purchase agreements for cryogenic-compatible phase modulators. NIST calibration standards shape product certification requirements with extended lead times for electro-optic coefficient traceability. Greater Boston's Route 128 corridor hosts defense primes qualifying modulators for satellite lasercom terminals under ITAR protocols.
Texas
Metro and regional network operators adopt equipment leasing models for coherent 100G-400G wavelength upgrades to conserve balance-sheet capacity. Competitive local exchange carriers face capital constraints favoring photonics-as-a-service rental structures. Dallas-Fort Worth and Austin clusters concentrate mid-tier telecom procurement seeking standardized form factors.
Virginia
Hyperscale data center interconnect buildout in Northern Virginia standardizes low-Vπ modulators for 800G deployment cycles. DOD funding through the CHIPS and Science Act tightens supply-chain security protocols for strategic photonics components. The Ashburn-Loudoun County corridor represents the densest concentration of cloud infrastructure procurement driving thin-film platform transition.
Oregon
Hyperscale facilities in the Portland metro area specify thin-film lithium niobate platforms for sub-2V drive voltage requirements. BIS export controls on advanced lithography equipment constrain domestic deep-UV patterning capacity affecting regional fabrication expansion. The Hillsboro cluster intersects with semiconductor equipment supply chains serving photonics integration roadmaps.
US Lithium Niobate Modulator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete modulators to transceiver assemblers. Market structure concentrates around vertically integrated photonics houses and specialized substrate fabricators serving defense and quantum channels. Three archetypes dominate: defense-qualified suppliers with ITAR clearances, telecom-focused scale producers, and thin-film foundry operators capturing CHIPS Act incentives. Capacity expansion and heterogeneous integration partnerships constitute the dominant competitive moves as bulk crystal architectures face displacement pressure.
Among France-based specialists, iXblue Group occupies a position exemplifying the defense-qualified archetype through specialized sensing channels. Lumentum Operations LLC, a US-based entity, represents the vertically integrated tier leveraging III-V materials disciplines. Fujitsu Optical Components Ltd anchors the Asia-Pacific supply node serving US demand through manufacturing scale. These three entities collectively illustrate how geographic origin and organizational structure map onto divergent strategic positioning within the lithium niobate modulator supply chain.
| Leading Market Players |
|---|
| iXblue Group |
| Lumentum Operations LLC |
| Fujitsu Optical Components Ltd |
| HyperLight Corporation |
| THORLABS |
| Gooch & Housego plc |
| EOSPACE, Inc. |
| Fabrinet Inc. |
| Liobate Technologies |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at domestic thin-film lithium niobate foundries is compressing supplier pricing power while amplifying procurement premiums for ITAR-cleared defense variants. This utilization squeeze simultaneously accelerates CHIPS Act capacity investments and widens the spread between standard telecom-grade and radiation-hardened configurations.
Pricing Analysis
Configured-to-order pricing for cryogenic-compatible phase modulators commands substantial premiums over standard 800G coherent transceiver variants. Three-tier pricing structure across defense-qualified, telecom-standard, and research-grade levels reflects certification depth and volume scale. Price differentiation hinges on MIL-STD-883 environmental screening and NIST traceability documentation. Cost compression in bulk crystal architectures is intensifying because hyperscale operators are consolidating procurement around thin-film platforms. Research institutions exhibit lowest price sensitivity due to grant-funded capital cycles, while competitive local exchange carriers in Texas and the Midwest face acute budget constraints favoring photonics-as-a-service rental structures.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates input cost volatility for high-purity lithium niobate boule supply. Domestic modulator fabricators draw from Japanese and Chinese crystal growers for substrate feedstock, while thin-film processing equipment sources from Dutch and German lithography specialists. Single-source vulnerability concentrates in ion-slice wafer bonding tools constrained by BIS export control protocols. Distribution runs through defense prime direct contracts, telecom equipment OEM tiered supply agreements, and national laboratory multi-year purchase vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
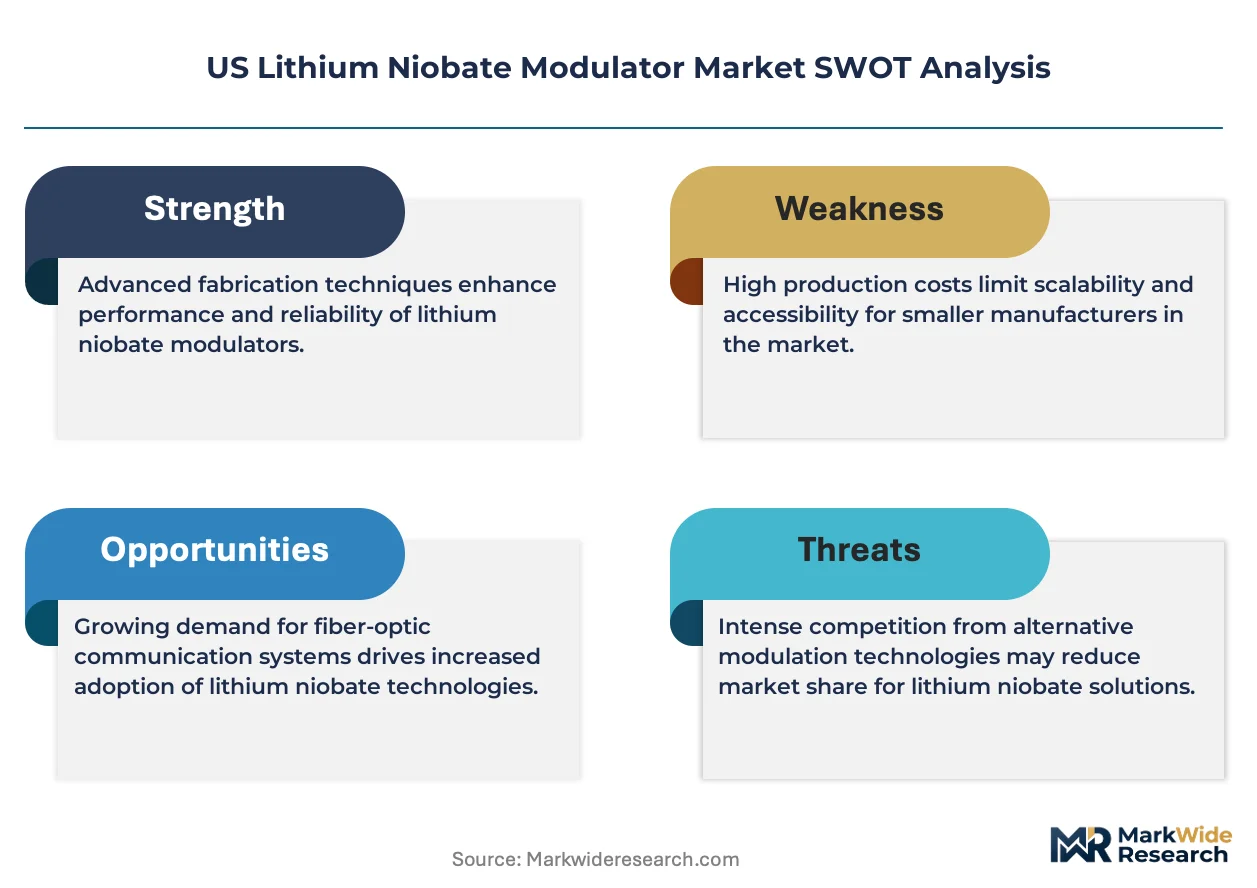
The US lithium niobate modulator market represents a high-growth disruption as CHIPS Act capital injections restructure domestic photonics manufacturing economics. Thin-film fabrication maturation is the technological inflection compressing development cycles and redistributing value capture.
For Market Incumbents: Build captive foundry capacity as the defensive moat against thin-film substitution pressure. Lumentum Operations LLC and iXblue Group should accelerate heterogeneous integration partnerships with silicon nitride platforms to lock in microwave photonic signal processing channels. Defense prime integration at Raytheon and Lockheed Martin offers margin insulation from silicon photonics encroachment on short-reach links. Certification investment in ITAR protocols and NIST calibration traceability creates switching costs for federal procurement vehicles.
For New Entrants and Emerging Players: Geographic underpenetration in Oregon's Hillsboro cluster presents accessible white-space for thin-film foundry qualification. Mid-tier competitive local exchange carriers in the Midwest lack dedicated photonics suppliers and respond favorably to equipment leasing bundled with software-defined provisioning. Quantum sensing procurement from national laboratory networks offers the most penetrable segment due to multi-year purchase agreement structures and tolerance for extended qualification timelines. A go-to-market angle anchored in cryogenic compatibility specifications bypasses direct confrontation with established telecom-scale producers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among photonics-as-a-service operators leasing coherent transponder capacity to capital-constrained regional carriers. Long-term viability over the coming decade rests on positioning upstream of 800G and eventual 1.6T coherent transceiver standardization. Acquisition targets should display thin-film lithium niobate-on-insulator process development depth paired with existing defense prime qualification relationships. The signal to monitor is FCC spectrum allocation rulings tightening electromagnetic interference certification requirements, which would accelerate consolidation around pre-compliant domestic fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Foundry Construction | CHIPS Act DOE capital allocations accelerate domestic lithium niobate-on-insulator wafer capacity. |
| Heterogeneous Integration Partnership | Silicon nitride hybridization reduces drive-voltage requirements for microwave photonic processors. |
| Defense Prime Qualification | ITAR-cleared supply agreements at Raytheon and Lockheed Martin insulate margins from commercial cycles. |
| Photonics-as-a-Service Launch | Equipment leasing bundles conserve balance-sheet capacity for competitive local exchange carriers. |
| NIST Calibration Investment | Electro-optic coefficient traceability certification reduces federal procurement qualification delays. |
Research Methodology
A spread of perspectives from thin-film process engineers, defense procurement officers at prime contractors, hyperscale data center network architects, and national laboratory research scientists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FCC spectrum allocation rulings, NIST calibration standard documentation, CHIPS Act funding disbursement records, and BIS export control determinations. Bottom-up and top-down triangulation anchored volume estimates across the analysis window.
Demand-supply-balance framing structured the analytical approach throughout the projection horizon. Segmentation dimensions modeled include product type architecture, end-user vertical, application context, and technology platform maturity. CAGRs derived from installed base replacement cycles, hyperscale capex disclosure patterns, and defense procurement pipeline visibility. Forecast inputs incorporated thin-film etching equipment lead times and lithium niobate boule price indices from Japanese and Chinese crystal growers.
Practitioners should monitor BIS export control expansions on advanced lithography equipment and NIST calibration bottleneck resolution for early signals of capacity constraint easing. Forecasts reflect assumptions about CHIPS Act disbursement velocity and defense procurement prioritization that could shift with federal budget realignments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Pancake Optical Module Market
Optical Components
Laser Photomask Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
US Optical Sensors Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Portable Lenses Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Co-Packaged Optics Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Optical Amplifier Market
Optical Components
LAMEA Lithium Niobate Modulator Market