
 3-7mm Galvo Scanner Market | 2026-2036
3-7mm Galvo Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
3-7mm Galvo Scanner Market Insights
Medical imaging is broadening the end-use vertical mix for 3-7mm galvo scanners as surgical laser systems and ophthalmic diagnostic equipment require higher beam steering precision. SCANLAB sustains technology leadership through its specialized positioning in high-speed digital scanning architectures. Cambridge Technology anchors European demand with deep manufacturing scale across precision motion control systems.
A 3-7mm galvo scanner is an electromechanical beam steering device employing galvanometer-driven mirrors to deflect laser beams across angular fields, with aperture diameters between 3mm and 7mm defining its spot size resolution and throughput characteristics. These devices serve primary industrial and commercial purposes in laser marking, cutting, welding, and medical therapeutic applications where rapid, accurate positioning of optical beams determines process quality. Laser scanners occupy the dominant share of product type demand due to entrenched use in materials processing workflows, while digital scanning technology captures the fastest expansion as real-time feedback loops displace analog servo architectures. Optical scanners retain stable margin pools in research and development settings where wavelength flexibility commands premium positioning.
FDA laser safety standards and the EU Machinery Directive shape product certification pathways, with compliance costs filtering smaller vendors from medical and industrial automation supply chains. REACH substance restrictions and RoHS hazardous material limits constrain mirror coating chemistries and driver electronics sourcing across European and North American markets. Stakeholders must monitor divergence between FDA 21 CFR 1040 laser classification protocols and emerging IEC 60825-1 revisions that could fragment international product validation requirements.
Market Dynamics
Digital servo architectures are compressing analog market share as automotive battery manufacturers demand real-time beam position feedback for traceability compliance. This technology transition concentrates procurement power among integrators capable of field-programmable control loop customization.
Growth Catalysts
- EU Machinery Directive compliance mandates:Industrial automation OEMs in Germany and Italy now require CE-marked galvo systems with embedded safety interlocks, filtering uncertified competitors from medical device supply chains.
- Lithium-ion cell serialization:Automotive battery plants in China and the United States are deploying mid-aperture scanners for permanent marking of electrode stacks and module housings.
- Silicon carbide driver electronics:Wide-bandgap semiconductors reduce thermal drift in high-duty-cycle welding applications, extending scanner operational lifespan in heavy industrial environments.
Market Restraints
- Mirror substrate supply concentration:Beryllium copper and silicon carbide mirror blanks rely on a limited supplier base concentrated in Japan and Germany, creating input cost volatility during aerospace demand surges.
- RoHS substance restrictions:European REACH compliance limits cadmium-based mirror coatings and leaded solder in driver boards, forcing reformulation investments that smaller vendors cannot absorb.
- Piezoelectric steering alternatives:MEMS-based beam deflection systems threaten sub-5mm aperture applications in ophthalmic diagnostics with superior angular resolution at lower unit cost.
Strategic Opportunities
- India precision manufacturing clusters:PLI scheme incentives for electronics and medical device production are attracting scanner integrators to Pune and Bengaluru industrial corridors.
- Additive manufacturing repair:Directed energy deposition systems for aerospace component refurbishment require galvo-steered powder bed fusion with programmable scan field correction.
- IEC 60825-1 revision alignment:Harmonized international laser safety classifications would reduce dual-certification burdens for vendors serving FDA and ECHA jurisdictions simultaneously.
Industry Challenges
- Embedded firmware certification timelines:FDA 21 CFR 1040 validation for surgical laser systems extends product launch cycles by 14-22 months, compressing revenue recognition windows.
- Multi-axis synchronization complexity:Integrating galvo scanners with linear motor stages and rotary tables demands specialized motion control expertise scarce in contract system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-7mm Galvo Scanner Market |
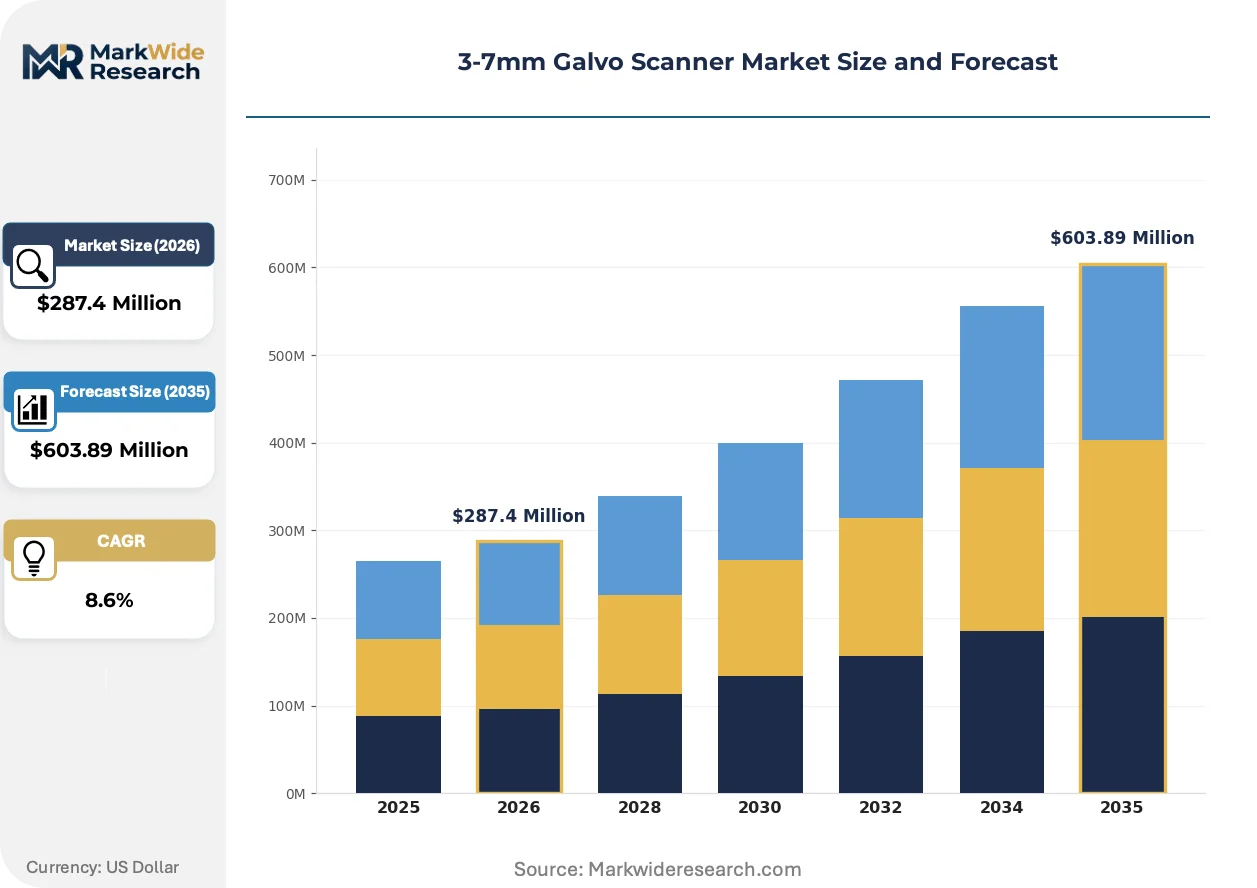
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $603.89 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Optical Scanners, 3D Scanners, Imaging Scanners Application: Industrial Automation, Medical Imaging, Manufacturing Processes, Research & Development Technology: Digital Scanning, Analog Scanning, Optical Technology, Laser Technology End User: Manufacturers, Healthcare Providers, Research Institutions, Educational Institutes |
| Companies Covered | Cambridge Technology, El.En. S.p.A., CTI Laser, GSI Group, Inc., Laser 2000 GmbH, Edmund Optics Inc., Newport Corporation, SCANLAB, Raylase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-7mm Galvo Scanner Market Trends and Innovations
Real-time feedback loops and predictive maintenance protocols are redefining scanner value propositions. Equipment buyers now prioritize field-upgradable control architectures over fixed-configuration hardware.
Digital position detector technology is automating beam drift compensation in high-throughput welding cells. Automotive tier-one suppliers in Stuttgart and Detroit are retrofitting analog systems with FPGA-based servo controllers to eliminate manual recalibration downtime. This automation is compressing maintenance intervals from quarterly to annual cycles while enabling predictive failure alerts through vibration signature analysis.
REACH substance restrictions are forcing mirror coating chemistry transitions across European supply chains. ECHA enforcement of cadmium and hexavalent chromium limits in 2024 has invalidated legacy electroplating processes for reflective surfaces. German and Swiss optical component vendors are responding with vacuum-deposited aluminum and protected silver alternatives that sacrifice some durability for compliance certainty.
Buyer consolidation among industrial laser OEMs is concentrating procurement leverage. System integrators in China and the United States now specify scanner performance guarantees tied to total cost of ownership metrics rather than unit price. This behavioral shift favors vendors offering remote diagnostics and spare part availability commitments, penalizing smaller manufacturers without global service infrastructure.
3-7mm Galvo Scanner Market Segmentation
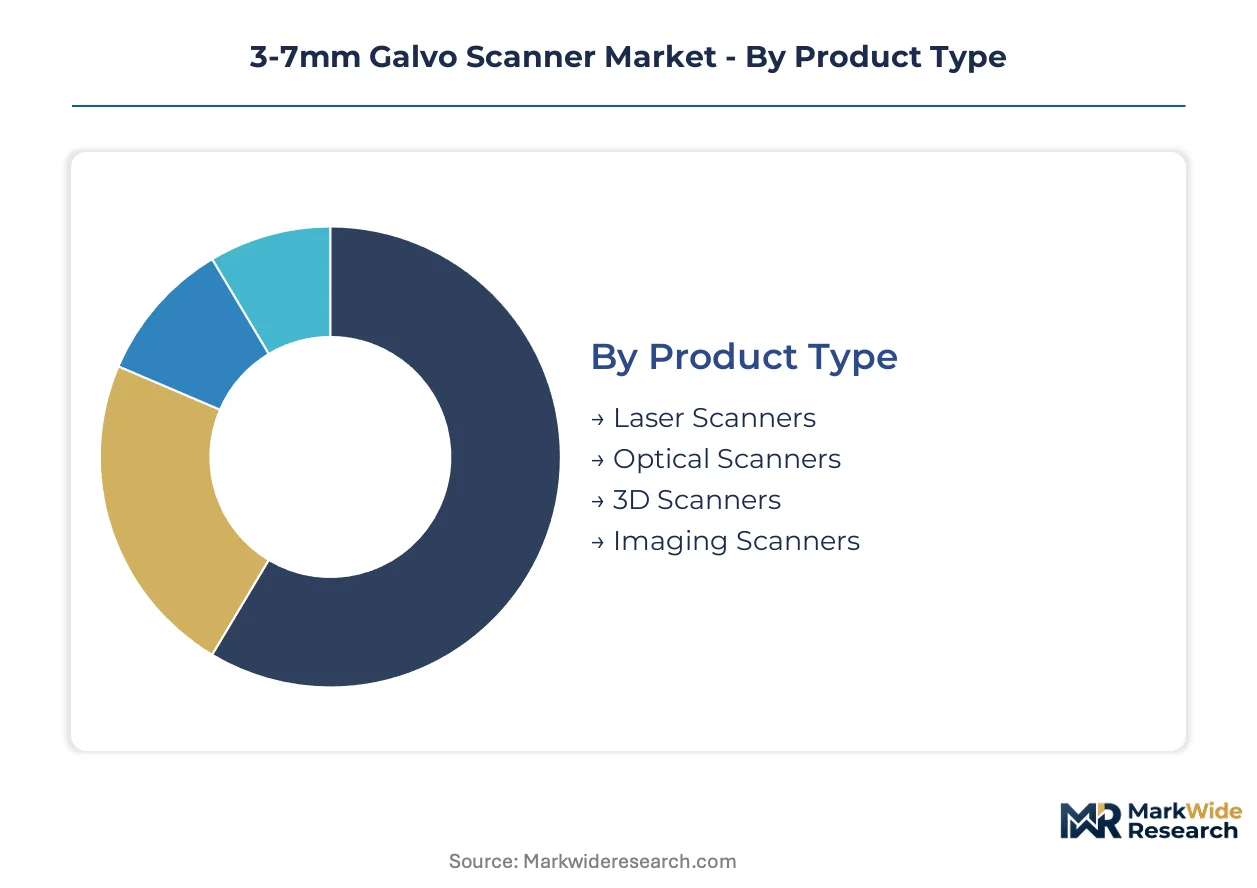
Beam steering specifications and control architectures determine procurement patterns across 3-7mm galvo scanner deployments. Segmentation reveals how digital servo displacement and medical imaging expansion are redistributing demand concentration across product categories.
Product Type:
Aperture diameter and wavelength compatibility define the specification axis for beam steering hardware selection.
- Laser Scanners:Electromechanical mirror systems deflect coherent light sources across angular fields for materials processing. Automotive battery plants in Germany and China specify these for electrode serialization where traceability compliance mandates permanent marking depth.
- Optical Scanners:Broadband mirror coatings accommodate multiple wavelengths for laboratory and research settings. Swiss and German optical component vendors dominate supply through vacuum-deposited aluminum alternatives that satisfy REACH substance restrictions.
- 3D Scanners:Multi-axis coordinated deflection enables volumetric beam steering for additive manufacturing repair applications.
- Imaging Scanners:Precision angular resolution supports ophthalmic diagnostic equipment requiring sub-micron positioning accuracy.
Mature deployment sits with Laser Scanners. Newer deployment is concentrated in 3D Scanners.
Application:
Process throughput requirements and regulatory certification intensity shape application-level demand distribution.
- Industrial Automation:CE-marked systems with embedded safety interlocks serve manufacturing OEMs in Germany and Italy. EU Machinery Directive compliance filters uncertified competitors from supply chains while concentrating procurement among integrators with field-programmable control loop expertise.
- Medical Imaging:Surgical laser systems and ophthalmic diagnostics demand FDA 21 CFR 1040 validation. Extended certification timelines of 14-22 months compress revenue recognition windows for vendors serving this vertical.
- Manufacturing Processes:Heavy-duty welding cells in Stuttgart and Detroit deploy silicon carbide driver electronics to reduce thermal drift.
- Research & Development:Wavelength flexibility commands premium positioning where coating chemistry experimentation requires rapid mirror substrate substitution.
Volume leadership belongs to Manufacturing Processes. Steepest expansion trajectory is occurring in Medical Imaging.
Technology:
Control loop architecture determines maintenance intervals and field upgradability for scanner deployments.
- Digital Scanning:FPGA-based servo controllers enable real-time beam position feedback and predictive failure alerts through vibration signature analysis. Automotive tier-one suppliers retrofit analog systems with these architectures to eliminate manual recalibration downtime and compress maintenance cycles from quarterly to annual.
- Analog Scanning:Fixed-configuration hardware retains installed base in legacy materials processing workflows where capital replacement cycles extend beyond technology refresh timelines.
- Optical Technology:Broadband position detection supports multi-wavelength research applications.
- Laser Technology:Coherent source compatibility dominates industrial marking and cutting specifications.
Procurement gravity centers on Digital Scanning. Analog Scanning retains residual share in cost-sensitive retrofit scenarios.
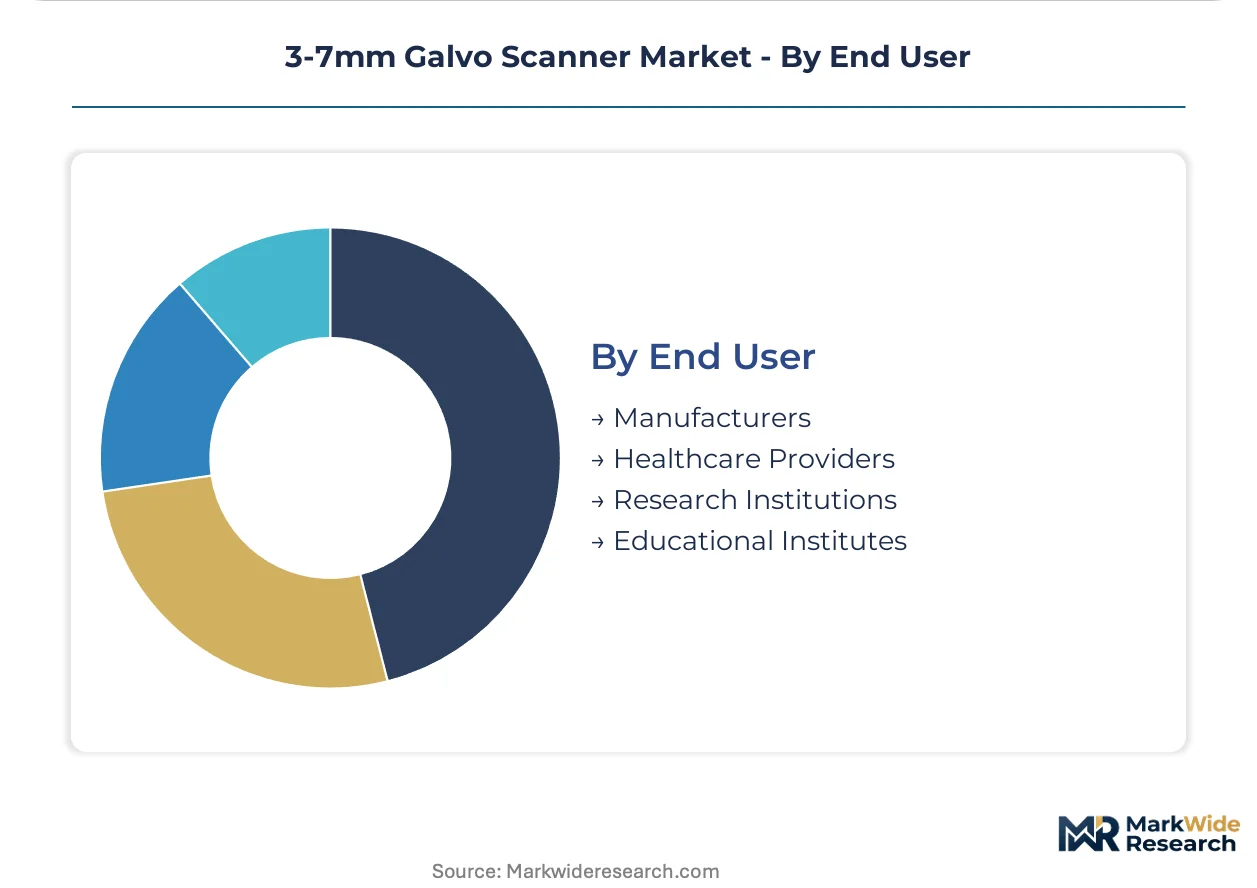
End User:
Total cost of ownership metrics and service infrastructure availability determine vendor selection across buyer categories.
- Manufacturers:System integrators in China and the United States specify performance guarantees tied to remote diagnostics and spare part availability commitments. This behavioral shift penalizes smaller vendors lacking global service infrastructure.
- Healthcare Providers:Surgical laser OEMs demand FDA-validated embedded firmware with embedded safety interlocks for patient-facing applications.
- Research Institutions:Wavelength flexibility and rapid coating substitution prioritize premium positioning over unit economics.
- Educational Institutes:Training and demonstration requirements favor lower-duty-cycle configurations with simplified calibration protocols.
Contract concentration sits with Manufacturers. Emerging demand is materializing among Healthcare Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dongguan concentrate precision manufacturing capacity for beam steering components. These zones offer 15% preferential corporate tax rates and streamlined customs clearance for imported mirror substrates. Cluster effects now extend to automotive battery laser marking systems serving CATL and BYD supply chains.
China
MIIT's Smart Manufacturing 2025 initiative funds digital servo upgrades in Guangdong and Jiangsu provinces. GB standards for laser equipment safety tighten certification requirements for domestic scanner vendors. Dongguan and Suzhou industrial parks host integrated production of galvo mirrors, driver electronics, and control software.
Germany
KBA vehicle homologation rules mandate permanent battery cell traceability markings, driving scanner procurement from Stuttgart automotive suppliers. EU Machinery Directive enforcement through notified bodies in Munich and Hamburg filters non-CE-marked competitors. Fraunhofer laser research institutes in Aachen and Dresden accelerate digital scanning technology transfer to Mittelstand manufacturers.
United States
IRA clean vehicle tax credits expand domestic battery manufacturing capacity in Michigan and Nevada. FDA 21 CFR 1040 laser classification protocols extend certification timelines for surgical laser OEMs in Minneapolis and Boston medical device clusters. Detroit-area tier-one suppliers retrofit analog galvo systems with FPGA-based architectures for real-time position feedback.
Japan
METI's Green Innovation Fund subsidizes silicon carbide driver electronics development for high-duty-cycle welding applications. JIS standards for industrial laser equipment harmonize with IEC 60825-1 revisions under review. Nagoya and Osaka precision optics manufacturers supply beryllium copper mirror blanks to global scanner assemblers.
India
PLI scheme incentives for electronics manufacturing attract scanner integrators to Pune and Bengaluru corridors. BIS certification requirements for industrial laser equipment phase in through 2025. Tamil Nadu and Telangana precision component clusters develop domestic mirror coating capabilities to reduce import dependence on German and Japanese suppliers.
3-7mm Galvo Scanner Market Competitive Landscape
Top-tier vendors anchor premium medical and aerospace certifications, while mid-tier specialists serve cost-sensitive industrial automation retrofits. The vendor base stratifies across three capability tiers: full-stack digital servo architects, analog system legacy maintainers, and regional component fabricators. Competitive moves concentrate on embedded firmware differentiation and multi-axis motion control integration partnerships. Technology licensing agreements between European servo controller developers and Asian mirror manufacturers reshape supply chain configurations.
Within the European precision motion control tier, SCANLAB GmbH and Cambridge Technology occupy positions exemplifying high-speed digital scanning specialization. Raylase AG represents German engineering-focused positioning in field-programmable servo architectures. These three entities anchor distinct competitive vectors: SCANLAB through medical imaging system integration, Cambridge Technology through industrial scale manufacturing, and Raylase through automotive battery traceability applications. Their collective presence shapes procurement standards for FDA-validated and CE-marked galvo deployments across German, Chinese, and North American manufacturing clusters.
| Leading Market Players |
|---|
| Cambridge Technology |
| El.En. S.p.A. |
| CTI Laser |
| GSI Group, Inc. |
| Laser 2000 GmbH |
| Edmund Optics Inc. |
| Newport Corporation |
| SCANLAB |
| Raylase |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide driver electronics adoption is compressing thermal management costs while concentrating procurement leverage among automotive battery manufacturers capable of specifying performance-guaranteed contracts. This technology transition simultaneously elevates field-programmable control architectures as a premium tier and forces analog legacy vendors into spot-market discounting.
Pricing Analysis
Short lead-time premiums of 15-25% apply to FDA-validated embedded firmware configurations where certification bottlenecks constrain immediate availability. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked medical systems from industrial automation retrofits and research-grade hardware. Price differentiation rests on embedded safety interlock complexity and remote diagnostics bundling. Cost compression in analog retrofit tiers is intensifying because Chinese system integrators now specify total cost of ownership guarantees rather than unit pricing. Contract manufacturers exhibit highest price sensitivity; surgical laser OEMs accept premium positioning for validation certainty.
Supply Chain Analysis
Freight cost volatility from Japan and Germany to Shenzhen assembly hubs adds 8-12% landed cost variance for beryllium copper mirror blanks. Manufacturing concentrates in China, Germany, and Japan, with Dongguan and Stuttgart hosting integrated galvo mirror and driver electronics production. Raw material dependencies include silicon carbide substrates, vacuum-deposited aluminum coatings, and FPGA controller chipsets. Single-source vulnerability in beryllium copper mirror blanks from Nagoya suppliers creates input cost spikes during aerospace demand cycles. Distribution runs through tier-one automotive suppliers in Stuttgart and Detroit, plus medical device OEMs in Minneapolis and Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
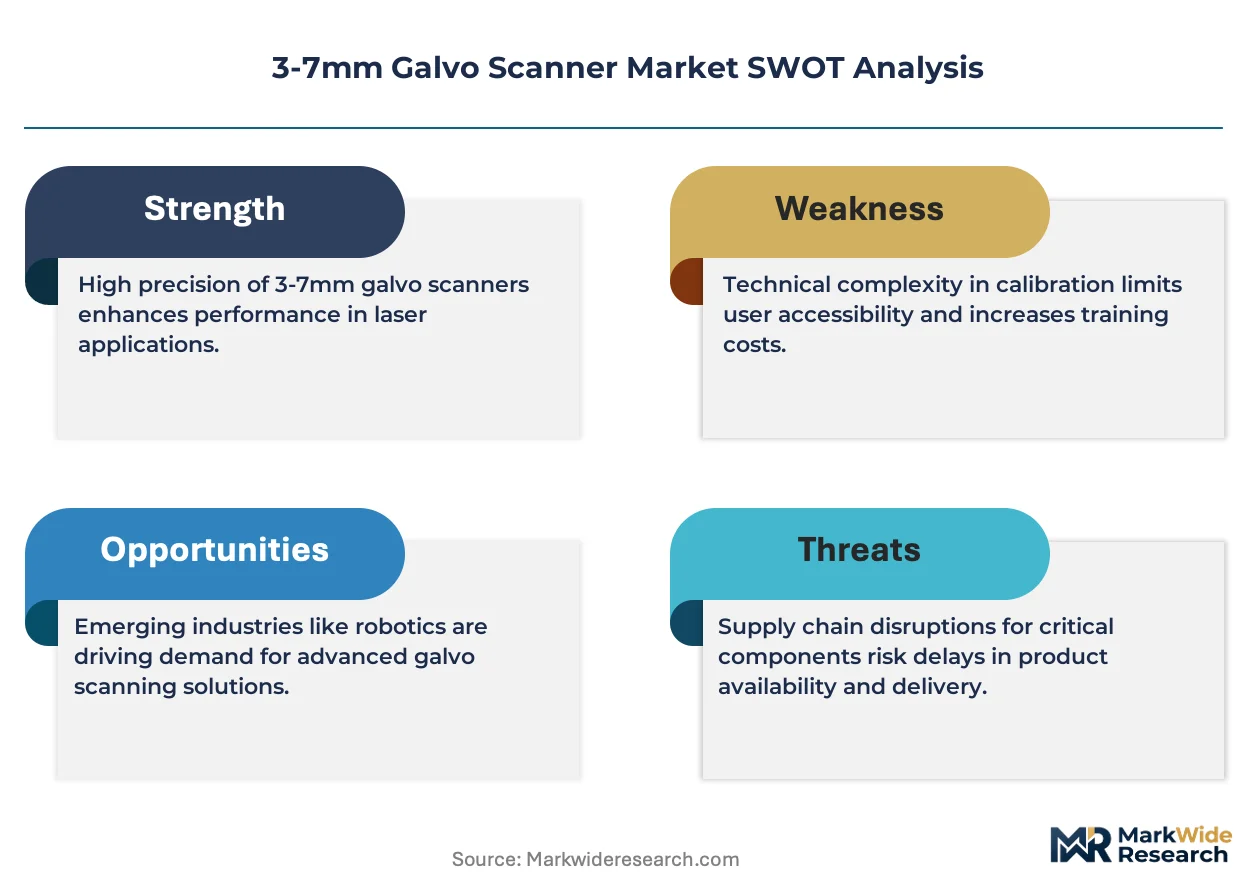
This market functions as a cost-of-compliance arena where FDA 21 CFR 1040 validation timelines erect 14-22 month barriers that filter capital-constrained entrants and sustain margin pools for certified incumbents.
For Market Incumbents: Deploy embedded firmware certification as a moat-building lever. Accelerate FPGA-based servo controller roadmaps to capture automotive battery traceability retrofit cycles before analog competitors recover R&D amortization. Consolidate mirror coating chemistry expertise in-house to neutralize REACH reformulation cost shocks from ECHA enforcement. Counter MEMS-based beam deflection substitutes in ophthalmic diagnostics through sub-micron positioning accuracy guarantees. For New Entrants and Emerging Players: Launch via additive manufacturing repair system integrators serving aerospace refurbishment contracts in India and Southeast Asia. Target Pune and Bengaluru precision manufacturing clusters where PLI scheme incentives reduce effective facility costs. White-space exists in 3D volumetric beam steering for directed energy deposition systems. Bypass FDA validation bottlenecks by focusing on industrial automation CE-marking pathways first. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial laser OEMs consolidating motion control capabilities. Long-term viability favors vendors with captive silicon carbide driver electronics development and embedded safety interlock IP. Acquisition target archetype: mid-tier specialists with FDA-validated firmware libraries and established service infrastructure in Germany or China. Monitor IEC 60825-1 revision harmonization progress as inflection signal for dual-certification burden reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Firmware Certification Investment | FDA 21 CFR 1040 validation compresses competitive field to capitalized players with 14-22 month launch cycles. |
| Silicon Carbide Driver Electronics Development | METI Green Innovation Fund subsidies in Japan accelerate high-duty-cycle welding application durability. |
| Multi-Axis Motion Control Partnership | Integration with linear motor stages and rotary tables addresses scarce contract integrator expertise. |
| REACH-Compliant Mirror Coating Transition | Vacuum-deposited aluminum alternatives from Swiss and German vendors satisfy ECHA cadmium restrictions. |
| Remote Diagnostics Platform Deployment | Automotive tier-one suppliers in Detroit and Stuttgart now require predictive failure alert capabilities. |
Research Methodology
Document review covered SEC filings from precision motion control vendors, ECHA REACH substance restriction enforcement records, and FDA 510(k) laser equipment clearances, complemented by interviews with galvo scanner procurement managers at automotive battery plants, biomedical engineers at surgical laser OEMs, and aftermarket service heads at industrial laser distributors. Secondary validation drew from MIIT Smart Manufacturing 2025 policy documents, Fraunhofer laser research institute publications, and KBA vehicle homologation rulemakings. Bottom-up unit economics from component cost structures were triangulated against top-down market sizing from OEM shipment disclosures.
Historical shipment trajectories were cross-referenced against panel input from plant engineers and OEM procurement teams to anchor growth assumptions across the analysis window. Segmentation modeling incorporated aperture diameter tiers, control architecture types, end-use verticals, and regional regulatory clusters. CAGRs were derived from slope-consistency checks against automotive battery manufacturing capacity expansion and medical imaging equipment installation rates. Industry-specific inputs included lithium-ion cell serialization mandate adoption curves and silicon carbide semiconductor foundry capacity ramps.
Regulatory enforcement intensity shifts, mirror substrate supply disruptions, and MEMS substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about certification timeline stability and automotive traceability mandate expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
CVD Sic Ring Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Optical Film Market
Optical Components
Diode Laser Module Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Global Adaptive Optics Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
South Korea Optical Detector Market
Optical Components
Spatial Light Modulator Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Machine Vision Light Source Market