
 Photovoltaic Inverters Market | 2026-2036
Photovoltaic Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic Inverters Market Intelligence
Modular inverter-plus-storage bundling is pivoting procurement patterns across utility and commercial segments. Huawei Technologies Co., Ltd. leverages its power-electronics heritage to dominate string-inverter shipments for large solar farms. Sungrow anchors its position through backward integration into energy-storage systems that pair with hybrid inverter platforms. SMA Solar Technology AG competes on European grid-code compliance, sustaining brand preference among independent power producers.
Photovoltaic inverters are power-electronic devices that convert direct-current output from solar modules into grid-compliant alternating current, with transformerless topologies achieving peak efficiencies above 98.6 percent. Their primary purpose is enabling safe, synchronized interconnection of solar generation to utility grids while maximizing energy harvest through maximum power point tracking. String inverters lead volume shipments across residential and commercial solar installations due to lower balance-of-system costs and flexible design. Central inverters retain dominance in utility-scale solar farms where megawatt-scale blocks justify dedicated conversion infrastructure. Microinverters represent the fastest-expanding product category as module-level power electronics gain traction in rooftop markets seeking shade resilience and granular monitoring.
The EU Green Deal and F-Gas Regulation shape European inverter demand by mandating higher efficiency tiers and restricting fluorinated gas use in manufacturing processes. China's MIIT enforces national GB standards that certify grid-tied inverter performance, while India's CEA technical standards govern voltage-ride-through requirements for utility-scale solar farms. The U.S. FAA coordinates with solar developers on aviation-obstruction lighting for large installations, indirectly affecting inverter siting and control-system design. Stakeholders must monitor evolving grid-code harmonization between regions and decide whether to develop multi-certification platforms or region-specialized product lines.
Market Dynamics
Transformerless string-inverter architectures are compressing procurement cycles across utility-scale solar farms as developers prioritize grid-stability features over legacy central-inverter footprints. India's CEA technical standards and China's MIIT certification regimes are accelerating replacement demand by mandating voltage-ride-through capabilities that obsolete earlier inverter generations.
Growth Catalysts
- EU Green Deal efficiency mandates:The F-Gas Regulation restricts fluorinated gas use in manufacturing while efficiency tiers force inverter replacement cycles across European solar portfolios.
- Utility-scale solar farm expansion:Developers in India, China, and the United States are scaling procurement of transformerless string inverters as grid-tied capacity expands.
- Dual carbon goals in China:MIIT enforcement of national GB standards certifies grid-tied inverter performance and accelerates domestic deployment timelines.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication concentrates in East Asian foundries, exposing inverter manufacturers to input cost volatility and allocation constraints.
- Grid-code fragmentation:Divergent voltage-ride-through requirements between India's CEA, Europe's network codes, and U.S. IEEE standards force multi-certification cost burdens on product lines.
- Central inverter substitution pressure:String inverters below 250 kW are displacing megawatt-scale central architectures in sub-utility projects, compressing addressable market for high-capacity conversion equipment.
Strategic Opportunities
- Hybrid inverter-plus-storage bundling:Modular packaging of power conversion with battery management systems opens utility and commercial procurement channels previously served by separate vendors.
- Rooftop microinverter penetration:Shade resilience and granular monitoring capabilities position module-level power electronics for residential expansion in distributed solar markets.
- U.S. IRA domestic content incentives:Investment tax credit adders for North American-manufactured inverters create localized production economics for string and hybrid platforms.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized expertise in wide-bandgap semiconductor integration and grid-forming control algorithms concentrates among legacy industrial automation firms.
- Multi-certification timeline compression:Parallel testing for CEA, MIIT, and IEEE compliance extends product launch cycles by 8-14 months for global platform strategies.
- Legacy SCADA integration complexity:New inverter communication protocols must interoperate with decade-old plant control systems at retrofitted solar farms.
Report Scope
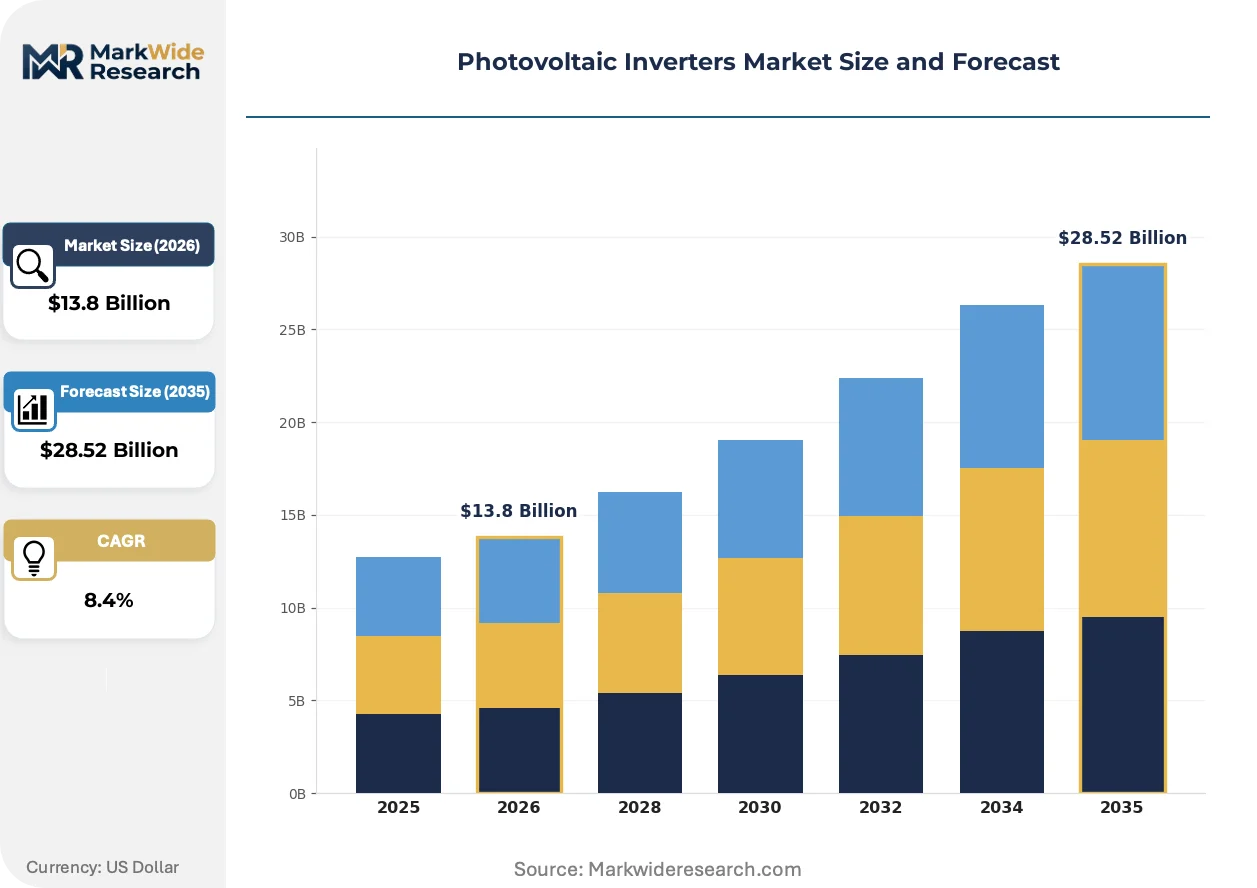
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic Inverters Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Central Inverters, Microinverters, Hybrid Inverters, Battery-Based Inverters Technology: Transformerless, Transformer-Based, High-Frequency Isolation, Capacitor-Based, Grid-Tied Application: Residential Solar Systems, Commercial Solar Installations, Utility-Scale Solar Farms, Agricultural Solar Power End User: Independent Power Producers, Solar EPC Contractors, Commercial Establishments, Small-Scale Power Generators |
| Companies Covered | Huawei Technologies Co., Ltd., Sungrow, SMA Solar Technology AG, Fronius, Ginlong Technologies, Enphase Energy, TBEA Co., Ltd., Growatt, GoodWe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic Inverters Market Strategic Shifts & Innovations
Solid-state power conversion and intelligent grid-forming capabilities are redefining inverter value propositions beyond basic DC-AC transformation. These advances compress balance-of-system costs while enabling solar assets to participate actively in network stability services.
Silicon carbide MOSFETs are absorbing switching losses that previously limited string-inverter efficiencies to sub-98% thresholds. Utility-scale developers in the United States and India are specifying SiC-based platforms for new solar farms exceeding 500 MW. This transition is absorbing market share from silicon IGBT architectures and forcing incumbent manufacturers to retool power-stage designs.
Europe's F-Gas Regulation is banning sulfur hexafluoride and perfluorocarbon use in inverter manufacturing processes and cooling systems. Industrial consequence includes accelerated R&D investment in air-cooled and dielectric fluid alternatives for high-power conversion modules. String inverter lines destined for EU markets are responding with sealed, fanless enclosures that meet IP65 ratings without fluorinated gas insulation.
Buyers are consolidating procurement around integrated inverter-storage packages rather than discrete component sourcing. Engineering-procurement-construction firms and independent power producers are displacing standalone inverter tenders with hybrid platform RFPs that specify DC-coupled battery integration. This pattern is most visible in U.S. utility-scale solar farms where IRA adders reward co-located storage and solar generation assets.
Photovoltaic Inverters Market Segmentation
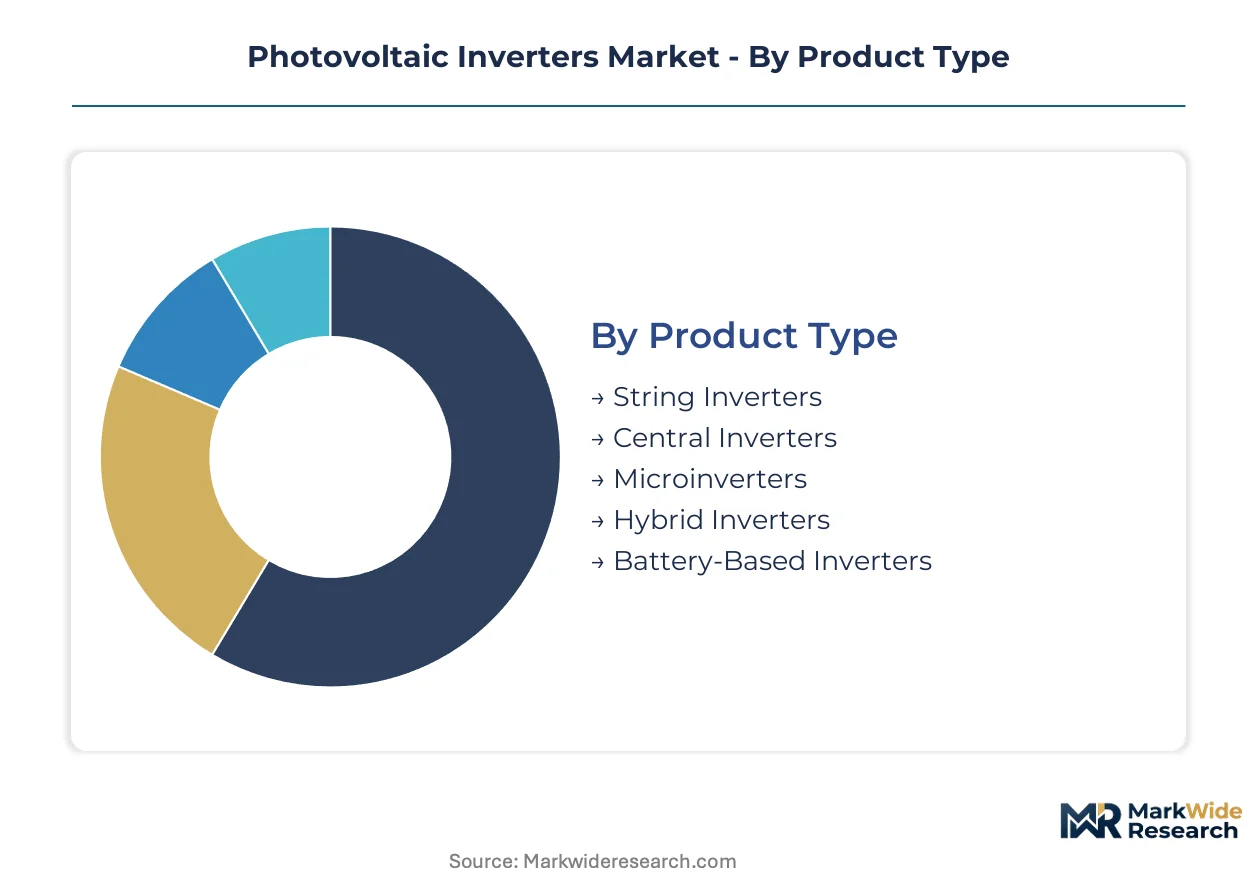
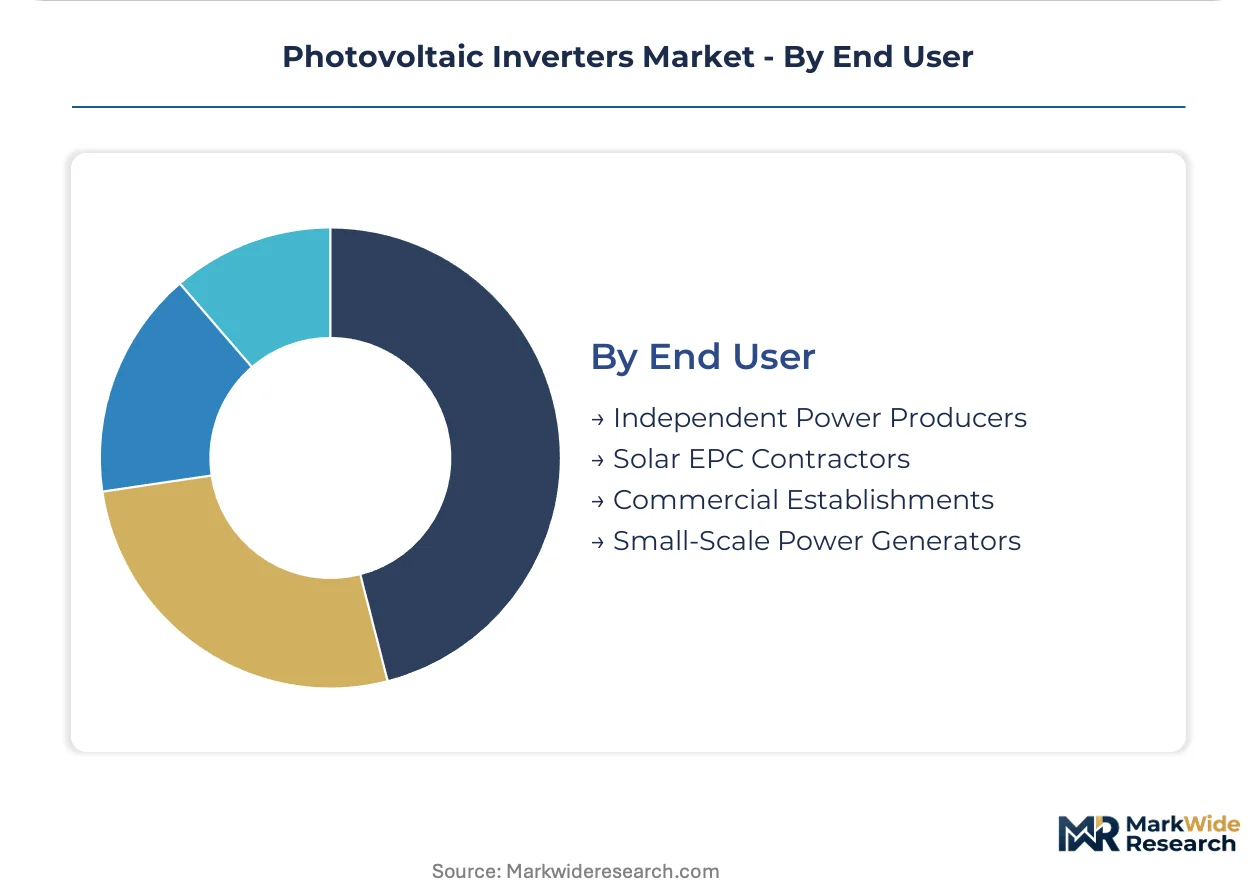
Photovoltaic inverter procurement pivots on four distinct segmentation axes that reshape vendor positioning and buyer decision frameworks. Product type and technology choices determine capital efficiency and grid-code compliance, while application scale and end-user category dictate service intensity and financing structures.
Product Type:
Buyers prioritize balance-of-system cost efficiency and grid-stability specifications when selecting inverter architectures for solar installations.
- String Inverters:Modular DC-AC conversion units rated 3-250 kW deploy transformerless topologies achieving peak efficiencies above 98.6%. Utility-scale solar farms in India and China specify transformerless string architectures for sub-megawatt blocks, driven by voltage-ride-through mandates from India's CEA and China's MIIT that obsolete central-inverter alternatives.
- Central Inverters:Megawatt-scale conversion platforms serve dedicated blocks exceeding 1 MW with integrated medium-voltage step-up transformers. Utility-scale developers in the United States retain central architectures for plants exceeding 500 MW, constrained by legacy SCADA integration requirements and established maintenance protocols at retrofitted facilities.
- Microinverters:Module-level power electronics enable granular maximum power point tracking and shade resilience for distributed rooftop installations.
- Hybrid Inverters:Integrated DC-coupled battery management systems combine solar conversion with storage dispatch capability.
- Battery-Based Inverters:Bidirectional power electronics optimized for off-grid and backup power applications with deep-cycle battery integration.
String inverters lead on scale; hybrid inverters lead on momentum.
Technology:
Semiconductor material selection and isolation architecture determine efficiency thresholds, thermal management requirements, and regulatory compliance pathways.
- Transformerless:Direct grid connection through silicon carbide MOSFET power stages eliminates magnetic core losses and achieves sub-98% efficiency thresholds. India's CEA technical standards and China's GB certification regimes accelerate transformerless deployment across utility-scale solar farms.
- Transformer-Based:Galvanic isolation through line-frequency transformers provides inherent ground-fault protection and legacy grid-code compatibility. Agricultural solar power installations in Germany and France specify transformer-based architectures, responding to local network operator requirements for fault-current limitation.
- High-Frequency Isolation:Compact ferrite-core transformers operating above 20 kHz reduce magnetic component mass by 80% versus line-frequency alternatives.
- Capacitor-Based:Film capacitor DC-link configurations replace electrolytic capacitors for extended operational life in high-temperature environments.
- Grid-Tied:Synchronization and anti-islanding protection circuits enable safe interconnection with utility distribution networks.
Transformerless platforms dominate new capacity additions; high-frequency isolation climbs the fastest on miniaturization demand.
Application:
Project scale determines inverter specification priorities, from residential shade resilience to utility-scale grid-forming capabilities.
- Utility-Scale Solar Farms:Centralized installations exceeding 5 MW require grid-forming inverters with voltage-source control and synthetic inertia provision. Developers across India, China, and the United States prioritize transformerless string and central architectures, responding to procurement patterns that bundle inverter-plus-storage packages.
- Residential Solar Systems:Rooftop installations below 20 kW demand module-level power electronics with granular monitoring and rapid shutdown compliance. Distributed solar markets in the United States specify microinverters and power optimizers, driven by NEC rapid shutdown mandates and shade resilience requirements.
- Commercial Solar Installations:Behind-the-meter systems ranging 20 kW-5 MW balance capital efficiency with monitoring granularity.
- Agricultural Solar Power:Agrivoltaic and irrigation-paired installations require corrosion-resistant enclosures and wide temperature operating ranges.
Utility-scale solar farms lead on scale; residential solar systems lead on momentum.
End User:
Procurement sophistication and financing structure differentiate buyer categories across the inverter value chain.
- Independent Power Producers:Long-term asset owners prioritize 25-year service life guarantees and grid-code compliance across multiple jurisdictions. IPPs in Europe specify SMA Solar and Huawei platforms, responding to EU Green Deal efficiency mandates and F-Gas Regulation manufacturing restrictions.
- Solar EPC Contractors:Engineering-procurement-construction firms optimize for balance-of-system cost reduction and installation labor efficiency. EPCs across India and the United States consolidate procurement around modular string inverter platforms, driven by compressed construction timelines and standardized commissioning protocols.
- Commercial Establishments:Retail, industrial, and institutional energy consumers seek behind-the-meter savings with peak-shaving capability.
- Small-Scale Power Generators:Distributed generation entrepreneurs and rural electrification projects prioritize capital accessibility and local service networks.
Independent power producers lead on scale; solar EPC contractors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photovoltaic inverter manufacturing traces its industrial lineage to German engineering centers and Chinese coastal manufacturing zones, with deployment patterns now spanning utility-scale solar corridors across three continents.
China
Domestic inverter demand surges from utility-scale solar farms in Qinghai and Inner Mongolia, where developers specify transformerless string architectures for multi-gigawatt projects. MIIT enforcement of national GB standards accelerates certification timelines for grid-tied equipment. The Yangtze River Delta manufacturing cluster around Shanghai and Suzhou hosts vertically integrated power electronics fabs producing silicon carbide MOSFET modules for export markets.
United States
Utility-scale developers in Texas and California drive procurement of hybrid inverter-plus-storage packages as IRA domestic content adders reshape supply chain economics. FAA coordination on aviation-obstruction lighting affects inverter siting at large solar installations in the Southwest. The Southeast solar corridor spanning Georgia and Florida attracts EPC contractors consolidating around modular string platforms for compressed construction timelines.
India
CEA technical standards mandating voltage-ride-through capabilities obsolete earlier inverter generations across Rajasthan and Gujarat solar parks. State-level renewable purchase obligations accelerate deployment in Maharashtra and Karnataka. Domestic manufacturing incentives under the PLI scheme attract power electronics assembly to Tamil Nadu's industrial zones near Chennai.
Germany
Agricultural solar installations in Bavaria and Baden-Württemberg specify transformer-based architectures responding to local network operator requirements for fault-current limitation. EU Green Deal efficiency tiers and F-Gas Regulation restrictions shape procurement among independent power producers. The North Rhine-Westphalia industrial belt retains engineering expertise in grid-forming control algorithms for next-generation platforms.
Photovoltaic Inverters Market Key Industry Players
The competitive structure tilts toward diversified power-electronics conglomerates with captive semiconductor supply relationships. Market concentration remains moderate, with tier-one vendors capturing utility-scale procurement through integrated storage bundling while regional specialists defend residential segments. Two strategic archetypes dominate: vertically integrated technology conglomerates leveraging power-electronics heritage, and pure-play solar specialists competing on grid-code compliance depth. Capacity expansion and hybrid platform diversification represent the dominant competitive moves as developers consolidate procurement around inverter-storage packages.
Among Chinese power-electronics conglomerates, Huawei Technologies Co., Ltd. and Sungrow occupy positions reflecting diversified industrial heritage spanning telecommunications and grid infrastructure. SMA Solar Technology AG exemplifies the European specialist archetype competing on regulatory compliance depth. These three anchors represent divergent strategic postures: conglomerate-backed platform breadth versus focused grid-code expertise.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Sungrow |
| SMA Solar Technology AG |
| Fronius |
| Ginlong Technologies |
| Enphase Energy |
| TBEA Co., Ltd. |
| Growatt |
| GoodWe |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in China's Yangtze River Delta manufacturing cluster anchor supply discipline through captive silicon carbide MOSFET fabrication, compressing procurement costs for domestic inverter vendors while forcing price competition on export markets. This ownership structure transmits pricing power downstream to utility-scale developers in India and the United States, who leverage IRA domestic content adders and PLI scheme incentives to extract volume discounts from module suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service bundling. Premium tiers command spreads for EU Green Deal compliance and F-Gas Regulation manufacturing standards, while economy tiers serve price-sensitive EPC contractors in India's state-level solar parks. Cost compression in standard-tier string inverters is intensifying because silicon IGBT inventory liquidation pressures incumbent vendors. Independent power producers exhibit lowest price sensitivity, prioritizing 25-year service guarantees over upfront capital expenditure.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Mumbai and Long Beach reshapes landed cost calculations for power semiconductor modules and ferrite-core magnetic components. Power electronics fabrication concentrates in China, South Korea, and Taiwan, drawing from polysilicon feedstock in Xinjiang and Inner Mongolia alongside rare-earth magnet supply from Jiangxi province. Single-source vulnerability in silicon carbide wafer supply exposes inverter manufacturers to allocation constraints during utility-scale procurement surges. Distribution runs through engineering-procurement-construction contractors who consolidate specifications for multi-gigawatt solar farm developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photovoltaic inverter procurement functions as a geographic-arbitrage play, with manufacturing cost differentials between China's MIIT-certified production zones and India's PLI-incentivized assembly corridors creating margin capture opportunities for vertically integrated conglomerates.
For Market Incumbents: Deepen backward integration into silicon carbide MOSFET sourcing to defend margins against emerging pure-play semiconductor entrants. Prioritize multi-certification platform investment spanning CEA, MIIT, and IEEE standards to compress product launch cycles and preempt displacement by modular string architectures in sub-utility projects. For New Entrants and Emerging Players: Solid-state transformer technology offers a technology-first wedge into agricultural solar installations in Germany and France, where local network operator requirements for fault-current limitation sustain transformer-based architecture demand. Target rooftop microinverter penetration in U.S. distributed solar markets, exploiting NEC rapid shutdown compliance gaps among legacy residential installers. For Investors and Strategic Acquirers: Valuations sit cheapest among European grid-code specialists with deep regulatory compliance expertise but limited storage integration capabilities. Long-term viability hinges on hybrid platform diversification over the coming decade. Watch for inflection when U.S. IRA domestic content adders trigger localized manufacturing commitments from Chinese conglomerates.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Transition | Absorbs switching losses that previously limited string-inverter efficiencies below 98% thresholds. |
| Hybrid Inverter-Storage Bundling | Opens utility procurement channels previously served by discrete power conversion and battery vendors. |
| Multi-Certification Platform Development | Compresses 8-14 month parallel testing timelines for CEA, MIIT, and IEEE compliance. |
| Air-Cooled Thermal Architecture | Eliminates fluorinated gas insulation to meet EU F-Gas Regulation manufacturing restrictions. |
| Grid-Forming Control Algorithm Investment | Enables synthetic inertia provision for utility-scale solar farms exceeding 500 MW capacity. |
Research Approach
Coverage spans China, the United States, India, and Germany, with primary inputs from each market's utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, and grid operators. Secondary validation draws from EIA generation data, IEA renewable deployment reports, FERC interconnection filings, and MIIT GB standard certification records. Bottom-up triangulation across inverter shipment volumes and top-down reconciliation against installed solar capacity estimates anchor market sizing.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the projection horizon. Segmentation dimensions modeled include product type, semiconductor technology, application scale, and end-user procurement sophistication. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns, with inputs from power semiconductor supply constraints and regulatory mandate implementation timelines.
The model holds under stable trade policy and grid-code harmonization assumptions; deviation in tariff exposure or multi-certification timeline compression would shift competitive positioning toward region-specialized product lines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
DC-DC Converter Market
Power Systems
South America Battery Management System Market
Power Systems
Shunt Capacitor Market
Power Systems
Europe Micro Inverter Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Global Flexible Batteries Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Traction Inverter Market
Power Systems
Japan Surge Protector Market
Power Systems
Bypass Thyristor Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Grid Tie Inverter Market
Power Systems
Electric Vehicle Power Inverter Market