
 Near-Infrared Fluorescence Imaging System Market | 2026-2036
Near-Infrared Fluorescence Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Near-Infrared Fluorescence Imaging System Market Outlook
Academic medical centers are unwinding purchasing concentration from general hospitals toward dedicated oncology and cardiovascular surgical units. Stryker leverages its installed base of surgical navigation platforms to bundle fluorescence imaging modules. Hamamatsu Photonics K.K. anchors supply of high-sensitivity InGaAs detectors that power system sensitivity thresholds. Carl Zeiss Meditec AG differentiates through integrated surgical microscope-fluorescence workflows for neurosurgical applications.
Near-infrared fluorescence imaging systems utilize excitation wavelengths between 700 and 900 nanometers to visualize targeted fluorescent probes in biological tissue, with indocyanine green serving as the most common clinically approved contrast agent for perfusion assessment and lymphatic mapping. The technology enables real-time intraoperative visualization of vascular structures, tumor margins, and nerve tissue that remains invisible under standard white-light conditions. Imaging systems and probes together capture the dominant share of product-level revenue, while surgical guidance applications outpace oncology in current installation velocity. Research institutions represent a faster-growing end-user channel than hospitals as preclinical probe development expands. Multispectral imaging technology commands premium positioning over standard fluorescence configurations due to its capacity for simultaneous multi-agent detection.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for commercial entry into the United States and European markets. Japan's PMDA enforces stringent quality management system audits that filter out smaller probe manufacturers lacking ISO 13485 certification. Stakeholders must monitor evolving reimbursement codes for fluorescence-guided procedures across national health technology assessment bodies to calibrate regional commercial investment sequencing.
Market Dynamics
Academic medical centers are consolidating purchasing authority into dedicated surgical subspecialty units, bypassing general hospital procurement committees and compressing vendor negotiation cycles for high-value imaging platforms.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates clinical validation timelines for fluorescence-guided oncology systems, reducing regulatory friction for novel probe developers.
- Indocyanine Green Perfusion Mapping:Cardiovascular surgical suites are standardizing intraoperative fluorescence assessment of graft patency and tissue viability, creating pull-through demand for integrated imaging modules.
- Japan PMDA Reimbursement Expansion:National health technology assessment bodies have approved procedure codes for image-guided lymphatic mapping, unlocking institutional procurement budgets.
Market Restraints
- InGaAs Detector Supply Concentration:Japanese and German sensor foundries control high-sensitivity detector manufacturing, exposing system assemblers to single-source supply risk.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates expanded post-market surveillance for fluorescence imaging systems, extending recertification timelines.
- White-Light Surgical Microscope Substitution:Established neurosurgical visualization platforms without fluorescence capability retain installed base loyalty through lower capital outlay.
Strategic Opportunities
- Preclinical Probe Development Channel:Research institutions are outpacing hospitals in fluorescence system procurement as academic labs expand targeted agent R&D pipelines.
- Multispectral Imaging Convergence:Simultaneous multi-agent detection capability is commanding premium positioning over standard single-wavelength configurations in high-volume cancer centers.
- German Outpatient Surgical Center Penetration:Ambulatory procedure volume growth is creating demand for compact, cart-based fluorescence systems outside traditional hospital settings.
Industry Challenges
- ISO 13485 Certification Timeline:Probe manufacturers face 12-18 month quality management system audit cycles to meet Japan PMDA and EU Notified Body requirements.
- Legacy Surgical Navigation Integration:Fluorescence module retrofit compatibility with existing robotic and navigation platforms demands proprietary software bridging and extended field service commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near-Infrared Fluorescence Imaging System Market |
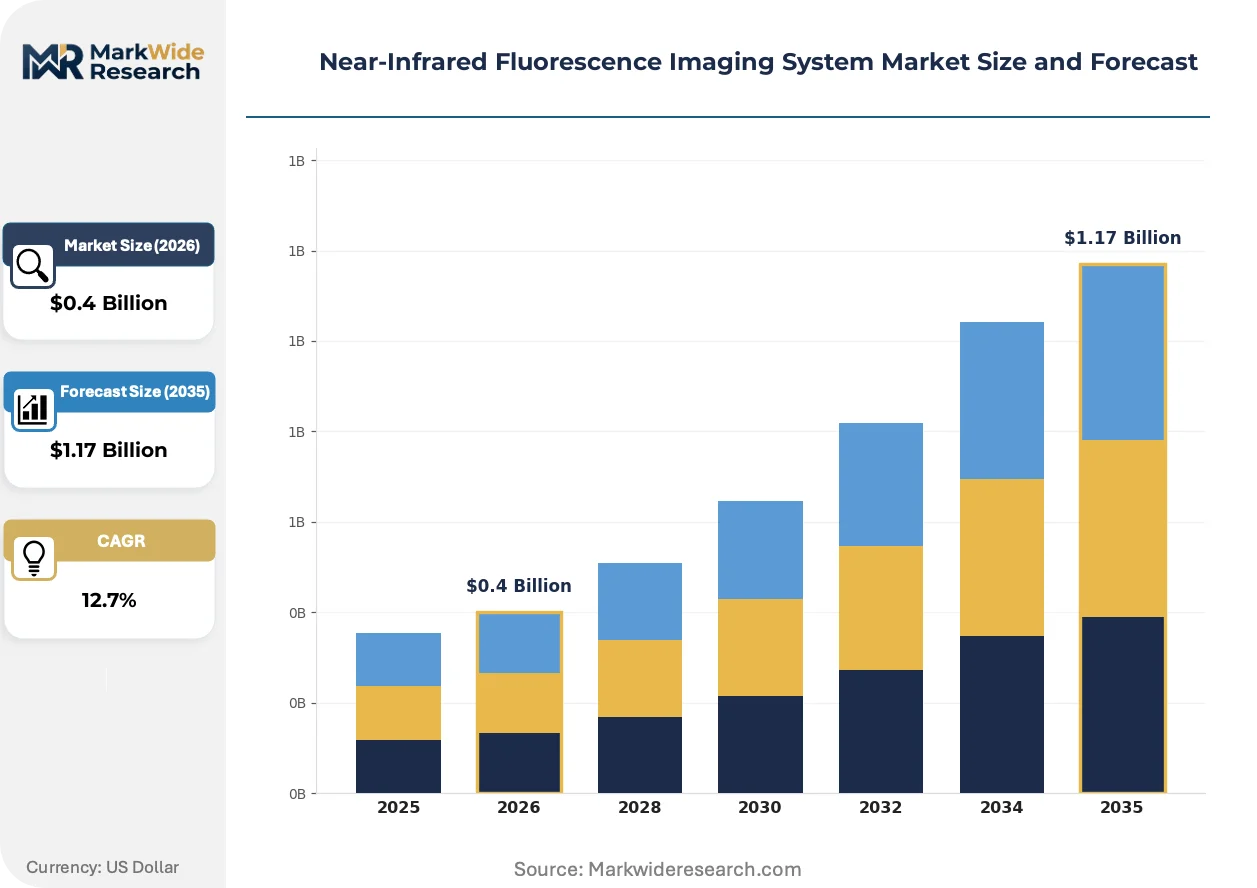
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $1.17 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Probes, Software, Accessories Application: Surgical Guidance, Oncology, Cardiovascular, Neurology End User: Hospitals, Research Institutions, Diagnostic Centers, Clinics Technology: Fluorescence, Multispectral Imaging, Real-Time Imaging, Spectral Imaging |
| Companies Covered | Stryker, Carl Zeiss Meditec AG, PerkinElmer, Inc., Olympus Corporation, Leica Microsystems, Hamamatsu Photonics K.K., Shimadzu Corporation, Medtronic plc, Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near-Infrared Fluorescence Imaging System Market Strategic Shifts
Fluorescence imaging hardware is undergoing platform convergence with established surgical visualization ecosystems, while regulatory pathways and procurement models co-evolve to match technology maturation.
Chip-scale NIR sensor arrays are miniaturizing. These silicon-integrated photodetectors replace discrete InGaAs components in cost-sensitive configurations. Ambulatory surgical centers in Germany and Japan are adopting the compact form factors for space-constrained procedure rooms. The technology is miniaturizing system footprints from cart-mounted towers to microscope-integrated modules, collapsing capital cost thresholds.
REACH chemical registration requirements are tightening scrutiny of novel fluorescent probe formulations entering European markets. The regulation is forcing probe developers to expand toxicology dossiers beyond standard indocyanine green derivatives. Oncology-focused system vendors with integrated agent portfolios face extended formulation approval timelines, compressing first-mover advantage windows for new molecular targets.
Academic medical center procurement committees are unbundling after-sales service contracts from capital equipment leases. Hospital supply chain directors in the United States are negotiating direct probe sourcing agreements separate from system vendor lock-in. The shift is most visible at National Cancer Institute-designated centers where annual probe consumption volumes justify multi-year supply contracts with independent agent manufacturers.
Near-Infrared Fluorescence Imaging System Market Segmentation
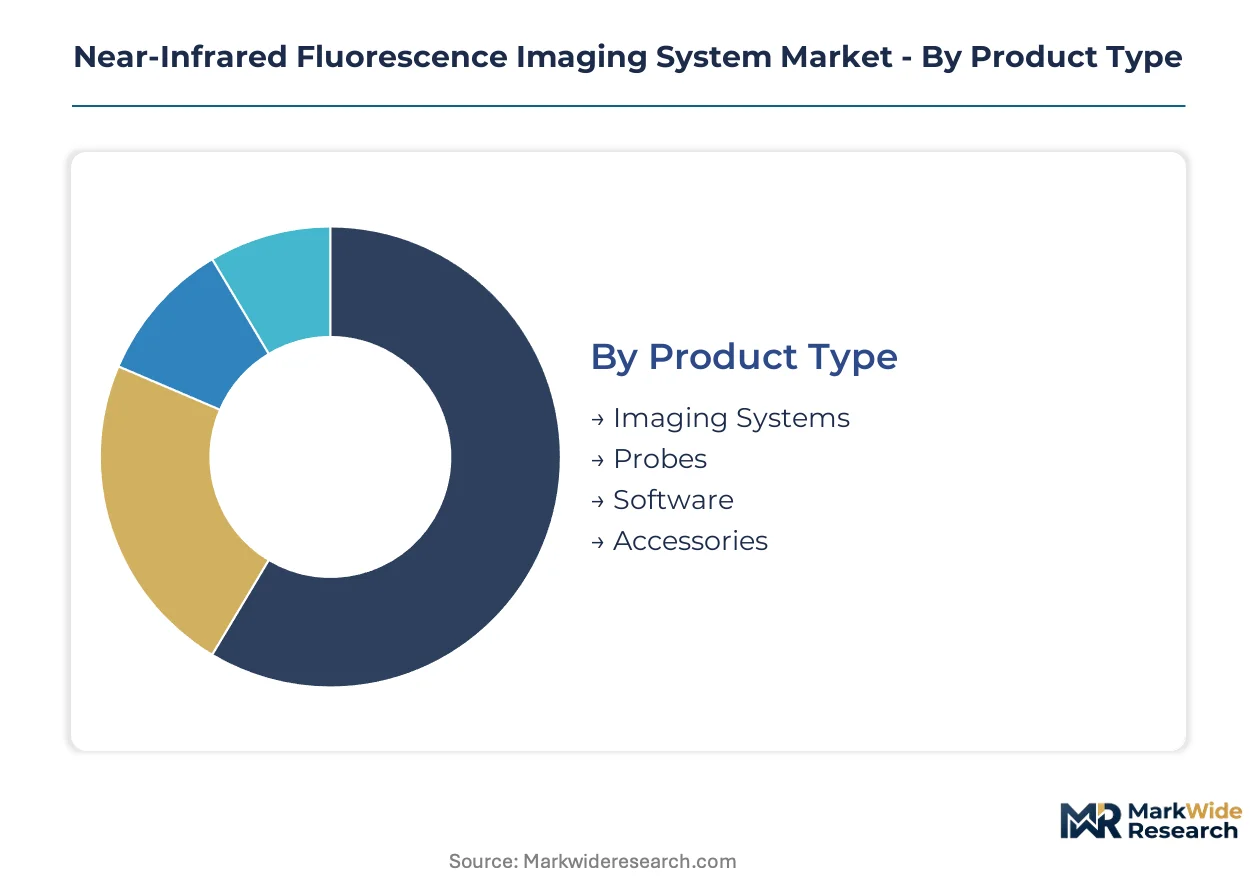
Near-infrared fluorescence imaging systems fragment across hardware, consumables, and software layers with distinct margin profiles and replacement cycles. Procurement patterns diverge sharply between capital-intensive imaging platforms and recurring probe purchases, creating divergent vendor strategies across segment boundaries.
Product Type:
Imaging systems face the most acute substitution pressure from integrated surgical microscope platforms that bundle fluorescence as a module rather than standalone capital equipment.
- Imaging Systems:Cart-mounted and microscope-integrated hardware platforms utilize InGaAs detector arrays and NIR excitation sources operating between 700-900 nanometers. Academic medical centers in the United States and Germany concentrate procurement authority for these systems within dedicated oncologic surgical units, bypassing general hospital committees and compressing vendor negotiation cycles.
- Probes:Targeted fluorescent agents including indocyanine green derivatives and investigational molecular probes require FDA 510(k) or PMDA approval for clinical use. Research institutions are outpacing hospitals in probe consumption volume as preclinical agent development pipelines expand across National Cancer Institute-designated centers.
- Software:Image processing and surgical navigation integration modules enable real-time perfusion mapping and margin assessment.
- Accessories:Optical filters, calibration phantoms, and disposable sheaths support system maintenance and infection control protocols.
Imaging systems anchor the volume base while probes gain share at the steepest rate.
Application:
Cost tier stratification separates high-complexity oncologic procedures from standardized cardiovascular assessments with divergent reimbursement density.
- Surgical Guidance:Real-time intraoperative visualization of vascular structures, tumor margins, and nerve tissue invisible under white-light conditions. Cardiovascular surgical suites in Japan and Germany are standardizing fluorescence assessment of graft patency, creating pull-through demand for integrated imaging modules.
- Oncology:Tumor margin delineation and sentinel lymph node mapping utilizing targeted fluorescent probes. FDA breakthrough device designations for fluorescence-guided oncology procedures are compressing time-to-market for novel system entrants.
- Cardiovascular:Perfusion mapping and tissue viability assessment during coronary artery bypass and valve replacement procedures.
- Neurology:Vascular and tumor margin visualization during neurosurgical interventions requiring integration with surgical microscope workflows.
Surgical guidance commands the dominant installation velocity while oncology climbs fastest on regulatory tailwinds.
End User:
Customer type determines procurement cycle length and probe consumption density, with research channels exhibiting shorter replacement intervals than clinical installations.
- Hospitals:General and specialty surgical units with established reimbursement pathways for image-guided procedures. German outpatient surgical centers are creating demand for compact, cart-based fluorescence systems outside traditional hospital settings.
- Research Institutions:Academic laboratories and preclinical development facilities expanding targeted agent R&D pipelines. Research institutions represent the expanding channel for fluorescence system procurement as probe development accelerates.
- Diagnostic Centers:Specialized imaging facilities conducting lymphatic mapping and perfusion studies.
- Clinics:Ambulatory surgical settings with space-constrained procedure rooms requiring miniaturized system footprints.
Hospitals retain the installed base majority while research institutions expand most quickly.
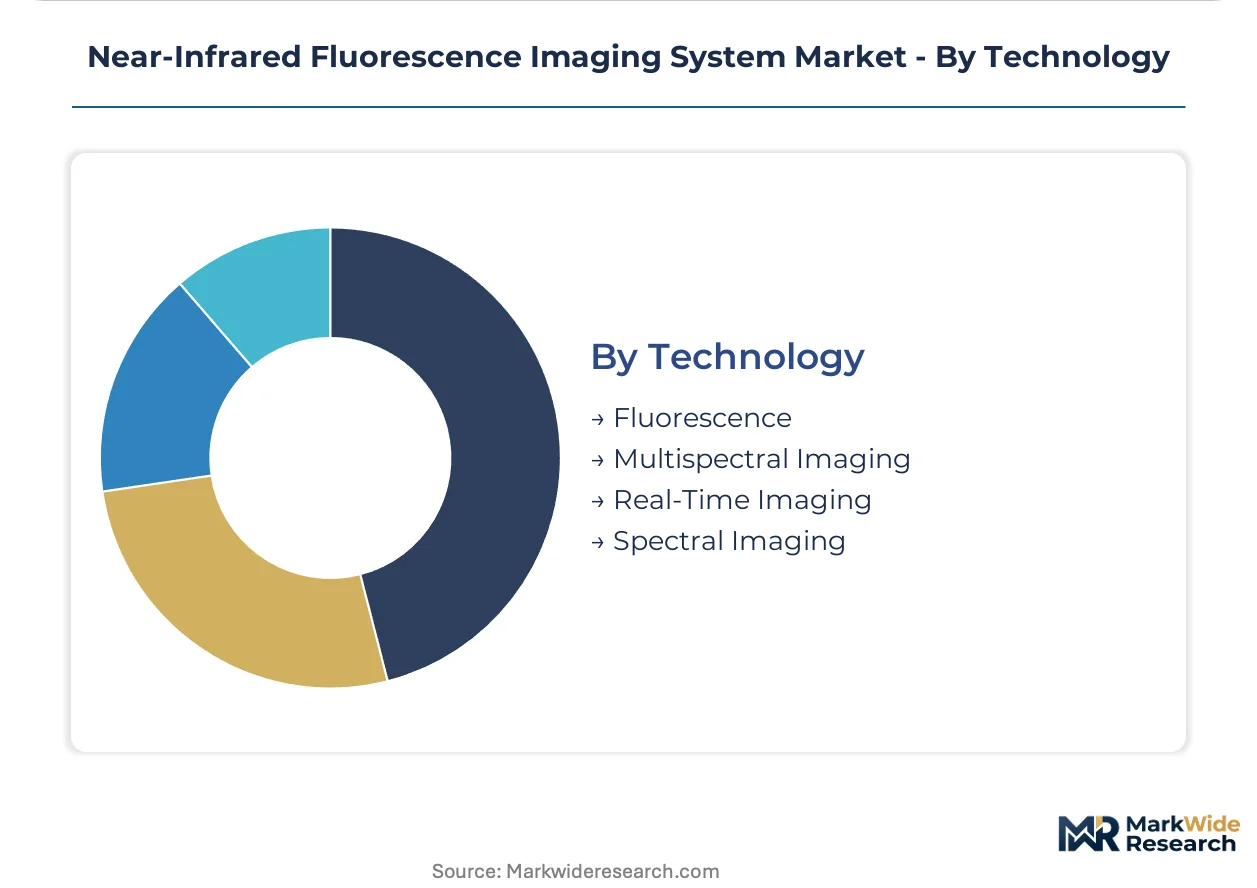
Technology:
Margin concentration favors multispectral configurations capable of simultaneous multi-agent detection over standard single-wavelength systems.
- Fluorescence:Standard single-wavelength NIR imaging utilizing indocyanine green excitation and emission detection. White-light surgical microscopes without fluorescence capability retain loyalty in cost-sensitive neurosurgical settings through lower capital thresholds.
- Multispectral Imaging:Simultaneous detection of multiple fluorescent agents across distinct wavelength bands. High-volume cancer centers are commanding premium positioning for multispectral capability over standard configurations.
- Real-Time Imaging:Continuous intraoperative visualization with minimal latency for surgical decision support.
- Spectral Imaging:Wavelength-resolved detection enabling tissue composition analysis beyond simple fluorescence intensity mapping.
Standard fluorescence technology secures the volume foundation while multispectral imaging captures the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision imaging components to United States academic medical centers, while Japan supplies high-sensitivity detector arrays to system assemblers across North America and Europe. This trade corridor concentrates procurement authority in specific metropolitan hospital clusters.
United States
National Cancer Institute-designated centers in Boston and Houston are accelerating fluorescence system procurement for oncologic surgical suites. FDA breakthrough device designations compress regulatory timelines for novel probe developers. The Mayo Clinic in Rochester anchors clinical validation protocols that diffuse to peer institutions.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are creating demand for compact cart-based systems outside traditional hospital settings. EU MDR mandates expanded post-market surveillance for fluorescence imaging platforms. Carl Zeiss Meditec in Oberkochen drives integrated surgical microscope-fluorescence workflows for neurosurgical applications.
Japan
Tokyo and Osaka metropolitan hospital networks are standardizing intraoperative fluorescence assessment for cardiovascular graft patency. PMDA enforces stringent ISO 13485 quality management audits that filter smaller probe manufacturers. Hamamatsu Photonics anchors supply of InGaAs detectors that power system sensitivity thresholds.
United Kingdom
London and Cambridge academic medical centers are expanding preclinical probe development pipelines faster than clinical installations. MHRA alignment with EU MDR extends recertification timelines for fluorescence imaging systems. The Cambridge biomedical cluster concentrates targeted agent R&D investment from venture-backed startups.
Switzerland
Basel and Zurich surgical units are procuring multispectral imaging configurations for simultaneous multi-agent detection. Swissmedic maintains rigorous clinical evidence requirements for fluorescence-guided procedure approvals. The Basel pharmaceutical corridor drives demand for integrated imaging platforms in drug development workflows.
Near-Infrared Fluorescence Imaging System Market Competitive Environment
Player mix skews toward diversified surgical visualization conglomerates with installed base leverage. The vendor base concentrates around three tiers: integrated surgical platform providers, specialized optical component suppliers, and preclinical probe developers. Strategic archetypes include bundlers leveraging navigation platform installed bases, detector specialists controlling upstream sensor supply, and microscope-integrated workflow providers. Dominant competitive moves encompass fluorescence module retrofit compatibility programs and direct probe sourcing agreements that bypass system vendor lock-in.
Among diversified surgical platform providers, Stryker and Medtronic exemplify the bundling archetype, leveraging broad installed bases across orthopedic and cardiovascular suites. Carl Zeiss Meditec occupies a position within the precision optics tier, representing integrated microscope-fluorescence workflow specialization. Hamamatsu Photonics K.K. anchors the component supply tier, exemplifying upstream detector manufacturing concentration that exposes system assemblers to single-source supply dynamics.
| Leading Market Players |
|---|
| Stryker |
| Carl Zeiss Meditec AG |
| PerkinElmer, Inc. |
| Olympus Corporation |
| Leica Microsystems |
| Hamamatsu Photonics K.K. |
| Shimadzu Corporation |
| Medtronic plc |
| Teledyne FLIR LLC |
| Others |
Value Chain & Pricing Dynamics
Twelve-to-eighteen-month ISO 13485 certification timelines for probe manufacturers compress inventory buffers and amplify pricing power for Japanese and German detector foundries serving system assemblers. This lead-time band concentrates procurement leverage among academic medical centers with dedicated surgical subspecialty units capable of absorbing premium positioning for multispectral configurations.
Pricing Analysis
Multispectral-imaging-versus-standard-fluorescence pricing gaps separate premium configurations from cost-sensitive cart-based systems. Three-tier pricing structure across premium, standard, and economy levels reflects detector sensitivity thresholds, software integration depth, and after-sales service bundling. Cost compression in standard fluorescence tiers is intensifying because chip-scale NIR sensor arrays displace discrete InGaAs components. Research institutions exhibit lowest price sensitivity due to grant-funded procurement, while German outpatient surgical centers face acute capital constraints.
Supply Chain Analysis
InGaAs detector manufacturing concentrates in Hamamatsu, Japan and select German sensor foundries, exposing system assemblers to single-source vulnerability during quality management system audits. Fluorescence imaging hardware draws from Japanese detector arrays, German precision optics, and United States software modules. Tariff exposure runs through transatlantic component shipments for EU MDR-compliant systems. Distribution runs through direct hospital procurement committees at academic medical centers and specialized surgical device distributors serving ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Academic medical center consolidation into dedicated oncologic surgical units is shifting buyer power toward institutional procurement committees capable of unbundling after-sales contracts from capital equipment leases.
For Market Incumbents: Shield installed base loyalty through fluorescence module retrofit compatibility programs for legacy surgical navigation platforms. Deepen backward integration into InGaAs detector supply through exclusive foundry partnerships in Japan. Prioritize ISO 13485 certification maintenance to sustain PMDA market access against emerging probe developers. For New Entrants and Emerging Players: Differentiate on preclinical probe development channel penetration at National Cancer Institute-designated centers with unmet agent R&D demand. Target compact cart-based system configurations for German ambulatory surgical centers outside traditional hospital procurement hierarchies. Pursue direct probe sourcing agreements that bypass incumbent system vendor lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical visualization conglomerates seeking to divest non-core fluorescence imaging modules. Long-term viability hinges on regulatory pathway acceleration through FDA breakthrough device designations and reimbursement code expansion across national health technology assessment bodies. Monitor EU MDR recertification timeline extensions as inflection indicator for incumbent compliance burden.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescence Module Retrofit Compatibility | Preserves installed base loyalty against standalone system substitution at Stryker and Medtronic surgical navigation platforms. |
| Preclinical Probe Development Partnership | Captures research institution procurement velocity outpacing hospital channel growth at National Cancer Institute-designated centers. |
| Multispectral Imaging Platform Launch | Commands premium positioning over standard fluorescence at high-volume cancer centers in Switzerland and Germany. |
| ISO 13485 Certification Acceleration | Unlocks Japan PMDA market access for probe manufacturers facing 12-18 month quality management audit cycles. |
| Direct Probe Sourcing Agreement | Bypasses system vendor lock-in as academic medical centers unbundle after-sales service from capital equipment leases. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, PMDA approval databases, and hospital procurement contract records. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and fluorescence system field service technicians informed demand-side validation. Bottom-up system installation counts and top-down revenue estimates triangulate market sizing across the analysis window.
Segmentation dimensions modeled include product type, application, end user, and technology tier across the projection horizon. CAGRs derive from weighted average of historical procurement velocity and regulatory pathway acceleration assumptions. Forecast inputs incorporate FDA breakthrough device designation timelines, EU MDR post-market surveillance expansion, and Japan PMDA reimbursement code approvals for image-guided procedures.
The analysis sits within stated boundaries; outcomes outside continued regulatory pathway compression or supply chain disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding detector foundry capacity expansion and academic medical center capital budget prioritization. Practitioners should keep alternative scenarios live as EU MDR clinical evidence requirements and REACH chemical registration scrutiny evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
High-Speed Camera Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Photoacoustic Imaging Market
Imaging
Global Trail Camera Market
Imaging
Printed Image Sensors Market
Imaging
Global Broadcast Cameras Market
Imaging
Camera Technology Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Photoacoustic Tomography Market
Imaging
Global Microbolometer Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
X-Ray Market
Imaging
Multi Camera System Market
Imaging
Photoconductor Drums Market
Imaging
Asia-Pacific Image Recognition Market