
 Global Tamper Evident Packaging Market | 2026-2036
Global Tamper Evident Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tamper Evident Packaging Market Intelligence
Pharmaceutical end-use is recalibrating demand toward multi-layer security labels and track-and-trace blister packs as drug manufacturers face intensifying counterfeit scrutiny. Huhtamaki Group leverages its European manufacturing footprint to sustain pharmaceutical-grade film supply across regulated markets. CCL Industries anchors North American demand through specialized shrink band and security label production for branded drug packaging. Essentra competes in high-barrier blister formats with in-house tooling capabilities that reduce lead times for custom pharmaceutical applications.
Tamper evident packaging denotes closure systems, labels, seals, or films engineered to reveal irreversible visual or physical damage upon unauthorized opening, typically incorporating frangible substrates, cohesive break patterns, or holographic authentication layers to protect product integrity. The primary commercial purpose centers on consumer safety assurance, liability reduction, and supply chain integrity verification across packaged goods industries. Security labels and shrink bands command the largest volume positions, while blister packs in pharmaceutical applications capture disproportionate margin pools due to compliance-driven specification rigidity. Plastic substrates dominate material throughput, though PET film segments are gaining structural share as sustainability mandates pressure PVC replacement in European and North American supply chains.
FDA drug supply chain security requirements and EU Falsified Medicines Directive enforcement are mandating unit-level tamper verification across pharmaceutical distribution, directly expanding specification intensity for packaging converters. China's NMPA traceability regulations and SAMR food safety labeling standards are extending tamper evident requirements into domestic food and beverage packaging, opening incremental demand corridors for certified film suppliers. Stakeholders must monitor regulatory harmonization between FDA, EMA, and NMPA serialization standards to anticipate specification convergence or divergence that will reshape converter qualification requirements and capital deployment priorities.
Market Dynamics
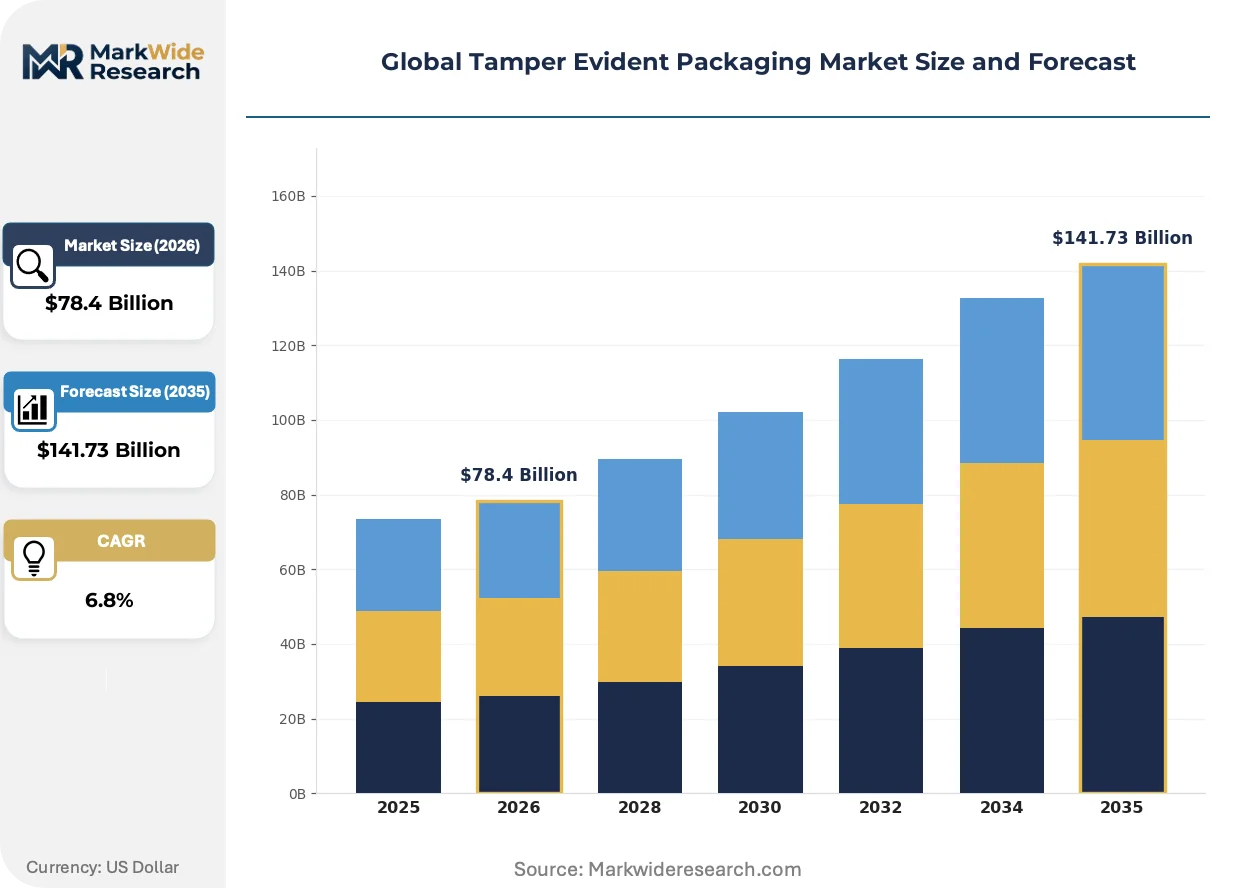
Regulatory serialization mandates across pharmaceutical supply chains are forcing packaging converters to reengineer specification intensity, compressing qualification timelines while fragmenting procurement authority between quality assurance and procurement functions.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability requirements in the United States mandate tamper verification layers on pharmaceutical containers, expanding specification volume for security labels and blister formats.
- EU Falsified Medicines Directive enforcement:European serialization deadlines compel drug manufacturers to adopt multi-layer authentication packaging, directly lifting demand for holographic seals and frangible closures.
- Food and beverage safety labeling in China:SAMR standards extend tamper evident requirements into domestic consumer goods, opening certified film demand corridors beyond pharmaceutical end-uses.
Market Restraints
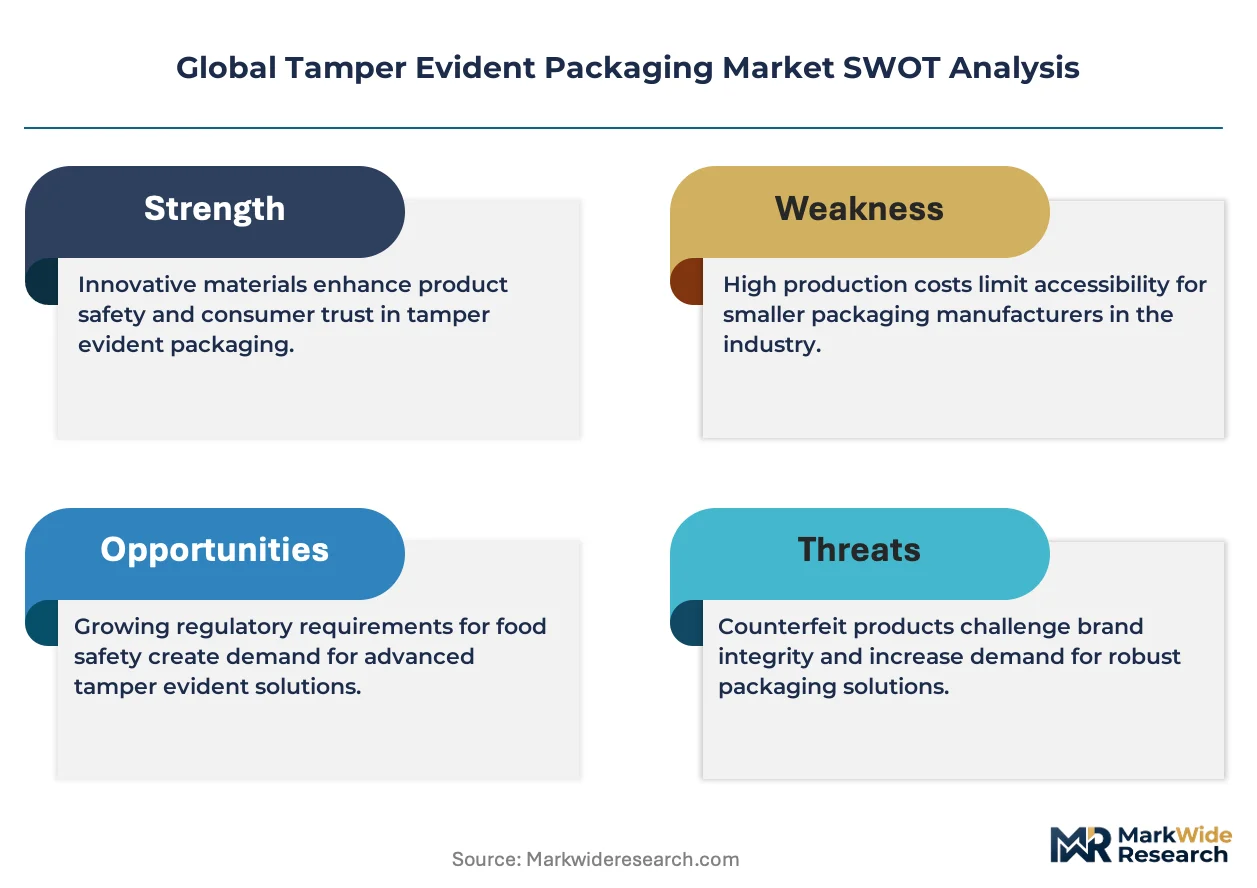
- Resin cost volatility:PET and PP substrate prices fluctuate with crude oil indices, squeezing converter margins on long-term pharmaceutical contracts with fixed pricing terms.
- Specialized tooling concentration:Custom blister die and holographic master production clusters in Germany and Switzerland, creating geographic supply risk for North American and Asian converters.
- Regulatory divergence friction:Non-harmonized serialization standards between FDA, EMA, and NMPA force redundant qualification testing, extending new product introduction timelines.
Strategic Opportunities
- Underpenetrated Latin American pharmaceutical markets:ANVISA traceability implementation lags FDA and EMA by several years, creating first-mover positioning for converters establishing local technical service presence.
- Biologics cold-chain packaging:Temperature-sensitive biologics require tamper evident formats with thermal stability, opening specification space for specialized film laminates and adhesive systems.
- Digital watermark authentication:Covert machine-readable markers is converging with conventional physical seals, enabling brand owners to deploy layered verification without consumer-facing complexity.
Industry Challenges
- Serialization engineering talent scarcity:Packaging engineers with combined expertise in track-and-trace software and physical security feature design command premium compensation, constraining converter expansion.
- Legacy equipment retrofit costs:Existing printing and converting lines require substantial modification to integrate variable data printing and vision inspection systems for pharmaceutical-grade output.
- Cross-border certification delays:Mutual recognition agreements between FDA and foreign regulators remain incomplete, forcing duplicate facility audits and extending time-to-revenue for new production sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tamper Evident Packaging Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrink Bands, Security Labels, Seals, Tape, Blister Packs Application: Pharmaceuticals, Food & Beverage, Electronics, Cosmetics, Agriculture End User: Drug Manufacturers, Food Processors, Electronics Assemblers, Personal Care Brands, Agrochemical Producers Material: Plastic, Paperboard, Aluminum Foil, PET Film, PVC |
| Companies Covered | Huhtamaki Group, CCL Industries, Berry Global, Essentra, Securikett, Amcor Limited, ALPLA Group, Constantia Flexibles Group, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tamper Evident Packaging Market Strategic Shifts & Innovations
Authentication technologies are layering physical and digital verification methods, while sustainability mandates pressure substrate substitution and regulatory enforcement tightens specification rigidity across regulated end-uses.
Blockchain-enabled supply chain verification is converging with conventional tamper evident seals to create immutable provenance records. Pharmaceutical distributors in the United States are piloting integrated systems that link physical package breach detection to distributed ledger entries. This dual-layer approach compresses investigation timelines for suspected diversion incidents while enabling real-time authentication queries.
REACH restrictions on PVC plasticizers are accelerating PET film substitution in European pharmaceutical blister applications. Converters serving EMA-regulated markets must reformulate barrier properties without legacy chlorine-based substrates. German packaging engineers are deploying co-extruded PET/PE laminates that replicate PVC thermoforming characteristics while satisfying sustainability audit requirements.
Direct-to-pharmacy distribution models are compressing traditional wholesaler channel structures. Hospital systems and specialty pharmacies in the United States now specify custom tamper evident formats with institutional branding and patient-specific data fields. This disintermediation fragments order volumes while multiplying SKU complexity for converters maintaining pharmaceutical-grade production lines.
Global Tamper Evident Packaging Market Segmentation
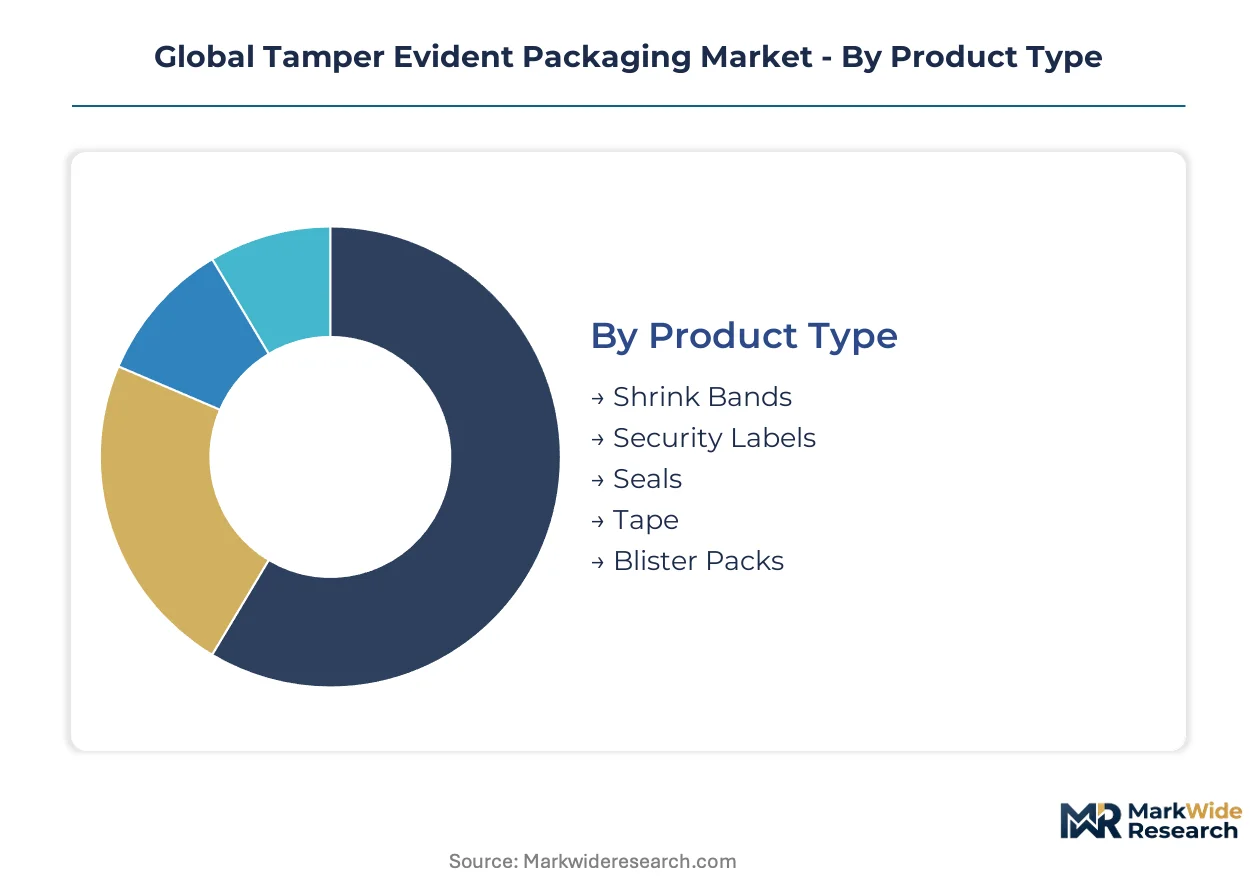
Segmentation in tamper evident packaging reveals how specification intensity varies across regulatory environments and product risk profiles. Material choices and format complexity diverge sharply between pharmaceutical compliance mandates and consumer goods brand protection requirements.
Product Type:
Standardized formats dominate high-volume food and beverage applications, while pharmaceutical end-users demand engineered customization with multi-layer authentication features.
- Shrink Bands:Heat-shrinkable polymer sleeves conform to container contours and fracture visibly upon removal. Demand clusters in United States beverage bottling where tamper visibility satisfies FDA food safety expectations. Cost efficiency and high-speed application compatibility sustain volume leadership.
- Security Labels:Adhesive-backed substrates with frangible facestocks or void-release patterns reveal unauthorized removal through irreversible text transfer or pattern destruction. Pharmaceutical manufacturers in Germany specify holographic and color-shifting variants to satisfy EMA authentication requirements under the Falsified Medicines Directive.
- Seals:Closure-integrated mechanical systems provide breach indication through breakable rings or snap-fit destruction.
- Tape:Pressure-sensitive adhesive formats with tamper-reveal backings secure carton flaps and pallet wraps.
- Blister Packs:Thermoformed cavities with lidding foil deliver unit-dose protection and child resistance for oral solid dosage forms.
Most installed capacity flows through Shrink Bands. Expansion is steepest in Security Labels.
Application:
Regulatory enforcement intensity creates a tiered demand structure, with compliance-driven pharmaceutical specifications commanding premium pricing against brand-protection-motivated consumer goods.
- Pharmaceuticals:Unit-level serialization and tamper verification mandated by FDA Drug Supply Chain Security Act and EU Falsified Medicines Directive. Blister packs, vial seals, and cartoning systems require integrated track-and-trace compatibility. China NMPA traceability regulations are extending similar requirements into domestic distribution.
- Food & Beverage:Tamper evident closures and labels protect product integrity in retail distribution. SAMR labeling standards in China and FDA food defense guidelines in the United States establish baseline requirements without universal serialization mandates.
- Electronics:Void labels and destructible seals protect high-value components against warranty fraud and gray market diversion.
- Cosmetics:Shrink bands and breakable caps signal unopened status for premium personal care products.
- Agriculture:Seed packaging and agrochemical containers employ tear-reveal formats to indicate tampering with genetic material or crop protection products.
Pharmaceuticals absorbs the highest specification intensity. Food & Beverage generates the largest unit volumes.
End User:
Procurement authority fragmentation distinguishes this category, with quality assurance teams controlling pharmaceutical converter selection while procurement functions manage consumer goods supplier relationships.
- Drug Manufacturers:Multinational pharmaceutical companies qualify converters through extensive facility audits and validation protocols. Serialization integration requirements favor suppliers with pharmaceutical-grade cleanroom capabilities and validated software systems.
- Food Processors:National and regional brands specify tamper evident formats based on retail channel requirements and liability exposure.
- Electronics Assemblers:OEMs and contract manufacturers deploy authentication features to combat counterfeiting in component distribution.
- Personal Care Brands:Premium positioning drives investment in distinctive tamper evident designs.
- Agrochemical Producers:Regulatory compliance with national agricultural chemical labeling standards shapes format selection.
Drug Manufacturers impose the most stringent qualification barriers. Food Processors offer the broadest addressable base.
Material:
Sustainability mandates and barrier property requirements are displacing legacy substrates across regulated end-uses, with performance-engineered alternatives gaining specification share.
- Plastic:Polypropylene and polystyrene formulations provide cost-efficient shrink and formability for high-volume applications. REACH restrictions on additives are accelerating reformulation efforts for European market access.
- PET Film:Co-extruded and metallized polyethylene terephthalate structures replicate PVC thermoforming characteristics while satisfying sustainability audit requirements. German converters lead deployment in pharmaceutical blister applications.
- Paperboard:Fiber-based substrates with tamper-reveal coatings serve secondary packaging and cartoning functions.
- Aluminum Foil:High-barrier lidding materials protect moisture-sensitive pharmaceuticals.
- PVC:Legacy chlorine-based substrate faces displacement pressure from European sustainability mandates despite established thermoforming performance.
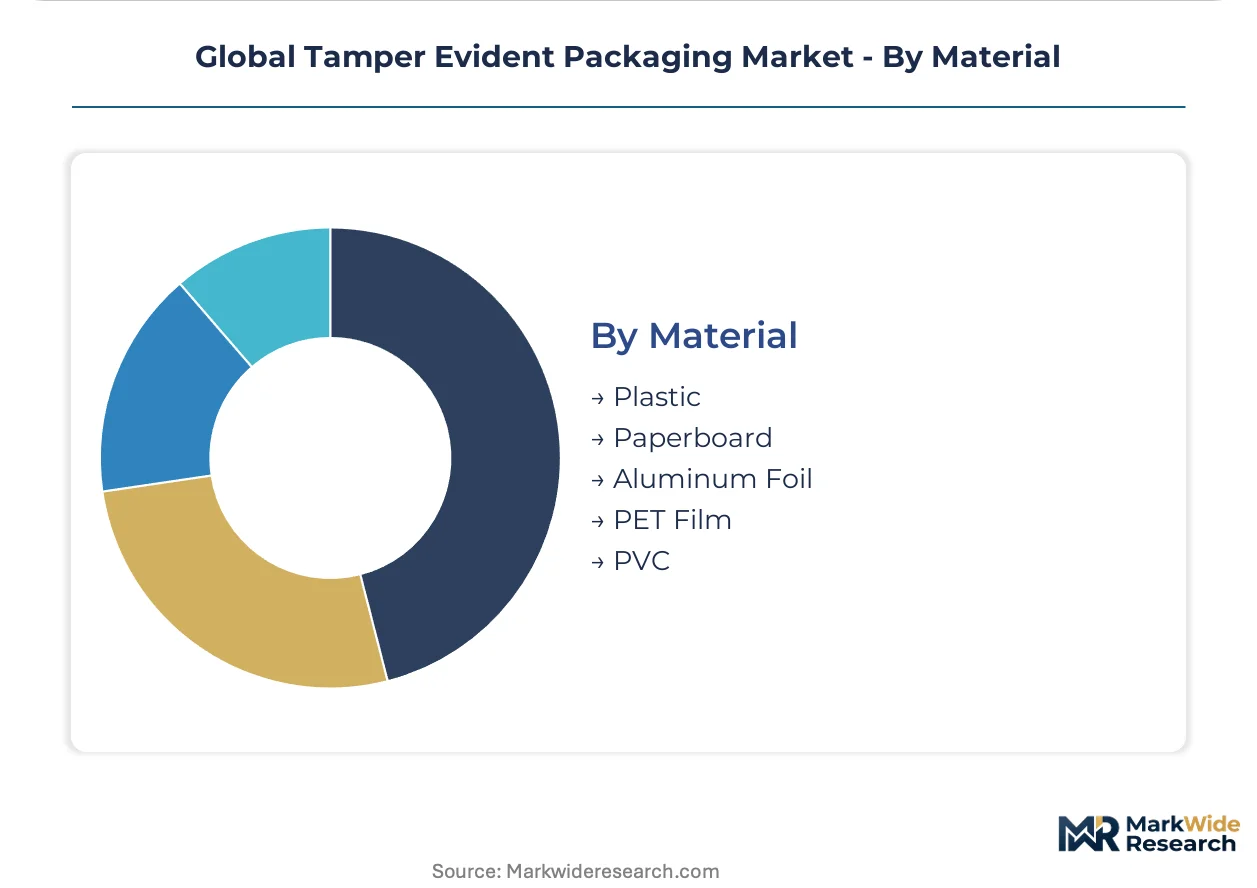
PVC retains substantial installed base. PET Film is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhineland packaging clusters anchor European converter capacity for pharmaceutical-grade tamper evident formats. FDA enforcement in the United States and NMPA traceability mandates in China are redistributing demand toward regulatory-heavy jurisdictions.
United States
Specialty pharmacies and hospital systems now specify custom tamper evident formats with patient-specific data fields. FDA Drug Supply Chain Security Act unit-level traceability requirements compress qualification timelines for domestic converters. New Jersey and Pennsylvania host dense concentrations of pharmaceutical packaging engineers serving branded drug manufacturers.
Germany
EMA Falsified Medicines Directive enforcement drives specification intensity for holographic seals and frangible closures. REACH restrictions on PVC plasticizers accelerate PET film substitution in blister applications. Stuttgart and Munich clusters specialize in co-extruded barrier laminates for cold-chain biologics.
China
NMPA traceability regulations extend tamper evident requirements into domestic pharmaceutical distribution. SAMR food safety labeling standards open incremental demand corridors for certified film suppliers beyond drug packaging. Yangtze River Delta converters scale pharmaceutical-grade cleanroom capacity to serve multinational drug manufacturers.
Switzerland
Swissmedic serialization standards align with EMA requirements, creating specification continuity across Alpine supply chains. Specialized tooling for custom blister dies concentrates in Basel and Zurich industrial corridors. Precision engineering heritage supports high-barrier format development for temperature-sensitive biologics.
India
CDSCO track-and-trace implementation lags FDA and EMA timelines, creating qualification runway for export-oriented converters. Maharashtra and Gujarat pharmaceutical zones drive demand for security labels on generic drug exports. Domestic food processors adopt tamper evident closures as FSSAI labeling standards tighten.
Global Tamper Evident Packaging Market Key Industry Players
Capacity expansion dominates the current landscape as converters add pharmaceutical-grade cleanroom lines to capture serialization-driven demand. The vendor base stratifies across three tiers: multinational integrated packaging groups with validated software systems, regional specialists with deep regulatory expertise, and commodity converters serving consumer goods. Two archetypes command disproportionate influence: European film laminators with sustainability-compliant substrate portfolios, and North American security label producers with FDA qualification depth. M&A activity concentrates on track-and-trace software integration, while strategic partnerships between converters and authentication technology licensors multiply SKU complexity.
Among European-based integrated groups, Huhtamaki Group and Constantia Flexibles Group occupy positions exemplifying the sustainability-driven archetype, leveraging continental manufacturing footprints to sustain pharmaceutical-grade film supply across EMA-regulated markets. CCL Industries anchors North American representation within the security label specialization vector, with Essentra sitting within the high-barrier blister format tier where in-house tooling capabilities reduce lead times for custom pharmaceutical applications.
| Leading Market Players |
|---|
| Huhtamaki Group |
| CCL Industries |
| Berry Global |
| Essentra |
| Securikett |
| Amcor Limited |
| ALPLA Group |
| Constantia Flexibles Group |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade certification tiers split the converter base into FDA-validated suppliers commanding long-term contracts and commodity producers serving consumer goods on spot pricing. This bifurcation concentrates margin capture among German and Swiss film laminators with EMA qualification depth while squeezing undifferentiated North American shrink band producers facing resin cost pass-through limitations.
Pricing Analysis
Crude oil-indexed PET and PP resin costs transmit directly into converter quotations through quarterly adjustment clauses in pharmaceutical contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cleanroom production from food-grade film extrusion and generic shrink sleeve commodity supply. Cost compression in standard-grade security labels is intensifying because Chinese converters are scaling metallized PET capacity with government equipment subsidies. Generic drug manufacturers in India exhibit the highest price sensitivity, while biologics producers in Switzerland accept 40-60% premiums for cold-chain validated barrier laminates with thermal stability guarantees.
Supply Chain Analysis
FDA and EMA facility qualification requirements gate pharmaceutical-grade film supply to converters in Germany, Switzerland, and the United States with validated cleanroom lines. Custom blister die tooling and holographic master production draws from specialized engineering clusters in Basel and Stuttgart, creating single-source vulnerability for North American and Asian converters seeking rapid format customization. Tariff exposure on Chinese metallized PET imports is reshaping sourcing strategies for US security label producers. Distribution runs through direct converter-to-drug-manufacturer relationships for pharmaceutical grades, while food and beverage applications flow through regional distribution networks with consolidated procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge where EMA qualification costs in Switzerland exceed FDA validation expenses in New Jersey by approximately 30%, favoring North American capacity expansion for export-oriented pharmaceutical packaging.
For Market Incumbents: Acquire track-and-trace software capabilities to defend against technology substitution from digital watermark authentication platforms. Incumbents should consolidate holographic master production capacity in Basel to reduce lead times for EMA-regulated custom blister formats. Backward integration into co-extruded PET/PE laminate extrusion insulates margin positions from REACH-driven substrate reformulation costs. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical blister packs offers entry space for certified converters targeting generic drug exporters in Maharashtra and Gujarat. New entrants should prioritize ANVISA pre-qualification in Brazil ahead of traceability mandate implementation. A technical service partnership with regional pharmaceutical distributors provides the lowest-friction go-to-market path in underpenetrated Latin American markets. For Investors and Strategic Acquirers: Consolidation pressure builds where serialization engineering talent scarcity constrains converter expansion timelines. Mid-cap European film laminators with sustainability-compliant substrate portfolios represent the most viable acquisition archetype over a five-to-ten year pharmaceutical outsourcing cycle. Investors should monitor FDA-EMA mutual recognition agreement progress as the inflection signal for cross-border facility audit rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Track-and-Trace Software Integration | Links physical tamper evident seals to blockchain-enabled supply chain verification systems for pharmaceutical distributors. |
| PET Film Substitution Capacity | Replicates PVC thermoforming characteristics while satisfying REACH restrictions on chlorine-based substrates in EMA-regulated markets. |
| Biologics Cold-Chain Validation | Develops thermal stability guarantees for temperature-sensitive barrier laminates serving Swissmedic-regulated distribution. |
| Latin American Technical Service Expansion | Establishes local qualification support ahead of ANVISA traceability implementation in Brazilian pharmaceutical distribution. |
| Holographic Master Production Consolidation | Concentrates custom tooling capabilities in Basel-Zurich corridor to reduce lead times for EMA authentication requirements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical packaging engineers, regulatory affairs directors at drug manufacturers, film procurement leads, and cleanroom operations managers with secondary validation against FDA Drug Supply Chain Security Act guidance documents, EMA Falsified Medicines Directive implementation reports, SAMR food safety labeling standards, and customs trade data for PET and PP resin imports. Bottom-up capacity modeling at converter facility level was triangulated against top-down pharmaceutical packaging demand projections.
Historical reference periods spanning pre-serialization and post-mandate implementation phases anchored the forecast window to observable regulatory shock effects. Segmentation dimensions included product type, application end-use, material substrate, and regional regulatory cluster intensity. CAGRs were derived from installed capacity expansion announcements cross-referenced with drug manufacturer qualification timelines. Forecast inputs incorporated REACH restriction schedules on PVC plasticizers and NMPA traceability rollout pacing across Chinese provincial pharmaceutical distribution networks.
Caveats apply where resin cost volatility, regulatory divergence between FDA and NMPA serialization standards, or mutual recognition agreement delays could materially shift the outlook. Forecasts reflect assumptions regarding pharmaceutical outsourcing continuity and sustainability mandate enforcement intensity. A model refresh is warranted upon material change in EMA-FDA harmonization progress or biologics cold-chain packaging specification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Polypropylene Film Market
Packaging
Wire Marking Labels Market
Packaging
Sealant Films Market
Packaging
Hot Foil Printing Machines Market
Packaging
ESD Workstations Market
Packaging
Release Coatings Market
Packaging
Polyester Labels Market
Packaging
Filmic Tapes Market
Packaging
MET-PET Cartons Market
Packaging
United Arab Emirates Plastic Caps and Closures Market
Packaging
HDPE Crates Market
Packaging
Extended Text Labels Market
Packaging
Italy Honeycomb Paper Market
Packaging
US Packaging Market
Packaging
Rigid Industrial Packaging Market
Packaging
Litho Laminated Cartons Market