
 Vacuum Thermoformed Packaging Market | 2026-2036
Vacuum Thermoformed Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Thermoformed Packaging Market Outlook
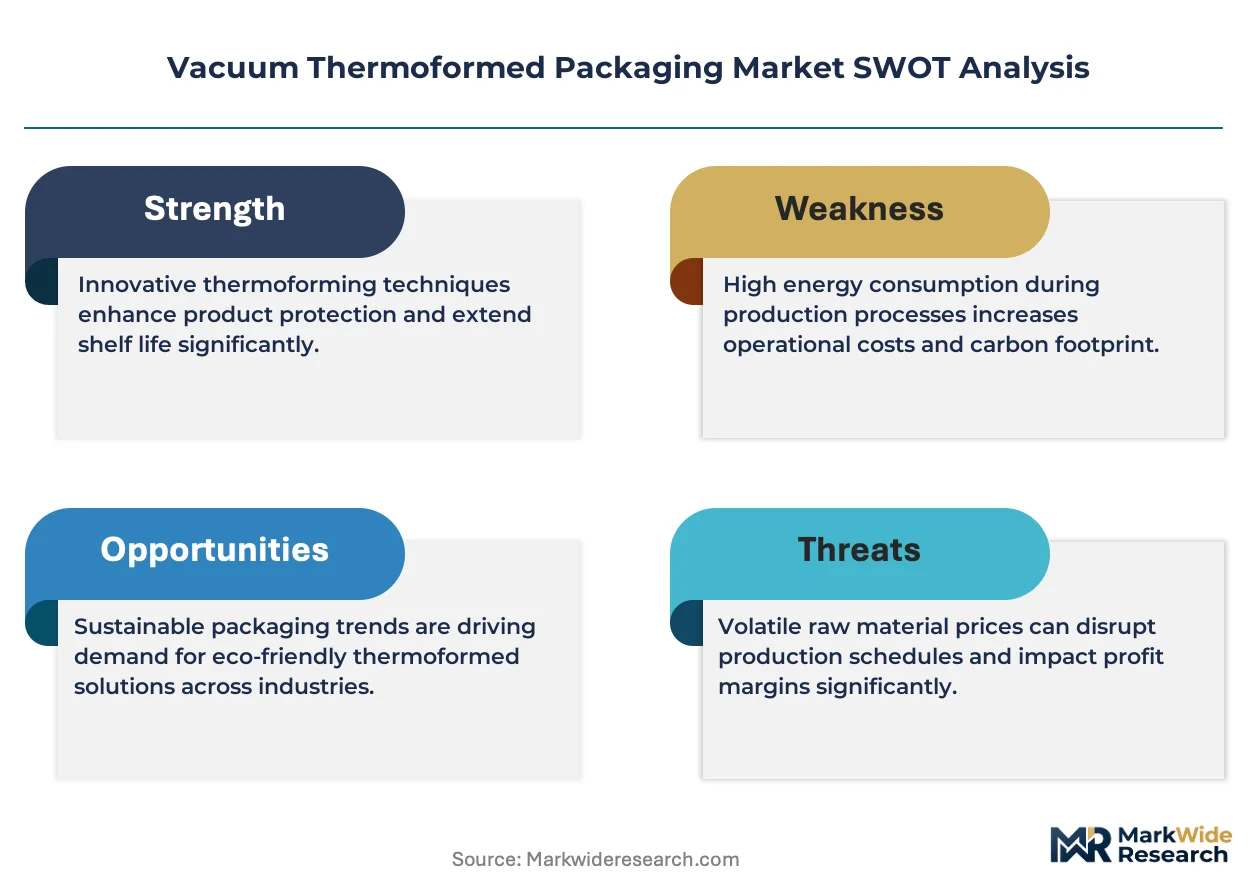
Polyethylene terephthalate is consolidating its position as the preferred substrate over polystyrene in food-contact thermoforming due to superior recyclability and clarity economics. Bardes Plastics leverages captive sheet extrusion to control resin conversion costs across Midwest manufacturing. Reflex Packaging sustains technical leadership in reusable dunnage programs for automotive tier suppliers. Innovative Plastec anchors its position through medical-grade cleanroom thermoforming capabilities.
Vacuum thermoformed packaging refers to the process of heating thermoplastic sheet material until pliable, then drawing it against a mold surface via vacuum pressure to create dimensionally precise containers, trays, and protective enclosures with wall thickness typically ranging from 0.005 to 0.250 inches. The technique produces lightweight, cost-efficient packaging with excellent product visibility and impact protection for retail display, sterile medical containment, and industrial component shipping. Blister packaging dominates pharmaceutical unit-dose dispensing where child-resistant lidding and moisture barrier properties command premium positioning. Clamshell packaging captures the fastest expansion in electronics retail as anti-theft visibility requirements intensify. Tray packaging represents the mature volume base in fresh protein and produce distribution where standardization and line speed economics matter most.
The FDA regulates food-contact substances under 21 CFR 177, while the EPA oversees volatile organic compound emissions from thermoforming operations under Clean Air Act standards. The EU F-Gas Regulation constrains blowing agent choices for foamed trays, pushing converters toward physical foaming with nitrogen or carbon dioxide. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in chemical recycling partnerships or mechanical recycling infrastructure to secure post-consumer feedstock access.
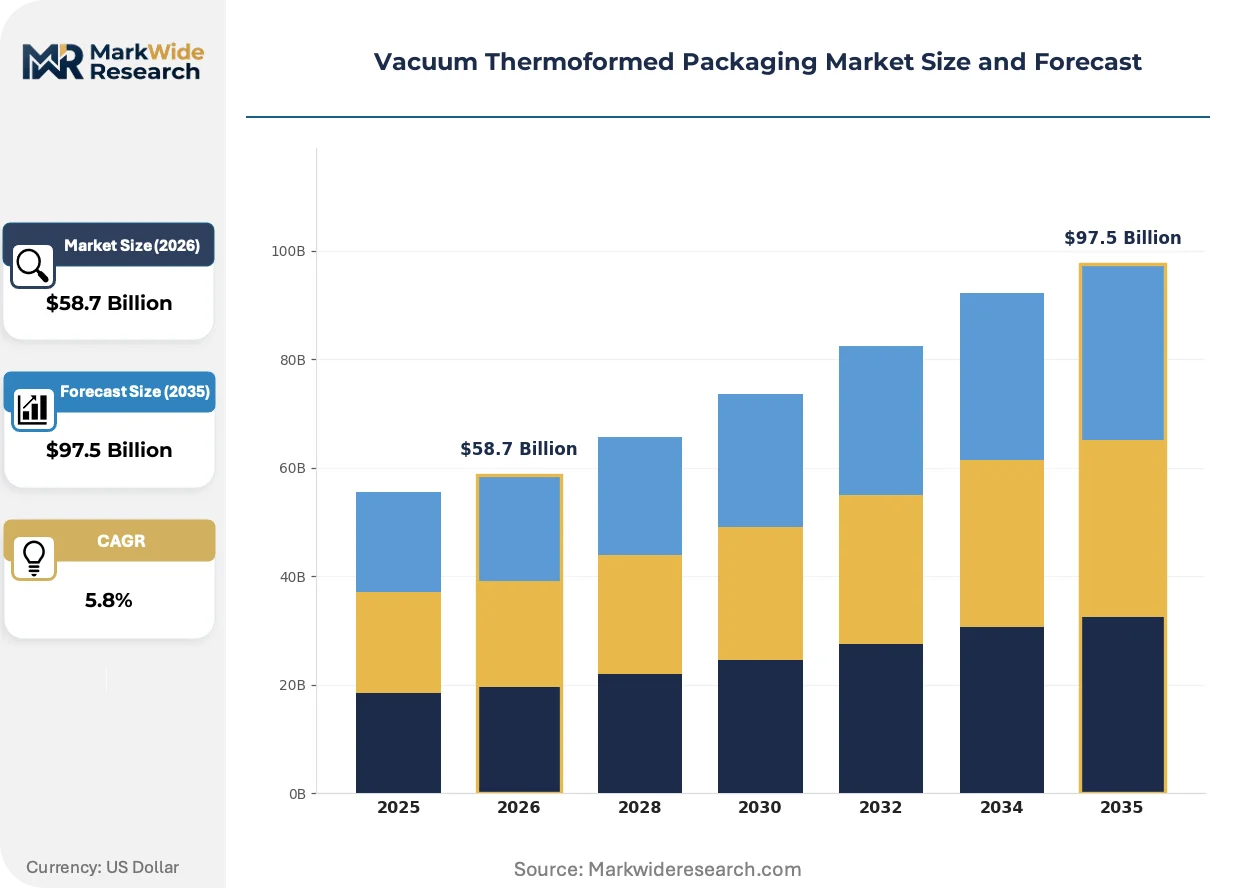
Market Dynamics
Material substitution pressure from EU Packaging and Packaging Waste Regulation is compressing polystyrene demand while expanding recyclable PET and PP sheet consumption across European food packaging lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable content are redirecting converter capex toward mono-material PET lines and chemical recycling partnerships.
- Food & Beverages sector:Protein processors are replacing rigid containers with thermoformed trays to cut shipping weight and extend shelf life through modified atmosphere compatibility.
- German automotive cluster:Tier suppliers around Stuttgart and Wolfsburg require precision dunnage for electric drivetrain components, sustaining demand for high-tolerance thermoformed packaging.
Market Restraints
- Resin price volatility:PET and PP feedstock costs swing with crude oil and recycled flake availability, squeezing converter margins on fixed-price annual contracts.
- Sheet extrusion concentration:North American supply concentrates among five major extruders, creating bottleneck risk during demand spikes.
- EU F-Gas Regulation:Restrictions on hydrofluorocarbon blowing agents limit foamed tray options and force capital-intensive retooling toward nitrogen or carbon dioxide physical foaming.
Strategic Opportunities
- Medical device cleanroom expansion:Sterile barrier packaging for surgical kits and implantables offers premium pricing with multi-year qualification cycles that lock out competitors.
- Reusable dunnage programs:Automotive OEMs are piloting closed-loop tray pooling systems that convert single-use packaging into recurring service revenue.
- India FSSAI compliance push:Food safety modernization is displacing unorganized flexible packaging with thermoformed trays from organized converters.
Industry Challenges
- Thermoforming tool design expertise:Shortage of mold engineers who can optimize plug-assist geometry for thin-gauge PET is extending new product development timelines.
- Cleanroom certification delays:ISO 14644 Class 7 validation for medical packaging facilities stretches 18-24 months, blocking market entry for undercapitalized players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Thermoformed Packaging Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packaging, Clamshell Packaging, Skin Packaging, Tray Packaging Material: Plastic, Paperboard, Aluminum, Composite End User: Food & Beverages, Electronics, Pharmaceuticals, Consumer Goods Process Type: Forming, Sealing, Cutting, Printing |
| Companies Covered | Bardes Plastics, Reflex Packaging, Innovative Plastec, Tekni-Pac, Plastiform, Plaxall, Vantage Plastics, Nishihara Manufacturing, Shepherd Thermoforming and Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Thermoformed Packaging Market Strategic Shifts
Digital printing integration and AI-driven quality inspection are compressing batch minimums and defect rates simultaneously, enabling mass customization without sacrificing line speed economics.
Barrier-coated PET sheet is converging with high-speed form-fill-seal lines to displace multilayer structures in fresh protein packaging. Major US retailers are mandating store-dropoff recyclable trays by 2027, forcing converters to qualify new coating chemistries. The structural consequence is converging with mono-material design principles that simplify mechanical recycling streams.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from food-contact thermoforming. European converters are pivoting to clay-based and bio-based barrier coatings. Fresh bakery and ready-meal segments are absorbing the 8-12% cost premium to maintain regulatory compliance and shelf-life performance.
Brand procurement teams are consolidating supplier panels and demanding lifecycle carbon data alongside unit pricing. Electronics retailers now specify thermoformed clamshells with 30% post-consumer recycled content minimums. Germany and France are the primary geographies where sustainability scorecards outweigh pure cost optimization in packaging awards.
Vacuum Thermoformed Packaging Market Segmentation
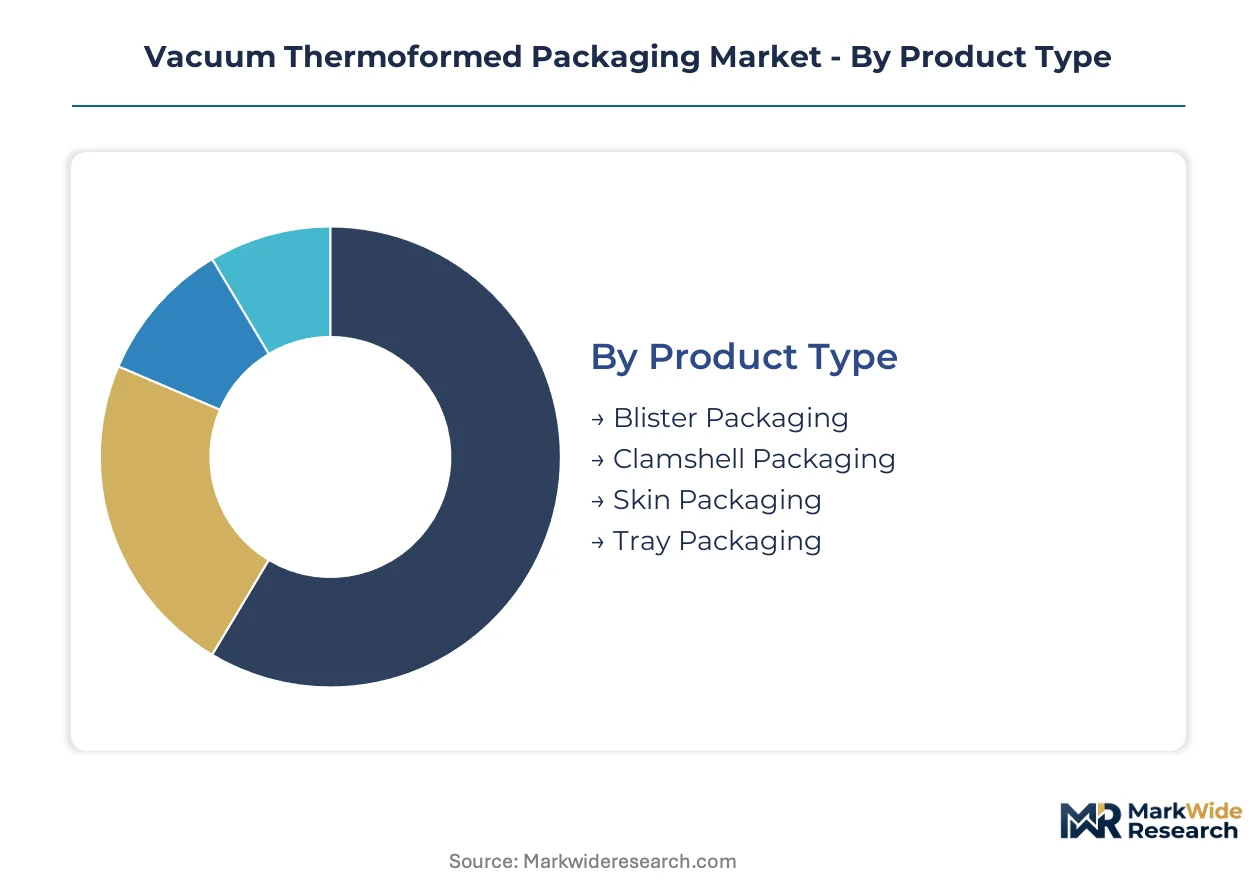
Vacuum thermoformed packaging serves distinct functional requirements across product protection, retail display, and sterile containment. Segment boundaries reflect divergent tooling investments, regulatory compliance burdens, and end-user specification intensity that reshape competitive positioning within each category.
Product Type:
Blister and clamshell formats operate as standalone retail-facing solutions, while skin and tray packaging embed into broader supply chain systems requiring line integration.
- Blister Packaging:Unit-dose cavities sealed to lidding foil dominate pharmaceutical dispensing where FDA 21 CFR 177 compliance and child-resistant features command premium positioning. Carded blister systems concentrate in North American over-the-counter drug retail.
- Clamshell Packaging:Hinged two-piece enclosures deliver anti-theft visibility for consumer electronics retail. German and French electronics retailers now mandate minimum post-consumer recycled content thresholds in clamshell awards.
- Skin Packaging:Film vacuum-sealed tightly around product contours serves industrial hardware and cutlery sets where reduced material usage offsets slower line speeds.
- Tray Packaging:Open-top containers for fresh protein and produce distribution represent the mature volume base where standardization drives line speed economics across automated form-fill-seal operations.
Tray packaging leads volumes today; clamshell packaging is gaining share fastest.
Material:
Substrate selection pivots on recyclability economics, barrier requirements, and thermoforming temperature windows that constrain converter equipment choices.
- Plastic:PET sheet consolidates position over polystyrene in food-contact applications due to superior clarity and mechanical recycling compatibility. EU Packaging and Packaging Waste Regulation mandates are accelerating mono-material PET transitions across European converters.
- Paperboard:Fiber-based substrates with thermoformable coatings capture sustainable packaging premiums in premium chocolate and cosmetics gift sets where rigidity and printability outweigh moisture sensitivity.
- Aluminum:Foil-laminated structures serve pharmaceutical cold-chain requirements where absolute moisture and light barrier properties justify cost premiums.
- Composite:Multi-layer structures combining plastic, foil, and paperboard persist in retortable medical trays despite mechanical recycling complexity.
Plastic dominates installed capacity; paperboard is expanding most quickly in premium segments.
End User:
Sector concentration varies by qualification intensity, with medical and pharmaceutical applications imposing multi-year validation cycles that lock out new entrants.
- Food & Beverages:Protein processors and fresh produce distributors drive standardized tray demand where modified atmosphere compatibility extends shelf life. German retail chains are piloting store-dropoff recyclable PET tray mandates.
- Electronics:Precision component shipping and retail display requirements sustain demand for anti-static and anti-theft packaging configurations around Stuttgart automotive electronics clusters.
- Pharmaceuticals:Sterile barrier packaging for surgical kits and implantables offers premium pricing with ISO 14644 Class 7 cleanroom certification requirements stretching 18-24 months.
- Consumer Goods:Cosmetics and personal care applications absorb custom tooling costs for distinctive shelf presence in fragmented brand portfolios.
Food & Beverages anchors volume; Pharmaceuticals commands highest margins.
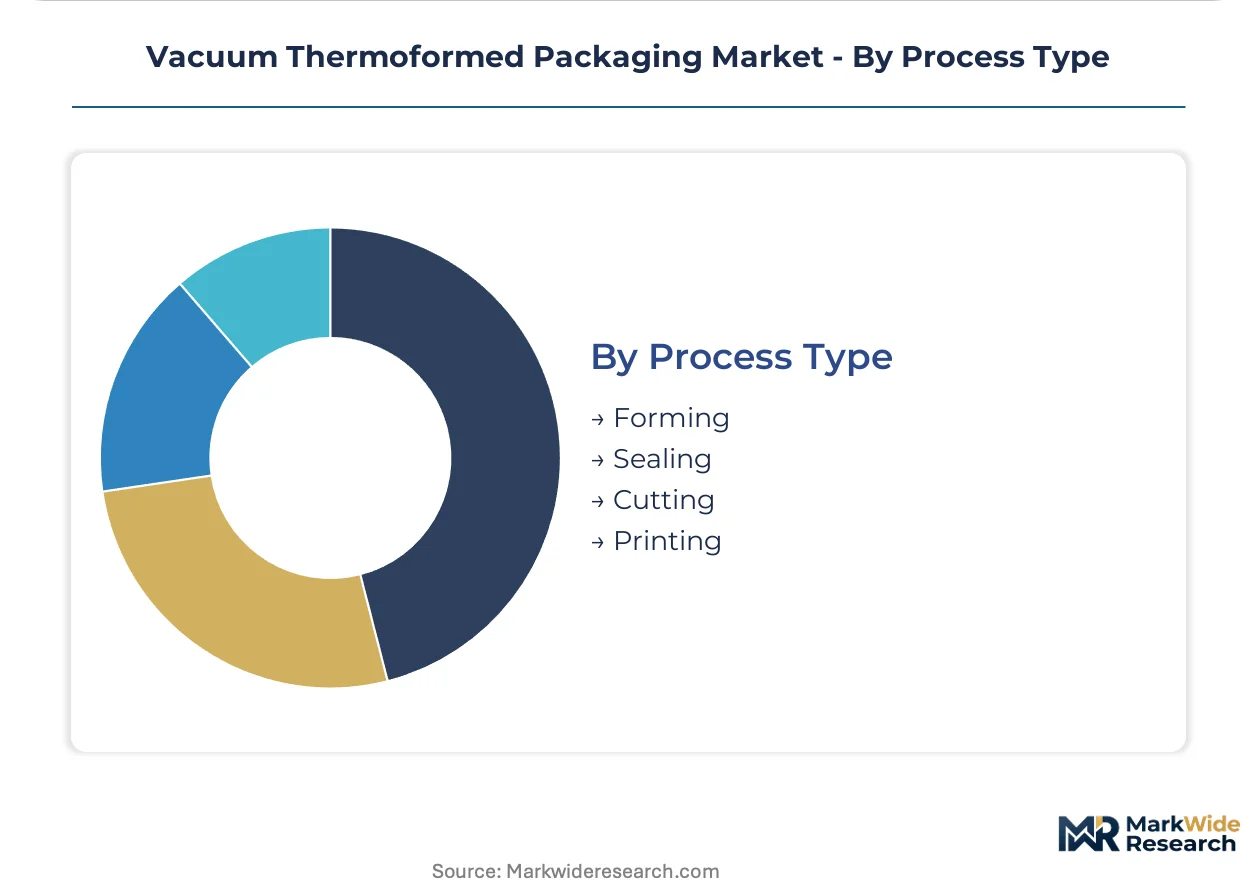
Process Type:
Process segmentation reflects capital equipment specialization and line integration depth across forming, downstream conversion, and decoration stages.
- Forming:Vacuum and pressure-forming stations represent the core thermoforming operation where plug-assist geometry optimization determines wall thickness distribution and material yield.
- Sealing:Heat-sealing and RF welding operations bond lidding materials to formed cavities, with pharmaceutical applications demanding validated seal strength distributions.
- Cutting:Steel-rule and matched-metal die cutting separate individual packages from continuous web, with registration precision critical for blister card alignment.
- Printing:Digital and flexographic decoration integrates branding and regulatory information, with digital compression of batch minimums enabling mass customization.
Forming captures the largest equipment footprint; digital printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electronics cluster around Stuttgart and Wolfsburg anchors European demand for precision thermoformed dunnage. Converter investments concentrate where regulatory pressure intersects with high-value manufacturing density.
Germany
Electric drivetrain component suppliers demand high-tolerance protective packaging for battery modules and power electronics. The EU Packaging and Packaging Waste Regulation accelerates converter transitions toward mono-material PET lines. Stuttgart's tier supplier ecosystem sustains premium thermoforming capacity for precision automotive dunnage.
United States
Protein processors and fresh produce distributors drive standardized tray demand across automated packaging lines. FDA 21 CFR 177 compliance requirements shape food-contact substrate selection. Midwest manufacturing corridors concentrate captive sheet extrusion capacity serving retail grocery chains.
China
Electronics manufacturing clusters generate substantial demand for anti-static clamshell and blister configurations. NMPA medical device regulations elevate cleanroom packaging standards for export-oriented producers. Yangtze River Delta converters scale barrier-coated PET capacity for pharmaceutical blister exports.
India
FSSAI compliance modernization displaces unorganized flexible packaging with thermoformed trays from organized converters. Food safety regulator mandates accelerate organized sector penetration. Maharashtra and Gujarat host emerging converter capacity serving domestic retail modernization.
France
Electronics retailers mandate minimum post-consumer recycled content thresholds in packaging procurement awards. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorochemical barrier treatments. Paris-region retail chains pilot store-dropoff recyclable tray collection systems.
Vacuum Thermoformed Packaging Market Competitive Environment
Global majors compete with regional champions across substrate technology and cleanroom certification tiers. The vendor base stratifies between integrated sheet extruders and specialized formers. Three archetypes dominate: captive extrusion-thermoforming hybrids, medical-grade cleanroom specialists, and automotive dunnage service providers. Competitive moves center on chemical recycling partnerships and reusable packaging program pilots.
Within the medical-grade tier, Innovative Plastec exemplifies cleanroom thermoforming capabilities. Among automotive-focused fabricators, Reflex Packaging occupies a position in reusable dunnage programs. Bardes Plastics represents captive sheet extrusion integration for resin cost control.
| Leading Market Players |
|---|
| Bardes Plastics |
| Reflex Packaging |
| Innovative Plastec |
| Tekni-Pac |
| Plastiform |
| Plaxall |
| Vantage Plastics |
| Nishihara Manufacturing |
| Shepherd Thermoforming and Packaging |
| Others |
Value Chain & Pricing Dynamics
PET resin feedstock costs cascade through three pricing tiers before reaching end-buyers, with sheet extrusion concentration in the US Midwest and Germany amplifying converter margin pressure during demand spikes. Annual fixed-price contracts between protein processors and tray suppliers absorb crude oil volatility unevenly, forcing smaller formers toward spot market exposure.
Pricing Analysis
Input-cost pass-through from virgin and recycled PET flake operates on quarterly adjustment clauses in European contracts, while North American agreements favor annual lock-ins. Price differentiation rests on ISO 14644 cleanroom certification grade and volume scale, with medical-grade thermoforming commanding substantial premiums over food-contact standard lines. Cost compression in commodity tray segments is intensifying because German retail chains now mandate lifecycle carbon data alongside unit pricing. Protein processors exhibit highest price sensitivity due to standardized tray specifications, whereas pharmaceutical OEMs prioritize qualification security over marginal cost.
Supply Chain Analysis
Logistics and freight costs from Middle Eastern resin producers to European sheet extruders have reconfigured sourcing patterns, with nitrogen-based physical foaming equipment adding capital-weighted distribution complexity. Supply concentrates in the United States, Germany, and China, with raw material dependencies spanning PET resin, polypropylene sheet, and barrier coating chemistries. Single-source vulnerability in North American sheet extrusion—where five major suppliers control capacity—creates bottleneck risk during seasonal demand surges. Distribution runs through direct converter-OEM relationships in automotive dunnage, while food packaging channels rely on distributor networks serving retail grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification intensity is concentrating procurement awards among qualified suppliers. The shift toward medical-grade cleanroom certification and post-consumer recycled content minimums favors incumbents with sunk validation investments.
For Market Incumbents: Extend certification moats by accelerating ISO 14644 Class 7 capacity additions in Germany and the US Midwest before qualification timelines lengthen further. Backward integration into captive sheet extrusion defends margin position against resin price volatility, while chemical recycling partnerships secure post-consumer feedstock access ahead of EU Packaging and Packaging Waste Regulation enforcement. The priority lever sits with reusable dunnage program pilots that convert single-use packaging into recurring service revenue. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for nitrogen-based physical foaming specialists to capture displaced hydrofluorocarbon capacity in foamed tray segments. Target India's FSSAI compliance modernization as the most penetrable geography, where organized converters displace unorganized flexible packaging in Maharashtra and Gujarat food retail. A go-to-market angle anchored in barrier-coated PET qualification for pharmaceutical blister exports bypasses entrenched food tray competition. For Investors and Strategic Acquirers: Roll-up economics work for medical-grade cleanroom specialists because ISO 14644 validation timelines create scarcity premiums that deter de novo entry. The 5-10 year viability window favors platforms consolidating fragmented automotive dunnage service providers around Stuttgart and Wolfsburg. The signal to watch is German OEM adoption of closed-loop tray pooling systems, which would revalue single-use packaging assets toward service-multiple valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Secures post-consumer PET feedstock access under EU Packaging and Packaging Waste Regulation mandates. |
| Cleanroom Capacity Expansion | Captures premium pricing in surgical kit packaging where ISO 14644 Class 7 certification blocks competitors. |
| Reusable Dunnage Program Launch | Converts single-use automotive packaging into recurring revenue with Stuttgart tier suppliers. |
| Barrier-Coated PET Qualification | Displaces multilayer structures in fresh protein packaging as retailers mandate store-dropoff recyclability. |
| Nitrogen Foaming Equipment Retooling | Complies with EU F-Gas Regulation restrictions while maintaining foamed tray production capability. |
Study Parameters
Coverage spans Germany, the United States, China, India, and France, with primary inputs from each market cluster combined with secondary validation. Interviews with thermoforming plant managers, procurement leads at protein processors and automotive tier suppliers, distribution channel partners, and medical device packaging engineers informed demand-side assumptions. Secondary sources included FDA 21 CFR 177 filings, EU Packaging and Packaging Waste Regulation impact assessments, SEC 10-K disclosures from packaging converters, and customs trade data on PET sheet imports. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated to cross-check volume outputs.
Rate-of-change decomposition across the analysis window separated volume growth into end-use expansion, material substitution effects, and regulatory displacement. Segmentation dimensions modeled include product type, material substrate, end-use sector, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy inflection points. Industry-specific forecast inputs incorporated EU F-Gas Regulation implementation timelines and India FSSAI compliance modernization trajectories.
Revisions become necessary when resin price volatility exceeds historical bands, cleanroom certification backlogs extend beyond 24 months, or German automotive production schedules shift materially. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Desiccant Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Fanfold Market
Packaging Materials
Global Liquid Packaging Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
China Packaging Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Textile Packaging Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Lubricant Packaging Market