
 Plastic Medicine Bottles Market | 2026-2036
Plastic Medicine Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Medicine Bottles Market Analytics
Pharmaceutical-grade barrier specifications is unwinding legacy commodity production across the plastic medicine bottles sector. Amcor plc leverages multilayer co-injection technology to sustain high-barrier product lines for moisture-sensitive formulations. Gerresheimer AG anchors European supply through specialized PET and COP polymer expertise. West Pharmaceutical Services differentiates via integrated closure-system design for biologic drug delivery.
Plastic medicine bottles are rigid pharmaceutical containers manufactured from polyethylene, polypropylene, PET, or PVC via injection blow molding or extrusion blow molding, designed to meet USP light transmission and moisture vapor transmission standards for drug stability. Their primary purpose is to protect dosage integrity from manufacturing through patient use while enabling compliant labeling and child-resistant functionality. Prescription bottles occupy the largest volume share due to chronic medication dispensing scale, while child-resistant bottles command premium positioning driven by Poison Prevention Packaging Act compliance requirements. Polypropylene segments are gaining fastest in parenteral and biologic applications where thermal stability and autoclave compatibility matter.
FDA enforces 16 CFR 1700 child-resistant packaging standards that directly determine closure design and material selection for oral prescription drugs. EMA's MDR and REACH frameworks govern material biocompatibility and chemical migration limits for European market access. India's CDSCO and BIS standards are tightening local manufacturing quality benchmarks as domestic pharmaceutical output expands. Stakeholders must monitor evolving dual-carbon regulations and recycled-content mandates that will reshape material sourcing decisions and capital allocation across the supply base.
Market Dynamics
Multilayer co-injection barrier technology is compressing legacy single-layer production economics across pharmaceutical packaging, forcing capital retooling decisions at commodity converters.
Growth Catalysts
- Poison Prevention Packaging Act enforcement:FDA 16 CFR 1700 mandates child-resistant closures for oral prescription drugs, sustaining premium demand for certified closure systems.
- Biologics manufacturing expansion:Parenteral drug producers require polypropylene bottles with autoclave stability, displacing glass in cold-chain applications.
- India CDSCO quality tightening:Domestic pharmaceutical output scaling drives compliant packaging demand from local bottle converters.
Market Restraints
- Resin input volatility:Polypropylene and PET feedstock prices track naphtha and paraxylene, compressing converter margins during upstream shocks.
- Closure-system supply concentration:Child-resistant mechanism production clusters among specialized European and North American molders, creating single-source risk.
- Glass substitution persistence:High-value biologics and orphan drugs retain glass vial preference where oxygen ingress tolerance approaches zero.
Strategic Opportunities
- China domestic pharma growth:NMPA manufacturing scale-up creates demand for locally produced compliant bottles with China-specific labeling.
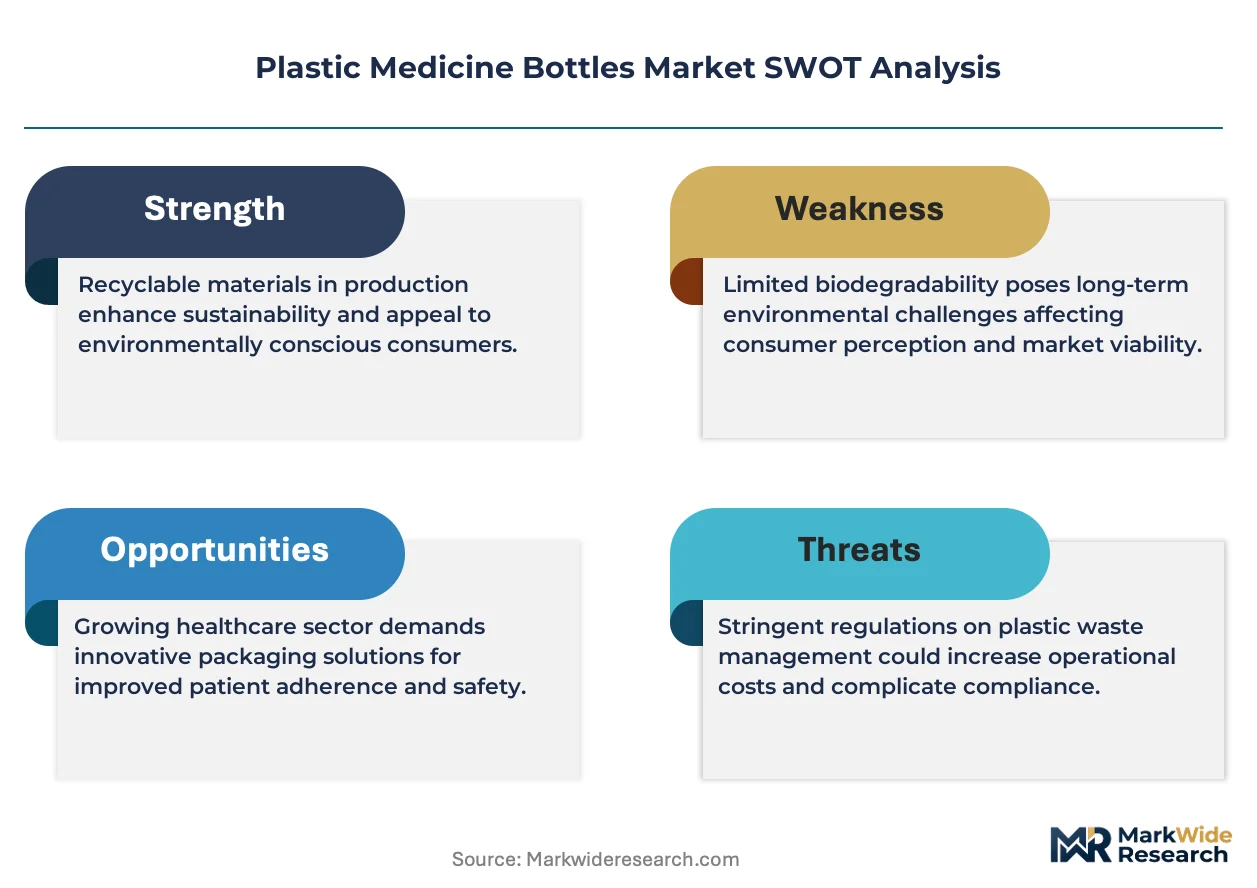
- Recycled-content mandates:EU Green Deal packaging regulations and state-level recycled resin floors create first-mover positioning for rPET-qualified producers.
- Integrated digital printing:Direct-to-object serialization enables unit-level traceability, converging packaging with track-and-trace compliance infrastructure.
Industry Challenges
- Multilayer co-injection technician scarcity:Barrier technology operation requires specialized process engineering talent concentrated among legacy pharmaceutical molders.
- Validation timeline compression:FDA and EMA stability testing protocols extend new product qualification cycles, delaying revenue from format innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Medicine Bottles Market |
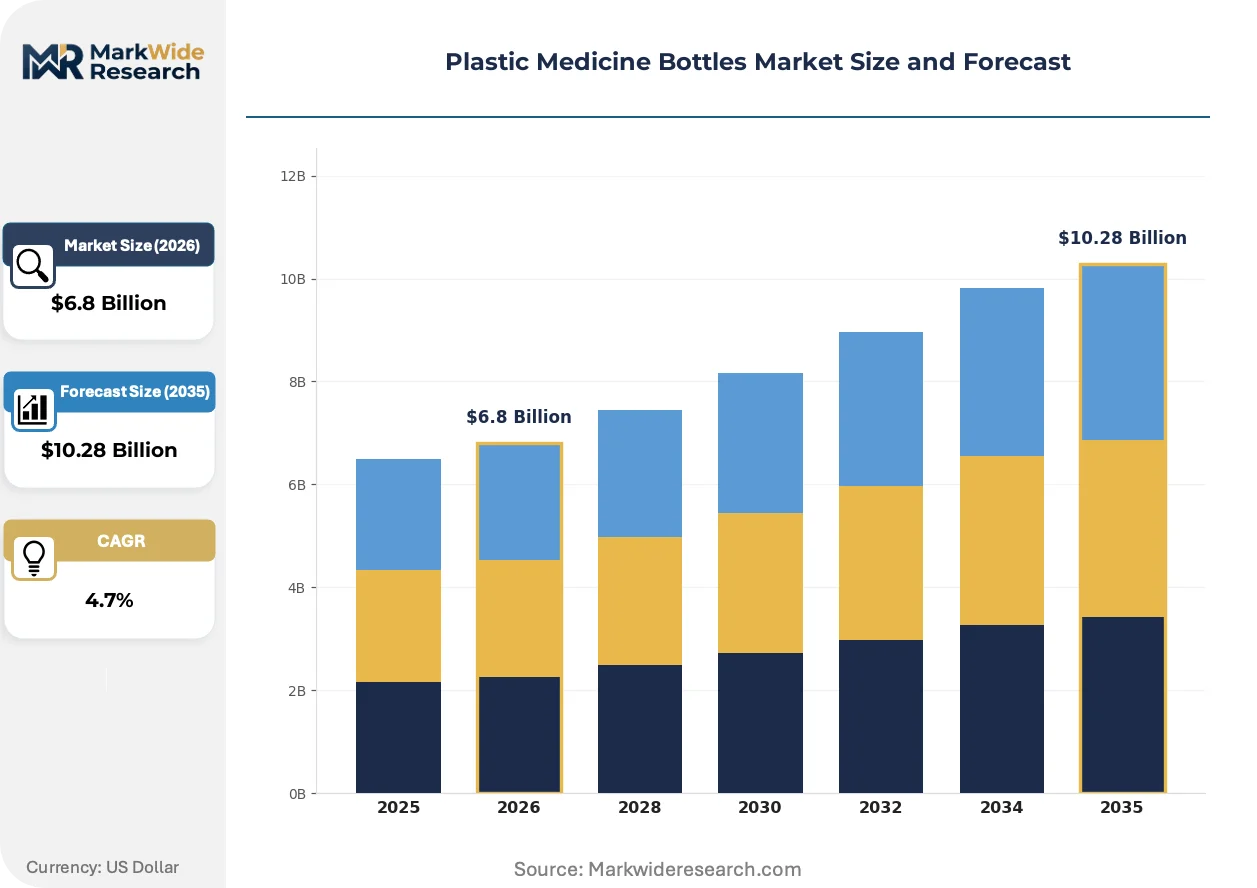
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Bottles, Over-the-Counter Bottles, Child-Resistant Bottles, Non-Child-Resistant Bottles Material: Polyethylene, Polypropylene, PVC, PET Cap Type: Screw Caps, Flip Caps, Dropper Caps, Pump Dispenser Caps End User: Pharmacies, Hospitals, Clinics, Home Healthcare |
| Companies Covered | O.Berk Company LLC, West Pharmaceutical Services, Amcor plc, Drug Plastics Group, Alpla Group, Gerresheimer AG, Alpha Packaging, Inc., Becton Dickinson, AptarGroup, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Medicine Bottles Market Evolving Landscape
Barrier architecture evolution and regulatory serialization mandates are restructuring production economics and competitive differentiation across pharmaceutical packaging converters.
Multilayer co-injection systems combining EVOH or nylon oxygen barriers within polypropylene or PET matrices are miniaturizing the performance gap between rigid plastic and glass containers. Chronic disease drug manufacturers are adopting these systems for moisture-sensitive oral solids previously reserved for glass. The technology is compressing total cost of ownership calculations and enabling plastic conversion in premium therapeutic categories.
EMA's Medical Device Regulation and REACH chemical migration limits are tightening material biocompatibility documentation requirements for European market access. Converter qualification costs are rising for polymer additives and colorants. High-barrier prescription bottle segments are responding with dedicated regulatory affairs functions and third-party testing partnerships.
Hospital system procurement consolidation is centralizing packaging specification authority at integrated delivery network headquarters. Regional distributors and group purchasing organizations are losing influence over bottle format decisions. This concentration is most visible in United States health system contracting, where standardization committees now mandate child-resistant compliance across all affiliated pharmacies.
Plastic Medicine Bottles Market Segmentation
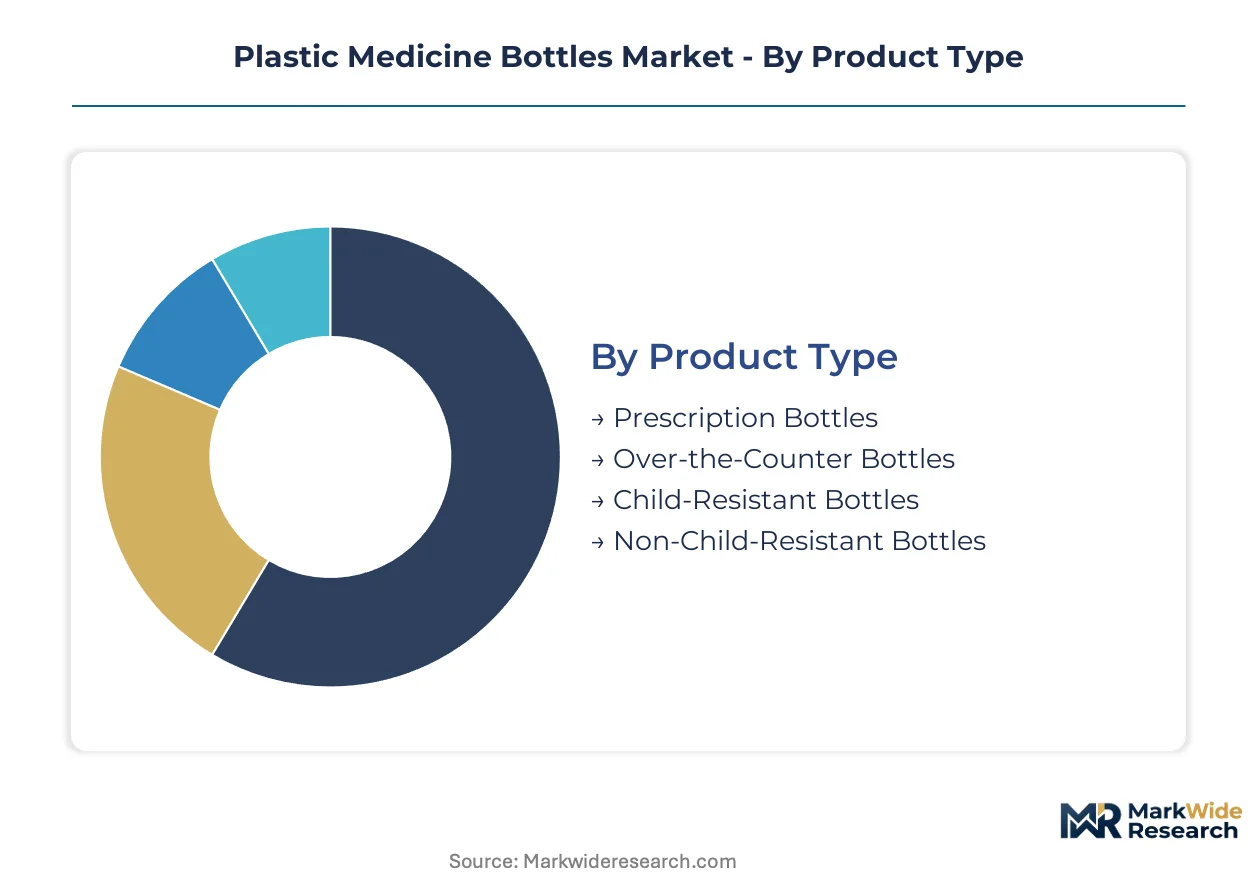
Segmentation in plastic medicine bottles reflects divergent regulatory burdens and performance specifications across therapeutic categories. Material selection and closure architecture determine compliance positioning, while end-user channel dictates volume scale and customization intensity.
Product Type:
Premium margin pools concentrate in certified child-resistant formats where Poison Prevention Packaging Act compliance creates supply scarcity and pricing power.
- Prescription Bottles:Standard cylindrical HDPE or PP containers with 13- to 60-dram capacities, engineered for USP light transmission and moisture vapor transmission compliance. Demand concentrates in United States retail pharmacy chains where CVS Health and Walgreens centralize procurement specifications. Chronic disease medication dispensing scale sustains volume leadership despite generic pricing pressure.
- Child-Resistant Bottles:Specialized containers integrating push-and-turn or squeeze-and-turn closures certified to 16 CFR 1700 protocols. Demand clusters in pediatric and geriatric therapeutic categories where accidental ingestion liability drives specification stringency. FDA enforcement sustains double-digit price premiums over non-compliant alternatives.
- Over-the-Counter Bottles:Lower-specification containers for analgesics, cough-cold, and digestive health products where shelf visibility and label adhesion matter more than barrier performance. Volume scales through mass retail and convenience channels.
- Non-Child-Resistant Bottles:Basic containers for adult-only medications and institutional dispensing where compliance exemptions apply. Price compression is severe due to commodity converter competition.
The dominant share belongs to Prescription Bottles, while Child-Resistant Bottles is closing the gap fastest.
Material:
Cost tier stratification separates commodity polyethylene from engineering-grade polypropylene where thermal stability commands application-specific premiums.
- Polypropylene:Semi-crystalline thermoplastic with 160°C melting point and autoclave sterilization compatibility, enabling parenteral and biologic drug containment. Demand is accelerating in cold-chain applications where thermal cycling resistance displaces glass. European biologics manufacturers anchor premium uptake.
- PET:Amorphous polyester with exceptional clarity and oxygen barrier properties when combined with multilayer co-injection architecture. Moisture-sensitive oral solid formulations in Germany and Switzerland drive high-barrier specification adoption.
- Polyethylene:Low-density and high-density grades dominate high-volume oral solid dispensing where cost minimization outweighs barrier performance. Indian domestic pharmaceutical production scales LDPE bottle demand.
- PVC:Rigid vinyl with chemical resistance for specific liquid formulations, though REACH migration limits constrain European application scope.
Polyethylene retains volume leadership across mass-market oral solids, while Polypropylene is expanding most quickly in parenteral conversion.
Cap Type:
Application-driven specification splits compliance-certified closures from convenience-oriented formats in retail and institutional channels.
- Screw Caps:Threaded polypropylene closures with induction seal capability, forming the baseline for prescription bottle integrity. United States 503B compounding pharmacies standardize on 38mm child-resistant screw specifications.
- Flip Caps:Hinged polyolefin designs enabling single-hand dispensing for arthritis patients and elderly users. OTC analgesic and vitamin segments in Japan favor this format.
- Dropper Caps:Integrated bulb-and-tip assemblies for ophthalmic and pediatric liquid formulations. Precision dosing requirements sustain specialized molding investment.
- Pump Dispenser Caps:Metered-dose mechanisms for topical and nasal applications where viscosity and dose accuracy determine design complexity.
Screw Caps command the largest installed base, though Flip Caps is gaining share fastest in aging-population markets.
End User:
Customer type determines order fragmentation, with hospital system consolidation contrasting against dispersed retail pharmacy procurement.
- Pharmacies:Retail and mail-order dispensaries purchasing standardized bottle formats at scale. United States integrated delivery networks now mandate child-resistant compliance across all affiliated outpatient pharmacies.
- Hospitals:Inpatient and emergency department dispensing requiring unit-dose and multi-dose formats with barcode serialization. China tertiary hospital expansion drives compliant packaging demand.
- Clinics:Outpatient and specialty care settings with moderate volume and format variety requirements. India's Ayushman Bharat health centers create distributed demand.
- Home Healthcare:Long-term care and patient-directed medication management where compliance packaging and patient education labeling intersect.
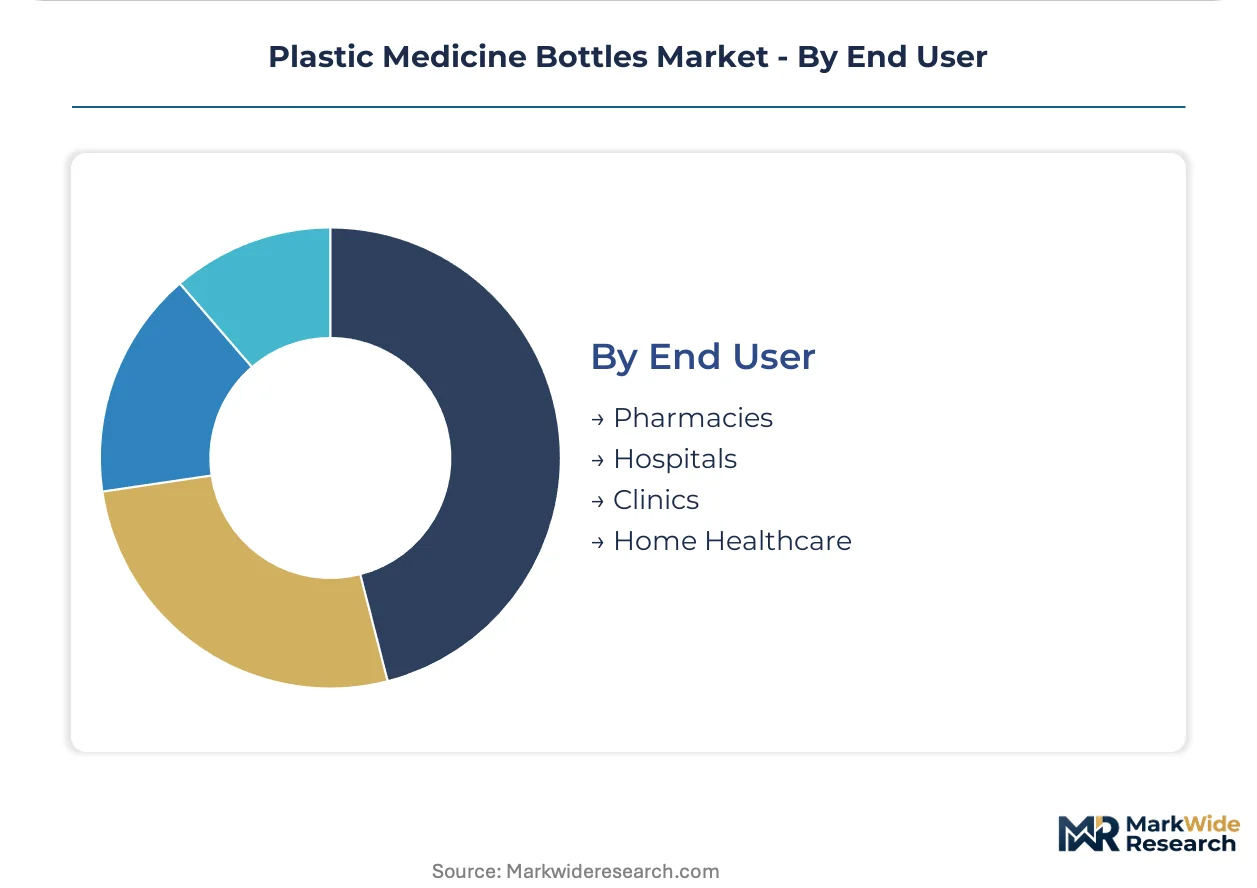
Pharmacies dominate current volume, while Hospitals is climbing the fastest on inpatient biologics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United States, India, China, and Switzerland, with each geography shaping distinct regulatory and demand environments for pharmaceutical-grade packaging.
United States
CVS Health and Walgreens procurement consolidation drives standardized child-resistant specifications across retail pharmacy networks. FDA 16 CFR 1700 enforcement sustains premium closure-system demand. New Jersey and Pennsylvania host specialized molders serving 503B compounding pharmacies.
Germany
Biologics manufacturers in Baden-Württemberg require polypropylene bottles with autoclave stability for parenteral applications. EMA MDR and REACH frameworks govern material biocompatibility documentation. The Rhine-Main cluster anchors European high-barrier prescription bottle supply.
India
Domestic pharmaceutical output scaling under CDSCO quality tightening creates compliant packaging demand from local converters. BIS standards are elevating manufacturing quality benchmarks. Gujarat and Maharashtra bottle producers supply chronic disease medication programs.
China
NMPA manufacturing scale-up generates demand for locally produced bottles with China-specific labeling requirements. Tertiary hospital expansion drives inpatient biologics packaging need. Yangtze River Delta converters serve domestic pharma growth.
Switzerland
Moisture-sensitive oral solid formulations in Basel and Zurich drive multilayer co-injection barrier adoption. Swissmedic regulations align with EMA frameworks for European market access. The Lake Geneva region concentrates specialized PET and COP polymer expertise.
Plastic Medicine Bottles Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized pharmaceutical converters. Tier-one players command high-barrier segments through regulatory qualification depth, while regional fabricators compete on volume scale for standard prescription formats. Two strategic archetypes dominate: integrated closure-system designers and multilayer barrier technology specialists. Competitive moves center on M&A for regulatory asset accumulation and capacity expansion in India and China.
Among the diversified packaging conglomerates, Amcor plc and Gerresheimer AG exemplify scale-driven archetypes with European regulatory depth. West Pharmaceutical Services occupies a position within the integrated closure-system tier. O.Berk Company LLC represents North American specialized converter positioning. These three anchors illustrate how geographic regulatory alignment and technology specialization stratify competitive positioning across premium and volume segments.
| Leading Market Players |
|---|
| O.Berk Company LLC |
| West Pharmaceutical Services |
| Amcor plc |
| Drug Plastics Group |
| Alpla Group |
| Gerresheimer AG |
| Alpha Packaging, Inc. |
| Becton Dickinson |
| AptarGroup, Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day resin hedging cycles in polypropylene and PET feedstock markets concentrate pricing power among converters with captive polymer supply or long-term offtake agreements, while spot-market dependent fabricators absorb margin compression during naphtha price spikes. FDA 16 CFR 1700 certification requirements for child-resistant closure systems create supply scarcity that sustains double-digit premiums over non-compliant alternatives, with Poison Prevention Packaging Act enforcement tightening the link between regulatory qualification depth and pricing tier access.
Pricing Analysis
FDA 16 CFR 1700 dictates the pricing tier structure across plastic medicine bottles, separating certified child-resistant formats from commodity prescription containers. Three-tier pricing structure across premium, standard, and economy levels reflects closure-system certification status, multilayer barrier performance, and volume scale. Cost compression in standard prescription formats is intensifying because Indian and Chinese domestic converters are scaling HDPE production for chronic disease medication programs. Retail pharmacy chains exhibit highest price sensitivity due to procurement consolidation, while biologics manufacturers show lowest sensitivity where autoclave-compatible polypropylene commands application-specific premiums.
Supply Chain Analysis
Rotterdam-Antwerp chemical corridor transit underwrites European pharmaceutical-grade resin distribution, with congestion or regulatory delays propagating through converter inventory positions. Supply concentrates in Germany, the United States, and India, with polypropylene and PET feedstock drawing from naphtha crackers in the Rhine-Main cluster and Gulf Coast petrochemical complexes. Single-source vulnerability sits with specialized European and North American molders controlling child-resistant mechanism production. Distribution runs through integrated delivery network headquarters in United States health systems and tertiary hospital procurement offices in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multilayer co-injection barrier technology is accelerating plastic-to-glass substitution in moisture-sensitive oral solids, with EMA MDR and REACH frameworks tightening material biocompatibility documentation requirements that favor converters with established regulatory affairs infrastructure.
For Market Incumbents: Compound barrier technology capabilities through selective acquisition of specialized European molders with EVOH co-injection expertise, as technician scarcity constrains organic capability buildup. Expand polypropylene autoclave-stable capacity in Baden-Württemberg to capture biologics cold-chain conversion from glass. Defend against Indian and Chinese domestic converter scaling by deepening FDA and EMA qualification moats. For New Entrants and Emerging Players: Lead with integrated digital printing and unit-level serialization capabilities targeting United States 503B compounding pharmacies, where track-and-trace compliance infrastructure convergence creates specification entry points. China's NMPA manufacturing scale-up presents the most penetrable geography for locally produced bottles with China-specific labeling. Position through direct hospital system contracting relationships rather than distributor channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core pharmaceutical assets, particularly European converters with stranded multilayer co-injection capacity. Long-term viability favors specialists with dual FDA-EMA qualification depth and captive closure-system design capabilities. Monitor EU Green Deal recycled-content mandate implementation as inflection indicator for rPET-qualified producer positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Co-Injection Capacity Expansion | Captures moisture-sensitive oral solid formulations previously reserved for glass in German and Swiss markets. |
| Backward Integration into Polymer Compounding | Secures pharmaceutical-grade resin supply against naphtha price volatility for Rhine-Main converters. |
| Integrated Closure-System Acquisition | Eliminates single-source risk from specialized European molders serving FDA 16 CFR 1700 compliance. |
| Digital Printing and Serialization Partnership | Enables unit-level traceability convergence with EMA track-and-trace infrastructure requirements. |
| rPET Qualification Investment | Positions for EU Green Deal recycled-content mandates ahead of state-level resin floor implementations. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging procurement managers, multilayer co-injection process engineers, regulatory affairs directors at European biologics manufacturers, and hospital system formulary committee members anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 16 CFR 1700 certification databases, EMA MDR submission records, CDSCO manufacturing quality circulars, and BIS pharmaceutical packaging standards. Customs data from Indian and Chinese resin import flows, SEC 10-K disclosures from diversified packaging conglomerates, and trade association production statistics completed the source triangulation. Bottom-up capacity and demand modeling reconciled against top-down market sizing.
Sensitivity analysis across resin price scenarios, regulatory timeline compressions, and biologics manufacturing expansion rates tested forecast robustness. Segmentation modeling incorporated product type, material grade, closure-system certification tier, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from trend extrapolation of chronic disease medication dispensing volumes, biologics cold-chain conversion rates, and domestic pharmaceutical production scaling in India and China. Multilayer barrier technology adoption curves and child-resistant packaging mandate enforcement intensity served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA enforcement intensity, stable naphtha-to-resin conversion economics, and continued biologics manufacturing expansion would require recalibration. Forecasts reflect documented assumptions regarding technician availability for barrier technology operation and validation timeline norms. Practitioners should keep alternative scenarios live as EU Green Deal recycled-content mandates and India CDSCO quality tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Polyethylene Mailers Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market