
 White Sack Kraft Paper Market | 2026-2036
White Sack Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
White Sack Kraft Paper Market Analytics
Aftermarket technical service revenue is reconfiguring margin capture across the White Sack Kraft Paper value chain. Mondi Group leverages its integrated pulp-to-paper network across Central European mills to sustain cost-advantaged supply. WestRock Company anchors North American demand through containerboard co-location and specialty converting assets. Smurfit Kappa competes via pan-European recycling infrastructure that secures consistent furnish for high-strength sack grades.
White Sack Kraft Paper denotes an unbleached, long-fiber kraft paper typically manufactured at 70–120 GSM basis weight with tear indices exceeding 350 mN, engineered primarily for multi-wall valve and open-mouth sacks carrying dry bulk goods. Roll Paper dominates converter procurement due to inline printing and gusseting efficiency, while Special Paper commands premium positioning through grease-resistant and moisture-barrier functionalization. Agricultural Packaging represents the fastest-growing end-use as grain and fertilizer exporters specify higher ply adhesion and printability standards.
The EU Green Deal and F-Gas Regulation constrain fluorinated barrier chemistries, redirecting R&D toward bio-based coatings that preserve recyclability streams. FDA food-contact standards in the United States and BIS packaging norms in India create divergent compliance pathways that segment export-qualified capacity from domestic-grade output. Stakeholders must monitor pulp futures volatility and regulatory timing on extended producer responsibility schemes to calibrate capacity commitments.
Market Dynamics
REACH compliance costs and fluorinated barrier phase-outs are compressing converter margins while redirecting capital toward bio-based coating R&D and virgin pulp certification infrastructure.
Growth Catalysts
- EU Green Deal packaging mandates:Extended producer responsibility schemes in Germany and France accelerate demand for recyclable multi-wall sacks in agricultural commodity exports.
- Infrastructure investment intensity:Cement and construction material packaging specifications across India and Southeast Asia specify higher tear-index kraft grades for valve sack applications.
- Moisture-resistant barrier innovation:Bio-based coating technologies enable sack converters to meet FDA food-contact standards without sacrificing fiber recyclability streams.
Market Restraints
- Pulp futures volatility:Softwood long-fiber furnish price swings constrain margin predictability for non-integrated converters dependent on spot market procurement.
- Fluorinated chemistry substitution timeline:F-Gas Regulation phase-out deadlines create technical gaps as mills await scaled bio-barrier alternatives with equivalent grease resistance.
- Regional supply concentration:Central European integrated pulp-to-paper networks capture disproportionate cost advantages versus merchant market dependent competitors.
Strategic Opportunities
- Indian agricultural export corridor:BIS packaging norm compliance investments position domestic mills to capture grain and fertilizer sack demand from Middle East and African buyers.
- Specialty converting channel expansion:Inline gusseting and flexographic printing capabilities at regional converter hubs reduce logistics costs for mid-volume cement customers.
- Carbon border adjustment alignment:EU CBAM preparatory phase creates first-mover advantage for mills with verified Scope 3 emissions data and chain-of-custody certification.
Industry Challenges
- Bio-coating formulation expertise scarcity:Polymer chemistry and paper science cross-training gaps delay pilot-to-production scaling for moisture-barrier grades.
- Multi-jurisdiction certification timelines:Parallel FDA, EFSA, and BIS food-contact approval processes extend product launch cycles for export-qualified sack lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Sack Kraft Paper Market |
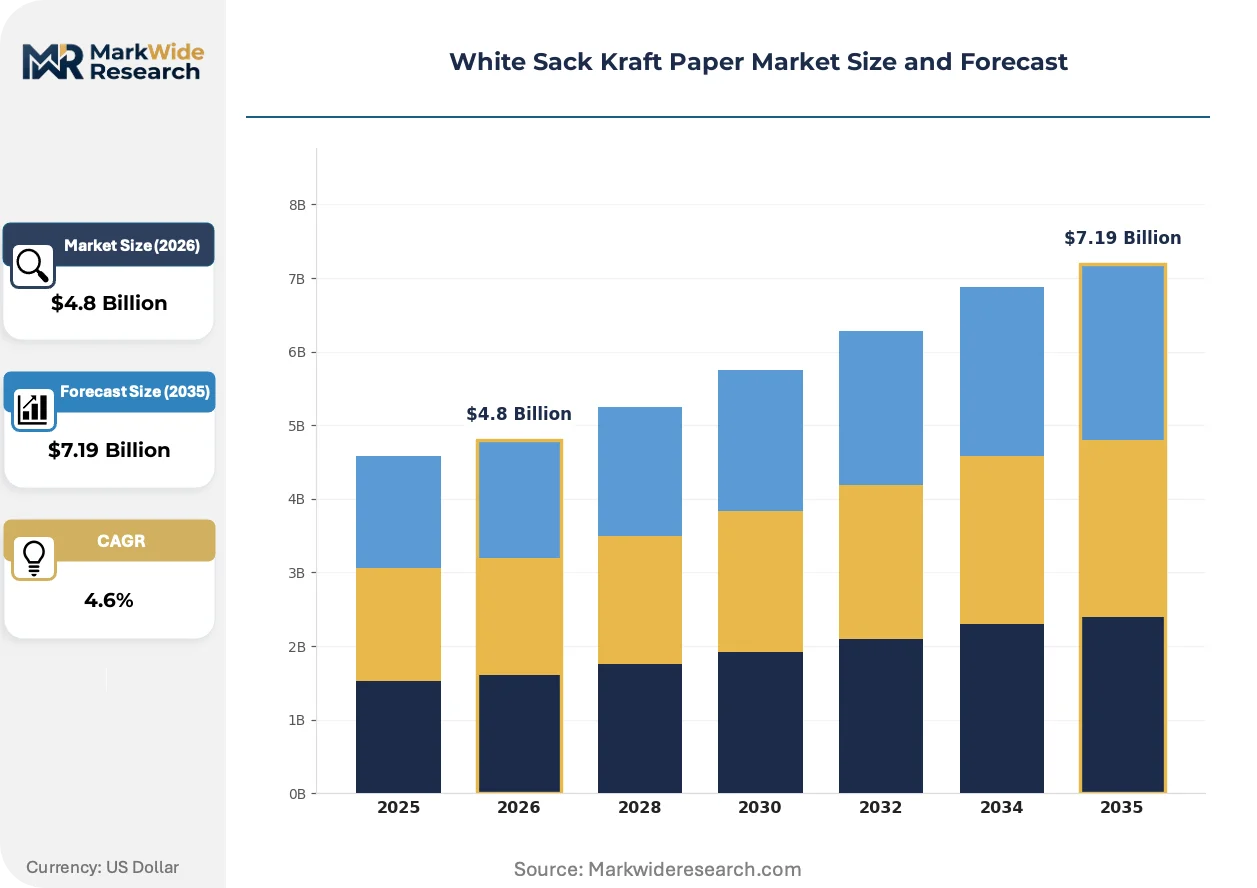
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Paper, Roll Paper, Special Paper, Coated Paper End Use: Industrial Packaging, Food Packaging, Retail Packaging, Agricultural Packaging Thickness: 30 GSM, 40 GSM, 50 GSM, 60 GSM Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | Mondi Group, WestRock Company, International Paper Company, Smurfit Kappa, Segezha Group, BillerudKorsnäs, Nordic Paper, Canfor Corporation, Gascogne Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Sack Kraft Paper Market Evolving Landscape
Barrier coating chemistry and inline converting automation are compressing traditional sack manufacturing economics while creating new competitive moats around integrated technical service capabilities.
Water-based polymer barrier coatings with oxygen transmission rates below 5 cc/m²/day are rendering obsolete conventional polyethylene-laminated kraft constructions in grain and pet food packaging. North American agricultural cooperatives specify these grades for 25-kg valve sacks requiring extended shelf stability. The shift is rendering obsolete regional converters without pilot coater investment or toll-coating partnerships.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force European mills to accelerate bio-based fluorine-free alternatives for grease-resistant applications. ECHA substance evaluation timelines compress formulation validation windows to 18-month cycles. Specialty food packaging converters in Italy and Spain are qualifying cellulose nanofibril-reinforced coatings ahead of 2025 enforcement milestones.
Direct mill-to-converter digital procurement platforms are fragmenting traditional distributor intermediation in sack-grade roll paper supply. Large cement and fertilizer compounders in Brazil and Turkey now contract basis-weight-specific production runs with guaranteed tear-index minimums. This channel compression is most visible in Mediterranean basin markets where logistics costs previously favored regional stock-and-distributor models.
White Sack Kraft Paper Market Segmentation
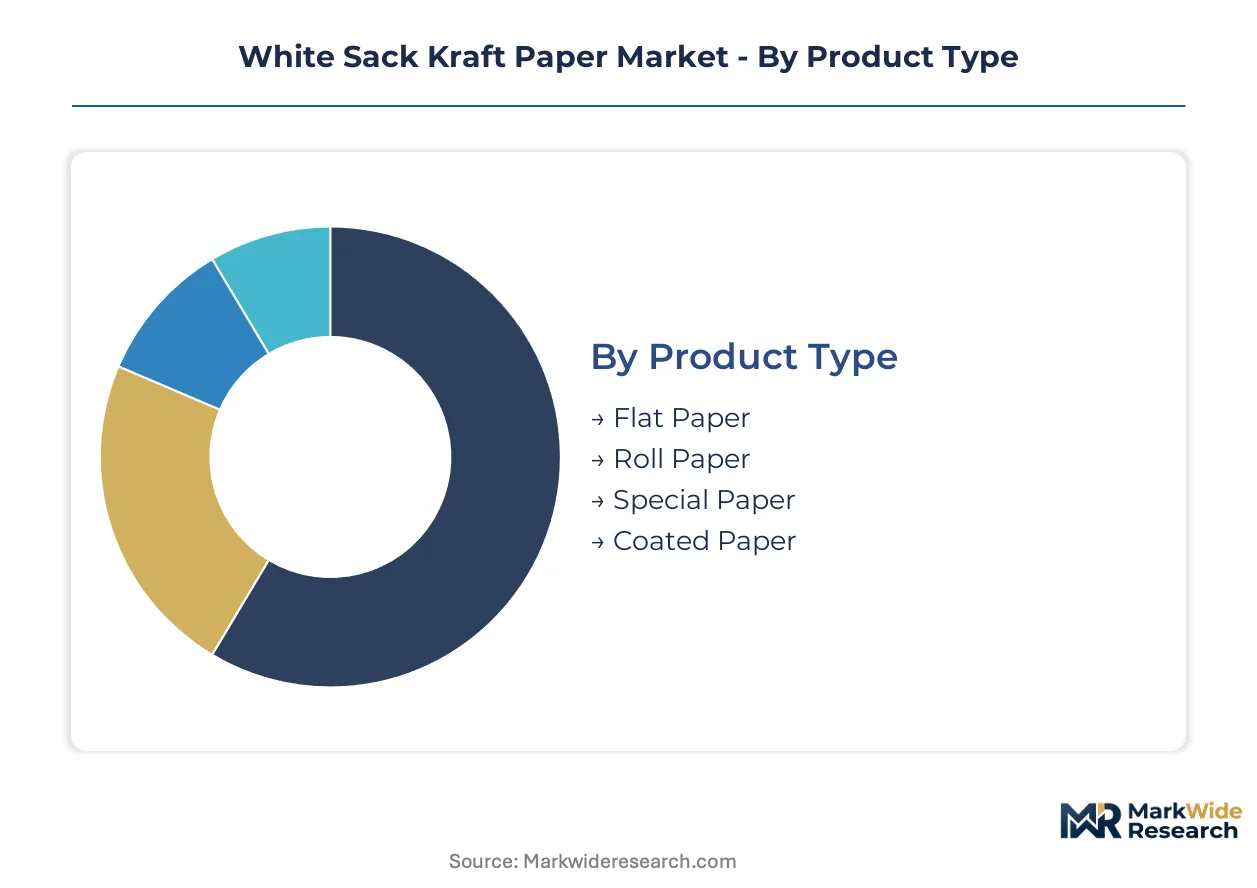
White Sack Kraft Paper demand fragments across distinct technical specifications and procurement channels, each carrying different margin profiles and aftermarket service intensity. Converter relationships and barrier coating customization separate premium-grade supply from commodity interchangeability.
Product Type:
After-sales technical support intensity varies sharply across product formats, with specialty grades requiring formulation troubleshooting and coating performance validation.
- Roll Paper:Supplied in continuous reels optimized for inline flexographic printing and automated gusseting at converter facilities. Demand concentrates among cement and fertilizer compounders in India and Turkey where direct mill contracts specify tear-index minimums and basis-weight tolerances for valve sack production.
- Special Paper:Functionalized with bio-based moisture barriers and grease-resistant coatings meeting FDA food-contact standards. Agricultural cooperatives in North America specify these grades for 25-kg grain sacks requiring extended shelf stability without sacrificing fiber recyclability streams.
- Flat Paper:Sheet-format supply for small-batch converters and specialty bag manufacturers with limited roll-handling equipment.
- Coated Paper:Pre-treated substrates with water-based polymer barriers achieving oxygen transmission rates below 5 cc/m²/day for pet food and chemical packaging.
Roll Paper holds the largest share; momentum sits with Special Paper as bio-barrier innovation displaces polyethylene-laminated constructions.
End Use:
Application-driven specification divergence creates distinct certification and compliance pathways across customer segments.
- Agricultural Packaging:The fastest-growing trajectory as grain and fertilizer exporters in India specify higher ply adhesion and printability standards for Middle East and African buyers. BIS packaging norm compliance investments position domestic mills to capture this corridor.
- Industrial Packaging:Cement and construction material specifications across India and Southeast Asia demand tear indices exceeding 350 mN for valve sack applications handling abrasive dry bulk.
- Food Packaging:Requires parallel FDA, EFSA, and BIS food-contact approvals extending product launch cycles for export-qualified sack lines.
- Retail Packaging:Lower-specification grades for consumer-facing carrier bags and lightweight merchandise sacks with minimal barrier requirements.
Industrial Packaging anchors volume; Agricultural Packaging climbs the fastest as infrastructure investment intensifies commodity export flows.
Thickness:
Basis weight selection directly correlates with sack ply count and load-bearing requirements across end-use applications.
- 70-120 GSM:Standard range for multi-wall valve and open-mouth sacks carrying dry bulk goods, manufactured with unbleached long-fiber kraft pulp.
- 30 GSM:Lightweight interleaving and protective wrapping applications with minimal structural demands.
- 40 GSM:Single-ply retail bags and secondary packaging where tear resistance is secondary to printability.
- 50 GSM:Mid-weight grades for two-ply agricultural sacks balancing cost and performance.
- 60 GSM:Heavy-duty industrial applications requiring enhanced puncture resistance.
Standard 70-120 GSM grades dominate procurement; lighter weights gain share fastest in retail substitution scenarios.
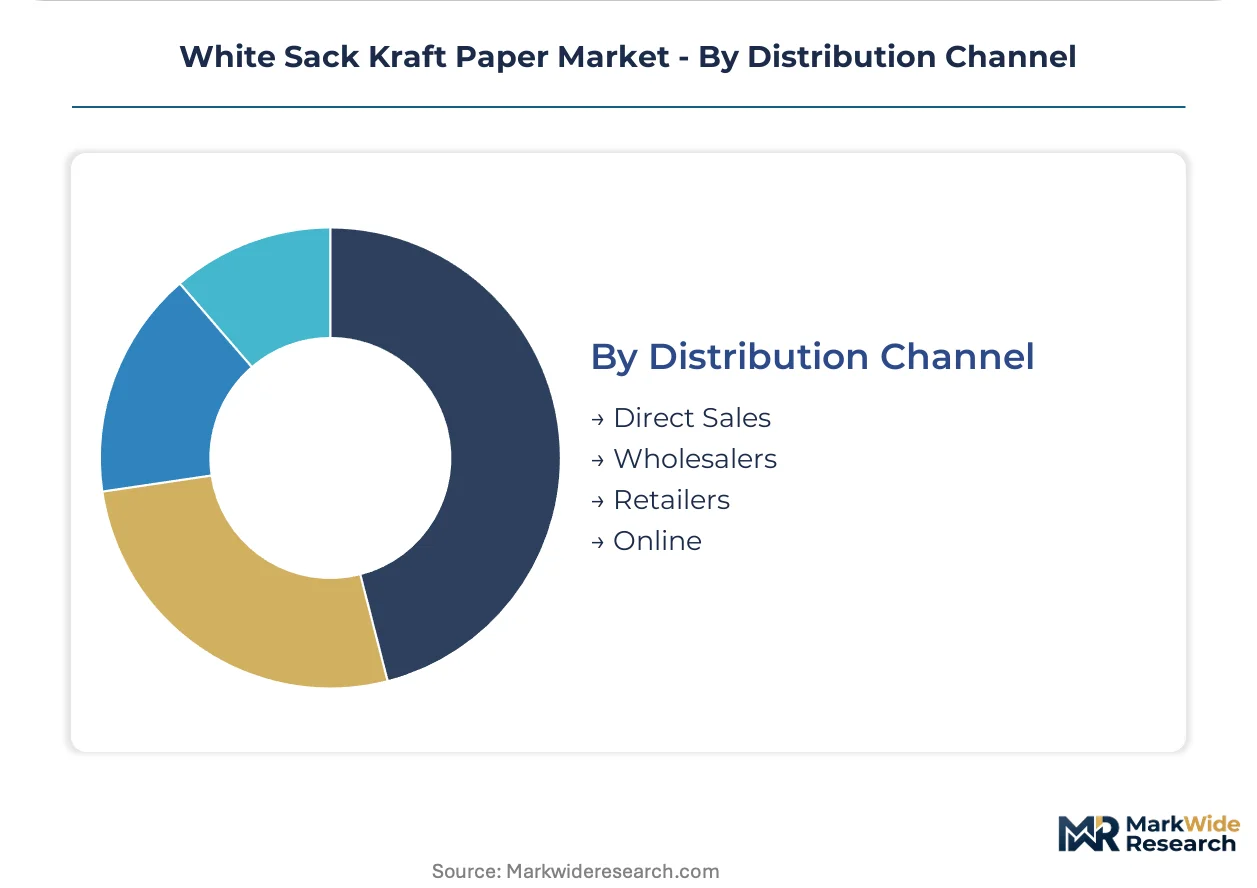
Distribution Channel:
Channel economics shift as direct digital procurement fragments traditional distributor intermediation in sack-grade roll paper supply.
- Direct Sales:Large compounders in Brazil and Turkey now contract basis-weight-specific production runs with guaranteed tear-index minimums, compressing regional stock-and-distributor models.
- Wholesalers:Maintain inventory positions for mid-volume converters lacking storage infrastructure or credit facilities for mill-direct purchasing.
- Retailers:Small-lot supply to artisanal bag makers and specialty packaging shops with irregular demand patterns.
- Online:Emerging platform for specification comparison and sample procurement, though bulk roll logistics limit penetration.
Direct Sales captures the largest volume; Online channels show steepest expansion trajectory as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian cement compounders exhibit the highest price elasticity as infrastructure tenders squeeze packaging budgets, while North American agricultural cooperatives absorb premium bio-barrier grades with minimal volume sensitivity.
India
Cement and fertilizer valve sack specifications from infrastructure contractors drive 70-120 GSM grade procurement at scale. BIS packaging norms mandate tear-index minimums and ply adhesion standards for agricultural commodity exports to Middle Eastern buyers. Gujarat and Maharashtra host concentrated converter clusters where direct mill contracts displace traditional distributor channels.
Germany
REACH Annex XVII enforcement on fluorinated substances redirects R&D spending toward cellulose nanofibril-reinforced grease-resistant coatings. The EU Green Deal's extended producer responsibility schemes accelerate recyclable multi-wall sack qualification for grain exporters. Bavarian specialty converters pilot bio-based barrier grades ahead of 2025 ECHA substance evaluation milestones.
United States
FDA food-contact standards for moisture-resistant grain sacks push agricultural cooperatives toward water-based polymer barrier coatings with oxygen transmission rates below 5 cc/m²/day. The EPA maintains oversight of coating chemistry migration limits in pet food packaging applications. Midwestern containerboard co-location hubs integrate inline gusseting and flexographic printing for regional cement customers.
Brazil
Large fertilizer compounders contract basis-weight-specific production runs through direct digital procurement platforms, fragmenting regional stock-and-distributor models. ANVISA regulates food-contact barrier coatings for agricultural export packaging. São Paulo state anchors converter capacity serving Mercosur grain trade corridors with tear-index-specified valve sack production.
Turkey
Cement packaging demand from Black Sea and Mediterranean infrastructure projects specifies higher tear-index kraft grades for abrasive dry bulk handling. The country's national standards body enforces packaging material safety for agricultural exports to Central Asian markets. Izmir and Mersin port zones concentrate converter facilities qualifying for EU CBAM preparatory phase carbon border documentation.
White Sack Kraft Paper Market Competitive Landscape
Capability concentration sits with integrated pulp-to-paper networks; scale advantage sits with containerboard co-location specialists. The market structures around three tiers: Central European integrated mills with virgin pulp certification, North American containerboard converters with specialty assets, and regional merchant-dependent players exposed to spot furnish volatility. Dominant competitive moves include backward integration into pulp supply and capacity expansion in high-tear-index grades for Indian infrastructure demand.
Within the integrated tier, Mondi Group and Smurfit Kappa exemplify archetypes of cost-advantaged supply through captive pulp networks. WestRock Company occupies a position among North American scale players leveraging containerboard infrastructure for regional converter proximity. These three entities anchor the competitive map without exhaustively representing all strategic variants in the space.
| Leading Market Players |
|---|
| Mondi Group |
| WestRock Company |
| International Paper Company |
| Smurfit Kappa |
| Segezha Group |
| BillerudKorsnäs |
| Nordic Paper |
| Canfor Corporation |
| Gascogne Group |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors set the baseline for European kraft paper delivered cost, concentrating margin capture among integrated mills with captive pulp supply while forcing merchant-dependent converters into spot-price vulnerability. This logistics-cost asymmetry feeds directly into three-tier pricing stratification across premium certified grades, standard industrial specifications, and economy-level domestic output.
Pricing Analysis
After-sales technical service contracts anchor lifetime value capture for specialty-grade suppliers, with formulation troubleshooting and barrier performance validation extending revenue streams beyond substrate delivery. Three-tier pricing structure across premium certified, standard specification, and economy domestic levels reflects certification tier and volume scale differentiation. Cost compression in economy grades is intensifying as Indian infrastructure tenders squeeze packaging budgets. Cement compounders in India exhibit the highest price elasticity, while North American agricultural cooperatives absorb premium bio-barrier grades with minimal volume sensitivity.
Supply Chain Analysis
Central European integrated mills in Germany, Austria, and the Czech Republic hold disproportionate cost-advantaged capacity through captive softwood pulp networks. Long-fiber kraft pulp, bio-based barrier chemistries, and virgin pulp certification infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in Nordic long-fiber furnish streams subject to weather-driven harvest disruptions. Distribution runs through direct mill-to-converter digital platforms that displace regional stock-and-distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White Sack Kraft Paper sits in early-cycle expansion as infrastructure investment across India and Southeast Asia accelerates cement packaging specifications toward higher tear-index grades. Bio-barrier innovation cycles and regulatory phase-out deadlines compress adoption timelines for compliant suppliers.
For Market Incumbents: Pre-empt bio-coating formulation expertise scarcity by acquiring polymer chemistry talent pools ahead of scaled production ramp. Defend margin position through backward integration into virgin pulp certification infrastructure that secures REACH-compliant supply chains. Channel control via direct digital procurement platforms locks out distributor-dependent competitors.
For New Entrants and Emerging Players: Mid-volume agricultural sack converters in Brazil and Turkey lacking inline gusseting capabilities represent the most penetrable entry point for toll-coating partnerships and technical service bundling. Specialty food packaging segments in Italy and Spain awaiting cellulose nanofibril-reinforced coating qualification offer second-mover advantage. Go-to-market execution should anchor on pilot coater investment with guaranteed tear-index minimums.
For Investors and Strategic Acquirers: Regional merchant-dependent players with spot-market pulp exposure and limited barrier R&D pipelines present consolidation targets as margin compression intensifies. Long-term viability over the five-to-ten year window hinges on EU CBAM alignment and verified Scope 3 emissions documentation. Monitor ECHA substance evaluation timelines for bio-barrier approval inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Pulp Supply | Captive long-fiber furnish secures cost advantages against spot-market volatility in Nordic supply streams. |
| Bio-Based Barrier Coating Scale-Up | Fluorine-free formulations meeting FDA food-contact standards unlock agricultural export corridor premiums. |
| Direct Digital Procurement Platform Deployment | Mill-to-converter contracts with guaranteed tear-index minimums displace regional distributor intermediation. |
| EU CBAM Emissions Documentation Investment | Verified Scope 3 data and chain-of-custody certification create first-mover advantage in carbon border adjustment alignment. |
| Inline Converting Capability Expansion | Flexographic printing and automated gusseting at regional hubs reduce logistics costs for mid-volume cement customers. |
Research Methodology
Initial hypotheses were tested against primary input from mill operations directors, sack converter procurement leads, agricultural cooperative supply managers, and barrier coating R&D specialists and refined through secondary validation. Trade data from pulp futures exchanges, ECHA substance evaluation filings, BIS packaging norm registrations, and customs export records anchored supply-side quantification. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product format, end-use application, basis weight tier, and distribution channel. CAGRs derived from weighted average of historical trajectory and forward-looking capacity commissioning schedules incorporated pulp price elasticity coefficients and regulatory enforcement timelines as industry-specific inputs.
Practitioners should monitor ECHA substance evaluation milestones, BIS norm revision cycles, and EU CBAM implementation phases for early signals of forecast revision triggers. Quarterly review of pulp futures volatility indices and extended producer responsibility scheme rollout timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market