
 Packaging Jars Market | 2026-2036
Packaging Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Jars Market Outlook
Germany's specialized glassworks corridor is narrowing the supply gap for pharmaceutical-grade borosilicate jars. Ball Corporation leverages its North American metal packaging network to serve craft beverage producers seeking aluminum jar alternatives. Owens-Illinois sustains capacity leadership in amber glass through furnace investments in Italy and France. Ardagh Group competes across both glass and metal jar formats, giving buyers multi-material sourcing flexibility.
Packaging jars are rigid containers manufactured from glass, plastic, metal, or bio-based substrates, typically featuring threaded necks for secure closure attachment and wall thicknesses calibrated for content protection, chemical resistance, or thermal stability. Their primary purpose spans containment, preservation, shelf-life extension, and brand differentiation across consumer and industrial supply chains. Glass jars command premium positioning in cosmetics and pharmaceuticals where inertness and UV-blocking properties justify higher unit economics. Plastic jars dominate food and household segments where weight reduction and shatter resistance drive procurement decisions. Bio-based jars represent the fastest-expanding product type as EU REACH compliance pressures and brand sustainability commitments redirect R&D spending from conventional polymers.
FDA regulations governing pharmaceutical primary packaging, EU REACH restrictions on substance migration, and ISO 15378 standards for medicinal products collectively elevate barrier performance requirements and documentation burdens for jar suppliers. These frameworks disadvantage smaller converters lacking in-house testing infrastructure while rewarding manufacturers with certified quality management systems. Stakeholders must monitor how evolving extended producer responsibility schemes in multiple jurisdictions reshape cost allocation between jar producers and their brand customers.
Market Dynamics
EU REACH substance restrictions and recycled content mandates under the Packaging and Packaging Waste Regulation are compressing formulation flexibility for jar converters while accelerating material substitution toward bio-based substrates.
Growth Catalysts
- Pharmaceutical-grade borosilicate demand:Germany's Rhine-Main corridor concentrates specialized glassworks near chemical and pharmaceutical buyers, creating dense supplier-buyer networks that shorten qualification timelines.
- REACH compliance pressures:Migration limits on conventional polymers redirect R&D spending toward certified bio-based alternatives, opening procurement channels for converters with in-house testing infrastructure.
- Aluminum jar alternatives:Craft beverage producers seeking weight reduction and recyclability credentials are specifying metal formats for premium positioning.
Market Restraints
- Energy cost volatility:Glass furnace operations face input cost swings tied to natural gas pricing, compressing margin buffers for mid-scale converters in Italy and France.
- Supply concentration risk:Amber glass capacity leadership consolidates among furnace operators with captive silica sand access, limiting second-source options for pharmaceutical buyers.
- Regulatory friction:ISO 15378 certification timelines and FDA pharmaceutical primary packaging documentation burdens disadvantage smaller converters lacking dedicated quality management systems.
Strategic Opportunities
- South Korea cosmetics premiumization:Skincare serums are specifying heavier-wall glass jars with UV-blocking properties, opening volume for European borosilicate exporters.
- Extended producer responsibility schemes:Cost allocation shifts between jar producers and brand customers create service-revenue potential for converters offering closed-loop collection infrastructure.
- Digital printing convergence:Direct-to-shape decoration technology eliminates label substrates, enabling batch-size reduction and personalization for niche cosmetic launches.
Industry Challenges
- Certification timeline compression:Pharmaceutical buyers demand simultaneous FDA and EMA qualification, stretching regulatory affairs capacity at mid-tier converters.
- Legacy furnace reconfiguration:Amber-to-clear glass transitions require extended downtime and refractory replacement, constraining responsiveness to demand mix shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Jars Market |
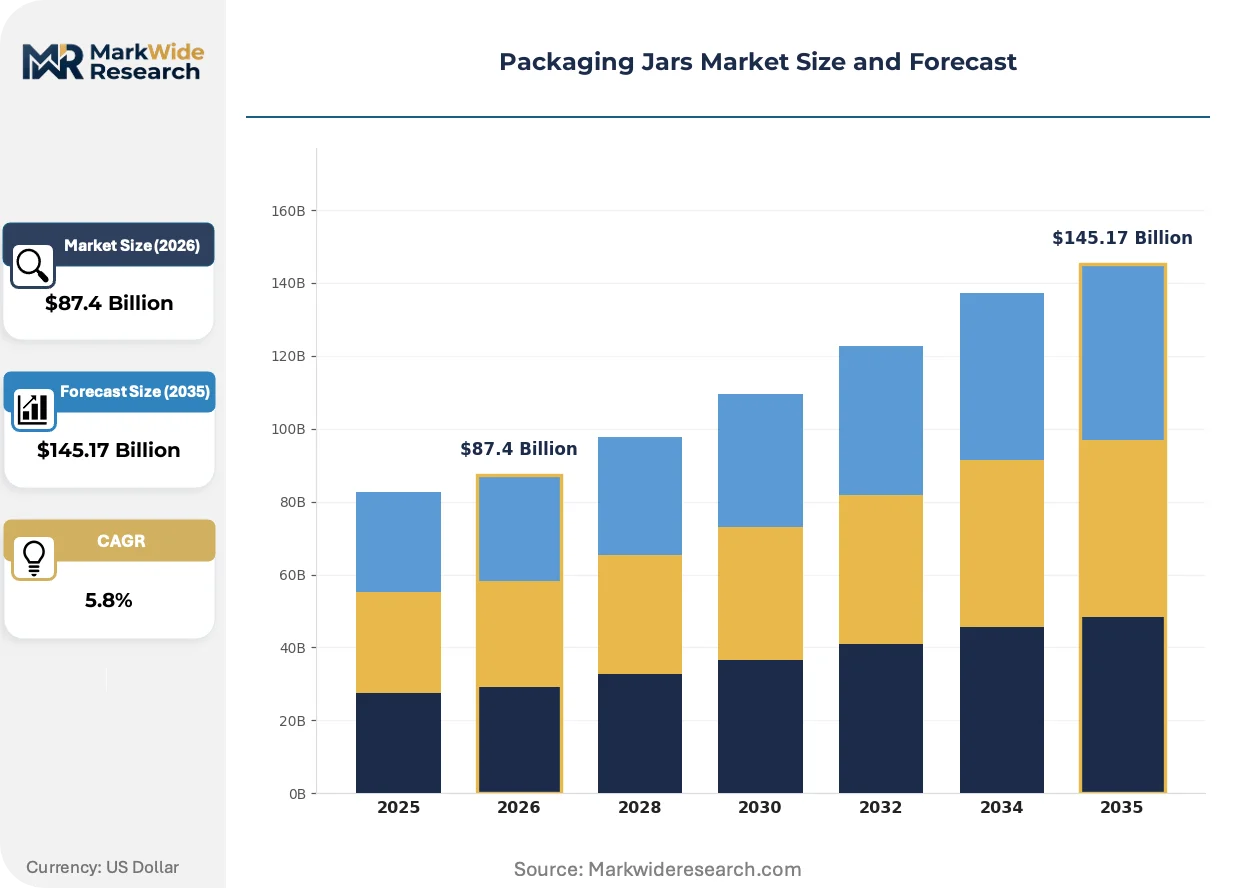
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Jars, Glass Jars, Metal Jars, Bio-Based Jars Closure Type: Screw Caps, Snap Caps, Corks, Flip Tops End Use: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Design Style: Standard, Custom Shapes, Printed, Embossed |
| Companies Covered | Ball Corporation, Owens-Illinois, Ardagh Group, Verallia, Berlin Packaging, Anchor Hocking, Silgan Holdings, Vidrala, Stoelzle Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Jars Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are jointly rewriting substrate selection criteria across food, cosmetic, and pharmaceutical packaging tiers.
Mono-material polyethylene terephthalate jars with integrated threaded closures are migrating from food condiment applications into cosmetic sampling formats. Mid-tier skincare brands are piloting these formats for travel-size serums. This migration is compressing decoration complexity as in-mold labeling replaces applied sleeves.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are tightening barrier coating options for plastic jar formats. Industrial gas suppliers are reformulating plasma-enhanced chemical vapor deposition processes. Pharmaceutical primary packaging in Germany and France faces accelerated qualification requirements for alternative barrier technologies.
Brand sustainability commitments are shortening supplier qualification cycles for bio-based and post-consumer recycled content. Major cosmetic houses are consolidating procurement around converters with mass-balance certification. South Korea's MFDS is tightening documentation requirements for recycled content claims in skincare packaging.
Packaging Jars Market Segmentation
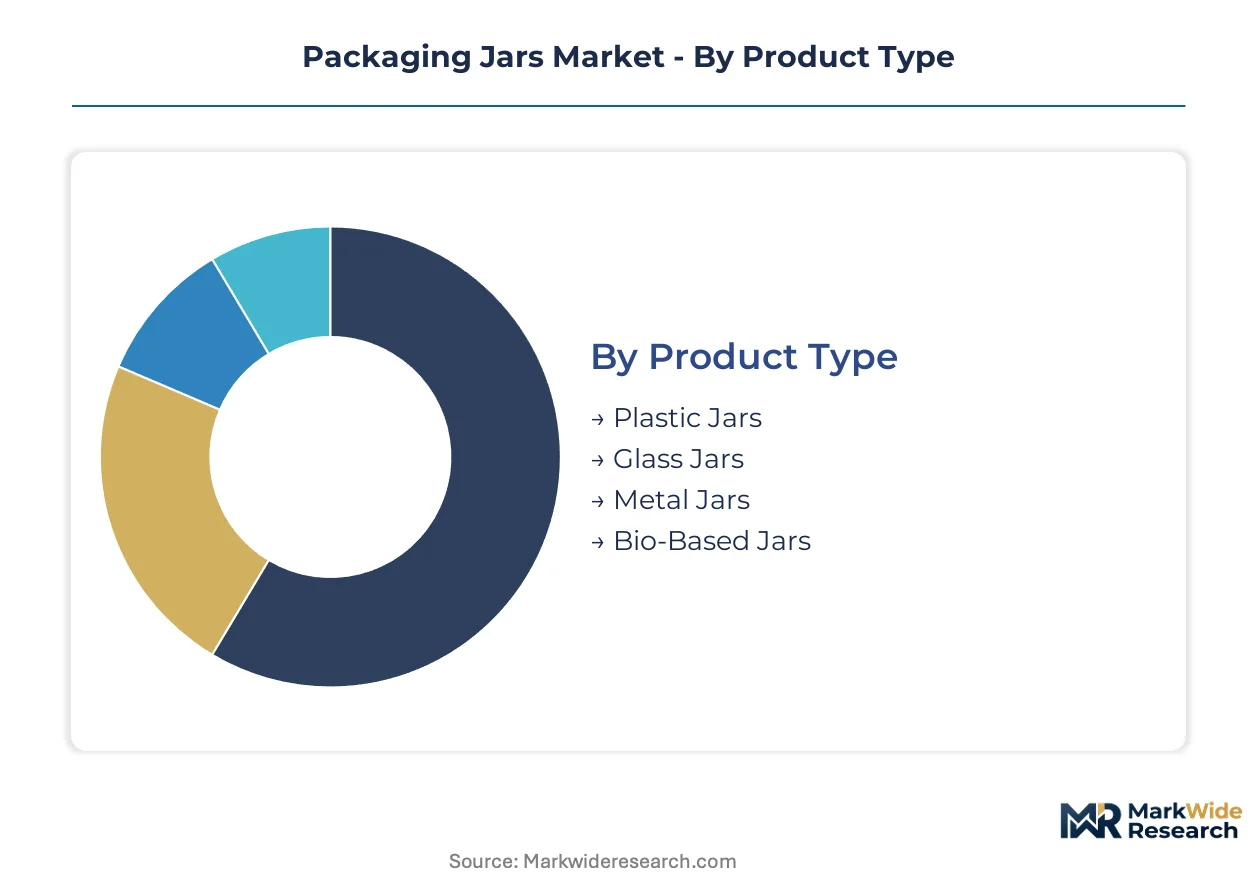
Packaging jar procurement decisions cascade through four interconnected dimensions. Product substrate determines barrier performance and regulatory compliance pathways. Closure mechanics, end-use specifications, and design customization each create distinct supplier qualification requirements and margin profiles.
Product Type:
Mature formats dominate current volume while emerging substrates reshape investment priorities across converter R&D programs.
- Plastic Jars:Polypropylene and polyethylene terephthalate formats offer weight reduction and shatter resistance for food condiment and household chemical applications. Demand concentrates in North American retail private label programs where distribution economics favor lightweight formats. REACH migration limits on conventional polymers are accelerating substitution toward certified bio-based alternatives.
- Glass Jars:Soda-lime and borosilicate compositions deliver inertness and UV-blocking properties for pharmaceutical and premium cosmetic applications. Germany's Rhine-Main corridor concentrates specialized glassworks near chemical and pharmaceutical buyers, creating dense supplier-buyer networks. Furnace energy costs tied to natural gas pricing compress margin buffers for mid-scale European converters.
- Metal Jars:Aluminum and tinplate formats serve craft beverage producers seeking recyclability credentials and weight reduction for premium positioning.
- Bio-Based Jars:Polylactic acid and cellulose-derived substrates are expanding fastest as EU Packaging and Packaging Waste Regulation recycled content mandates redirect procurement specifications.
Glass handles the majority of throughput in premium tiers; bio-based formats are gaining share fastest as brand sustainability commitments harden.
Closure Type:
Application requirements and consumer convenience expectations divide this category across tamper-evidence, resealability, and dispensing functionality.
- Screw Caps:Threaded polypropylene and metal closures provide hermetic seals for pharmaceutical primary packaging and long-shelf-life food applications. ISO 15378 certification requirements elevate supplier documentation burdens, disadvantaging smaller converters lacking dedicated quality management systems.
- Flip Tops:Hinged polyolefin closures enable single-handed dispensing for household and personal care applications where convenience drives repeat purchase.
- Snap Caps:Press-fit polyethylene closures offer cost-efficient sealing for dry goods and sampling formats with shorter consumption cycles.
- Corks:Natural and synthetic stopper formats persist in premium beverage and cosmetic positioning where ritual unsealing enhances brand experience.
Screw caps anchor pharmaceutical and food safety applications; flip tops are climbing fastest as personal care brands prioritize dispensing ergonomics.
End Use:
Regulatory intensity and performance specifications create four distinct procurement ecosystems with divergent qualification timelines.
- Food & Beverage:Barrier properties and migration compliance dominate substrate selection for condiments, preserves, and ready-to-drink formats. FDA food contact notification requirements and EU framework regulation on food contact materials govern supplier documentation.
- Pharmaceuticals:Borosilicate glass and certified polymers must satisfy FDA pharmaceutical primary packaging standards and EMA quality guidelines. Simultaneous dual-market qualification stretches regulatory affairs capacity at mid-tier converters.
- Cosmetics:South Korean skincare brands are specifying heavier-wall glass jars with UV-blocking properties, opening volume for European borosilicate exporters.
- Household Products:Chemical resistance and child-resistant closure compatibility drive polypropylene jar specifications for cleaning and laundry applications.
Food and beverage generates the highest unit volumes; cosmetics is expanding most quickly as premium skincare serums specify pharmaceutical-grade packaging.
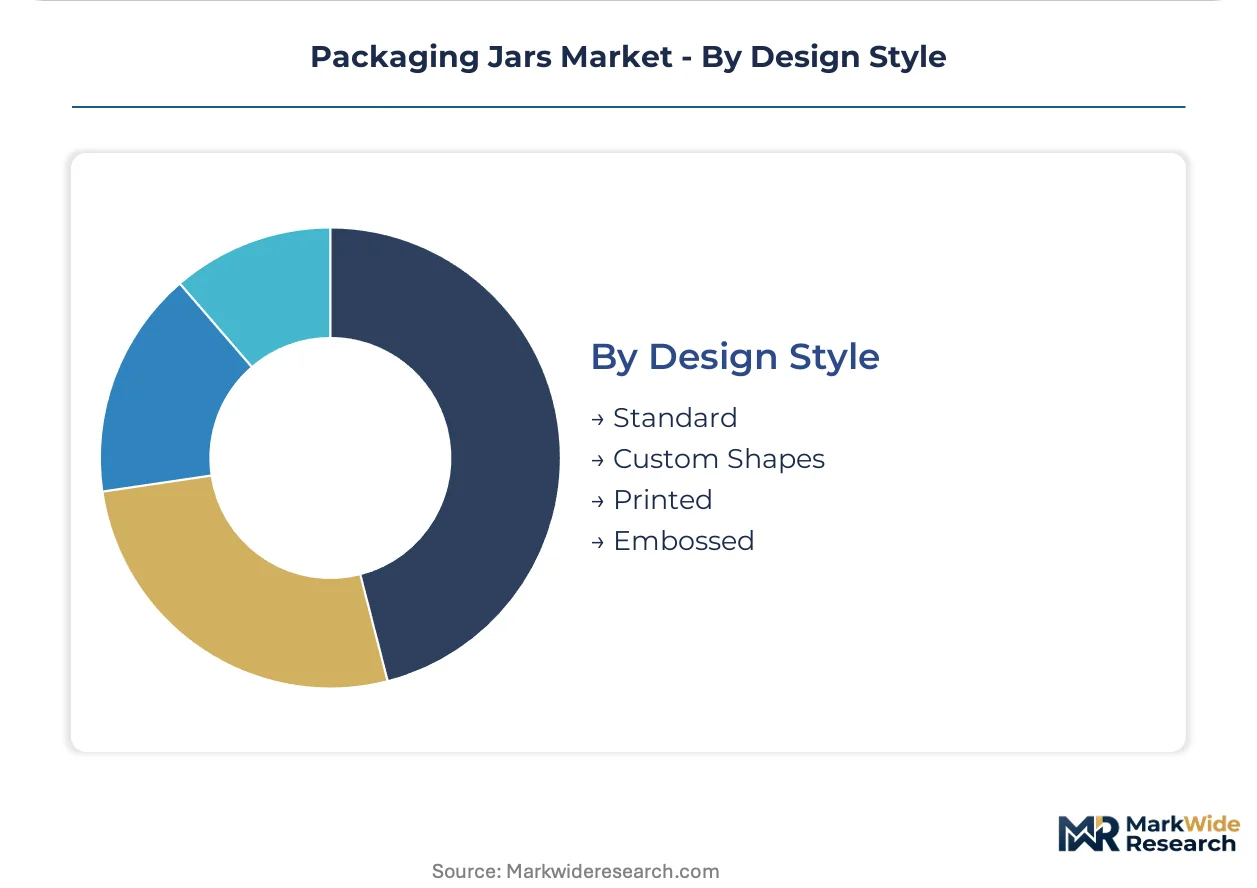
Design Style:
Brand differentiation requirements split this dimension between commodity efficiency and customized premium positioning.
- Standard:Cylindrical and straight-sided formats with minimal decoration serve private label and value-tier retail programs where cost minimization governs procurement.
- Custom Shapes:Proprietary mold designs enable silhouette recognition for cosmetic and premium food brands seeking shelf differentiation. Digital printing convergence enables batch-size reduction for niche cosmetic launches.
- Printed:Direct-to-shape decoration technology eliminates label substrates, reducing material complexity and enabling personalization.
- Embossed:Raised surface textures and logo integration deliver tactile brand signatures for luxury cosmetic and gift packaging segments.
Standard formats handle mass-market throughput; custom shapes are gaining share fastest as direct-to-shape technology collapses minimum order quantities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main manufacturing corridor's dense glassworks clustering anchors Germany's pharmaceutical packaging supply chain, while South Korea's Incheon port infrastructure enables premium cosmetic jar imports from European borosilicate specialists.
Germany
Pharmaceutical-grade borosilicate demand concentrates along the Rhine-Main corridor where specialized glassworks cluster near Frankfurt's chemical buyers. EU REACH substance restrictions and recycled content mandates under the Packaging and Packaging Waste Regulation compress formulation flexibility for jar converters. The Mainz-Wiesbaden industrial zone hosts furnace operators with captive silica sand access serving EMA-qualified pharmaceutical packaging programs.
United States
Craft beverage producers specify aluminum jar alternatives for weight reduction and recyclability credentials, driving metal format procurement. FDA pharmaceutical primary packaging documentation burdens stretch regulatory affairs capacity at mid-tier converters. Ball Corporation leverages its North American metal packaging network from Colorado headquarters to serve regional craft producers seeking premium positioning.
France
Amber glass capacity leadership consolidates among furnace operators with ISO 15378 certification for medicinal products. The EU F-Gas Regulation phase-down schedules tighten barrier coating options for plastic jar formats. Verallia operates furnace assets in the Champagne-Ardenne region supplying pharmaceutical-grade containers to Paris-based cosmetic houses.
South Korea
Cosmetics brands expand premium glass jar specifications for skincare serums with UV-blocking properties. MFDS documentation requirements tighten for recycled content claims in skincare packaging. Seoul-based beauty conglomerates source heavier-wall borosilicate jars through Incheon port logistics channels from European exporters.
Italy
Furnace energy costs tied to natural gas pricing compress margin buffers for mid-scale glass converters. ECHA migration limits on conventional polymers redirect R&D spending toward certified bio-based alternatives. Owens-Illinois sustains amber glass capacity through furnace investments in the Emilia-Romagna industrial district serving Mediterranean pharmaceutical buyers.
Packaging Jars Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate-specific furnace and converter operations. The vendor base structures around three tiers: multinational furnace operators with captive silica access, mid-scale converters with ISO 15378 certification, and regional metal packaging fabricators. Strategic archetypes include energy-integrated glassworks, certified pharmaceutical specialists, and aluminum format diversifiers. Competitive moves concentrate on furnace reconfiguration for amber-to-clear transitions and mass-balance certification for bio-based procurement channels.
Among North American metal packaging specialists, Ball Corporation exemplifies platform-scale aluminum jar production; Owens-Illinois anchors the glass furnace tier with amber and borosilicate capacity; Ardagh Group occupies a diversified position across both glass and metal formats. These three represent distinct strategic archetypes: metal-centric platform integration, substrate-specialized furnace leadership, and multi-material sourcing flexibility. Their positioning reflects how energy access, certification infrastructure, and geographic clustering shape competitive boundaries in pharmaceutical and cosmetic packaging procurement.
| Leading Market Players |
|---|
| Ball Corporation |
| Owens-Illinois |
| Ardagh Group |
| Verallia |
| Berlin Packaging |
| Anchor Hocking |
| Silgan Holdings |
| Vidrala |
| Stoelzle Glass |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German Rhine-Main borosilicate furnace operators determines both pricing tier spreads and supply chain shape, as pharmaceutical buyers face extended qualification timelines and limited second-source options for amber glass primary packaging. This concentration compresses margin buffers for mid-scale converters while elevating premium capture for energy-integrated glassworks with captive silica sand access.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade borosilicate certified to ISO 15378 from commodity soda-lime formats and private-label polypropylene jars. Price differentiation rests on certification level and furnace energy integration, with EMA-qualified suppliers commanding premium positioning over uncertified converters. Cost compression in mid-tier amber glass is intensifying because natural gas price volatility erodes margin buffers at Italian and French furnace operators. Private-label food and household buyers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize barrier performance and dual-market qualification over unit economics.
Supply Chain Analysis
EU REACH substance restrictions and F-Gas Regulation phase-down schedules limit barrier coating technology flows into plastic jar converters, reshaping raw material sourcing patterns. Geographic supply concentration centers on Germany, Italy, and France for pharmaceutical-grade glass, with China and South Korea dominating cosmetic sampling format plastics. Raw material dependencies include high-purity silica sand, boron compounds for thermal resistance, and certified bio-based polymer feedstocks. Single-source vulnerability runs through amber glass furnace operators with captive sand deposits. Distribution runs through brand-direct qualification programs for pharmaceutical tiers and retail private-label aggregators for food and household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified furnace capacity and in-house migration testing infrastructure constitute scarce assets that gate participation in pharmaceutical and premium cosmetic procurement channels. Converters without these capabilities face narrowing addressable market scope as regulatory documentation burdens intensify.
For Market Incumbents: Insulate pharmaceutical-grade positioning by securing dual FDA-EMA qualification capacity and backward integration into captive silica sand mining. Ball Corporation's metal platform leverage and Owens-Illinois's amber furnace investments exemplify how substrate-specific scale and energy integration defend margin structure against bio-based substitution threats and emerging regional glassworks in Eastern Europe. For New Entrants and Emerging Players: South Korean cosmetic sampling formats and certified bio-based polymer channels offer underpenetrated entry points where mass-balance certification and MFDS documentation capabilities differentiate against incumbent commodity converters. Target travel-size skincare serums specifying mono-material polyethylene terephthalate with in-mold labeling, leveraging direct-to-shape decoration technology to collapse minimum order quantities for niche brand launches. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors energy-integrated furnace operators with pharmaceutical certification infrastructure and geographic clustering near chemical buyers. Long-term viability across a 5-10 year window rests on amber-to-clear furnace reconfiguration flexibility and closed-loop collection service revenue potential. Watch EU Packaging and Packaging Waste Regulation enforcement timelines as the inflection signal for accelerated bio-based procurement channel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Reconfiguration Investment | Amber-to-clear transition capability captures pharmaceutical demand mix shifts toward UV-blocking clear borosilicate. |
| Mass-Balance Certification Program | EU Packaging and Packaging Waste Regulation compliance opens bio-based procurement channels for cosmetic brand consolidators. |
| Closed-Loop Collection Infrastructure | Extended producer responsibility scheme participation creates service-revenue streams beyond unit sales. |
| Dual-Market Qualification Capacity | Simultaneous FDA and EMA documentation capability stretches mid-tier competitors and defends premium positioning. |
| Direct-to-Shape Decoration Technology |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and furnace operator disclosures, combining interviews with pharmaceutical packaging procurement managers, cosmetic brand supply chain directors, glassworks plant engineers, and polymer converter technical leads. Secondary sources include EMA quality guideline documentation, FDA pharmaceutical primary packaging guidance, EU REACH substance restriction registers, and SEC filings from publicly traded packaging converters. Bottom-up volume modeling triangulates against top-down value estimates derived from end-use segment procurement patterns.
Forecast inputs incorporate substrate-specific production capacity, regulatory compliance timeline assumptions, and brand sustainability commitment trajectories across the projection horizon. Segmentation dimensions modeled include product substrate, closure mechanics, end-use regulatory intensity, and design customization level. CAGRs derive from regression analysis of historical volume trends adjusted for furnace investment cycles and qualification backlog durations. Industry-specific inputs include natural gas price volatility scenarios and EU recycled content mandate enforcement pacing.
Practitioners should monitor EU Packaging and Packaging Waste Regulation implementation schedules, MFDS recycled content documentation tightening, and F-Gas Regulation barrier coating technology availability for early signals of forecast revision triggers. Material shifts in pharmaceutical buyer dual-market qualification requirements or abrupt energy cost discontinuities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Ukraine Container Glass Market