
 Lamination Systems Market | 2026-2036
Lamination Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lamination Systems Market Analysis
REACH compliance is restructuring material certification costs across European lamination supply chains. BOBST Group SA leverages its Swiss engineering heritage to dominate high-speed roll-to-roll thermal systems for flexible packaging. Nordmeccanica S.p.A. anchors solventless adhesive lamination technology, competing on energy efficiency against thermal alternatives. Comexi Group Industries specializes in hybrid digital-inline configurations that extend its reach into short-run graphic arts workflows.
Lamination systems bond protective films or coatings to substrates through thermal fusion, cold pressure, or adhesive dispersion, typically operating at line speeds between 200 and 600 meters per minute for industrial packaging applications. The equipment serves primarily to enhance barrier properties, surface durability, and print aesthetics for flexible packaging and commercial graphics. Thermal lamination occupies the largest installed base due to its maturity in food packaging, though pressure-sensitive systems are gaining share in electronics and automotive interior applications where heat-sensitive substrates dominate. Roll-to-roll technology leads by throughput economics, while digital and inline configurations represent the fastest-growing technology category as converters integrate finishing directly after variable-data printing.
The European Chemicals Agency enforces REACH substance restrictions on adhesives and films, compelling equipment vendors to validate solventless and water-based process compatibility. The FDA regulates indirect food-contact laminates through 21 CFR substrate compliance, shaping resin selection and migration testing protocols for U.S.-bound packaging lines. Germany's Federal Institute for Risk Assessment coordinates with ECHA on cross-border material safety assessments, tightening market access for non-compliant Asian imports. Stakeholders must monitor regulatory divergence between EU Green Deal packaging targets and U.S. state-level extended producer responsibility laws to align capital deployment with emerging compliance boundaries.
Market Dynamics
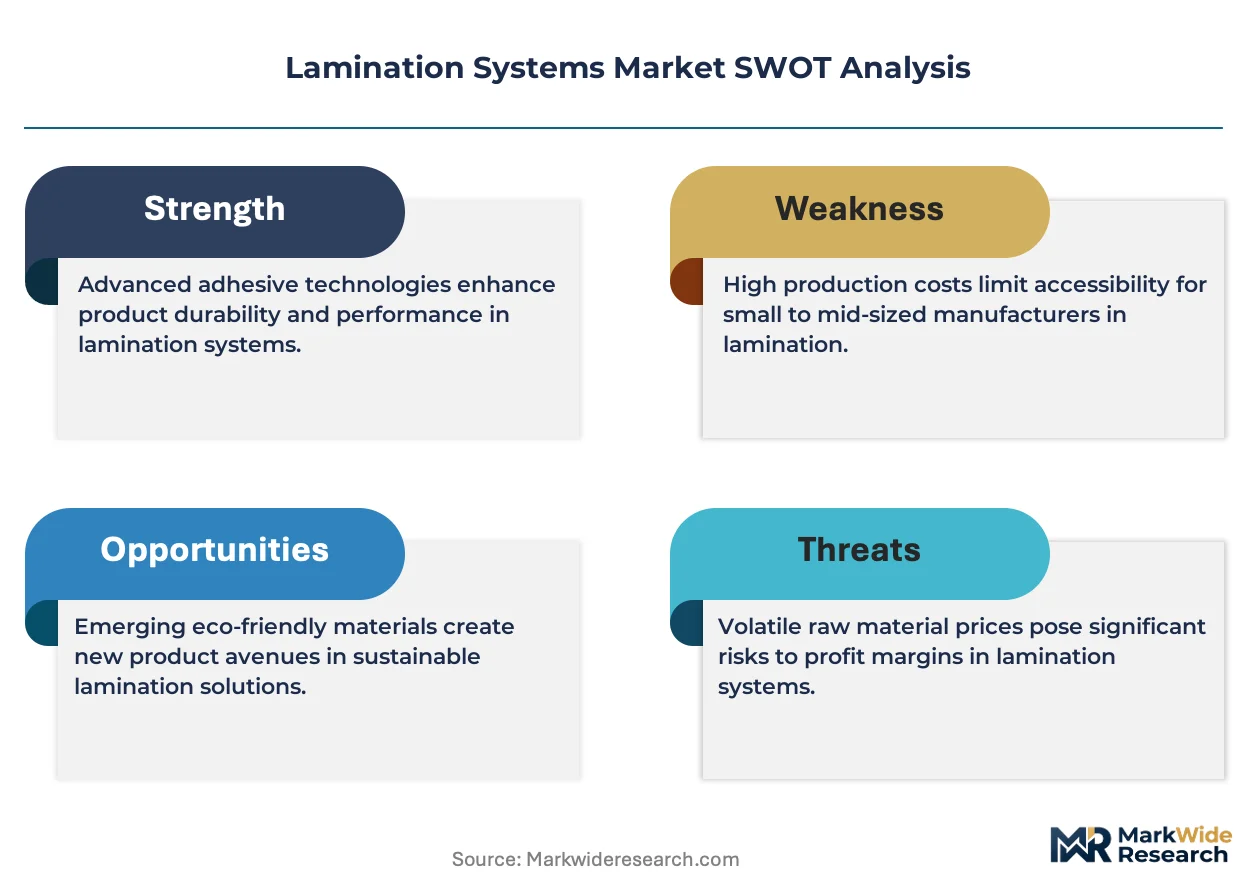
REACH substance restrictions and FDA substrate compliance mandates are forcing packaging converters to requalify entire adhesive portfolios, creating a bifurcation between solventless-capable equipment lines and legacy thermal systems facing stranded-asset risk.
Growth Catalysts
- Food-contact safety mandates:ECHA's REACH enforcement compels European converters to replace solvent-based adhesives with water-based and solventless alternatives, triggering equipment replacement cycles.
- Flexible packaging expansion:E-commerce fulfillment networks demand higher barrier properties for shelf-stable food pouches, driving thermal lamination capacity additions.
- Electronics substrate protection:Pressure-sensitive cold lamination systems penetrate automotive interior and display manufacturing where heat-sensitive polymers dominate.
Market Restraints
- Petrochemical resin volatility:Polyethylene and polypropylene film costs swing with crude oil indices, compressing converter margins and delaying capital commitments.
- Equipment supplier concentration:Swiss and Italian engineering clusters control precision coating head and tension control subsystems, creating single-source vulnerabilities.
- Adhesive curing speed limits:Water-based formulations require extended drying tunnels versus solventless instant cure, constraining line speed economics.
Strategic Opportunities
- Short-run digital integration:Hybrid inline configurations that marry inkjet printing with finishing lamination capture graphic arts workflows previously served by offline batch processing.
- EU Green Deal packaging targets:Recyclable mono-material laminate mandates create demand for compatible thermal and adhesive bonding systems.
- India packaging modernization:FSSAI food safety regulations and organized retail expansion drive first-time lamination system adoption among domestic flexible packaging converters.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous ECHA substance authorization and FDA 21 CFR migration testing extend product launch cycles by 18-24 months.
- Legacy PLC integration friction:Digital inline modules must interface with 1990s-era roll-to-roll control architectures, requiring custom middleware development.
- Solventless adhesive chemist scarcity:Formulation expertise for two-component polyurethane systems concentrates among retiring European specialists, constraining technical service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lamination Systems Market |
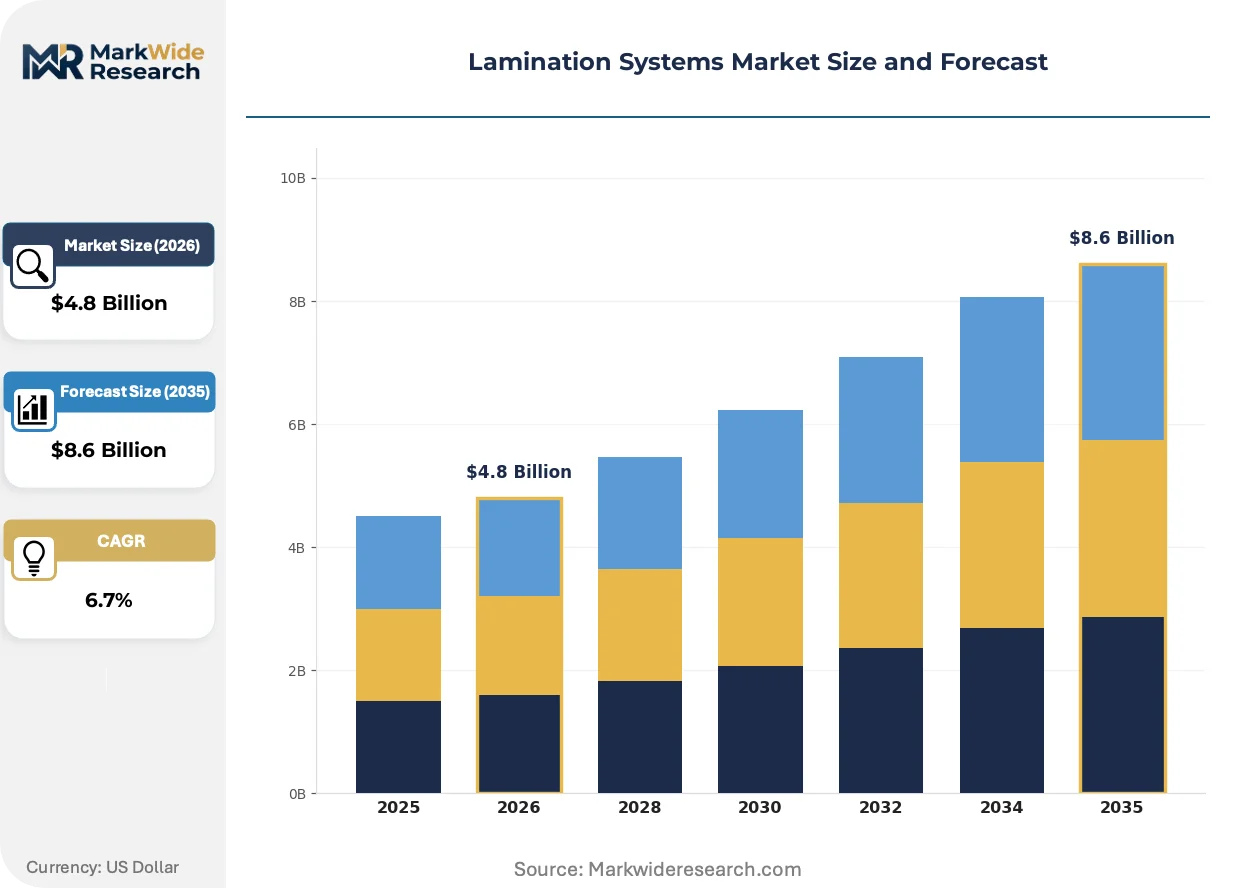
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Lamination, Cold Lamination, Pressure Sensitive Lamination, Liquid Lamination Application: Packaging, Graphic Arts, Automotive, Electronics Technology: Roll-to-Roll, Sheet-to-Sheet, Digital, Inline End User: Printing Companies, Manufacturers, Retail, Education |
| Companies Covered | BOBST Group SA, Comexi Group Industries, HMT Manufacturing Inc., Black Bros. Co., Nordmeccanica S.p.A., Faustel Inc., Monotech Systems Ltd, Graphco, Equinox Precision Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lamination Systems Market Emerging Trajectories
Electrification of heating systems and AI-driven tension control are compressing energy consumption and defect rates simultaneously, while regulatory chemistry restrictions accelerate adhesive platform turnover.
Electron beam (EB) curing technology replaces thermal drying ovens in high-throughput food packaging lines. Major European converters retrofit existing solventless coaters with EB modules to eliminate thermal energy input entirely. The technology is integrating into greenfield plant designs as a standard configuration rather than premium upgrade.
REACH Annex XVII substance restrictions now cover per- and polyfluoroalkyl substances (PFAS) in food-contact films, forcing laminate producers to validate fluorine-free barrier coatings. German converters face the tightest enforcement timelines, with the Federal Institute for Risk Assessment coordinating cross-border material assessments. Equipment vendors must certify compatibility with emerging ceramic and bio-based barrier layers.
Converter procurement departments unbundle after-sales service contracts from equipment purchases, shifting to outcome-based availability guarantees. Tier-one flexible packaging groups in North America now demand uptime-based payment structures rather than fixed maintenance retainers. This restructuring concentrates service revenue among vendors with remote diagnostics infrastructure and regional spare parts depots.
Lamination Systems Market Segmentation
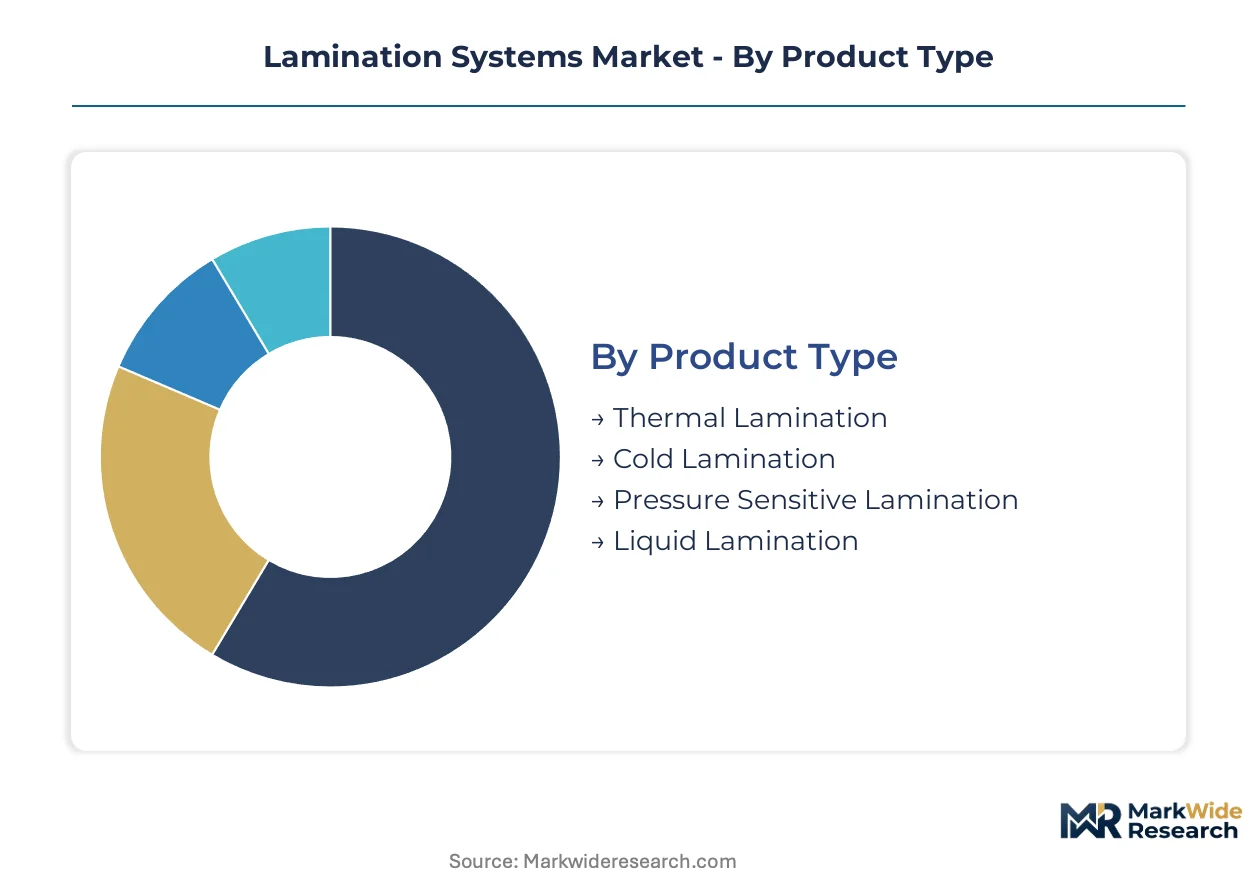
Segmentation in lamination systems reveals how certification burdens, substrate compatibility, and throughput economics fragment procurement decisions across converter types. Each dimension carries distinct regulatory and technical requirements that shape equipment specification and vendor selection.
Product Type:
Thermal lamination systems require ECHA REACH substance authorization for adhesives and films, while cold and pressure-sensitive alternatives face lighter chemical compliance loads but stricter FDA 21 CFR substrate migration testing for food-contact applications.
- Thermal Lamination:Heat-activated adhesive films bond substrates at 80-150°C through nip roller pressure. European flexible packaging converters in Germany and Italy dominate installed base expansion as ECHA enforcement tightens solvent-based adhesive restrictions. REACH Annex XVII compliance costs are accelerating replacement cycles among mid-cap converters.
- Cold Lamination:Pressure-activated adhesive systems operate without thermal input, preserving heat-sensitive substrates. Demand concentrates in automotive interior manufacturing across Stuttgart and Turin production clusters, where polymer dashboards and display films require zero thermal deformation. FDA substrate regulations for indirect food contact impose parallel migration testing burdens on U.S.-bound lines.
- Pressure Sensitive Lamination:Pre-coated adhesive films activate under mechanical pressure alone.
- Liquid Lamination:UV-curable or water-based coatings applied through precision coating heads.
Thermal lamination sits at the top of the volume ranking, with cold lamination climbing the fastest on automotive and electronics substrate protection demand.
Application:
Application segments diverge sharply on throughput requirements and regulatory exposure, with food packaging carrying the heaviest ECHA and FDA compliance burdens while automotive and electronics emphasize precision over speed.
- Packaging:Flexible food pouches and barrier films demand line speeds of 400-600 meters per minute with validated migration compliance. German and Swiss converters anchor capacity expansion as EU Green Deal recyclable mono-material mandates reshape laminate specifications. ECHA PFAS restrictions are forcing validation of fluorine-free barrier coatings.
- Graphic Arts:Short-run commercial prints and photobooks prioritize finish quality over speed. North American and Japanese print service providers drive hybrid digital-inline adoption, integrating inkjet printing with finishing lamination in single-pass workflows.
- Automotive:Interior trim, dashboard films, and acoustic laminates require cold-process compatibility.
- Electronics:Display protection films and flexible circuit substrates demand micron-level precision.
Packaging commands the largest equipment installed base, though graphic arts is expanding most quickly on digital integration demand.
Technology:
Technology selection tracks converter scale and product mix, with roll-to-roll systems optimized for commodity volume and digital configurations capturing variable-data short runs.
- Roll-to-Roll:Continuous web processing delivers lowest per-unit cost at high volumes. Swiss and Italian engineering clusters dominate precision coating head and tension control supply, creating single-source dependencies for major flexible packaging groups. Line speeds of 200-600 meters per minute anchor food packaging economics.
- Digital:Inline inkjet integration enables variable-data printing with immediate finishing. North American graphic arts converters retrofit legacy roll-to-roll architectures with digital modules, though PLC integration friction with 1990s-era control systems extends deployment timelines.
- Sheet-to-Sheet:Discrete substrate processing for rigid materials and small formats.
- Inline:Direct integration with upstream printing or coating operations.
Roll-to-roll technology retains the highest shipment volumes, while digital configurations are gaining share fastest on converter workflow integration priorities.
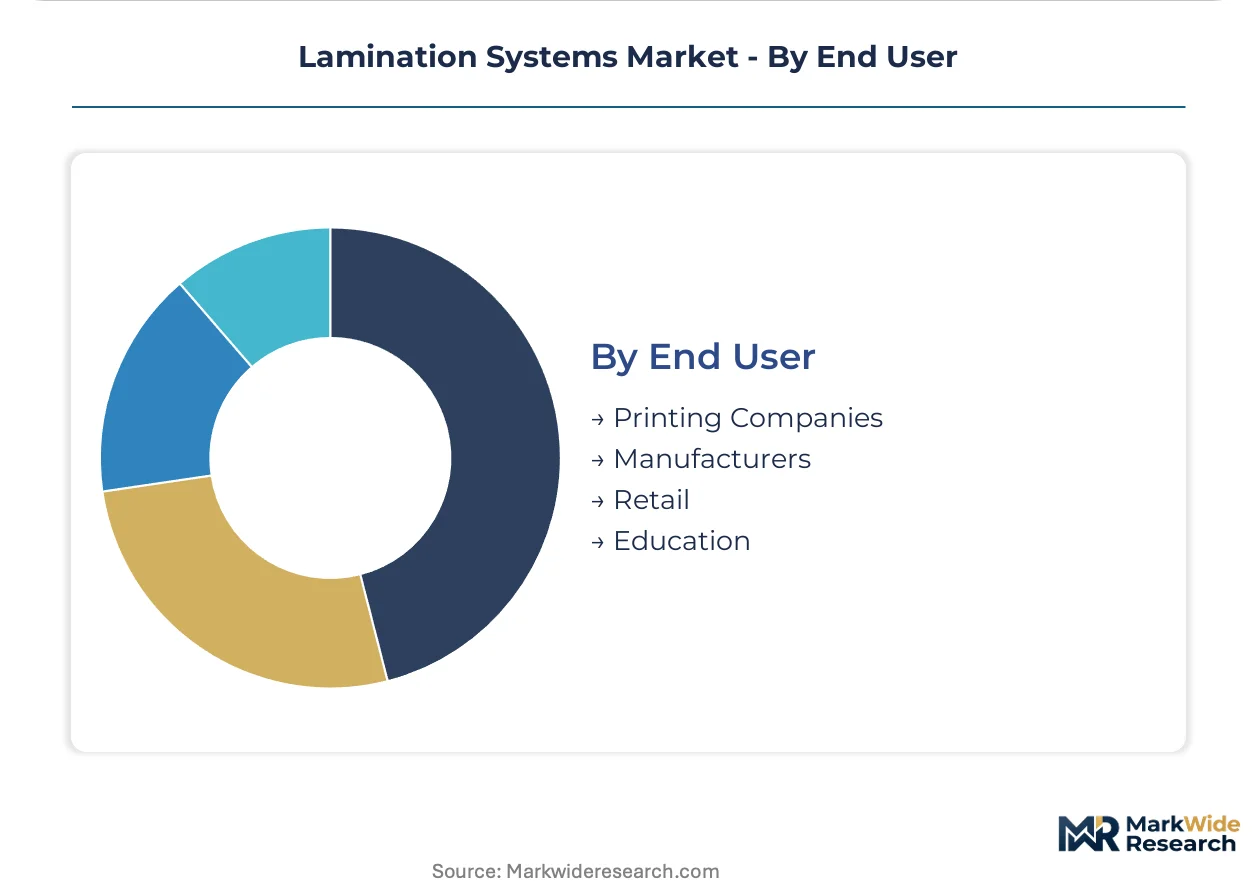
End User:
End user categories reflect divergent capital intensity and service requirements, with manufacturers demanding uptime guarantees and education sector buyers prioritizing acquisition cost over throughput.
- Printing Companies:Commercial printers and packaging converters constitute the core equipment demand base. Tier-one flexible packaging groups in North America now procure on outcome-based availability guarantees rather than fixed maintenance contracts, concentrating service revenue among vendors with remote diagnostics infrastructure.
- Manufacturers:Automotive suppliers and electronics OEMs specify cold lamination systems for heat-sensitive polymer processing. Stuttgart and Munich automotive clusters drive pressure-sensitive system adoption for interior trim applications.
- Retail:In-store print services and private label packaging operations.
- Education:Schools and universities with document preservation and display needs.
Printing companies represent the dominant procurement segment, with manufacturers showing the steepest expansion trajectory on automotive and electronics substrate protection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mechanical engineering talent and Swiss precision manufacturing clusters anchor European lamination system supply chains. North American packaging converters concentrate technical service expertise around Midwest industrial corridors. Asian demand is concentrating in India and China as food safety regulations modernize.
Germany
Flexible packaging converters in Bavaria and Baden-Württemberg drive thermal lamination capacity expansion for food-contact applications. The Federal Institute for Risk Assessment coordinates with ECHA on REACH Annex XVII enforcement timelines for PFAS-free barrier coatings. Stuttgart automotive clusters demand cold-process systems for interior trim lamination.
United States
Midwest flexible packaging groups retrofit solventless coating lines to meet FDA 21 CFR substrate migration testing requirements. State-level extended producer responsibility laws in California and New York reshape recyclable mono-material laminate specifications. Chicago-area converters procure on outcome-based availability guarantees rather than fixed maintenance contracts.
India
Domestic flexible packaging converters in Maharashtra and Gujarat adopt first-time lamination systems as organized retail expands. FSSAI food safety regulations mandate migration testing protocols previously absent in unorganized segments. Mumbai-Pune industrial corridors attract European equipment vendors establishing regional service depots.
Italy
Emilia-Romagna and Lombardy engineering clusters specialize in solventless adhesive lamination technology competing on energy efficiency. REACH compliance costs accelerate replacement cycles among mid-cap converters in the packaging triangle. Turin automotive suppliers specify pressure-sensitive systems for dashboard film applications.
China
Coastal flexible packaging manufacturers in Jiangsu and Zhejiang provinces upgrade thermal systems for export-compliant food-contact production. GB standards for food packaging materials tighten adhesive formulation requirements. Yangtze River Delta converters face ECHA-equivalent substance restrictions from downstream EU-bound customers.
Lamination Systems Market Vendor Landscape
The competitive structure tilts toward precision-engineering specialists with multi-decade coating head expertise. Swiss and Italian engineering clusters control tension control and precision coating subsystems, creating single-source dependencies for major flexible packaging groups. Two strategic archetypes dominate: heritage European precision fabricators and regional Asian assemblers serving price-sensitive emerging markets. Competitive moves concentrate on geographic service expansion and adhesive chemistry platform partnerships rather than horizontal consolidation.
Within the heritage European tier, BOBST Group SA and Nordmeccanica S.p.A. represent precision-engineering archetypes with established positions in high-throughput roll-to-roll configurations. Comexi Group Industries occupies a specialist position in hybrid digital-inline systems. Among North American fabricators, Faustel Inc. and Black Bros. Co. exemplify mid-scale equipment builders serving regional converter markets. HMT Manufacturing Inc. represents the diversified industrial machinery archetype with cross-sector coating expertise. These named entities anchor industry-level commentary on geographic concentration and capability segmentation without asserting specific strategic actions or financial positions.
| Leading Market Players |
|---|
| BOBST Group SA |
| Comexi Group Industries |
| HMT Manufacturing Inc. |
| Black Bros. Co. |
| Nordmeccanica S.p.A. |
| Faustel Inc. |
| Monotech Systems Ltd |
| Graphco |
| Equinox Precision Corp. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Italy and Switzerland anchor precision coating head production, translating concentrated engineering heritage into pricing discipline that resists commoditization despite Asian assembler competition. Their control over tension control subsystems allows selective premium capture from tier-one flexible packaging groups while regional assemblers serve price-sensitive emerging markets.
Pricing Analysis
The bundled-versus-unbundled service split now dominates procurement negotiations, with tier-one North American converters demanding outcome-based availability guarantees rather than fixed maintenance retainers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because water-based adhesive formulations require extended drying tunnels that constrain line speed economics. Small-scale education sector buyers exhibit highest price sensitivity, while automotive OEMs prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Swiss flexible packaging groups, while regional distributors serve mid-cap converters in India and China. Precision coating heads and tension control subsystems draw from Switzerland, Italy, and Germany. Raw material dependencies center on polyethylene and polypropylene films, polyurethane adhesive resins, and ceramic barrier coatings. Single-source vulnerability concentrates in Swiss and Italian engineering clusters controlling critical subsystems. Distribution runs through authorized service depots with regional spare parts inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe exceed FSSAI adoption timelines in India, creating 18-24 month certification gaps that favor early-mover equipment deployment in emerging regulatory environments.
For Market Incumbents: Acquire solventless adhesive formulation expertise to counter retiring European specialist scarcity. Backward integration into precision coating head manufacturing reduces single-source dependency on Swiss engineering clusters. Capacity addition in Maharashtra and Gujarat captures FSSAI-driven replacement cycles among Indian flexible packaging converters. For New Entrants and Emerging Players: AI-driven tension control modules offer a technology-first wedge into legacy roll-to-roll retrofit demand. Graphic arts workflows in North America present the most penetrable segment given PLC integration friction with 1990s-era control architectures. Go-to-market positioning should emphasize remote diagnostics infrastructure to meet outcome-based procurement requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Asian assemblers lacking REACH-compliant certification portfolios. Long-term viability over the next decade hinges on adhesive chemistry platform partnerships rather than standalone equipment manufacturing. Watch for ECHA PFAS enforcement timelines as the inflection indicator for fluorine-free barrier coating validation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Head Manufacturing | Reduces Swiss and Italian single-source dependency for major flexible packaging groups. |
| Remote Diagnostics Infrastructure Buildout | Enables outcome-based availability guarantees demanded by tier-one North American converters. |
| Solventless Adhesive Chemistry Partnership | Addresses formulation expertise scarcity among retiring European specialists. |
| Regional Service Depot Expansion | Captures FSSAI-driven demand across Mumbai-Pune industrial corridors in India. |
| Digital Inline Module Development | Resolves PLC integration friction with legacy roll-to-roll control architectures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at flexible packaging converters, procurement leads at downstream OEMs, aftermarket service heads, and technical R&D directors with secondary validation against customs and trade data, SEC filings from disclosed equipment vendors, and ECHA substance restriction databases. Bottom-up equipment shipment tallies and top-down converter capacity expansion estimates were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across thermal, cold, and pressure-sensitive product types, with further disaggregation by roll-to-roll, digital, and inline technology configurations over the projection horizon. CAGRs were derived from installed base replacement cycles and greenfield capacity additions. Industry-specific forecast inputs incorporated REACH Annex XVII enforcement timelines and FDA 21 CFR migration testing protocol changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical resin volatility and adhesive curing speed limits. Forecasts reflect assumptions around regulatory enforcement consistency and converter capital commitment timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Overwrapping Machines Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Tissue Paper Embosser Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
Extrusion Press Market