
 Global Tissue Paper Converting Machines Market | 2026-2036
Global Tissue Paper Converting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tissue Paper Converting Machines Market Outlook
Packaging companies are collapsing order timelines for semi-automatic and high-speed tissue converting lines as private-label tissue brands squeeze margins. Fabio Perini S.p.A. leverages its Italian engineering heritage to dominate premium napkin and facial tissue machinery. Körber AG anchors its position through integrated automation platforms spanning folding to wrapping. Gambini S.p.A. specializes in narrow-width toilet paper lines that serve emerging market entrants.
Tissue paper converting machines mechanically process parent tissue rolls into finished consumer products through slitting, folding, perforating, and packaging operations, typically running at 300 to 600 meters per minute on high-speed lines. Automatic equipment commands the largest installed base but digital control retrofit kits represent the fastest-expanding margin pool as converters seek to avoid full line replacement. Mechanical technology still occupies the majority of legacy machines though pneumatic systems lead new orders for facial tissue applications where softness calibration demands precise pressure control.
CE marking under the EU Machinery Directive and FDA facility registration requirements for US tissue manufacturers shape machine design specifications and validation protocols. China's SAMR enforces GB standards on imported converting equipment while India's BIS certification delays entry for non-domestic suppliers. Stakeholders must monitor how carbon accounting rules under the EU Green Deal redirect capital toward energy-efficient pneumatic and digital machine architectures.
Market Dynamics
Packaging companies are compressing order timelines for semi-automatic and high-speed tissue converting lines as private-label tissue brands squeeze margins. EU machinery safety directives and CE marking requirements are tightening compliance thresholds for equipment imports, forcing manufacturers to redesign control architectures before shipment.
Growth Catalysts
- CE marking under EU Machinery Directive:European importers demand pre-certified equipment, pulling investment toward compliant pneumatic and digital machine architectures that streamline cross-border sales.
- Facial tissue softness calibration:Precise pressure control requirements in premium consumer products are accelerating orders for pneumatic systems over mechanical alternatives.
- China's SAMR enforcement of GB standards:Domestic tissue converters face mandatory equipment upgrades, creating replacement demand for imported converting lines that meet national certification.
Market Restraints
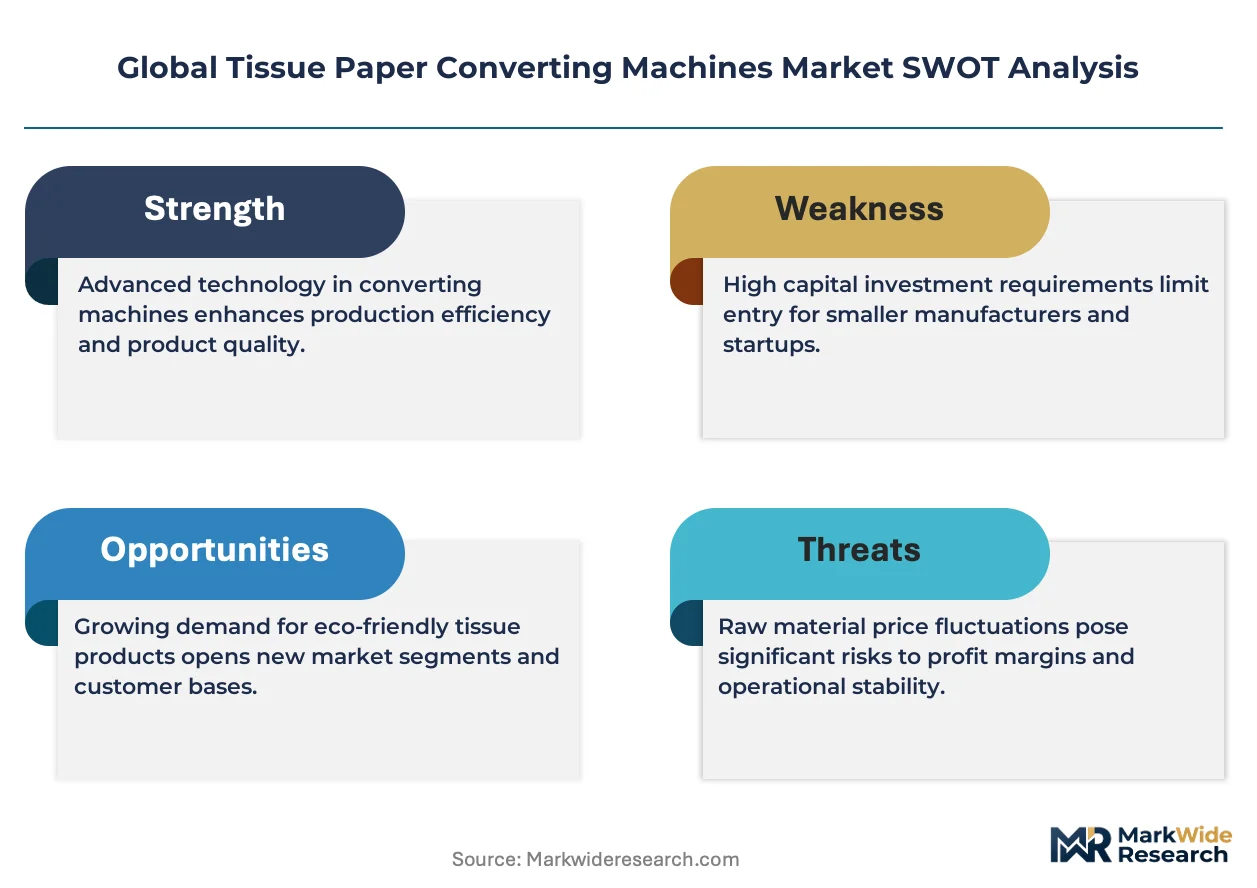
- Steel and servo motor input volatility:Machine frames and precision drive components face cost pressure from commodity fluctuations, squeezing fixed-price contract margins for European builders.
- Legacy mechanical installed base:Decades-old slitting and folding equipment in North American mills creates path dependency that slows full-line replacement cycles.
- India's BIS certification delays:Non-domestic suppliers face extended validation timelines that freeze market entry for 12-18 months on average.
Strategic Opportunities
- Digital control retrofit kits:Converters seeking to avoid full line replacement represent an expanding margin pool for modular automation upgrades.
- EU Green Deal carbon accounting rules:Energy-efficient machine architectures qualify for preferential financing, redirecting capital toward pneumatic and digital systems.
- Narrow-width toilet paper lines:Emerging market entrants in Southeast Asia require compact, lower-capital equipment configurations that incumbent premium suppliers have underdeveloped.
Industry Challenges
- Mechatronics technician scarcity:Converters struggle to staff maintenance roles that bridge mechanical legacy systems with digital control platforms.
- FDA facility registration validation:US tissue manufacturers face extended documentation timelines for imported equipment that delays production ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tissue Paper Converting Machines Market |
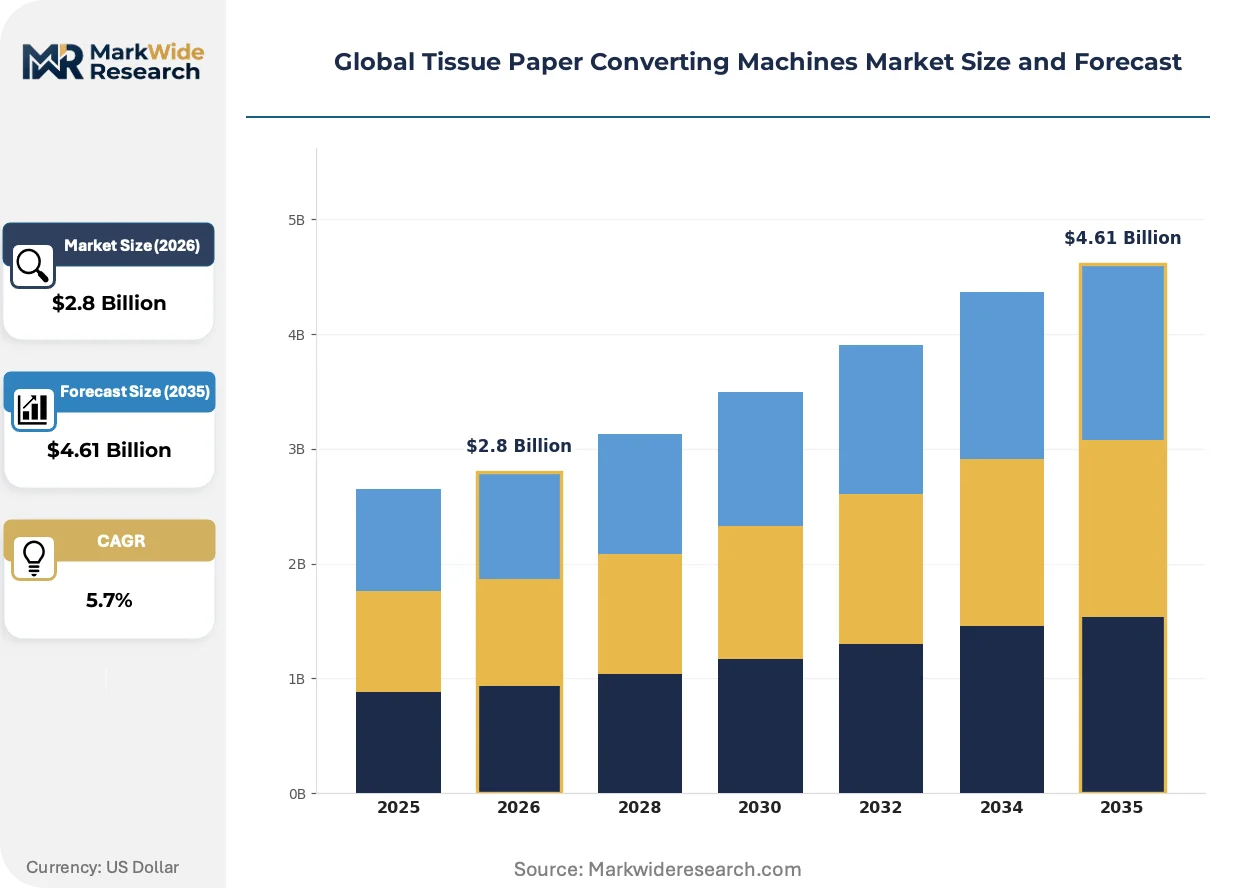
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, High-Speed End User: Packaging Companies, Manufacturers, Distributors, Retailers Technology: Digital, Hydraulic, Pneumatic, Mechanical Application: Facial Tissue, Toilet Paper, Paper Towels, Napkins |
| Companies Covered | Gambini S.p.A., C. G. Bretting Manufacturing Co. Inc., Paper Converting Machine Company, Curt G Joa Inc., Körber AG, Fabio Perini S.p.A., A.Celli Group, Omet S.R.L., Toscotec S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tissue Paper Converting Machines Market Strategic Shifts
Automation architectures are fragmenting across three distinct vectors: control system digitization, pneumatic precision engineering, and modular retrofit economics. Each trajectory carries different implications for capital deployment and competitive positioning.
Digital control platforms with integrated HMI and predictive maintenance modules are supplanting relay-based electromechanical systems in high-throughput lines. Mid-scale converters in Germany and the United States are adopting these systems fastest, driven by labor cost pressure and downtime reduction targets. The shift is compressing margins for pure mechanical component suppliers while expanding software and service revenue pools for integrated platform vendors.
REACH chemical compliance and the EU F-Gas Regulation are restricting hydraulic fluid formulations and refrigerant-based cooling systems in converting equipment. Machine builders must reformulate lubrication circuits and thermal management to maintain CE marking eligibility. Facial tissue applications with stringent hygiene requirements face the steepest redesign burden, pushing European manufacturers toward dry pneumatic actuation.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in mature markets. Converters in Japan and South Korea now procure spare parts through third-party industrial distributors rather than OEM captive channels. This shift compresses service revenue for machinery suppliers while opening margin opportunities for specialized component distributors with regional stocking presence.
Global Tissue Paper Converting Machines Market Segmentation
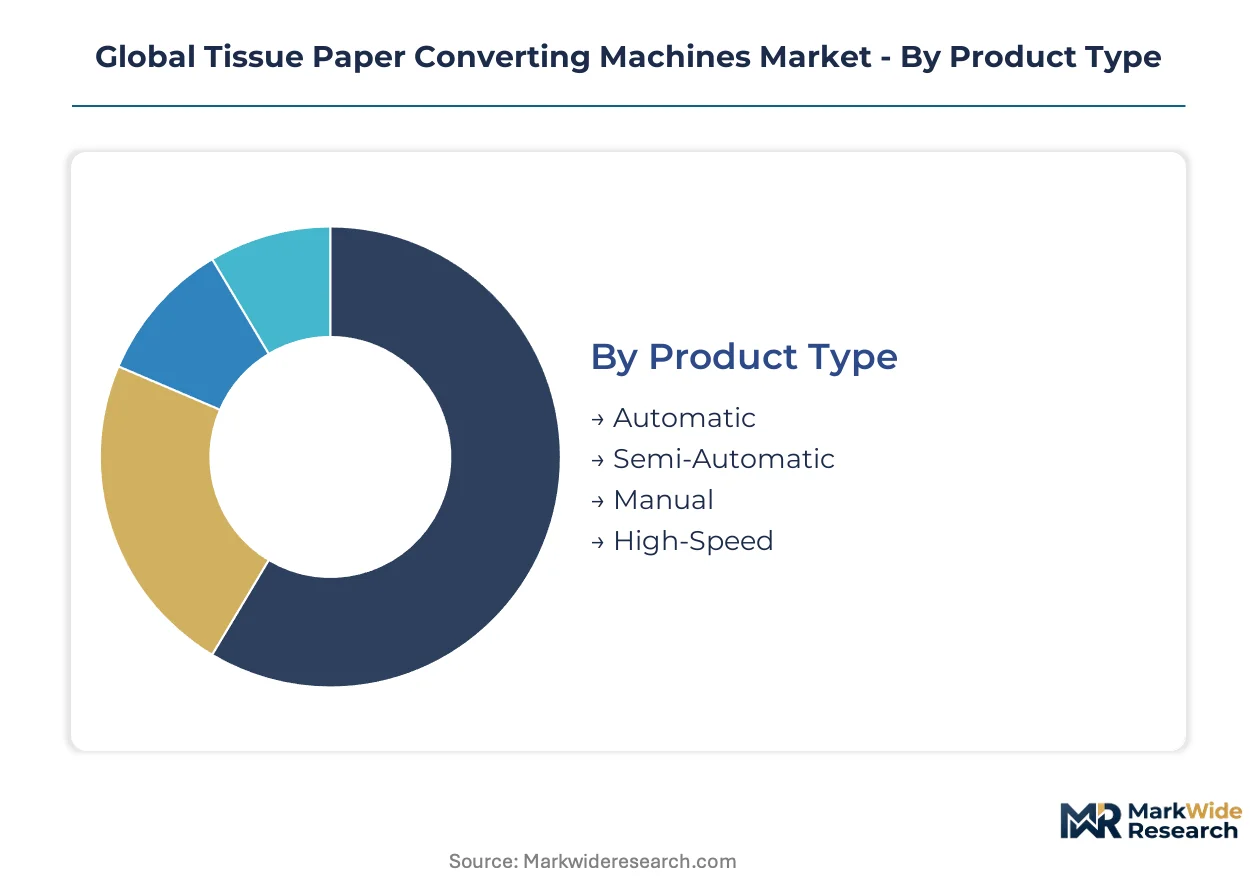
Segmentation in tissue paper converting machines reveals how capital deployment, regulatory compliance, and end-use specifications fragment procurement patterns. Buyers optimize across throughput speed, automation depth, and hygiene-grade requirements rather than treating equipment as interchangeable commodity hardware.
Product Type:
Substitution pressure runs strongest against manual and semi-automatic lines as labor costs climb and private-label brands demand throughput consistency that only automated systems deliver reliably.
- Automatic:These lines integrate slitting, folding, perforating, and packaging into continuous workflows with minimal operator intervention. Packaging companies in Germany and the United States prioritize automatic equipment to compress order-to-delivery timelines for private-label tissue brands.
- High-Speed:Operating at 600 meters per minute, these systems serve multinational tissue producers with dedicated capacity for facial tissue and toilet paper. China's SAMR enforcement of GB standards accelerates replacement demand as domestic converters upgrade from legacy mechanical lines.
- Semi-Automatic:Hybrid configurations retain mechanical folding stations while adding digital control modules for changeover flexibility. Emerging market entrants in Southeast Asia favor these systems for lower capital thresholds.
- Manual:Bench-scale equipment persists in artisanal and specialty tissue production where batch sizes resist automation economics.
Automatic equipment anchors the volume base while high-speed lines gain share at the steepest rate.
End User:
Margin capture concentrates with packaging companies that bundle converting services with downstream distribution, squeezing standalone manufacturers on price and contract duration.
- Packaging Companies:These buyers operate integrated converting-to-fulfillment networks for private-label tissue brands. EU machinery safety directives and CE marking requirements tighten compliance thresholds, forcing equipment redesigns before cross-border shipment.
- Manufacturers:Tissue mills with captive converting capacity prioritize digital control retrofit kits to extend legacy line life without full replacement capital outlay. FDA facility registration requirements for US tissue producers extend validation timelines for imported equipment.
- Distributors:Regional equipment lessors serve mid-scale converters with short-term contracts and rapid deployment models.
- Retailers:Vertically integrated chains in Japan and South Korea procure narrow-width toilet paper lines for private-label production.
Packaging companies command the largest procurement volume while manufacturers represent the most active retrofit demand segment.
Technology:
Regulatory chemistry restrictions are displacing hydraulic architectures fastest, redirecting capital toward pneumatic precision engineering and digital control platforms.
- Pneumatic:Dry actuation systems enable precise pressure calibration for facial tissue softness specifications. REACH chemical compliance and the EU F-Gas Regulation restrict hydraulic fluid formulations, pushing European builders toward pneumatic redesigns.
- Digital:Integrated HMI and predictive maintenance modules supplant relay-based electromechanical systems. Mid-scale converters in Germany adopt these platforms to reduce downtime and compress labor cost structures.
- Mechanical:Legacy slitting and folding equipment dominates North American installed bases, creating path dependency that slows full-line replacement cycles.
- Hydraulic:Fluid-power systems persist in heavy-duty napkin and paper towel applications where torque density requirements exceed pneumatic limits.
Mechanical technology retains the largest installed base while pneumatic systems expand most quickly in new order flows.
Application:
Hygiene-grade differentiation fragments machine specifications most acutely in facial tissue, where softness calibration demands pneumatic precision that toilet paper lines rarely require.
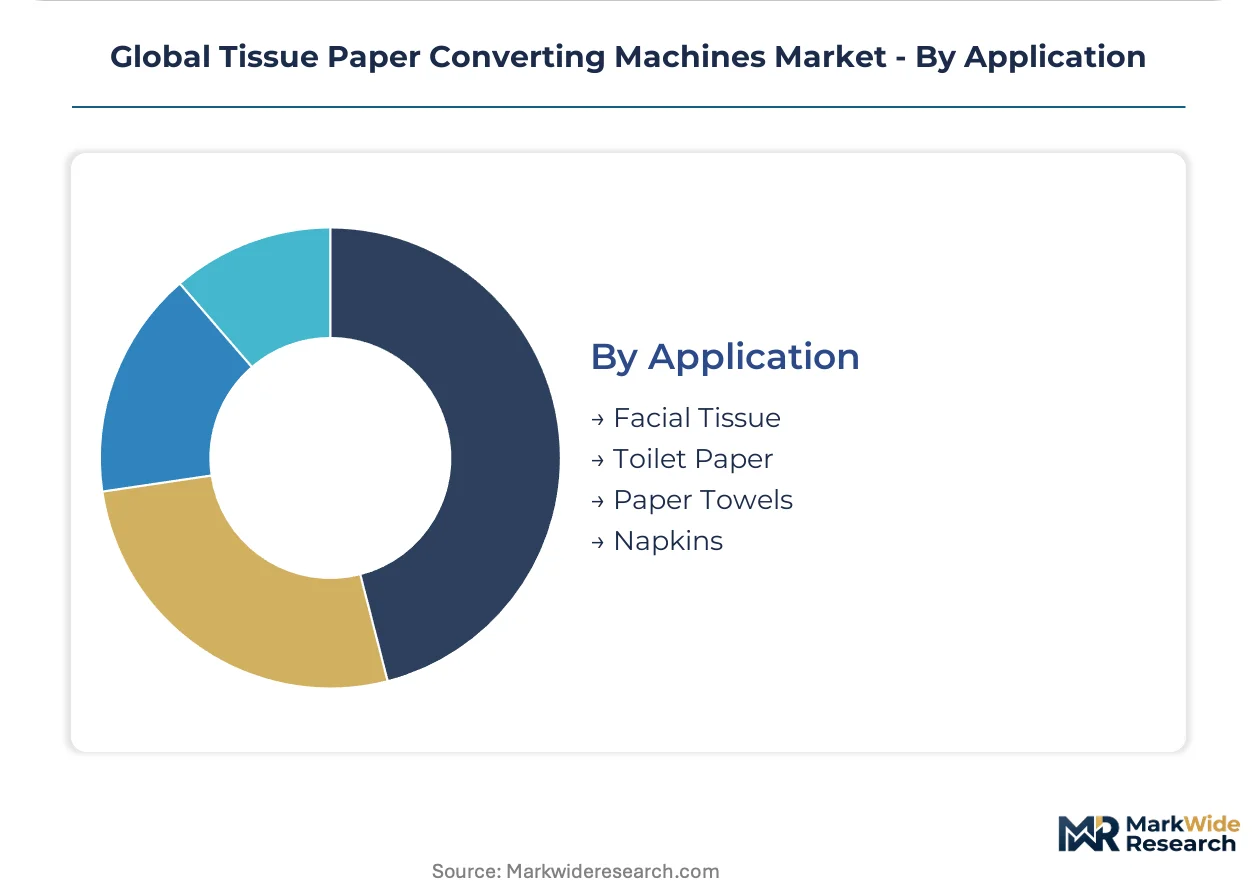
- Facial Tissue:Premium consumer products require precise pressure control during folding and embossing operations. CE marking under the EU Machinery Directive shapes validation protocols for equipment serving this segment.
- Toilet Paper:High-volume, lower-margin production favors automatic and high-speed lines with minimal changeover flexibility. Narrow-width configurations serve emerging market entrants in Southeast Asia with compact footprints.
- Paper Towels:Industrial and commercial grades prioritize absorbency metrics that influence perforation blade specifications and roll density controls.
- Napkins:Tabletop and dispenser formats require specialized folding architectures that Italian engineering heritage suppliers dominate.
Toilet paper anchors the volume base while facial tissue commands the steepest technology premium expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European machinery trade flows, handling specialized equipment imports from Italian and German builders. Containerized shipments of converting lines move through this hub to tissue converters across the continent. Rail connections extend distribution into Central and Eastern European manufacturing zones.
China
Domestic tissue converters accelerate equipment replacement cycles as private-label brands capture supermarket shelf space. SAMR enforcement of GB standards on imported machinery tightens certification timelines for European and Japanese suppliers. The Yangtze River Delta cluster around Shanghai concentrates procurement decisions for multinational tissue producers expanding capacity.
Germany
Mid-scale converters prioritize digital control retrofits to compress labor cost structures without full line replacement capital outlay. CE marking under the EU Machinery Directive shapes validation protocols for equipment serving facial tissue softness specifications. The Baden-Württemberg engineering corridor hosts system integrators bridging mechanical legacy platforms with predictive maintenance modules.
United States
Packaging companies collapse order timelines for high-speed lines as private-label tissue brands squeeze contract margins. FDA facility registration requirements extend validation timelines for imported equipment, delaying production ramp schedules. The Midwest paper corridor spanning Wisconsin and Michigan retains decades-old mechanical installed bases that slow full-line replacement decisions.
India
Emerging market entrants favor semi-automatic configurations for lower capital thresholds and operational flexibility. BIS certification delays freeze market entry for non-domestic suppliers across 12-18 month validation windows. The Gujarat industrial belt attracts narrow-width toilet paper line deployments serving regional distribution networks.
Italy
Premium napkin and facial tissue machinery builders leverage engineering heritage to command technology premiums in export markets. REACH chemical compliance and the EU F-Gas Regulation restrict hydraulic fluid formulations, pushing pneumatic redesigns for CE marking eligibility. The Lucca tissue district concentrates specialized folding architecture expertise for tabletop and dispenser formats.
Global Tissue Paper Converting Machines Market Competitive Environment
Concentration sits with integrated automation platform vendors and specialized narrow-width equipment fabricators. The vendor base splits between consolidated European engineering groups with captive service networks and fragmented Asian fabricators competing on capital cost. Two strategic archetypes dominate: heritage Italian engineering houses with premium positioning and German system integrators bundling folding-to-wrapping workflows. Competitive moves center on digital control retrofit kit portfolios and modular automation licensing arrangements.
Among Italian heritage suppliers, Fabio Perini S.p.A. and Gambini S.p.A. exemplify the premium-tier archetype built on regional engineering reputation. Körber AG anchors the integrated platform segment with German corporate structure spanning automation workflows. These three occupy positions that reflect divergent capital deployment strategies: specialized narrow-width lines versus comprehensive system integration.
| Leading Market Players |
|---|
| Gambini S.p.A. |
| C. G. Bretting Manufacturing Co. Inc. |
| Paper Converting Machine Company |
| Curt G Joa Inc. |
| Körber AG |
| Fabio Perini S.p.A. |
| A.Celli Group |
| Omet S.R.L. |
| Toscotec S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for servo motor procurement from German suppliers concentrate pricing power with integrated platform vendors who pre-position inventory. Packaging companies leverage consolidated procurement volumes to compress per-unit capital costs on high-speed lines, while fragmented Southeast Asian entrants absorb premium markups on narrow-width configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by automation depth and after-sales bundling. CE marking certification and FDA facility registration tiers add 15-25% premiums over uncertified equipment. Cost compression in standard-tier automatic lines is intensifying because private-label tissue brands squeeze converter margins. Distributors and regional lessors exhibit highest price sensitivity, whereas multinational packaging companies prioritize throughput guarantees over capital cost.
Supply Chain Analysis
China, Germany, and Italy anchor precision component fabrication for converting equipment frames and control systems. Machine builders draw from Japanese servo motor suppliers, Swedish specialty steel mills, and German pneumatic actuator manufacturers. Single-source vulnerability in high-precision folding architecture patents held by Italian heritage suppliers creates supply risk for non-licensed builders. Distribution runs through Hamburg and Shanghai port hubs with rail extensions into Central European and Yangtze River Delta manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among packaging companies that consolidate converting services with downstream fulfillment, squeezing standalone manufacturers on contract duration and price. This consolidation shifts margin capture toward integrated automation platform vendors.
For Market Incumbents: Shield installed base revenue through digital control retrofit kit portfolios that extend legacy line life without full replacement. Deepen backward integration into pneumatic actuator manufacturing to offset Japanese supplier pricing volatility. Capture CE marking pre-certification workflows as a competitive moat against Asian fabricators facing EU Machinery Directive compliance delays. For New Entrants and Emerging Players: Anchor in narrow-width toilet paper lines for Southeast Asian emerging market entrants where incumbent premium suppliers maintain underdeveloped product ranges. Target India's Gujarat industrial belt with semi-automatic configurations that navigate BIS certification delays through local assembly partnerships. Lead with rapid deployment leasing models that compress 12-18 month validation windows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive tissue machinery divisions lacking standalone scale. Five-to-ten year viability hinges on automation platform software recurring revenue ratios exceeding hardware margins. Watch for inflection when EU Green Deal carbon accounting rules redirect capital toward energy-efficient pneumatic architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control Retrofit Kit Expansion | Modular upgrades capture margin from converters avoiding full line replacement capital outlay. |
| Pneumatic System Redesign for REACH Compliance | Dry actuation architectures maintain CE marking eligibility under EU chemical restrictions. |
| Backward Integration into Servo Motor Sourcing | In-house precision drive production insulates margins from commodity price volatility. |
| Narrow-Width Line Localization in Southeast Asia | Compact equipment configurations match emerging market capital thresholds and footprint constraints. |
| Predictive Maintenance Platform Licensing | Software recurring revenue pools expand as after-sales service unbundles in mature markets. |
Study Parameters
A spread of perspectives from plant engineers at tissue converters, procurement leads at packaging companies, aftermarket service heads at machinery OEMs, and regulatory affairs specialists at CE marking bodies converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EU Machinery Directive compliance databases, SAMR GB standard filings, FDA facility registration records, and trade flow data from Hamburg and Shanghai port authorities. Bottom-up equipment shipment tallies triangulated against top-down tissue production capacity estimates across the analysis window.
Segmentation dimensions modeled include automation level, technology architecture, end-user category, application hygiene grade, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, private-label tissue brand expansion rates, and compliance-driven upgrade mandates. Forecast inputs incorporated steel and servo motor input cost trajectories, plus carbon accounting rule implementation timelines under the EU Green Deal.
Material uncertainties — commodity price spikes, certification timeline extensions, and carbon border adjustment mechanisms — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and converter capital allocation priorities. Recalibration cycles align with material shifts in EU Machinery Directive amendments and SAMR GB standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Glue Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Capping Machine Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Confectionery Packaging Machine Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market