
 Latin America Pharmaceutical Plastic Packaging Market | 2026-2036
Latin America Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Plastic Packaging Market Insights
A shift from single-source to multi-source resin procurement is realigning supply security for converters serving Brazilian and Mexican drug makers. Amcor Group Inc leverages its regional film extrusion footprint to sustain just-in-time delivery contracts with large generics producers. Gerresheimer AG anchors its position through specialized barrier polymer expertise for moisture-sensitive oral solids. Berry Global Group Inc competes on scale, operating multiple thermoforming lines that supply blister packs across Central American distribution corridors.
Latin America pharmaceutical plastic packaging encompasses primary and secondary containers fabricated from polyethylene terephthalate, polypropylene, and multilayer barrier films, manufactured via injection molding, blow molding, and thermoforming to ensure product integrity, child resistance, and shelf-life extension for oral, topical, and parenteral dosage forms. Blister packs dominate value capture due to their unit-dose compliance advantages and compatibility with high-speed tropical climate distribution. Rigid bottles maintain volume leadership in liquid and suspension categories, while flexible pouches represent the fastest-growing form segment as contract manufacturing organizations seek lightweight alternatives for single-use overwraps.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce pharmacopeial compatibility and extractables testing standards that determine which polymer grades gain formulary approval, effectively filtering market access for imported and locally converted packaging. These regulators are converging toward ICH Q3D elemental impurity limits, forcing resin suppliers to certify batch-level composition data. Stakeholders must monitor how pending bioequivalence packaging equivalence rules reshape tender specifications for government-procured generics.
Market Dynamics
ANVISA's tightened extractables testing protocols are forcing converters to requalify resin grades, compressing supplier margins while accelerating batch-level traceability investments across Brazilian pharmaceutical corridors.
Growth Catalysts
- Generics procurement expansion:Brazilian government tenders for essential medicines are scaling unit-dose blister pack volumes as domestic manufacturers displace imported finished dosages.
- ICH Q3D convergence:Regional regulators are harmonizing elemental impurity limits, enabling multinational drug makers to deploy unified packaging specifications across Mexico, Colombia, and Brazil.
- Barrier polymer advancement:Cyclic olefin copolymers and multilayer coextrusions are extending shelf stability for moisture-sensitive oral solids in tropical distribution climates.
Market Restraints
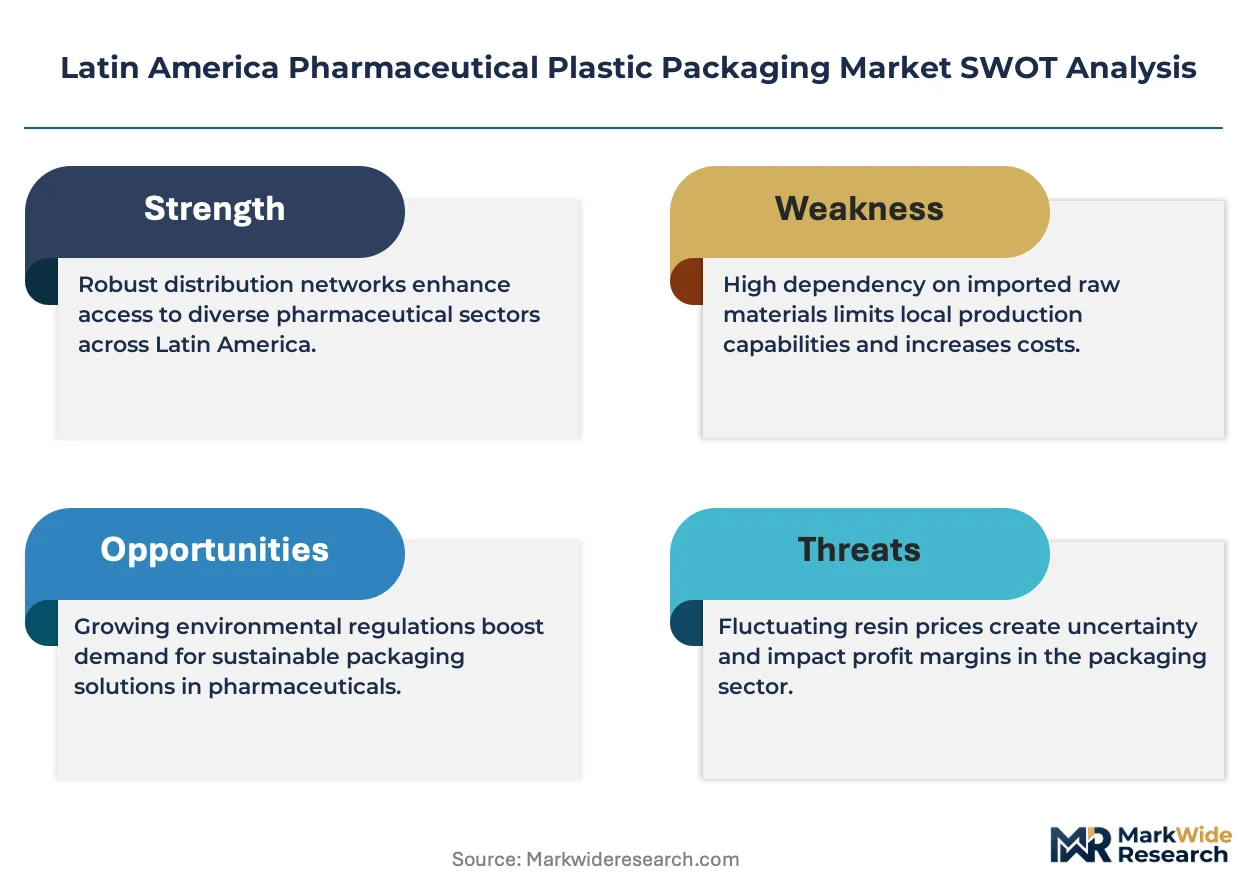
- Resin import dependency:Polypropylene and polyethylene terephthalate supply concentrates in US Gulf Coast and Asian export hubs, exposing converters to freight volatility and currency mismatch.
- Qualification timeline friction:ANVISA's updated stability testing guidelines extend material approval cycles, freezing formulation changes for 18-24 months.
- Glass substitution persistence:Parenteral and high-value biologics segments retain borosilicate vial preference due to polymer extractables uncertainty, capping plastic penetration.
Strategic Opportunities
- Colombian contract manufacturing growth:INVIMA's streamlined bioequivalence pathways are attracting regional CMOs seeking compliant primary packaging for export to Andean Community markets.
- Child-resistant closure innovation:Push-and-turn mechanisms integrated with senior-friendly designs open pediatric and geriatric dosage form segments previously served by non-compliant alternatives.
- Recyclable mono-material structures:ANVISA's draft circular on sustainable procurement creates preferential tender scoring for polyethylene and polypropylene-only blister configurations.
Industry Challenges
- Polymer characterization expertise scarcity:Regional laboratories lack capacity for extractables profiling under USP 1664 and ICH Q3D combined protocols, creating bottlenecks for new supplier qualification.
- Thermoforming line reconfiguration costs:Shifting from PVC-PVdC to polypropylene-based barrier films demands mold redesign and heating profile recalibration, straining mid-scale converter capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Plastic Packaging Market |
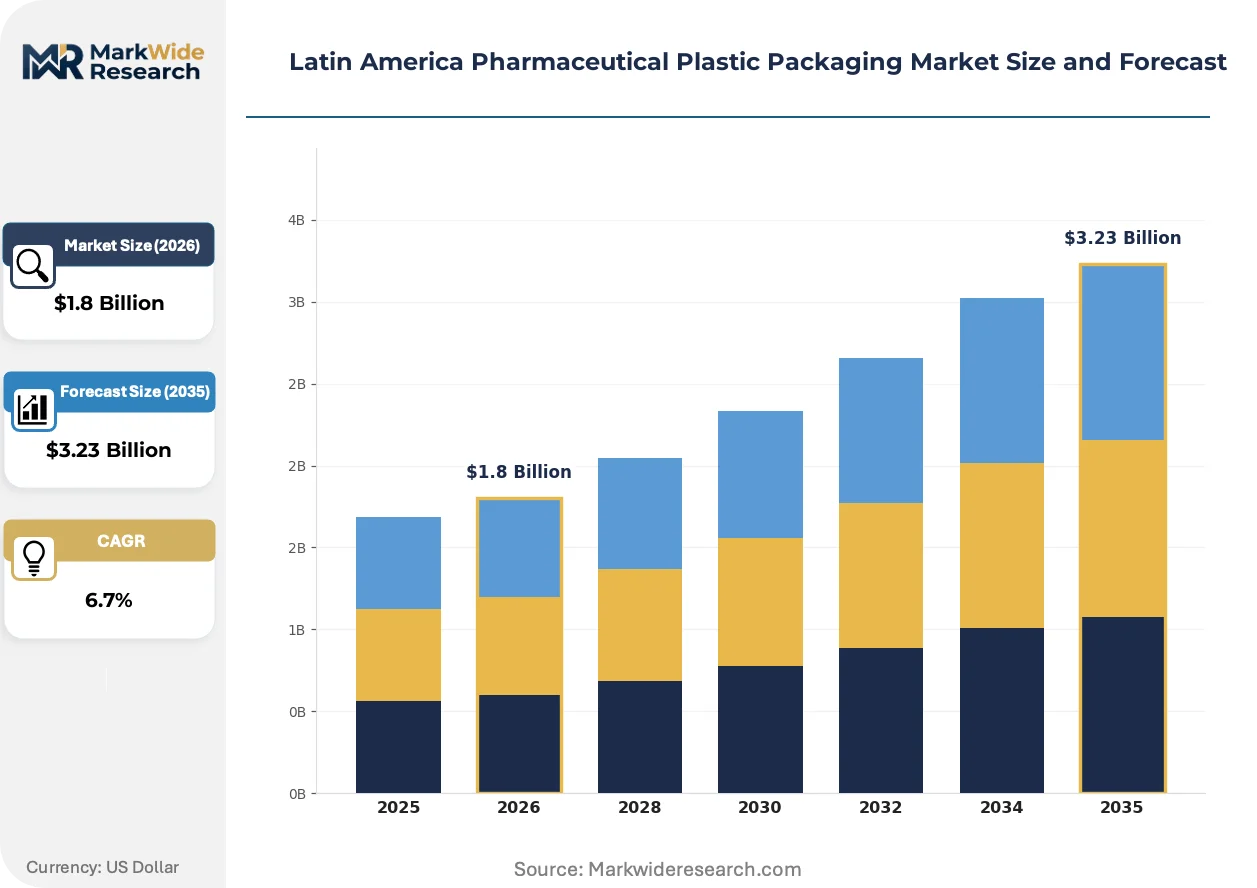
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Containers, Ampoules Form: Rigid, Flexible, Semi-Rigid, Pouches Technology: Injection Molding, Blow Molding, Thermoforming, Compression Molding End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Hospitals, Pharmacies |
| Companies Covered | Amcor Group Inc, Gerresheimer AG, Berry Global Group Inc, ALPLA Group, Klockner Pentaplast Group, Videplast Industria de Embalagens Ltda, Greiner Packaging International GmbH, Plastimax SA, Pretium Packaging, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Plastic Packaging Market Trends and Innovations
Digital track-and-trace integration and sustainable material transitions are restructuring how packaging specifications get written, tested, and procured across Latin American pharmaceutical supply chains.
Cold-chain-qualified multilayer barrier films are overtaking conventional PVC-PVdC laminates in tropical climate distribution. Brazilian generics producers are specifying these structures for high-humidity warehouse corridors. The shift is compressing legacy converter margins while rewarding extrusion capabilities with in-house barrier coextrusion.
ANVISA's pending bioequivalence packaging equivalence rules are tightening primary container change-control documentation. Drug makers must now demonstrate therapeutic equivalence when switching between approved polymer grades. This regulatory friction most affects government tender participants in Brazil, who are consolidating supplier panels to reduce qualification burden.
Buyer concentration among large Brazilian and Mexican generics houses is compressing switching cycles and unbundling technical service from unit pricing. Regional CMOs are consolidating procurement through designated packaging engineering partners rather than transactional converter relationships. This pattern is most visible in São Paulo's pharmaceutical manufacturing corridor, where three domestic drug makers now control majority blister pack specification authority.
Latin America Pharmaceutical Plastic Packaging Market Segmentation
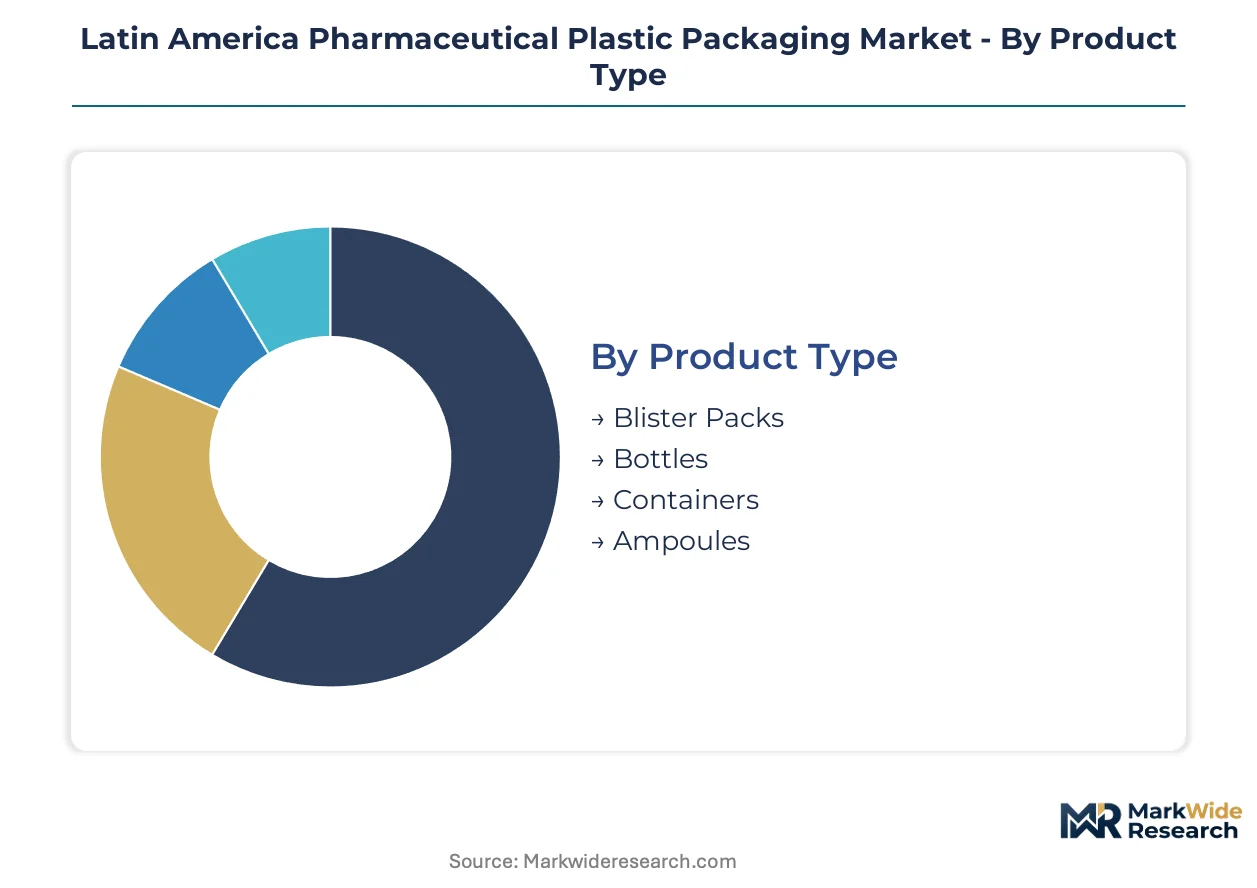
Segmentation in Latin American pharmaceutical plastic packaging reveals how capital deployment, regulatory compliance, and dosage form requirements fragment procurement patterns across converters and drug makers. Understanding these divisions exposes where specification authority concentrates and where margin pressure transfers through supply tiers.
Product Type:
Capital intensity peaks in segments requiring multi-layer coextrusion equipment and barrier film qualification laboratories, with thermoforming lines demanding seven-figure reconfiguration investments when switching resin platforms.
- Blister Packs:Unit-dose configurations fabricated from PVC-PVdC, polypropylene, or cyclic olefin copolymer laminates dominate government generics tenders in Brazil. ANVISA's extractables testing protocols favor established converters with in-house USP 1664 capability, freezing out smaller suppliers during requalification cycles.
- Bottles:High-density polyethylene and polyethylene terephthalate rigid containers serve liquid suspensions and solid oral dosages across Mexican pharmaceutical corridors. Demand concentrates among domestic generics houses scaling production for COFEPRIS-regulated distribution.
- Containers:Wide-mouth polypropylene jars accommodate bulk tablet and capsule dispensing to hospital and pharmacy channels. Specifications prioritize child-resistant closure compatibility over barrier performance.
- Ampoules:Plastic alternatives to glass for parenteral applications remain niche due to polymer extractables uncertainty and biologics manufacturer preference for borosilicate primary containment.
Most installed capacity flows through Blister Packs. Expansion is steepest in Bottles as Brazilian and Mexican liquid dosage production scales.
Form:
Structural rigidity determines distribution resilience across tropical climate corridors, with humidity exposure and temperature cycling dictating material selection for shelf-life extension.
- Rigid:Injection-molded and thermoformed structures provide dimensional stability for high-speed filling lines and automated dispensing systems. Brazilian pharmaceutical manufacturers specify rigid formats for products distributed through the country's northern humidity-exposed warehouse networks.
- Flexible:Multilayer pouches and overwraps reduce freight cost per dose for contract manufacturing organizations exporting to Andean Community markets. INVIMA's streamlined bioequivalence pathways accelerate adoption for regional CMOs.
- Semi-Rigid:Intermediate structures combining thermoformed trays with flexible lidding balance protection and material efficiency for medium-volume specialty pharmaceuticals.
- Pouches:Single-use flexible primary containers represent the fastest-climbing format segment as lightweight alternatives gain traction in clinical trial supply and hospital unit-dose distribution.
Volume leadership sits with Rigid formats. The steepest expansion trajectory belongs to Pouches as logistics cost optimization reshapes procurement specifications.
Technology:
Equipment specialization creates supplier lock-in, with mold design complexity and heating profile optimization demanding process engineering expertise that concentrates among established regional converters.
- Injection Molding:Precision closure and container production requiring high-cavitation tooling and robotic handling systems. Mexican pharmaceutical packaging corridors host the region's densest concentration of multi-cavity injection assets serving COFEPRIS-regulated drug makers.
- Blow Molding:Extrusion and injection blow processes fabricate hollow bottles for liquid and suspension categories. Stretch blow molding of polyethylene terephthalate dominates high-clarity pharmaceutical bottle specifications.
- Thermoforming:Vacuum and pressure forming of blister cavities from roll-fed film stocks. The technology anchors Brazilian generics supply chains where ANVISA-compliant barrier laminates require dedicated forming and sealing stations.
- Compression Molding:Limited pharmaceutical application restricted to specific closure designs and specialty tablet press components, with minimal regional installed base.
Asset utilization peaks in Thermoforming for blister-dominant markets. Technology refresh rates run highest in Injection Molding as multi-material capability becomes mandatory.
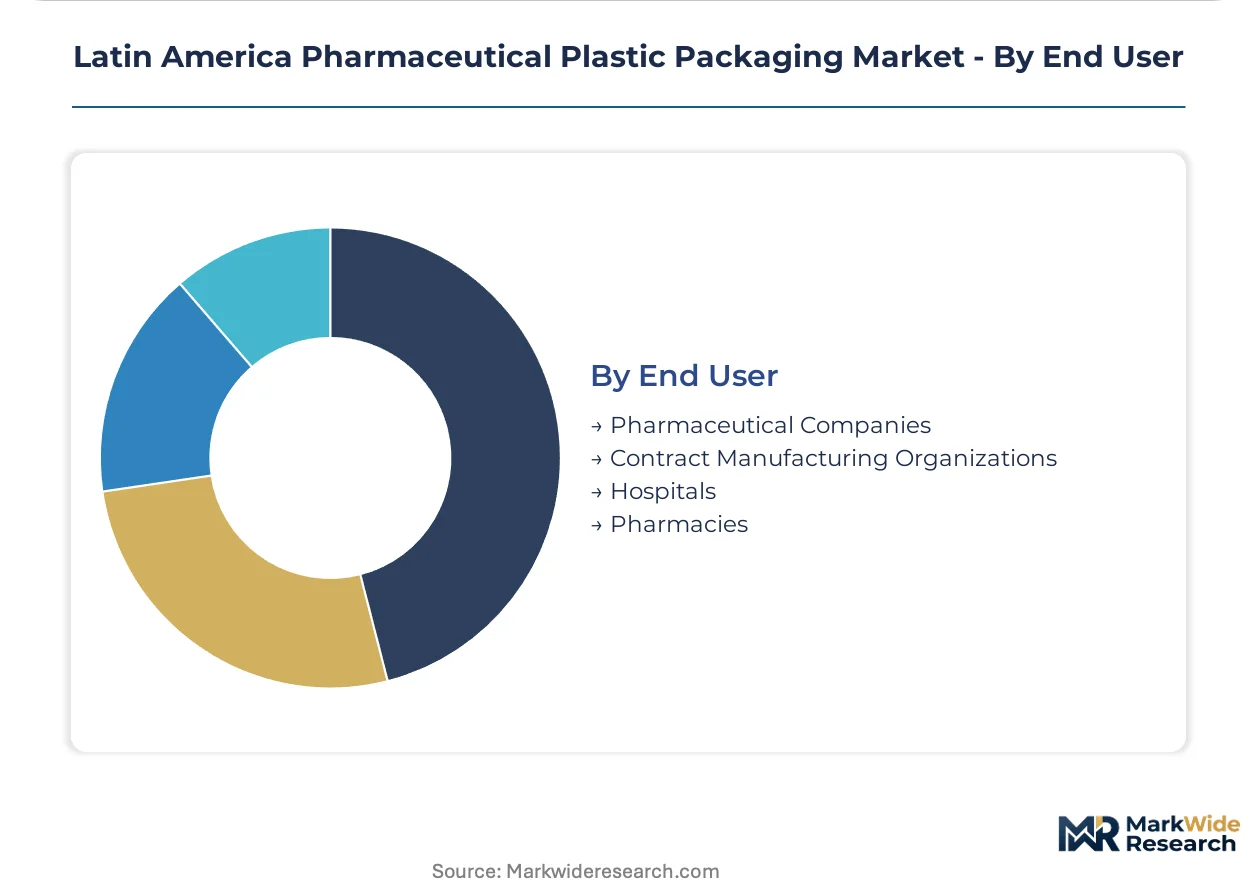
End User:
Procurement authority fragmentation determines specification complexity, with consolidated pharmaceutical houses driving standardization while fragmented pharmacy channels accept converter-catalog offerings.
- Pharmaceutical Companies:Integrated drug makers with internal packaging engineering functions issue detailed material specifications and audit converter quality systems directly. Three Brazilian generics houses now control majority blister pack specification authority in São Paulo's manufacturing corridor.
- Contract Manufacturing Organizations:Regional CMOs consolidating procurement through designated packaging engineering partners rather than transactional converter relationships. Colombian CMOs leverage INVIMA pathways to serve Andean Community export demand.
- Hospitals:Institutional purchasing favors unit-dose compliance packaging and automated dispensing compatibility, with tender structures prioritizing supply security over unit cost minimization.
- Pharmacies:Fragmented retail channel accepting standardized container and closure configurations from converter catalog offerings, with limited specification influence.
Contract Manufacturing Organizations are consolidating procurement fastest. Pharmaceutical Companies retain the tightest specification control and longest qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting pharmaceutical packaging procurement toward jurisdictions where compliance costs and qualification timelines diverge. Brazilian and Mexican converters absorb volume leadership as ANVISA and COFEPRIS protocols mature, while Colombian and Chilean corridors attract contract manufacturing seeking streamlined bioequivalence pathways.
Brazil
Domestic generics manufacturers are displacing imported finished dosages through government essential medicine tenders, driving blister pack specification authority toward São Paulo-based converters. ANVISA's updated stability testing guidelines extend material approval cycles to 18-24 months, freezing formulation changes and consolidating supplier panels. The São Paulo pharmaceutical manufacturing corridor now hosts three domestic drug makers controlling majority blister pack procurement decisions.
Mexico
COFEPRIS-regulated distribution networks are scaling production of liquid suspensions and solid oral dosages, concentrating demand for high-density polyethylene and polyethylene terephthalate rigid bottles. The regulator's convergence toward ICH Q3D elemental impurity limits enables multinational drug makers to deploy unified packaging specifications across North American operations. Mexico City Metro and Nuevo León host the densest concentration of multi-cavity injection molding assets serving domestic generics houses.
Colombia
INVIMA's streamlined bioequivalence pathways are attracting regional contract manufacturing organizations seeking compliant primary packaging for Andean Community export markets. Flexible pouch demand is climbing as logistics cost optimization reshapes procurement specifications for lightweight single-use overwraps. Bogotá-based CMOs are consolidating procurement through designated packaging engineering partners rather than transactional converter relationships.
Chile
Pharmaceutical distribution infrastructure is upgrading cold-chain capabilities, favoring multilayer barrier films over conventional PVC-PVdC laminates for tropical climate resilience. The national pharmaceutical regulator maintains pharmacopeial compatibility standards that filter market access for imported packaging materials. Santiago's logistics corridors are integrating digital track-and-trace systems that tighten primary container change-control documentation requirements.
Argentina
Currency volatility and resin import dependency are compressing converter margins, yet domestic pharmaceutical production maintains steady demand for rigid bottle and container formats. The national health authority enforces extractables testing protocols that favor established suppliers with batch-level traceability systems. Buenos Aires and Córdoba manufacturing clusters are prioritizing polyethylene and polypropylene-only configurations ahead of anticipated sustainable procurement regulations.
Latin America Pharmaceutical Plastic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barrier polymer and sustainable material niches. The market structures around three maturity tiers: multinational converters with regional film extrusion footprints, mid-scale thermoforming specialists serving domestic generics corridors, and emerging local players competing on compliance certification speed. Dominant competitive moves include strategic partnerships with resin suppliers for batch-level composition data and capacity expansion in barrier coextrusion capabilities.
Within the multinational converter tier, Amcor Group Inc and Gerresheimer AG exemplify divergent strategic positions. Amcor leverages regional film extrusion assets to sustain just-in-time delivery contracts with large Brazilian generics producers. Gerresheimer anchors its position through specialized barrier polymer expertise for moisture-sensitive oral solids. Berry Global Group Inc occupies a scale-driven position, operating multiple thermoforming lines that supply blister packs across Central American distribution corridors.
| Leading Market Players |
|---|
| Amcor Group Inc |
| Gerresheimer AG |
| Berry Global Group Inc |
| ALPLA Group |
| Klockner Pentaplast Group |
| Videplast Industria de Embalagens Ltda |
| Greiner Packaging International GmbH |
| Plastimax SA |
| Pretium Packaging |
| Others |
Pricing and Supply Chain Analysis
Specialized polymer characterization chemists in São Paulo command wage premiums that compress converter margins and widen spreads between certified premium-grade blister packs and standard polyethylene containers. Labor-cost differentials between Brazilian barrier-film specialists and Mexican injection-molding corridors feed directly into three-tier pricing stratification across government tender, private-label, and export segments.
Pricing Analysis
Distributor margins on imported cyclic olefin copolymers absorb 12-18 percentage points before reaching Brazilian generics manufacturers, compressing downstream converter profitability. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified barrier laminates from COFEPRIS-compliant standard films and uncertified economy grades. Pricing pressure stems from resin import dependency and currency mismatch, with cost compression running through mid-scale thermoforming converters. Government tender participants exhibit highest price sensitivity due to unbundled technical service requirements, while multinational drug makers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Polypropylene and polyethylene terephthalate resin supply rests on US Gulf Coast petrochemical complexes and South Korean export hubs, exposing Latin American converters to freight volatility and dollar-denominated procurement. Raw material dependencies center on propylene monomer, terephthalic acid, and specialty barrier additives for multilayer coextrusion. Single-source vulnerability concentrates in cyclic olefin copolymer grades qualified under USP 1664 protocols, where batch-level traceability requirements filter supplier pools. Distribution runs through São Paulo and Mexico City pharmaceutical manufacturing corridors before radiating to Andean Community and Central American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American pharmaceutical plastic packaging hinges on backward integration into resin compounding and premium-tier migration toward certified barrier structures for moisture-sensitive oral solids.
For Market Incumbents: Hedge against ANVISA's pending bioequivalence packaging equivalence rules by consolidating supplier panels and capturing batch-level composition data through strategic resin partnerships. Defensive positioning requires in-house USP 1664 extractables profiling capability to freeze out smaller competitors during requalification cycles, while capacity addition in Colombian thermoforming corridors captures INVIMA-streamlined contract manufacturing growth. For New Entrants and Emerging Players: Enter via specialized barrier polymer niches for tropical climate distribution, where established converters lack cyclic olefin copolymer formulation expertise. Colombian CMO procurement consolidation presents the most penetrable entry point, with designated packaging engineering partnerships replacing transactional converter relationships as the dominant go-to-market angle. For Investors and Strategic Acquirers: Mid-scale Brazilian thermoforming specialists with ANVISA certification backlog are the most active acquirer target category in this space, as multinational converters seek regional footprint expansion. Long-term viability over a 5-10 year horizon depends on barrier coextrusion asset ownership and sustainable mono-material qualification speed. The signal to watch is ANVISA's draft circular on sustainable procurement, which would accelerate preferential tender scoring shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures batch-level composition data required under ANVISA's ICH Q3D convergence protocols. |
| Barrier Coextrusion Capacity Expansion | Positions converters for cold-chain-qualified multilayer films overtaking PVC-PVdC in tropical distribution. |
| Sustainable Mono-Material Certification | ANVISA's draft circular creates preferential tender scoring for recyclable polypropylene-only configurations. |
| Strategic Partnership with Regional CMOs | Colombian contract manufacturers are consolidating procurement through designated packaging engineering partners. |
| In-House Extractables Profiling Investment | USP 1664 capability freezes out smaller suppliers during ANVISA's extended material approval cycles. |
Research Methodology
Direct dialogue with pharmaceutical packaging engineers, regulatory affairs specialists at ANVISA and COFEPRIS, generics procurement directors, and thermoforming line operators grounded qualitative findings in operational reality. Secondary validation drew from customs trade databases, SEC filings of multinational converters, pharmacopeial compatibility standards, and resin supplier technical datasheets. Bottom-up and top-down triangulation cross-checked converter capacity estimates against drug maker tender volumes and import substitution trends.
Bottom-up modeling built segment-level projections from individual country regulatory timelines, generics tender award patterns, and resin price elasticity assumptions across the projection horizon. Segmentation dimensions included product type, dosage form, technology platform, and end-user procurement authority. CAGRs were derived from installed capacity utilization rates and qualification cycle durations, with forecast inputs centering on ANVISA stability testing guideline implementation pace and ICH Q3D elemental impurity limit adoption across Latin American regulators.
The model holds under sustained generics procurement expansion and regulatory convergence toward ICH standards; deviation in resin supply disruption severity or bioequivalence packaging equivalence rule timing would shift volume trajectories. A small set of named triggers—ANVISA circular finalization, Colombian CMO export growth inflection, and cyclic olefin copolymer supply concentration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market