
 VCI Shrink Films Market | 2026-2036
VCI Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
VCI Shrink Films Market Analytics
Polyethylene is consolidating its position against PVC in VCI shrink films as converters respond to tighter environmental standards and lower processing costs. Cortec leverages its captive VCI chemistry expertise to anchor North American supply for precision metal shipments. Daubert sustains formulation leadership through in-house corrosion inhibitor synthesis. Oji F-Tex competes on blown film scale and Japanese automotive OEM qualification.
VCI shrink films combine volatile corrosion inhibitor chemistry with heat-activated shrink polymer matrices, typically extruded as 50-150 micron multi-layer structures that release passivating vapor within sealed packaging to prevent ferrous and non-ferrous oxidation during storage and transit. The technology serves manufacturers requiring protective packaging that conforms tightly to irregular metal surfaces while delivering active corrosion control without oils or greases. Polyethylene dominates product type supply due to clarity, sealability, and recyclability advantages over legacy PVC, though polypropylene gains traction in high-temperature automotive underhood applications. Heat shrink technology leads the technology dimension by installed base, yet UV coating variants attract electronics exporters seeking combined corrosion and UV degradation protection for long-haul ocean freight.
EPA regulates volatile organic compound emissions from film converting operations under Clean Air Act standards, while REACH restricts certain amine-based VCI chemistries in European supply chains, forcing reformulation investments. FDA indirect food contact rules shape VCI film selection for food processing equipment exports. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation of VCI chemistries as amine-based inhibitors face restriction, while polyethylene conversion economics accelerate material substitution away from legacy PVC structures.
Growth Catalysts
- Automotive OEM integration:Tier-1 suppliers in Germany's automotive belt demand corrosion protection bundled with conformal packaging for just-in-time parts delivery.
- REACH-driven formulation upgrades:Low-emission polyethylene VCI films capture share as converters retool to meet tightened volatile organic compound limits across European supply chains.
- Yangtze River Delta metalworking density:China's precision machining clusters generate concentrated demand for heat-shrink corrosion protection of high-value ferrous components.
Market Restraints
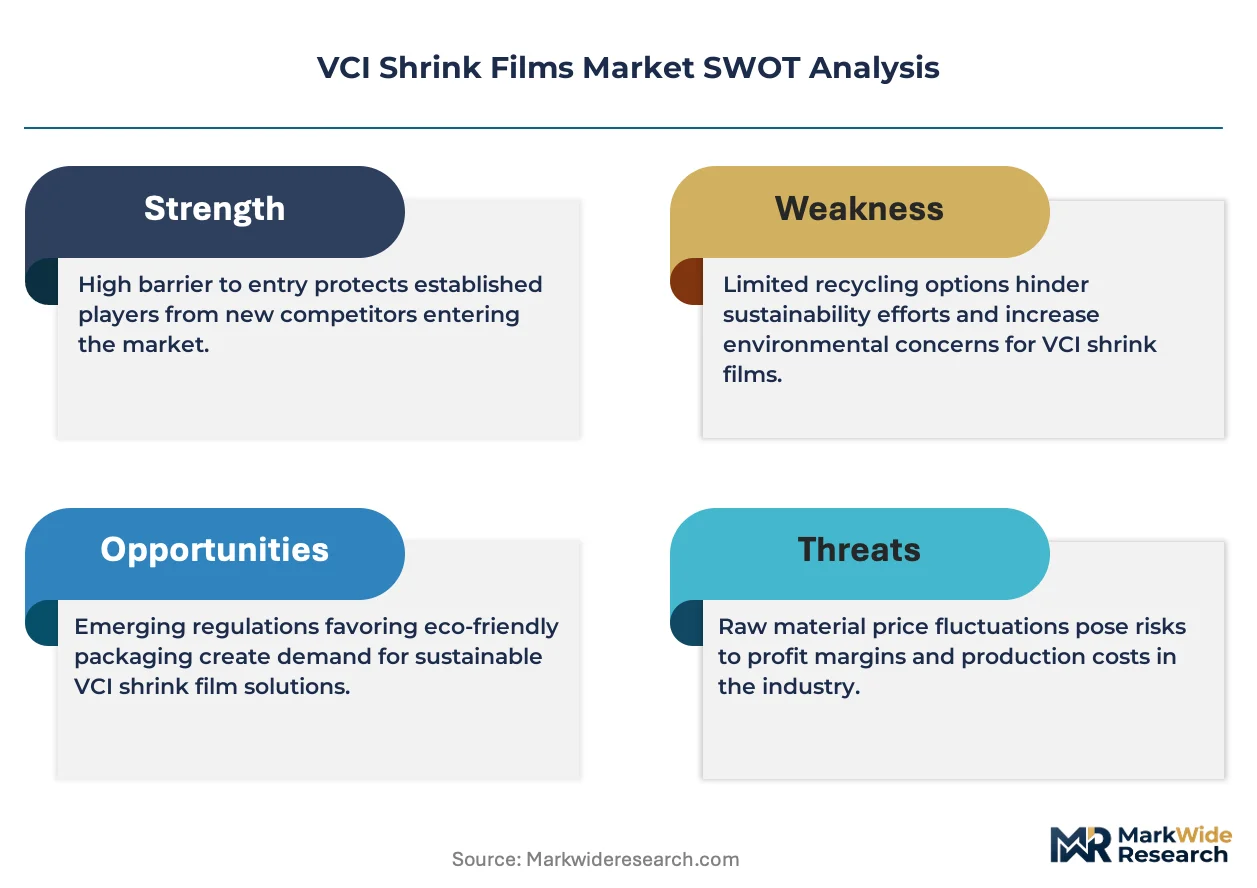
- Petrochemical feedstock volatility:Ethylene and propylene price swings compress converter margins on multi-layer blown film structures.
- Amine chemistry supply concentration:European VCI additive production clusters in Germany and the Netherlands create single-source vulnerability for REACH-compliant formulations.
- Technical performance ceiling:Polyethylene vapor transmission rates limit VCI release kinetics for extended-duration ocean freight beyond 180 days.
Strategic Opportunities
- Indian precision engineering expansion:Pune and Chennai metalworking corridors remain underpenetrated by qualified VCI film suppliers despite accelerating automotive component exports.
- UV-coating convergence:Electronics exporters seek combined corrosion and photodegradation protection for photovoltaic and semiconductor shipments through tropical transshipment ports.
- Japan's carbon-neutral packaging mandates:METI guidelines on recycled content create preferential procurement pathways for bio-based polyethylene VCI structures.
Industry Challenges
- Multi-jurisdiction formulation complexity:Maintaining separate product lines for EPA Clean Air Act compliance and REACH amine restrictions strains R&D bandwidth.
- Blown film equipment reconfiguration:Seven-layer coextrusion lines require seven-figure capital commitments to achieve barrier and optical specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VCI Shrink Films Market |
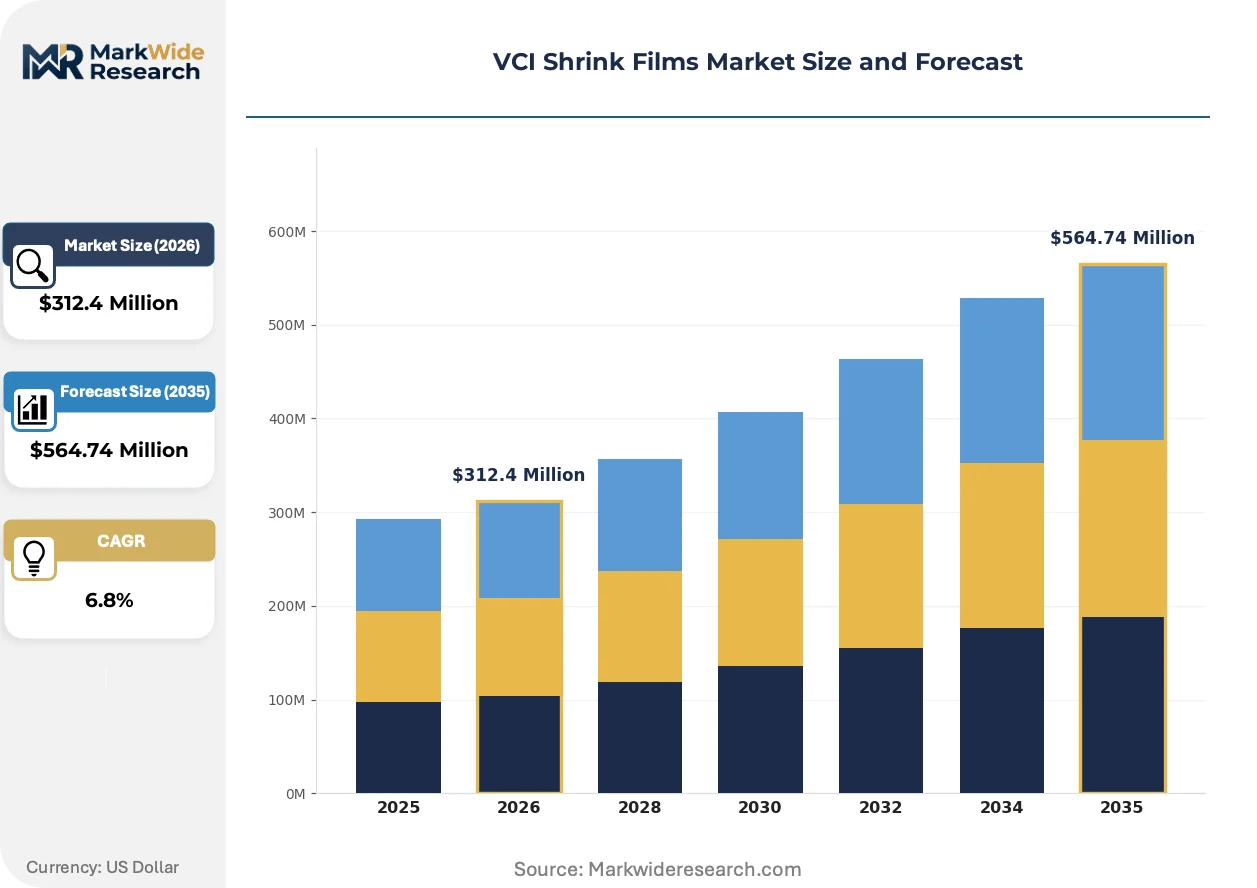
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Automotive Parts, Electronics, Metal Components, Industrial Equipment End User: Manufacturers, Distributors, Retailers, Exporters Technology: Heat Shrink, UV Coating, Anti-Static, Others |
| Companies Covered | Transcendia (Metpro), Oji F-Tex, Cortec, Armor Protective Packaging, Daubert, NTIC (Zerust), Branopac, Rustx, Aicello, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VCI Shrink Films Market Evolving Landscape
Active chemistry and polymer matrix innovations are compressing lead times for corrosion protection while regulatory divergence between jurisdictions forces parallel development tracks.
Polypropylene VCI shrink films are decentralizing high-temperature automotive underhood applications from traditional polyethylene dominance. Powertrain suppliers in Stuttgart and Detroit adopt these structures for engine component packaging where underhood thermal cycling exceeds polyethylene softening points. The shift is fragmenting material specifications across OEM supply bases and forcing converters to maintain dual resin capabilities.
REACH Annex XVII amendments restricting certain nitrite-based VCI chemistries are compelling reformulation investments across European converter operations. The industrial consequence is a 12-18 month qualification cycle for replacement inhibitor systems with equivalent ferrous protection profiles. German automotive packaging specifications are most affected, with BMW and Volkswagen Group suppliers accelerating validation of alternative amine-free vapor-phase inhibitors.
Specification consolidation among Tier-1 metalworking distributors is compressing supplier qualification cycles from 24 months to 12 months in North American and European markets. Buyers increasingly mandate ISO 9227 salt-spray certification and lot-traceable VCI chemistry documentation as table stakes. This behavioral shift is most visible in aerospace fastener and medical instrument supply chains, where end-use liability exposure drives packaging material standardization.
VCI Shrink Films Market Segmentation
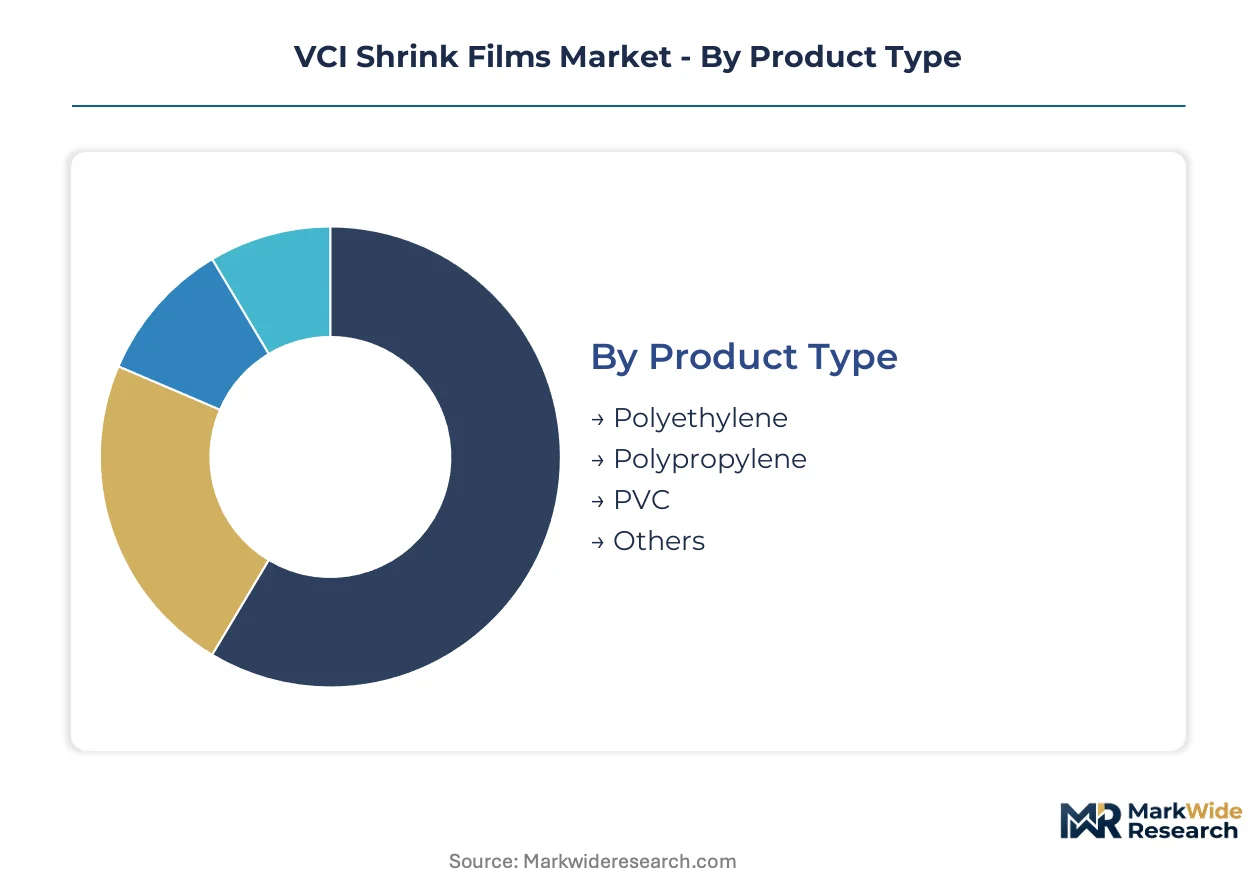
VCI shrink film specifications fragment across resin chemistry, activation mechanism, and end-use thermal requirements. Procurement decisions hinge on vapor transmission kinetics, seal strength thresholds, and regulatory compliance profiles that vary sharply by destination geography.
Product Type:
Resin supply concentrates in polyethylene blown film corridors along the US Gulf Coast and China's Yangtze River Delta, with specialized polypropylene capacity clustering around automotive OEM qualification centers.
- Polyethylene:Linear low-density formulations dominate multi-layer coextrusion for clarity and heat-seal response. Germany's automotive belt and Shanghai precision metalworking clusters specify this grade for 90% of heat-shrink corrosion protection applications.
- Polypropylene:Higher softening points accommodate engine component packaging where underhood thermal cycling exceeds polyethylene limits. Stuttgart and Detroit powertrain suppliers drive qualification cycles for this resin.
- PVC:Legacy formulations persist in cost-sensitive industrial equipment packaging where recyclability mandates are absent.
- Others:Bio-based polyethylene trials are accelerating under Japan METI carbon-neutral procurement guidelines.
Today's leader: Polyethylene. Tomorrow's challenger: Polypropylene.
Application:
Demand intensity tracks metalworking value density, with precision ferrous components commanding premium VCI specifications over bulk industrial equipment.
- Automotive Parts:Just-in-time delivery requirements bundle corrosion protection with conformal packaging for irregular geometries. BMW and Volkswagen Group suppliers in Germany enforce ISO 9227 salt-spray certification as table stakes.
- Metal Components:High-value ferrous machining from China's Yangtze River Delta generates concentrated heat-shrink demand for 180-day ocean freight protection.
- Electronics:Photovoltaic and semiconductor exporters seek combined VCI and UV degradation resistance through tropical transshipment corridors.
- Industrial Equipment:Heavy machinery OEMs prioritize puncture resistance over vapor-phase kinetics for domestic distribution.
Automotive applications command specification premiums. Electronics represents the steepest expansion trajectory.
End User:
Procurement authority concentrates with manufacturers integrating packaging into production workflows, while exporters face the most complex multi-jurisdiction formulation requirements.
- Manufacturers:Tier-1 metalworking operations in Pune and Chennai specify lot-traceable VCI chemistry documentation for aerospace fastener and medical instrument liability coverage.
- Exporters:Electronics and automotive shipments through Rotterdam and Singapore require dual-compliant formulations satisfying both EPA Clean Air Act and REACH amine restrictions.
- Distributors:Specification consolidation compresses supplier qualification cycles from 24 months to 12 months across North American aerospace supply chains.
- Retailers:Minimal direct procurement; specifications flow through private-label packaging converters.
Manufacturers retain technical specification control. Exporters face the fastest-rising compliance burden.
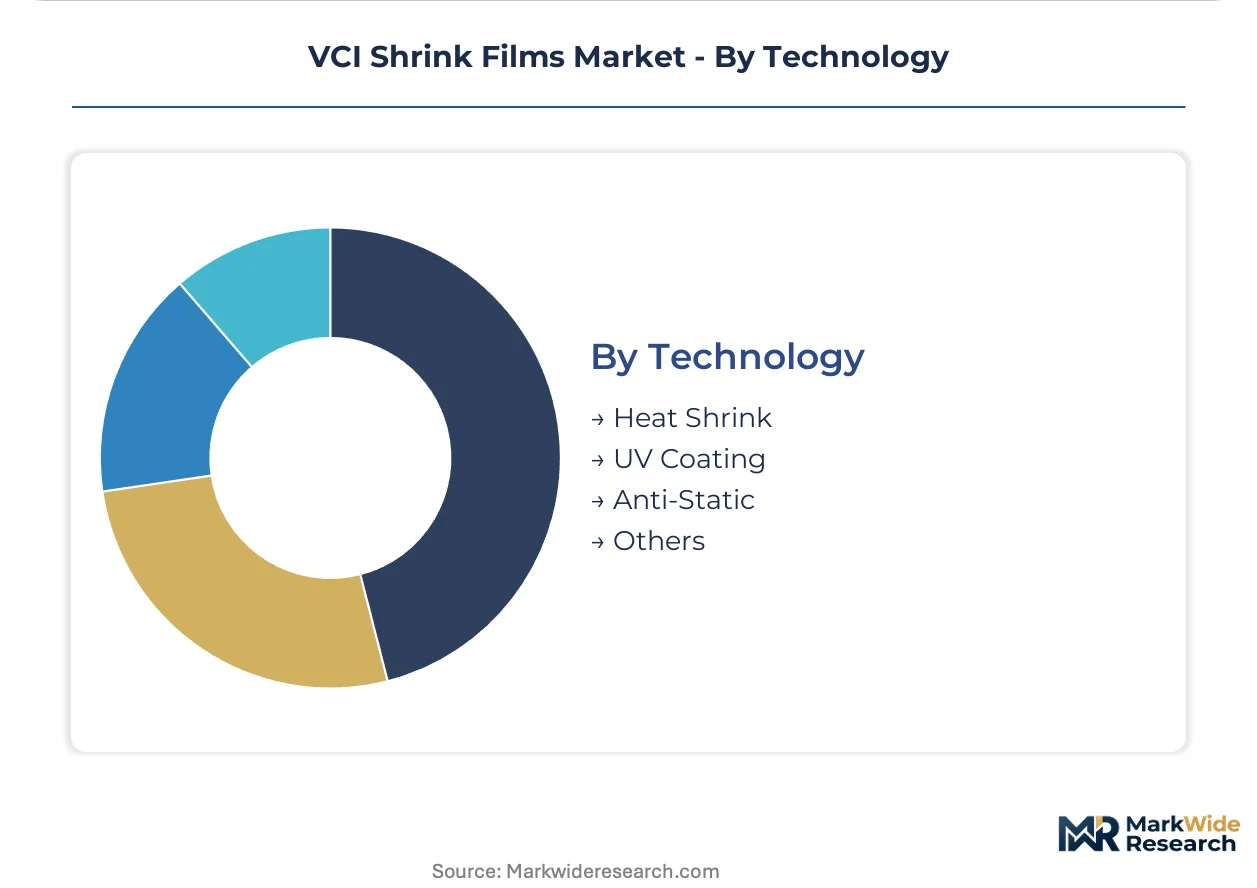
Technology:
Installed base favors heat activation, while coating convergence addresses multi-threat protection requirements for extended-duration logistics.
- Heat Shrink:Blown film extrusion at 50-150 micron thickness delivers conformal sealing with controlled VCI vapor release kinetics. This technology anchors European and Asian supply for standard corrosion protection.
- UV Coating:Combined photodegradation and corrosion resistance serves photovoltaic module exporters through high-UV tropical ports. Japanese electronics OEMs are accelerating validation cycles.
- Anti-Static:Surface resistivity specifications protect semiconductor wafer shipments from electrostatic discharge during automated handling.
- Others:Oxygen-scavenging layers and moisture-activated VCI release remain niche for pharmaceutical equipment packaging.
Heat Shrink maintains volume dominance. UV Coating gains share fastest in electronics logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive belt concentrates precision metalworking demand that drives VCI shrink film specification premiums across European supply chains.
Germany
BMW and Volkswagen Group suppliers enforce ISO 9227 salt-spray certification as mandatory procurement criteria for Tier-1 packaging materials. REACH Annex XVII amendments restricting nitrite-based VCI chemistries compel 12-18 month reformulation cycles across converter operations. Stuttgart powertrain clusters accelerate polypropylene qualification for engine component packaging exceeding polyethylene thermal limits.
United States
Precision metal shipments from Great Lakes manufacturing corridors sustain demand for multi-layer blown film structures with lot-traceable VCI chemistry documentation. EPA Clean Air Act standards regulate volatile organic compound emissions from film converting operations in Ohio and Michigan industrial zones. Detroit automotive packaging specifications fragment material requirements between standard corrosion protection and high-temperature underhood applications.
China
Yangtze River Delta precision machining clusters generate concentrated demand for heat-shrink corrosion protection of high-value ferrous components in 180-day ocean freight configurations. MEE enforcement of dual carbon goals pressures converters toward lower-emission polyethylene formulations. Shanghai metalworking exporters navigate multi-jurisdiction compliance requirements for shipments through Rotterdam and Singapore transshipment hubs.
Japan
METI carbon-neutral packaging guidelines create preferential procurement pathways for bio-based polyethylene VCI structures serving electronics and automotive OEMs. Kanto region semiconductor equipment manufacturers specify combined anti-static and corrosion-resistant films for automated handling environments. Nagoya automotive supplier networks maintain stringent qualification cycles for vapor-phase inhibitor documentation.
India
Pune and Chennai metalworking corridors remain underpenetrated by qualified VCI film suppliers despite accelerating automotive component exports to European and North American markets. BIS standards for packaging materials shape converter investment priorities in Maharashtra and Tamil Nadu industrial zones. Aerospace fastener manufacturers in Bengaluru specify lot-traceable VCI chemistry for medical instrument and aviation component liability coverage.
VCI Shrink Films Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and automotive OEM qualification pathways. Market structure consolidates around captive VCI chemistry capabilities and blown film scale economics, with three distinct tiers emerging: integrated chemistry-polymer specialists, regional converter networks, and niche application developers. Strategic moves center on REACH-compliant reformulation investments and seven-layer coextrusion capacity expansion to capture specification premiums.
Within the integrated chemistry tier, Cortec and Daubert exemplify North American formulation leadership through in-house corrosion inhibitor synthesis capabilities. Oji F-Tex anchors Asian supply dynamics through Japanese automotive OEM qualification pathways and blown film manufacturing scale. These three companies represent contrasting archetypes: chemistry-captive specialists leveraging proprietary VCI knowledge, and scale-driven converters competing on multi-layer extrusion capacity and regional logistics density.
| Leading Market Players |
|---|
| Transcendia (Metpro) |
| Oji F-Tex |
| Cortec |
| Armor Protective Packaging |
| Daubert |
| NTIC (Zerust) |
| Branopac |
| Rustx |
| Aicello |
| Others |
Value Network & Pricing Analysis
Seven-layer coextrusion specialists in Germany's automotive belt command wage premiums that widen spreads between ISO 9227-certified premium tiers and uncertified economy alternatives. Labor-cost differentials between European converter corridors and Yangtze River Delta manufacturing clusters directly feed pricing stratification across REACH-compliant and standard formulations.
Pricing Analysis
Input-cost pass-through from ethylene and propylene volatility dominates pricing dynamics for multi-layer blown film structures. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9227-certified automotive specifications from industrial equipment grades. Cost compression in standard polyethylene tiers is intensifying because of feedstock price swings and converter margin pressure. Distributors and bulk industrial equipment buyers exhibit highest price sensitivity, while aerospace fastener and medical instrument manufacturers accept premium tiers for liability coverage.
Supply Chain Analysis
Certification and qualification gating through BMW and Volkswagen Group supplier programs restricts viable sourcing to a narrow tier of chemistry-captive converters. Supply concentrates in Germany, China, and the United States, with blown film capacity clustering around automotive OEM qualification centers. Raw material dependencies center on ethylene and propylene feedstocks, nitrite-free VCI additive packages, and seven-layer coextrusion equipment. Single-source vulnerability for REACH-compliant amine-free inhibitor formulations in Germany and the Netherlands creates supply chain risk. Distribution runs through Tier-1 metalworking distributors and direct automotive supplier contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in VCI shrink films rests on polyethylene conversion economics displacing legacy PVC structures and premium-tier capture of automotive qualification pathways.
For Market Incumbents: Lock in automotive OEM relationships through accelerated polypropylene qualification for underhood thermal applications. Secure backward integration into nitrite-free VCI additive synthesis to defend against REACH-driven reformulation costs and supply concentration risks in European chemistry clusters. For New Entrants and Emerging Players: Tier-1 distributors in underpenetrated Indian metalworking corridors represent the most accessible channel partner type for market entry. Target Pune and Chennai precision engineering clusters with REACH-compliant formulations and accelerated 12-month qualification cycles. Pursue joint development agreements with semiconductor equipment manufacturers seeking combined anti-static and corrosion-resistant films. For Investors and Strategic Acquirers: Specialty chemical companies with corrosion inhibitor synthesis capabilities are the most active acquirer in this space, seeking packaging integration to capture specification premiums. Five-to-ten year viability favors converters with captive VCI chemistry and seven-layer coextrusion scale. Watch for METI carbon-neutral procurement guideline expansion as signal for bio-based polyethylene VCI structure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | BMW and Volkswagen Group suppliers mandate amine-free vapor-phase inhibitors, forcing 12-18 month validation cycles. |
| Seven-Layer Coextrusion Capacity Expansion | Barrier and optical specifications for automotive packaging require seven-figure capital commitments at converter operations. |
| Backward Integration into VCI Chemistry | Cortec and Daubert demonstrate margin protection through in-house corrosion inhibitor synthesis capabilities. |
| Polypropylene Qualification for Underhood Applications | Stuttgart and Detroit powertrain suppliers specify higher softening points exceeding polyethylene thermal limits. |
| UV-Coating Convergence Development | Japanese electronics OEMs validate combined photodegradation and corrosion resistance for tropical transshipment. |
Research Methodology
Direct dialogue with blown film plant managers, automotive Tier-1 procurement leads, VCI chemistry R&D directors, and metalworking distribution channel partners anchored qualitative findings. Secondary validation drew from ECHA REACH filings, EPA Clean Air Act enforcement data, SEC 10-K disclosures from packaging converters, and customs trade records for ethylene and propylene derivatives. Bottom-up demand modeling across resin chemistry, activation mechanism, and end-use thermal requirements triangulated with top-down market sizing.
Segment-level value outputs tracked polyethylene, polypropylene, and PVC formulations across heat-shrink, UV-coating, and anti-static technologies through the projection horizon. Modeled dimensions included resin chemistry tier, automotive versus electronics versus industrial end-use, and regional regulatory compliance clusters. CAGRs derived from elasticity-adjusted demand curves incorporating OEM production forecasts and VCI film content per shipment. Key inputs encompassed ethylene price trajectories, REACH Annex XVII amendment timelines, and automotive qualification cycle durations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and regulatory divergence between EPA and ECHA jurisdictions. Forecasts reflect documented assumptions on substitution elasticities and qualification cycle completion rates. A model refresh is warranted upon material change in REACH amine restriction enforcement or METI carbon-neutral procurement mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Nigeria Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Lidding Foil Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Brazil Packaging Market