
 Heat Sealing Equipment Market | 2026-2036
Heat Sealing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sealing Equipment Market Foresight
A shortage of certified packaging automation technicians is unwinding capacity expansion timelines across European and North American manufacturing bases. Bosch Packaging Technology leverages its vertically integrated service network to sustain long-term equipment contracts with multinational food processors. Multivac anchors its position through deep specialization in vacuum sealing systems for protein packaging lines. Illinois Tool Works competes by controlling aftermarket parts distribution, which locks in recurring revenue streams from installed base maintenance.
Heat sealing equipment employs controlled thermal energy, typically between 100°C and 300°C, to fuse thermoplastic films and form hermetic seals critical for product preservation and contamination prevention. The equipment serves primary industrial functions across pouch packaging, tray sealing, and bag sealing operations where oxygen exclusion and moisture barriers determine shelf stability. Impulse sealers dominate entry-level and mid-volume installations due to lower energy consumption and reduced thermal mass requirements. Ultrasonic sealing technology represents the fastest-expanding segment as manufacturers eliminate heat-dependent consumables and achieve narrower seal widths for material savings. Vacuum sealers command premium positioning within the medical devices end-user segment where sterility maintenance and package integrity validation carry regulatory weight.
FDA enforces seal-strength validation under 21 CFR Part 820 quality system regulations for medical device packaging, while EU MDR and REACH compliance frameworks mandate material traceability and chemical safety documentation for sealing films and consumables. These overlapping requirements compel equipment vendors to integrate real-time seal verification, audit logging, and material certification workflows directly into machine control architectures. Stakeholders must evaluate how pending packaging waste directives and extended producer responsibility schemes will reshape equipment specifications and retrofit obligations across their installed base portfolios.
Market Dynamics
Ultrasonic sealing technology is bifurcating the installed base between heat-dependent legacy systems and energy-efficient alternatives, forcing equipment vendors to reengineer service architectures and parts inventories around dual technology footprints.
Growth Catalysts
- EU MDR seal-integrity mandates:Medical device packaging lines across Germany and France require validated thermal sealing with audit-trail documentation, driving replacement demand for compliant equipment.
- China's pharmaceutical packaging clusters:Domestic vaccine and biologics manufacturers are scaling automated pouch sealing capacity to serve export markets under WHO prequalification standards.
- Impulse sealer energy efficiency:Reduced thermal mass requirements cut operating costs for mid-volume food processors in India's snack packaging corridor.
Market Restraints
- Copper and aluminum price volatility:Heating element raw material costs swing with commodity markets, compressing margins on entry-level impulse sealers.
- Technician certification scarcity:European packaging automation specialists require 18-24 month training pipelines, extending commissioning timelines for new installations.
- Ultrasonic transducer supply concentration:Piezoelectric component sourcing clusters in Japan and South Korea create single-point vulnerability for non-heat sealing equipment.
Strategic Opportunities
- India's pharmaceutical packaging expansion:CDSCO compliance requirements for sterile barrier systems create demand for vacuum sealing equipment with integrated seal-strength verification.
- EU Green Deal packaging waste directives:Extended producer responsibility schemes incentivize equipment retrofits for mono-material film compatibility.
- Remote diagnostics convergence:IoT-enabled seal monitoring combined with predictive maintenance algorithms unlocks subscription revenue from installed base service contracts.
Industry Challenges
- FDA 21 CFR Part 820 validation timelines:Medical device packaging lines require 6-12 month qualification periods for seal-strength protocols, delaying revenue recognition.
- Legacy PLC integration complexity:Brownfield food processing facilities operate 15-20 year-old control architectures that resist seamless connectivity with modern sealing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sealing Equipment Market |
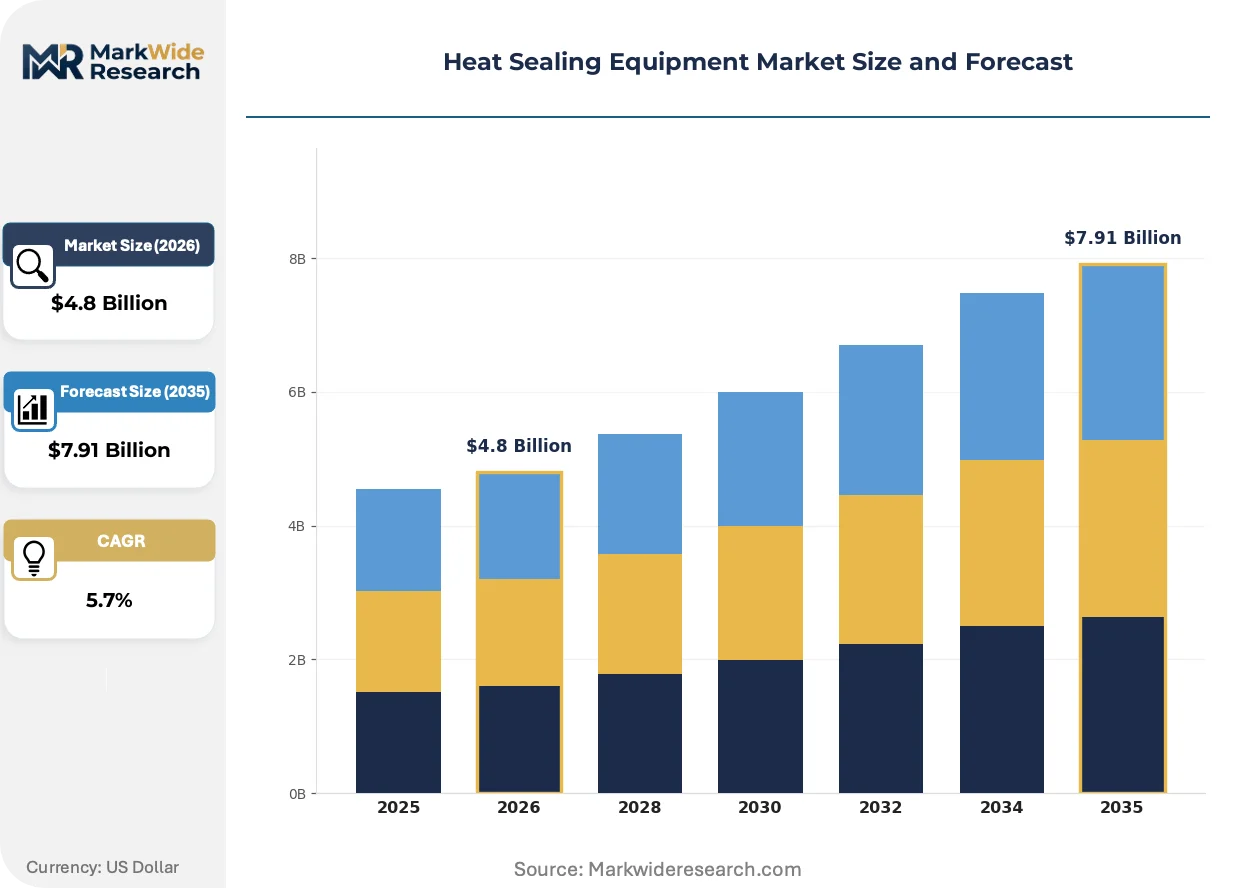
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impulse Sealers, Constant Heat Sealers, Vacuum Sealers, Band Sealers Technology: Ultrasonic Sealing, Laser Sealing, Hot Air Sealing, Radio Frequency Sealing End User: Food Packaging, Electronics, Medical Devices, Retail Application: Pouch Packaging, Tray Sealing, Bag Sealing, Tube Sealing |
| Companies Covered | Bosch Packaging Technology, PAC Machinery, Multivac, Barry-Wehmiller Companies, Pro Mach, Audion Elektro, GEA Group, Illinois Tool Works, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sealing Equipment Market Shifts & Advancements
Equipment architectures are pivoting from standalone thermal systems toward integrated validation platforms that embed compliance documentation directly into production workflows.
Ultrasonic sealing technology is bifurcating the competitive landscape between incumbent heat-sealing vendors and specialized ultrasonic equipment suppliers. Medical device manufacturers in Switzerland and Germany are adopting ultrasonic systems at accelerated rates to eliminate heat-dependent consumables and achieve narrower seal widths. This technology shift is compressing addressable market share for traditional impulse and continuous band sealers in premium packaging segments.
REACH chemical safety documentation requirements are forcing equipment vendors to integrate material certification workflows into machine control systems. Sealing film suppliers must now provide full substance traceability, and equipment interfaces must capture and store this data for audit purposes. Pharmaceutical packaging lines in the Netherlands and Belgium are most affected, with manufacturers retrofitting existing equipment with barcode scanning and database connectivity modules.
Buyer consolidation among multinational food processors is compressing equipment procurement cycles and demanding standardized platforms across multiple production sites. Procurement teams at major protein packaging operations now mandate cross-facility parts commonality and unified training protocols. This behavioral shift is most visible in China's industrial zones, where central engineering teams specify equipment architectures for dozens of regional plants simultaneously.
Heat Sealing Equipment Market Segmentation
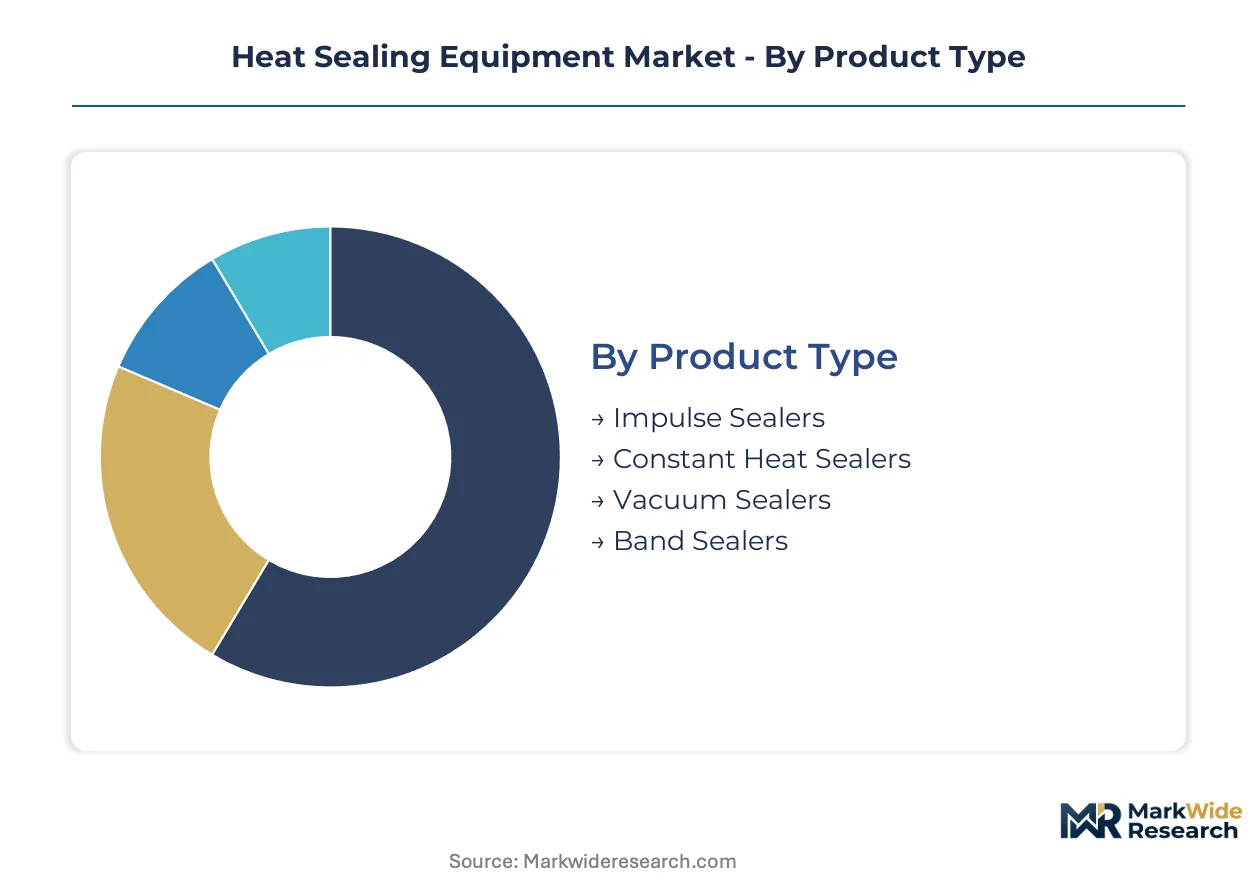
Equipment differentiation across product types, technologies, and end-use applications determines competitive positioning and margin capture in heat sealing markets. Segmentation reveals where capital deployment concentrates and which technology transitions are compressing legacy revenue pools.
Product Type:
Margins concentrate in vacuum sealing systems where sterility validation requirements and medical-grade certification create pricing power. Impulse sealers compete on volume economics in food processing corridors.
- Impulse Sealers:Heating elements activate only during sealing cycles, cutting energy consumption versus continuous thermal systems. Demand clusters in India's snack packaging belt where mid-volume processors prioritize operating cost reduction over throughput speed.
- Vacuum Sealers:Integrated vacuum drawdown and hermetic seal formation protect oxygen-sensitive medical devices and protein products. German and Swiss pharmaceutical packaging lines specify these systems under EU MDR seal-integrity mandates, sustaining premium positioning despite longer procurement cycles.
- Constant Heat Sealers:Continuously heated jaws deliver high-throughput sealing for homogeneous film structures.
- Band Sealers:Conveyor-fed continuous sealing suits bulk powder and grain bagging operations.
Impulse sealers hold installed capacity. Vacuum sealers are rotating up the share rankings.
Technology:
Technology selection maps directly to material compatibility requirements and regulatory compliance burdens across end-use segments.
- Ultrasonic Sealing:High-frequency mechanical vibration generates localized molecular friction without thermal mass, eliminating heat-dependent consumables. Medical device manufacturers in Switzerland and Germany are adopting these systems to achieve narrower seal widths and reduce material waste under REACH documentation requirements.
- Laser Sealing:Focused infrared energy enables non-contact sealing of heat-sensitive substrates and micro-scale packages. Electronics packaging lines in South Korea and Japan deploy laser systems for semiconductor barrier films where thermal distortion risks component damage.
- Hot Air Sealing:Directed heated air stream seals thick-gauge industrial films and woven polypropylene.
- Radio Frequency Sealing:Dielectric heating polarizes molecular dipoles in PVC and polar polymers for medical bag and inflatable product fabrication.
Hot air sealing dominates legacy installed base. Ultrasonic sealing is climbing the fastest.
End User:
End-user concentration reflects regulatory intensity and packaging automation maturity across industrial corridors.
- Food Packaging:Protein processors and ready-meal manufacturers drive band and tray sealing demand. China's industrial zones are scaling automated sealing lines to serve domestic retail consolidation and export cold-chain requirements.
- Medical Devices:Sterile barrier validation and FDA 21 CFR Part 820 compliance create equipment specification rigidity. Vacuum sealing with integrated seal-strength verification is expanding in the Netherlands and Belgium as REACH film traceability mandates intensify.
- Electronics:Moisture barrier bags and anti-static packaging protect semiconductors during global distribution.
- Retail:Private-label and e-commerce fulfillment operations specify impulse sealers for polybag and pouch closure.
Food packaging anchors volume demand. Medical devices is gaining share fastest.
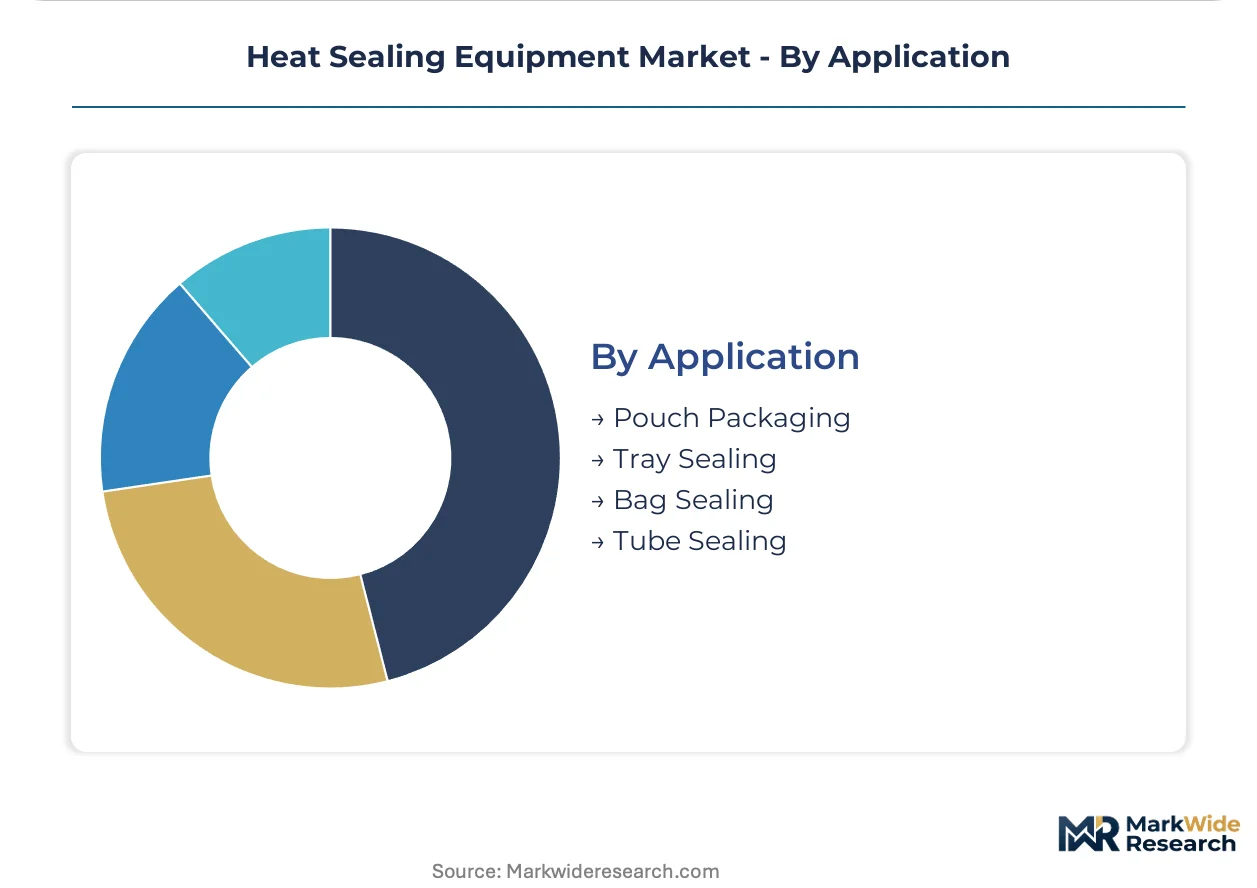
Application:
Application segmentation tracks format evolution in flexible packaging and the automation requirements of each form factor.
- Pouch Packaging:Stand-up and flat pouches require precise seal alignment and gas-flush compatibility for extended shelf life. India's pharmaceutical packaging clusters are scaling automated pouch sealing capacity under CDSCO sterile barrier requirements for vaccine export markets.
- Tray Sealing:Modified atmosphere packaging for fresh proteins demands hermetic seal integrity under vacuum or gas-flush conditions. German food processors specify tray sealers with real-time leak detection to comply with EU food contact material regulations.
- Bag Sealing:Open-mouth bag closure spans agricultural commodities through industrial chemicals.
- Tube Sealing:Cosmetic and pharmaceutical squeeze tubes require crimp or thermal seal integrity for product preservation.
Bag sealing holds legacy capacity. Pouch packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA seal-integrity mandates for medical device packaging anchor demand concentration in the United States, while China's pharmaceutical manufacturing corridors and Germany's precision packaging clusters drive equipment procurement cycles across three continents.
United States
FDA 21 CFR Part 820 validation requirements for sterile barrier systems sustain replacement demand across Minnesota and Massachusetts medical device corridors. The agency's quality system regulations compel manufacturers to document seal-strength protocols with 6-12 month qualification timelines. Boston-area biologics packaging operations are retrofitting legacy thermal sealing lines with real-time verification modules to accelerate compliance documentation.
Germany
EU MDR seal-integrity mandates and REACH chemical traceability requirements converge on pharmaceutical packaging lines in Bavaria and Baden-Württemberg. The country's medical technology sector specifies vacuum sealing equipment with integrated audit-logging capabilities for export certification. Stuttgart-area protein processors deploy tray sealers with leak-detection sensors to satisfy EU food contact material regulations under intensifying enforcement.
China
NMPA regulatory alignment with WHO prequalification standards accelerates automated pouch sealing deployment across Yangtze River Delta vaccine manufacturing clusters. The agency's sterile barrier requirements for biologics exports drive specification rigidity in Shanghai and Suzhou pharmaceutical corridors. Domestic snack packaging operations in Shandong Province scale impulse sealer installations to serve retail consolidation and cold-chain expansion.
India
CDSCO compliance requirements for sterile barrier systems create demand concentration in Maharashtra and Gujarat pharmaceutical packaging belts. The regulator's vaccine export certification protocols mandate vacuum sealing equipment with seal-strength verification for prequalified manufacturers. Mumbai-area contract packaging organizations are commissioning automated lines to capture WHO-prequalified supplier status for African and Southeast Asian markets.
Switzerland
Swissmedic medical device packaging regulations and REACH film documentation requirements sustain premium equipment positioning in Basel and Zurich precision manufacturing corridors. The country's pharmaceutical cluster specifies ultrasonic sealing systems to eliminate heat-dependent consumables and achieve material waste reduction. Geneva-area medical device manufacturers are validating narrow-seal-width protocols for biologics primary packaging under intensifying EU MDR alignment pressure.
Heat Sealing Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-engineering specialists commanding premium positioning in medical-grade segments while volume fabricators compete on energy efficiency in food packaging corridors. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive aftermarket networks, specialized sealing equipment pure-plays with deep application expertise, and regional fabrication houses serving price-sensitive mid-volume processors. Competitive intensity centers on M&A activity consolidating service capabilities and strategic partnerships securing piezoelectric component supply for ultrasonic technology transitions.
Among diversified industrial conglomerates, Bosch Packaging Technology and Illinois Tool Works exemplify archetypes anchored by aftermarket control and vertically integrated service architectures. Multivac occupies a specialist position within vacuum sealing system design. These three entities represent distinct competitive vectors: conglomerate scale with recurring revenue lock-in, precision-engineering depth in sterility-critical applications, and technology-specific specialization capturing medical device procurement cycles.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| PAC Machinery |
| Multivac |
| Barry-Wehmiller Companies |
| Pro Mach |
| Audion Elektro |
| GEA Group |
| Illinois Tool Works |
| Krones AG |
| Others |
Supply & Pricing Matrix
Capacity utilization rates above 85% in German and Japanese precision component foundries compress price floors for vacuum sealing systems while simultaneously concentrating supply leverage among heat element and piezoelectric transducer specialists. This scale asymmetry forces mid-volume food packaging equipment vendors to absorb commodity volatility or cede share to vertically integrated conglomerates with captive aftermarket networks.
Pricing Analysis
Price spreads between German-engineered vacuum sealers and Chinese-fabricated impulse units span three-to-one ratios across identical throughput specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade — FDA-validated medical systems command 40-60% premiums over CE-marked food-grade equivalents. Cost compression in entry-level impulse sealers intensifies because copper and aluminum heating element prices swing with commodity markets. Mid-volume Indian snack processors exhibit highest price sensitivity, while Swiss pharmaceutical contract manufacturers prioritize seal-integrity validation over capital expenditure minimization.
Supply Chain Analysis
Piezoelectric transducer sourcing clusters in Japan and South Korea create single-point vulnerability for ultrasonic sealing equipment manufacturers expanding capacity. Heating element fabrication draws from German precision wire specialists and Chinese commodity metalworkers, with seal jaw machining concentrated in Bavaria and Shanghai industrial zones. Tariff exposure on aluminum rod and copper coil imports into European assembly plants threatens margin stability for entry-level equipment vendors. Distribution runs through OEM-direct sales for medical-grade systems and regional distributor networks for food packaging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrasonic technology displacement sits at 15-20% penetration in medical device packaging, leaving substantial runway for equipment replacement cycles across European and North American sterile barrier operations.
For Market Incumbents: Shield installed base revenue by embedding IoT-enabled predictive maintenance modules that lock in recurring service contracts before ultrasonic specialists capture retrofit demand. Backward integration into piezoelectric component sourcing reduces exposure to Japanese and South Korean supply concentration. Prioritize certification investment for EU MDR audit-trail documentation to defend premium positioning against emerging ultrasonic pure-plays. For New Entrants and Emerging Players: Lead with ultrasonic sealing specialization targeting Swiss and German medical device manufacturers seeking REACH-compliant material waste reduction. India's pharmaceutical packaging clusters present the most penetrable geography, with CDSCO sterile barrier mandates driving vacuum sealer demand ahead of domestic vendor capacity buildout. Pursue equipment-as-a-service pricing to bypass capital expenditure approval cycles at mid-volume contract packaging organizations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ultrasonic equipment pure-plays with established piezoelectric supply relationships and medical-grade validation track records. Long-term viability hinges on capturing share during the 5-10 year window before incumbent conglomerates reengineer service architectures around dual technology footprints. Monitor FDA 510(k) submission volumes for ultrasonic sealing systems as inflection indicator for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Technology Licensing | Enables non-heat sealing entry for legacy vendors without R&D timeline risk. |
| Backward Integration into Transducers | Secures piezoelectric supply chain against Japanese and South Korean concentration. |
| IoT Predictive Maintenance Platform | Converts equipment sales into recurring revenue streams from installed base. |
| EU MDR Certification Fast-Track | Accelerates sterile barrier equipment approval for German pharmaceutical corridors. |
| India Pharmaceutical Cluster Expansion | Captures CDSCO-compliant vacuum sealer demand from vaccine export manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with packaging automation technicians, pharmaceutical manufacturing engineers, food processing plant managers, and aftermarket service directors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and trade flow data for heating element and piezoelectric component imports. Bottom-up equipment shipment estimates triangulated against top-down capital expenditure surveys from pharmaceutical and food processing trade associations.
Across the analysis window, the forecast framework modeled demand by product type, technology, end-use application, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis, technology penetration curves, and regulatory compliance deadline impacts. Industry-specific inputs included ultrasonic transducer supply capacity expansion timelines and FDA validation protocol duration benchmarks for sterile barrier systems.
The analysis sits within stated boundaries; outcomes outside continued EU MDR enforcement intensity and stable copper-aluminum commodity trading ranges would require recalibration. Practitioners should keep alternative scenarios live as REACH chemical documentation requirements and extended producer responsibility schemes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Skin Packaging Equipment Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Filling Equipment Market
Packaging Equipment
Global 2-Shot Injection Molding Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Rotary Band Heat Sealer Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Automatic Liquid Filling Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Depalletizers Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Nitrogen Filling Systems Market