
 Plastic Sterilization Trays Market | 2026-2036
Plastic Sterilization Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Sterilization Trays Market Analytics
Hospital procurement consolidation is shifting purchasing power toward centralized supply chains and multi-year vendor contracts. Medline Industries leverages its vertically integrated distribution network to compete for national health system accounts. Cardinal Health sustains channel control through direct-to-facility logistics infrastructure that reduces tray turnaround cycles. Stryker anchors its position with proprietary sterilization container systems that integrate with its broader surgical workflow portfolio.
Plastic sterilization trays are rigid polymer containers engineered to medical-grade specifications, typically molded from polypropylene or polycarbonate resins with validated steam and ethylene oxide penetration properties, designed to organize, protect, and maintain sterility of surgical instruments through processing, storage, and transport. Reusable trays dominate installed base volumes due to lifecycle cost advantages in high-throughput hospital central sterile departments, while custom trays capture disproportionate margin pools through procedure-specific instrument mapping and silicone mat integration. Polypropylene leads material selection for its chemical resistance and autoclave durability, though polycarbonate variants are gaining traction in ophthalmic and microsurgical applications requiring optical clarity for instrument verification.
FDA 510(k) clearance requirements and ISO 11607 sterilization packaging standards govern tray validation protocols, while EPA regulations on ethylene oxide emissions constrain sterilization facility capacity and extend tray utilization cycles. The EU MDR and REACH substance restrictions are reshaping material qualification pathways for trays exported to European markets. Stakeholders must monitor evolving FDA guidance on reusable device reprocessing as agency scrutiny intensifies on cleaning validation for complex instrument geometries housed within polymer trays.
Market Dynamics
Hospital procurement consolidation is compressing vendor relationships into multi-year national contracts, stripping regional distributors of pricing autonomy while rewarding sterilization tray suppliers with integrated logistics and validated container systems.
Growth Catalysts
- EPA ethylene oxide emission controls:Extended sterilization cycles are increasing tray utilization rates and replacement frequency in high-throughput central sterile departments.
- Polypropylene material advances:Enhanced autoclave durability is expanding reusable tray lifecycles beyond 500 cycles in academic medical centers.
- United States surgical volume concentration:Ambulatory surgery center expansion is generating demand for procedure-specific custom tray configurations.
Market Restraints
- Polycarbonate resin cost volatility:Optical-grade polymer feedstock price swings are compressing margins for ophthalmic tray manufacturers.
- Single-use disposable substitution:Pre-sterilized peel-packs are capturing low-complexity instrument sets in outpatient settings.
- FDA 510(k) validation timelines:Extended clearance durations for novel tray geometries are delaying product commercialization by 12-18 months.
Strategic Opportunities
- India hospital infrastructure expansion:Greenfield medical cities in Gujarat and Tamil Nadu are specifying modular sterilization systems for new central sterile departments.
- RFID-integrated tray tracking:Convergence of polymer molding with IoT sensor embedding is enabling real-time instrument location and cycle-count monitoring.
- EU MDR substance compliance:REACH-restricted phthalate-free material certifications are creating premium positioning for compliant tray exporters.
Industry Challenges
- Bioburden validation expertise scarcity:Central sterile departments lack personnel trained to ISO 17665 steam penetration testing protocols for complex lumen instruments.
- Legacy ERP integration friction:Tray inventory management systems require custom API development to interface with hospital materials management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Sterilization Trays Market |
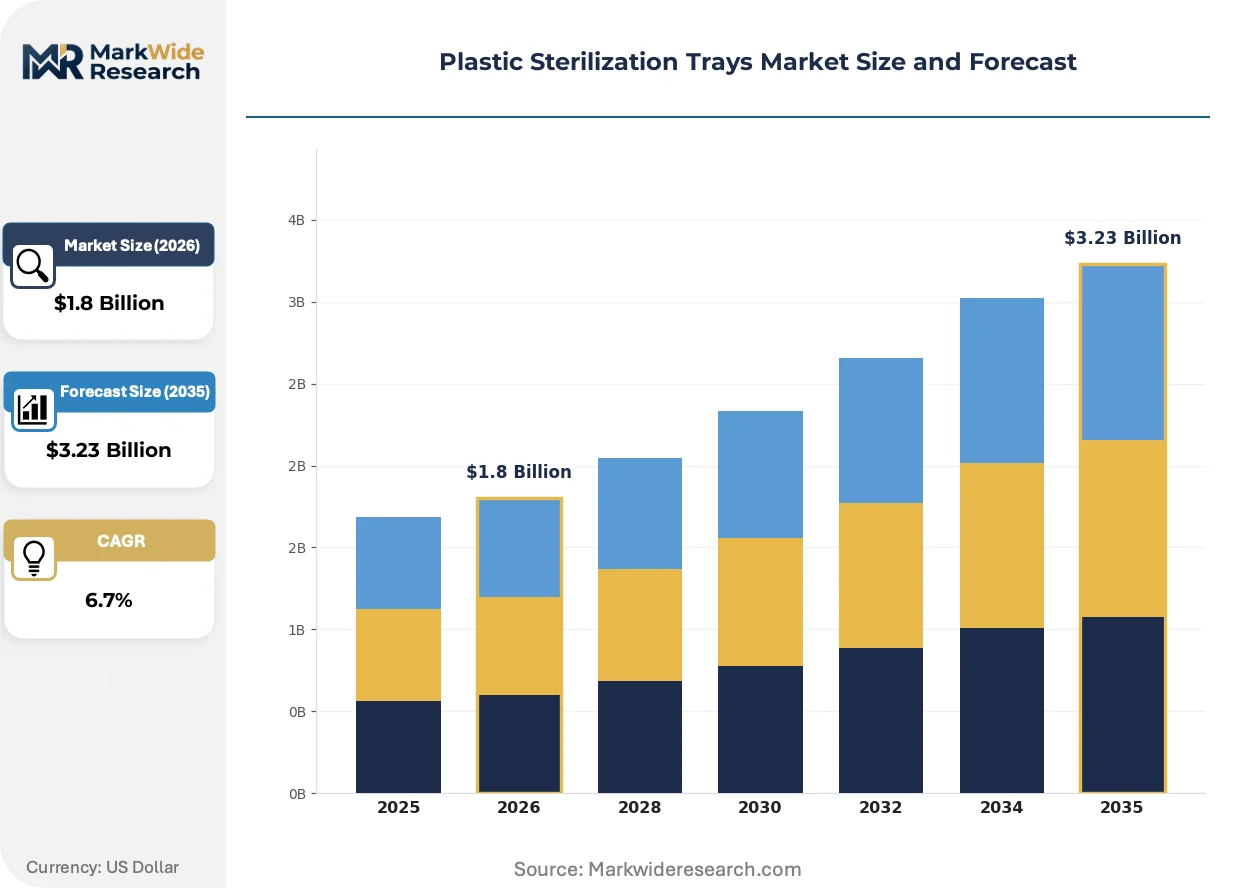
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Trays, Reusable Trays, Custom Trays, Standard Trays Material: Polypropylene, Polyethylene, Polycarbonate, ABS End User: Hospitals, Clinics, Dental Offices, Laboratories Application: Surgical Instruments, Dental Instruments, Laboratory Tools, Medical Devices |
| Companies Covered | Medline Industries, Placon Corporation, PST Corp, Cardinal Health, Stryker, Key Surgical, Aesculap, Mac Medical, Kentek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Sterilization Trays Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are redefining competitive advantage in sterilization tray manufacturing, compressing the viable supplier base to those with integrated validation capabilities.
Antimicrobial polymer compounding is consolidating surface protection technology directly into polypropylene resin formulations. Academic medical centers in the United States are specifying these integrated materials for cardiac and orthopedic instrument sets. The technology is consolidating what previously required secondary silicone mat inserts into single-mold tray architectures, reducing assembly labor and bioburden trap points.
EU MDR technical documentation requirements are forcing sterilization tray exporters to maintain European Authorized Representative relationships and post-market surveillance systems. The regulation is diverting compliance resources toward clinical evaluation reports for reusable device claims. German and French notified bodies are processing tray certifications with 8-12 month backlogs, favoring incumbent suppliers with established technical files.
Direct-to-facility logistics contracts are displacing distributor-mediated tray procurement in consolidated health systems. Cardinal Health and Medline are competing to own the sterile processing supply chain end-to-end, bundling tray provision with instrument reprocessing services. The shift is most visible in United States multi-hospital systems exceeding 50 facilities, where procurement committees mandate single-source sterilization container agreements.
Plastic Sterilization Trays Market Segmentation
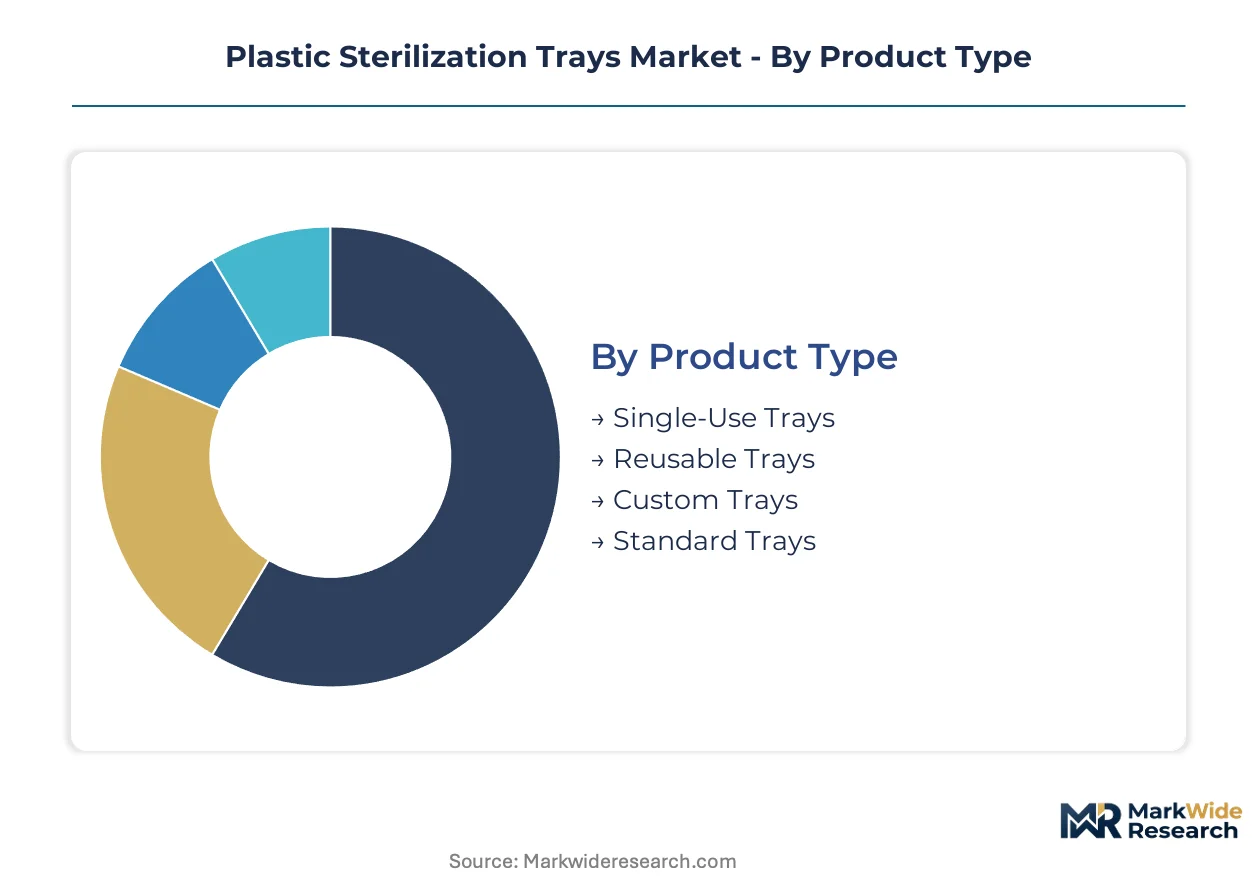
Segmentation in plastic sterilization trays determines procurement pathways, validation requirements, and margin structures. Hospital central sterile departments specify tray architectures based on instrument complexity, sterilization modality compatibility, and total cost of ownership across reprocessing cycles.
Product Type:
Supply concentration in tray manufacturing favors vendors with validated reprocessing documentation and multi-year hospital contracts.
- Reusable Trays:Molded polypropylene or polycarbonate containers engineered for 500+ steam autoclave cycles. Demand concentrates in United States academic medical centers where FDA 510(k) validated container systems anchor central sterile workflows. Lifecycle cost advantages sustain dominance in high-throughput surgical environments.
- Custom Trays:Procedure-specific configurations with silicone mat integration and instrument mapping for orthopedic, cardiac, or ophthalmic sets. United States ambulatory surgery centers drive specification growth as outpatient procedural volume expands. Premium positioning reflects design engineering and bioburden validation investments.
- Single-Use Trays:Pre-sterilized polymer containers for low-complexity instrument sets in outpatient settings.
- Standard Trays:Generic-format containers for general surgical instruments without procedure-specific customization.
Today's leader: Reusable Trays. Tomorrow's challenger: Custom Trays.
Material:
Material selection tracks sterilization modality requirements and optical clarity needs across surgical specialties.
- Polypropylene:Dominant medical-grade resin selected for steam penetration properties, chemical resistance, and autoclave durability exceeding 500 cycles. United States hospital central sterile departments specify this material for general surgical instrument sets. FDA material master file documentation supports 510(k) pathway efficiency.
- Polycarbonate:Optical-grade polymer enabling instrument verification without tray opening. United States ophthalmic and microsurgical centers drive adoption where visual confirmation reduces handling contamination. EPA ethylene oxide emission constraints extend sterilization cycles, favoring materials with validated EtO penetration.
- Polyethylene:Lower-cost alternative for single-use applications with limited heat resistance requirements.
- ABS:Engineering polymer for structural components requiring impact resistance in transport-intensive logistics.
Polypropylene commands installed base volume. Polycarbonate captures fastest margin expansion.
End User:
Customer concentration patterns mirror healthcare delivery consolidation and sterile processing centralization.
- Hospitals:Multi-facility health systems with centralized central sterile departments specifying validated container systems through national procurement contracts. United States hospital procurement consolidation strips regional distributor autonomy while rewarding integrated logistics vendors. Multi-year vendor agreements lock in tray specifications across 50+ facility networks.
- Clinics:Outpatient surgical centers with procedure-specific tray requirements and limited on-site sterilization capacity. United States ambulatory surgery center expansion generates demand for compact, specialty-configured tray systems. Turnaround time constraints favor pre-validated container configurations.
- Dental Offices:Smaller-scale sterilization needs with instrument sets requiring compact tray formats.
- Laboratories:Research and diagnostic facilities with non-surgical sterilization protocols and specialized containment requirements.
Hospitals anchor procurement volume. Clinics represent the steepest expansion trajectory.
Application:
Application segmentation aligns with instrument complexity, sterilization validation requirements, and regulatory pathway intensity.
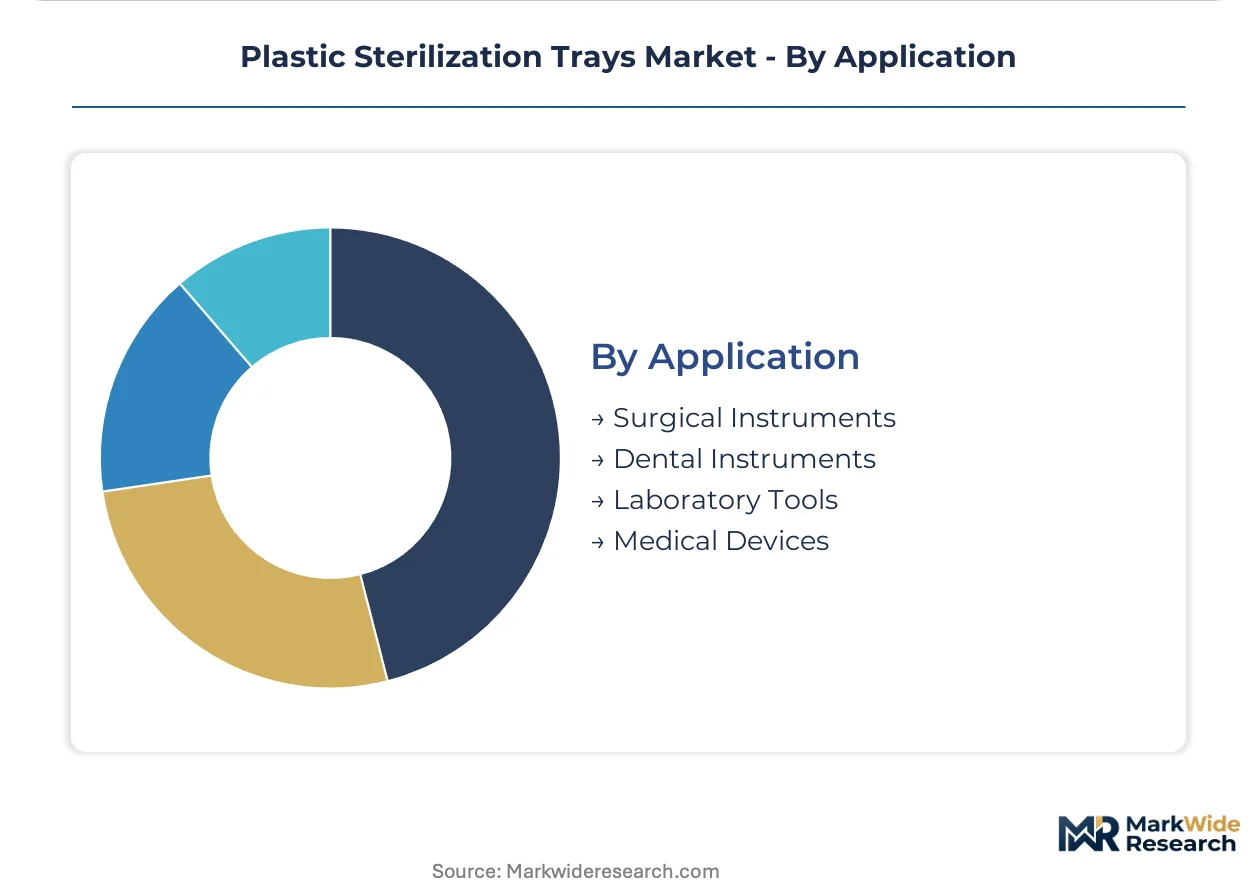
- Surgical Instruments:Complex geometries including lumened devices and power equipment requiring validated steam penetration and bioburden elimination. United States orthopedic and cardiac surgical volume concentrates demand in academic medical centers. FDA scrutiny on reusable device reprocessing intensifies cleaning validation requirements for housed instruments.
- Dental Instruments:Handpieces and operative tools with standardized sterilization protocols and compact tray footprint requirements. United States dental service organizations consolidate procurement toward national distributor contracts. Smaller instrument sets enable efficient batch processing.
- Laboratory Tools:Research equipment with non-patient-contact sterilization standards and chemical resistance priorities.
- Medical Devices:Implantable and diagnostic equipment requiring validated packaging systems and sterile barrier maintenance.
Surgical Instruments dominate value capture. Dental Instruments expand most quickly in outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterile processing specialists concentrate in United States hospital systems, German medical device clusters, and emerging Indian healthcare infrastructure. Their geographic distribution shapes procurement patterns, regulatory compliance requirements, and vendor qualification pathways across regional markets.
United States
Academic medical centers in Boston, Cleveland Clinic, and Mayo Clinic networks drive specification of validated container systems. FDA 510(k) clearance requirements and EPA ethylene oxide emission controls constrain sterilization facility capacity. The Southeast corridor from Florida to North Carolina anchors ambulatory surgery center expansion generating custom tray demand.
Germany
Notified body certification backlogs favor incumbent suppliers with established EU MDR technical files. REACH substance restrictions on phthalate-containing polymers reshape material qualification pathways for tray exporters. The Baden-Württemberg medical technology cluster around Tuttlingen concentrates surgical instrument manufacturing driving integrated tray-instrument bundling.
India
Greenfield medical cities in Gujarat and Tamil Nadu specify modular central sterile departments for new hospital infrastructure. CDSCO medical device rules and BIS polymer standards govern import substitution programs for domestic tray manufacturing. The Delhi-NCR corridor attracts sterilization equipment distributors serving northern hospital networks.
Japan
PMDA quality management system requirements extend validation timelines for foreign tray manufacturers. METI healthcare technology roadmaps prioritize automation in central sterile processing. The Osaka-Kobe manufacturing belt hosts polymer compounders supplying medical-grade polypropylene to domestic tray fabricators.
United Kingdom
NHS procurement frameworks consolidate sterilization container purchasing toward national supply agreements. MHRA post-Brexit device regulations diverge from EU MDR pathways creating dual compliance burdens. The Midlands manufacturing corridor around Birmingham maintains polymer molding capacity serving domestic medical device supply chains.
Plastic Sterilization Trays Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across sterilization container supply. Hospital procurement consolidation compresses vendor tiers into integrated logistics providers versus specialized tray manufacturers. Three archetypes dominate: vertically integrated health supply distributors, surgical workflow portfolio owners, and dedicated polymer container fabricators. Dominant competitive moves include direct-to-facility logistics contracting and proprietary container system bundling with instrument reprocessing services.
Among United States-based supply chain integrators, Medline Industries and Cardinal Health exemplify the distributor-architype competing for national health system accounts. Stryker occupies a position within the surgical portfolio-owner tier anchoring sterilization containers within broader operating room workflow systems. These three entities represent distinct strategic postures—supply chain control, logistics infrastructure ownership, and procedure integration—shaping competitive dynamics as procurement committees mandate single-source agreements across multi-facility networks.
| Leading Market Players |
|---|
| Medline Industries |
| Placon Corporation |
| PST Corp |
| Cardinal Health |
| Stryker |
| Key Surgical |
| Aesculap |
| Mac Medical |
| Kentek |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation into multi-facility health systems is compressing vendor tiers toward national contract pricing with integrated logistics bundling. United States GPOs and centralized supply chains now dictate pricing terms that strip regional distributors of margin autonomy while rewarding sterilization container suppliers with validated reprocessing documentation.
Pricing Analysis
Bundle-unbundle service splits separate sterilization tray vendors competing on container-only pricing from those anchoring multi-year contracts with instrument reprocessing services. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) validation status, with validated container systems commanding sustained premiums over unvalidated alternatives. Cost compression in the standard tier is intensifying because polycarbonate resin feedstock volatility and extended FDA clearance timelines erode manufacturer margins. Ambulatory surgery centers exhibit highest price sensitivity due to limited capital budgets, while academic medical centers prioritize lifecycle cost over unit price.
Supply Chain Analysis
Direct-to-facility channels handle hyperscale health system demand while regional distributors serve fragmented clinic networks. Polypropylene resin supply concentrates in United States Gulf Coast petrochemical corridors, German polymer compounding clusters around Tuttlingen, and Japanese medical-grade material producers in the Osaka-Kobe belt. Raw material sourcing draws from propylene feedstock markets, optical-grade polycarbonate manufacturers, and silicone mat component suppliers. Single-source vulnerability in FDA-validated resin grades creates supply chain risk for tray fabricators dependent on material master file documentation. Distribution runs through Cardinal Health and Medline logistics infrastructure for national accounts, with independent distributors retaining regional clinic access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in plastic sterilization trays rests on antimicrobial polymer compounding consolidation that eliminates secondary component costs while enabling premium positioning. Custom tray configuration and RFID-integrated tracking systems represent the fastest margin-accretion opportunities.
For Market Incumbents: Anticipate single-use disposable substitution in outpatient settings by accelerating antimicrobial polymer R&D and securing exclusive national health system contracts before procurement committees finalize vendor consolidation. Backward integration into medical-grade polypropylene compounding insulates against resin cost volatility while creating captive supply advantages for FDA 510(k) validation continuity. Cardinal Health and Medline distribution infrastructure control represents the primary defensive moat; Stryker must deepen surgical workflow bundling to maintain portfolio stickiness against pure-play container specialists. For New Entrants and Emerging Players: E-commerce direct procurement platforms targeting United States ambulatory surgery centers bypass entrenched distributor relationships and enable rapid custom tray specification. India greenfield hospital infrastructure in Gujarat and Tamil Nadu offers the most penetrable geography for modular sterilization system contracts. EU MDR phthalate-free certification gaps create white-space for REACH-compliant tray exporters. Digital channel-first go-to-market with rapid-turn custom design services differentiates against incumbent lead times. For Investors and Strategic Acquirers: Health supply chain integrators are the most active acquirer in this space, seeking validated container capabilities to complete end-to-end sterile processing offerings. Long-term viability favors tray fabricators with integrated polymer compounding and FDA master file control rather than assembly-only operations. Acquisition target archetype: mid-scale manufacturers with established 510(k) clearances and underutilized molding capacity in United States or EU jurisdictions. Signal to watch: FDA guidance intensification on reusable device reprocessing validation that would advantage incumbent technical file holders.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Polymer Integration | Consolidates silicone mat functionality into single-mold architectures, reducing assembly labor and bioburden trap points. |
| FDA 510(k) Validation Investment | Secures premium positioning in academic medical centers where validated container systems anchor central sterile workflows. |
| RFID-IoT Sensor Embedding | Enables real-time instrument tracking and cycle-count monitoring for high-value orthopedic and cardiac sets. |
| EU MDR Authorized Representative Network | Overcomes German and French notified body backlogs for tray certification continuity in European markets. |
| Direct-to-Facility Logistics Contracting | Bundles tray provision with instrument reprocessing services across multi-hospital systems exceeding fifty facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with central sterile department managers, hospital procurement committee leads, biomedical engineers, and GPO contracts specialists alongside secondary validation. Primary fieldwork captured tray utilization patterns, sterilization cycle counts, and vendor contract structures across United States academic medical centers and ambulatory surgery networks. Secondary sources included FDA 510(k) clearance databases, EPA ethylene oxide emission compliance filings, EU MDR technical documentation registries, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down healthcare expenditure flows.
Historical reference periods anchored the forecast window to pre-consolidation procurement patterns and post-MDR implementation compliance costs. Segmentation dimensions spanned product type, material grade, end-user facility scale, and surgical specialty application across the modeling period. CAGRs derived from installed base replacement cycles, ambulatory surgery center expansion trajectories, and antimicrobial polymer adoption curves. Forecast inputs incorporated EPA sterilization facility capacity constraints, REACH substance restriction timelines, and RFID-IoT convergence adoption rates.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial polymer compounding or single-use disposable substitution would alter the outlook. Forecasts reflect assumptions regarding hospital procurement consolidation velocity, FDA reusable device reprocessing guidance evolution, and EU notified body certification backlog resolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market