
 Heat Release Tape Market | 2026-2036
Heat Release Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Release Tape Market Insights
Medical equipment firms are redrawing procurement priorities as cleanroom-grade bonding replaces legacy mechanical fastening in device assembly. Sekisui Chemical Co., Ltd. leverages its polymer science heritage to dominate high-purity silicone adhesive formulations. tesa tape, inc anchors European medical device supply chains with ISO-certified cleanroom production. Nitto Denko Corporation specializes in ultra-thin heat release constructions for semiconductor back-end processes.
Heat release tape comprises a carrier substrate coated with thermally activatable adhesive that softens at controlled temperatures to permit clean removal or repositioning without residue transfer, typically engineered with activation thresholds between 90°C and 150°C depending on acrylic, silicone, or rubber chemistries. Silicone adhesive tape leads margin pools owing to biocompatibility premiums in medical device manufacturing, while hot melt adhesive tape competes on cost in textile lamination where repositioning tolerance is lower. Automatic dispensing systems represent the fastest-growing installation method as electronics manufacturers replace manual application to reduce variability in bond-line thickness.
FDA adhesive biocompatibility standards and the European Union's REACH framework constrain raw material selection, forcing reformulation of rubber-based systems away from legacy plasticizers. ISO 10993 testing protocols extend qualification timelines for medical device applications, creating barrier-to-entry effects for new suppliers. Stakeholders must monitor regulatory divergence between FDA and EMA adhesive classification schemes when designing unified product platforms.
Market Dynamics
Precision electronics assembly is compressing activation temperature tolerances below 5°C variance, forcing adhesive formulators to abandon legacy batch-blending in favor of continuous reactor control systems.
Growth Catalysts
- Semiconductor packaging density:Taiwan and South Korea fabs are consuming ultra-thin carrier tapes for die-attach processes requiring sub-100 micron bond-line control.
- MDR biocompatibility pathways:European medical device manufacturers are qualifying silicone adhesive tapes under EU MDR Article 10 technical documentation requirements.
- Cleanroom bonding protocols:ISO 14644 Class 7 assembly lines are replacing mechanical clips with residue-free thermal release tapes in disposable diagnostic device production.
Market Restraints
- Specialty silicone feedstock concentration:Precipitated silica and platinum catalyst supply chains concentrate among German and Japanese chemical conglomerates.
- REACH SVHC screening burdens:ECHA quarterly substance candidate list updates force reformulation cycles averaging 18 months for rubber-based adhesive platforms.
- Acrylic thermal ceiling:Acrylic chemistry hard-caps activation thresholds at 120°C, blocking adoption in high-temperature solder reflow applications above 150°C.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme beneficiaries in Noida and Sri City are establishing captive tape slitting operations for smartphone assembly.
- Automotive battery module bonding:Cell-to-pack architectures are creating demand for thermally-reversible fixation during warranty service access.
- ISO 10993-5 cytotoxicity waivers:FDA breakthrough device designation pathways are accelerating adhesive qualification timelines for novel surgical instruments.
Industry Challenges
- Cleanroom operator certification:ISO 14644-1 monitoring protocol proficiency requires 6-month training pipelines that outpace facility expansion in Vietnam and Mexico.
- Adhesive-aging test infrastructure:Accelerated life testing chambers for 10-year medical device shelf-life claims demand capital outlays exceeding mid-tier converter capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Release Tape Market |
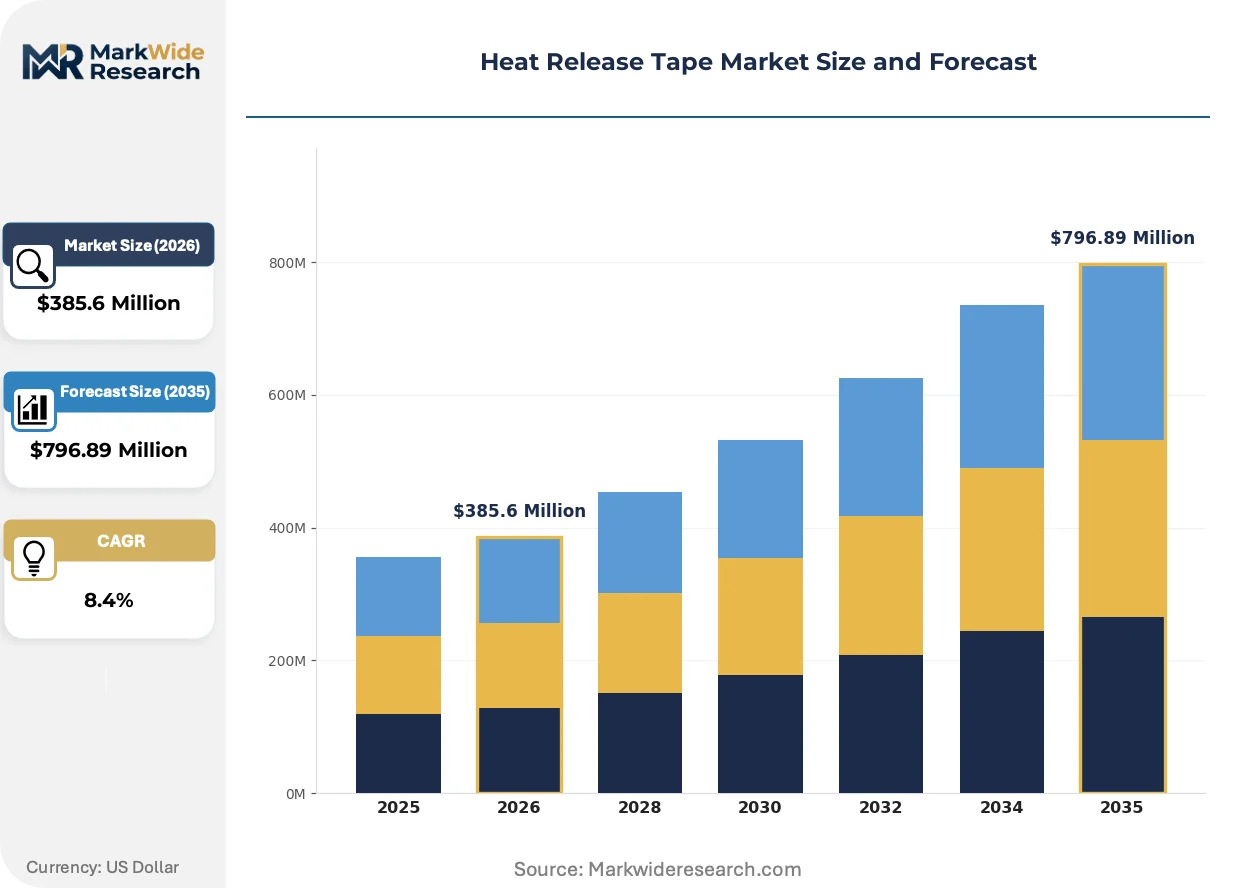
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Adhesive Tape, Silicone Adhesive Tape, Rubber Adhesive Tape, Hot Melt Adhesive Tape Industry Application: Consumer Electronics Assembly, Electrical Insulation, Medical Device Manufacturing, Textile Lamination Installation Method: Manual Application, Automatic Dispensing, Heat Press, Vacuum Lamination End User Segment: Electronic Manufacturers, Medical Equipment Firms, Textile Producers, Electrical Components Suppliers |
| Companies Covered | Lintec Corporation, tesa tape, inc, Sekisui Chemical Co., Ltd., Shurtape Technologies, LLC, Scapa Group plc, 3M Company, Avery Dennison Corporation, Lohmann Rauscher GmbH Co. KG, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Release Tape Market Trends and Innovations
Activation chemistry precision is overtaking carrier substrate thickness as the primary technical battleground, with formulators racing to decouple thermal response from humidity sensitivity in cleanroom environments.
Silicone adhesive platforms are bifurcating into two performance tiers: addition-cure systems for medical device permanent implantation and condensation-cure variants for electronics temporary processing. Semiconductor back-end houses in Hsinchu are adopting the latter for wafer dicing frame mounting. This split is compressing R&D budgets at mid-size converters unable to maintain dual formulation pipelines.
REACH Annex XVII restriction proposals on organotin catalysts are forcing silicone tape manufacturers toward platinum-based curing systems with 40% higher raw material costs. German medical device exporters face extended ECHA notification timelines for imported tape components. The regulatory friction is redirecting supply chain qualification efforts toward FDA 510(k) pathways for US market entry.
Device assemblers are consolidating adhesive specifications across product families to reduce SKU complexity in procurement systems. Electronics contract manufacturers in Shenzhen are rejecting custom formulations in favor of catalog-standard thermal release tapes with published TDS parameters. This standardization push is squeezing regional converter margins while benefiting scale producers with validated master files.
Heat Release Tape Market Segmentation
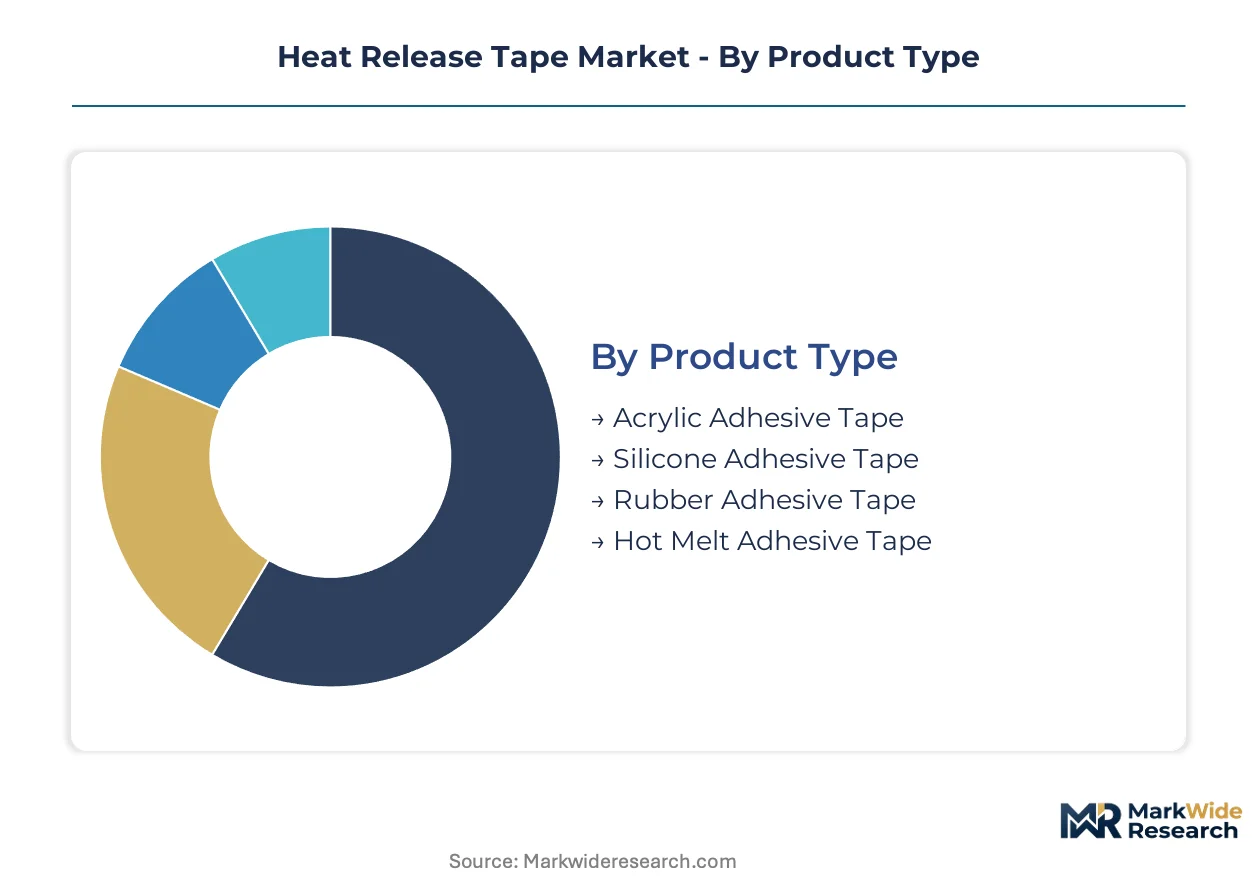
Adhesive chemistry selection determines regulatory pathway complexity and margin structure across heat release tape procurement. Formulators align product architectures with end-use certification requirements rather than pursuing universal platform strategies.
Product Type:
FDA 510(k) and EU MDR biocompatibility pathways diverge sharply by adhesive chemistry, with silicone systems commanding premium positioning through cytotoxicity waivers while rubber formulations face REACH SVHC-driven reformulation cycles.
- Acrylic Adhesive Tape:Thermoplastic polymer systems activate between 90°C and 120°C through softening rather than chemical degradation. Semiconductor packaging lines in Hsinchu and Yongin specify acrylic constructions for wafer dicing frame mounting where residue-free removal must occur below solder reflow thresholds. The 120°C thermal ceiling blocks adoption in high-temperature assembly processes.
- Silicone Adhesive Tape:Addition-cure and condensation-cure platinum-catalyzed systems dominate medical device bonding under ISO 10993-5 cytotoxicity protocols. Cleanroom-grade silicone tapes from German and Japanese suppliers anchor EU MDR Article 10 technical documentation submissions for permanent implantation devices.
- Rubber Adhesive Tape:Legacy natural and synthetic rubber formulations compete on cost in textile lamination where repositioning tolerance is lower. ECHA quarterly SVHC list updates force 18-month average reformulation cycles for plasticizer-dependent systems.
- Hot Melt Adhesive Tape:Ethylene-vinyl acetate and polyolefin-based thermoplastic constructions serve high-volume textile bonding in Bangladesh and Vietnam garment clusters where thermal reversibility is rarely required.
Established volume favors acrylic systems in electronics processing; emerging adoption favors silicone platforms in medical device qualification pipelines.
Industry Application:
End-use specifications compress activation temperature tolerances below 5°C variance in precision assembly while tolerating broader ranges in commodity bonding.
- Consumer Electronics Assembly:Die-attach processes in Taiwan and South Korea fabs demand sub-100 micron bond-line control with cleanroom-compatible outgassing profiles. Ultra-thin carrier tapes with 50-micron total construction thickness dominate smartphone module integration.
- Electrical Insulation:Transformer and motor winding applications specify heat release tapes for temporary coil fixation during varnish impregnation. IEC 60454 certification requirements govern dielectric strength and thermal endurance specifications.
- Medical Device Manufacturing:Disposable diagnostic device producers in Massachusetts and Minnesota are replacing mechanical clips with residue-free thermal release tapes in ISO 14644 Class 7 assembly lines. FDA breakthrough device designation pathways accelerate adhesive qualification timelines.
- Textile Lamination:Sportswear and protective garment manufacturers in Portugal and Turkey specify hot melt adhesive tapes for membrane-to-fabric bonding where repositioning tolerance is minimal and cost sensitivity is acute.
Electronics assembly commands specification authority; medical device qualification represents the steepest expansion trajectory.
Installation Method:
Capital investment intensity separates manual from automated deployment, with electronics manufacturers driving standardization toward catalog-specified thermal release tapes.
- Manual Application:Low-volume prototyping and repair operations in Mexican and Vietnamese contract assembly facilities rely on hand-cut tape segments with visual alignment.
- Automatic Dispensing:Shenzhen and Dongguan electronics contract manufacturers are replacing manual application with servo-controlled dispensing systems to reduce bond-line thickness variability. This installation method is climbing the fastest among precision electronics assemblers.
- Heat Press:Textile lamination operations in Milan and Barcelona industrial zones employ platen-based thermal activation for membrane bonding with controlled pressure profiles.
- Vacuum Lamination:Aerospace composite and flexible electronics producers in Toulouse and Hamburg specify vacuum-assisted thermal release fixation to eliminate void formation in multi-layer stacks.
Manual methods retain share in emerging manufacturing zones; automatic dispensing gains specification in high-mix electronics contract manufacturing.
End User Segment:
Procurement consolidation across product families is reducing SKU complexity, squeezing regional converter margins while benefiting scale producers with validated master files.
- Electronic Manufacturers:Taiwan Semiconductor Manufacturing Company and Samsung Electronics captive packaging operations specify ultra-thin heat release constructions with published TDS parameters, rejecting custom formulations.
- Medical Equipment Firms:Medtronic and Boston Scientific procurement teams are consolidating adhesive specifications across diagnostic and surgical device portfolios to simplify supplier qualification.
- Textile Producers:Decathlon and VF Corporation supply chain auditors enforce OEKO-TEX Standard 100 compliance for adhesive tapes in skin-contact garment applications.
- Electrical Components Suppliers:ABB and Siemens transformer divisions specify heat release tapes with IEC 60454-3-1 certification for temporary coil fixation during impregnation cycles.
Electronics manufacturers drive volume scale; medical equipment firms drive margin expansion through biocompatibility premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device manufacturers in Minnesota and Massachusetts drive North American procurement, while semiconductor packaging houses in Hsinchu and Yongin anchor East Asian consumption. Electronics contract manufacturers in Shenzhen and Dongguan are consolidating specifications toward catalog-standard tapes.
United States
FDA breakthrough device designation pathways accelerate adhesive qualification timelines for novel surgical instruments. ISO 10993-5 cytotoxicity testing extends qualification pipelines for permanent implantation devices. Disposable diagnostic producers in Greater Boston are replacing mechanical clips with residue-free thermal release tapes in ISO 14644 Class 7 assembly lines.
Germany
REACH Annex XVII restriction proposals on organotin catalysts force silicone tape manufacturers toward platinum-based curing systems. ECHA quarterly SVHC list updates drive reformulation cycles averaging 18 months. Medical device exporters in Baden-Württemberg face extended notification timelines for imported tape components under EU MDR Article 10.
South Korea
Samsung Electronics captive packaging operations specify ultra-thin heat release constructions with sub-100 micron bond-line control. MFDS biocompatibility standards align with FDA pathways for adhesive qualification. Semiconductor back-end houses in Yongin are adopting condensation-cure silicone variants for wafer dicing frame mounting.
Taiwan
Taiwan Semiconductor Manufacturing Company fabs consume ultra-thin carrier tapes for die-attach processes requiring precision thermal activation. NMPA-aligned export standards govern tape shipments to mainland China packaging facilities. Hsinchu Science Park houses are compressing activation temperature tolerances below 5°C variance through continuous reactor control systems.
Japan
PMDA pharmaceutical quality standards extend to medical device adhesive components through METI industrial policy coordination. Platinum catalyst supply chains concentrate among domestic chemical conglomerates. Osaka-based polymer science specialists dominate high-purity silicone adhesive formulations for cleanroom-grade bonding applications.
Heat Release Tape Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with polymer science heritage. The vendor base stratifies across three tiers: scale producers with validated FDA master files, regional converters serving single-country electronics clusters, and specialty silicone formulators targeting medical device qualification pipelines. Dominant competitive moves include portfolio diversification into adjacent adhesive chemistries and geographic expansion through distributor partnerships in emerging electronics manufacturing zones.
Among Japanese materials conglomerates, Sekisui Chemical Co., Ltd. and Nitto Denko Corporation exemplify the premium-tier archetype through polymer science specialization. German adhesive specialists tesa tape, inc occupy a position within the European medical device supply chain anchored by ISO-certified cleanroom production. These three entities represent the concentration of formulation expertise that smaller regional converters struggle to replicate under tightening regulatory timelines.
| Leading Market Players |
|---|
| Lintec Corporation |
| tesa tape, inc |
| Sekisui Chemical Co., Ltd. |
| Shurtape Technologies, LLC |
| Scapa Group plc |
| 3M Company |
| Avery Dennison Corporation |
| Lohmann Rauscher GmbH Co. KG |
| Nitto Denko Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German and Japanese silicone precursor plants shapes margin floors across medical-grade tape tiers, compressing price flexibility for converters lacking backward integration into platinum-catalyzed resin supply.
Pricing Analysis
Cost-plus contracts with quarterly silicone indexation dominate procurement between medical device OEMs and certified converters. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-validated silicone systems from acrylic electronics grades and rubber-based textile constructions. Cost compression in acrylic electronics tiers is intensifying because Shenzhen contract manufacturers are consolidating specifications toward catalog-standard tapes with published TDS parameters. Textile laminators in Bangladesh and Vietnam exhibit acute price sensitivity, while medical device firms in Massachusetts and Minnesota absorb biocompatibility premiums without volume pushback.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor back-end processing, consuming ultra-thin carrier tapes for die-attach operations with sub-100 micron bond-line requirements. Precipitated silica and platinum catalyst feedstock draws from German and Japanese chemical conglomerates, creating single-source vulnerability for medical-grade silicone formulations. Distribution runs through authorized converter networks serving ISO 14644 cleanroom facilities, with direct mill relationships reserved for captive packaging operations at TSMC and Samsung Electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor packaging capex cycles signal recovery traction, with die-attach tape consumption correlating to fab utilization rates in Hsinchu and Yongin.
For Market Incumbents: Secure platinum catalyst supply agreements with domestic Japanese chemical conglomerates to hedge against REACH Annex XVII organotin restrictions. Defend margin position by consolidating ISO 10993 master file portfolios across medical device product families, reducing SKU complexity that regional converters cannot replicate under 18-month ECHA reformulation timelines. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated adhesive qualification timelines for novel surgical instruments. Target Indian electronics manufacturing zones under PLI scheme benefits, where Noida and Sri City captive slitting operations lack validated silicone formulation expertise. Pursue distributor partnerships with Shenzhen contract manufacturers rejecting custom formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among medical-grade silicone converters with validated FDA master files and EU MDR Article 10 technical documentation. Long-term viability favors acquisition targets with dual certification pipelines spanning ISO 10993 cytotoxicity waivers and IEC 60454 dielectric specifications. Monitor ECHA quarterly SVHC list updates as inflection signals for forced consolidation among rubber-based adhesive specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum Catalyst Supply | Mitigates REACH Annex XVII organotin substitution cost inflation for medical-grade silicone platforms. |
| ISO 10993-5 Cytotoxicity Master File Consolidation | Accelerates FDA 510(k) pathways for diagnostic device producers in Greater Boston cleanroom clusters. |
| Automatic Dispensing System Partnership | Captures specification authority as Shenzhen electronics manufacturers replace manual tape application. |
| Indian PLI Scheme Captive Slitting Expansion | Establishes tariff-advantaged supply positions for smartphone assembly in Noida and Sri City. |
| EU MDR Article 10 Technical Documentation Investment | Extends barrier-to-entry effects against mid-tier converters in German medical device export corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, ECHA SVHC candidate list updates, and SEC disclosures from listed materials conglomerates. Conversations with cleanroom operations managers, medical device procurement leads, semiconductor packaging engineers, and adhesive formulator R&D directors informed demand-side validation. Customs data from Taiwan and South Korea, IEC certification registries, and ISO 10993 testing laboratory records provided supply-side triangulation against bottom-up volume estimates.
Segmentation dimensions modeled include adhesive chemistry tier, end-use industry application, installation method capital intensity, and regional regulatory cluster alignment. CAGRs were derived from trend extrapolation of semiconductor packaging density and medical device biocompatification pathways across the projection horizon. Forecast inputs incorporated cleanroom Class 7 assembly line expansion trajectories and REACH reformulation cycle timelines for rubber-based systems.
Underlying assumptions cover stable platinum catalyst supply from Japanese chemical conglomerates, with deviation risk concentrated in ECHA quarterly SVHC list expansions and FDA-EMA adhesive classification divergence. Recalibration cycles align with material shifts in semiconductor packaging node transitions and EU MDR enforcement phase completions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Metal Foil Tapes Market
Tapes
Unidirectional Tapes Market
Tapes
Freezer Tape Market
Tapes
Carbon Tapes Market
Tapes
Filmic Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Industrial Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Acetate Cloth Tape Market
Tapes
Global UV-Cured Acrylic Adhesive Tapes Market
Tapes
Smart Card Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Tapes Market
Tapes
Breathable Tape Market
Tapes
Paper Packaging Tapes Market