
 Rigid Industrial Packaging Market | 2026-2036
Rigid Industrial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Industrial Packaging Market Intelligence
Aftermarket container refurbishment and reconditioning revenue is reconfiguring margin pools away from virgin material production toward circular service models. Greif leverages its global reconditioning network to capture recurring revenue from chemical and food sector clients. Crown Holdings anchors its position through vertical integration into steel and aluminum can manufacturing, sustaining cost discipline across metal packaging lines. Sealed Air Corporation differentiates via engineered barrier technologies for sensitive industrial contents.
Rigid industrial packaging encompasses durable, non-collapsible enclosures manufactured from steel, plastic, wood, or fiberboard, typically engineered to UN performance standards for hazardous goods transport with load ratings from 200 to 1,500 kilograms; these structures protect bulk chemicals, lubricants, and intermediate manufacturing inputs through multi-modal supply chains. Metal drums retain dominant share in hazardous chemical applications where UN certification and thermal stability command premium positioning, while plastic intermediate bulk containers represent the fastest-expanding material category as polyethylene recycling streams mature and weight-based freight savings accumulate. Fiberboard boxes occupy stable demand in automotive parts logistics where one-way export flows limit return economics for reusable alternatives.
EPA hazardous waste manifest rules and DOT 49 CFR shipping regulations govern container performance standards for U.S. cross-border chemical transport, while EU REACH and the Packaging and Packaging Waste Directive impose material traceability and recycled content thresholds that reshape supplier qualification criteria. The FDA maintains overlapping jurisdiction for food-contact industrial totes used in ingredient bulk handling. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize reconditioning capabilities or outsource to specialized service networks.
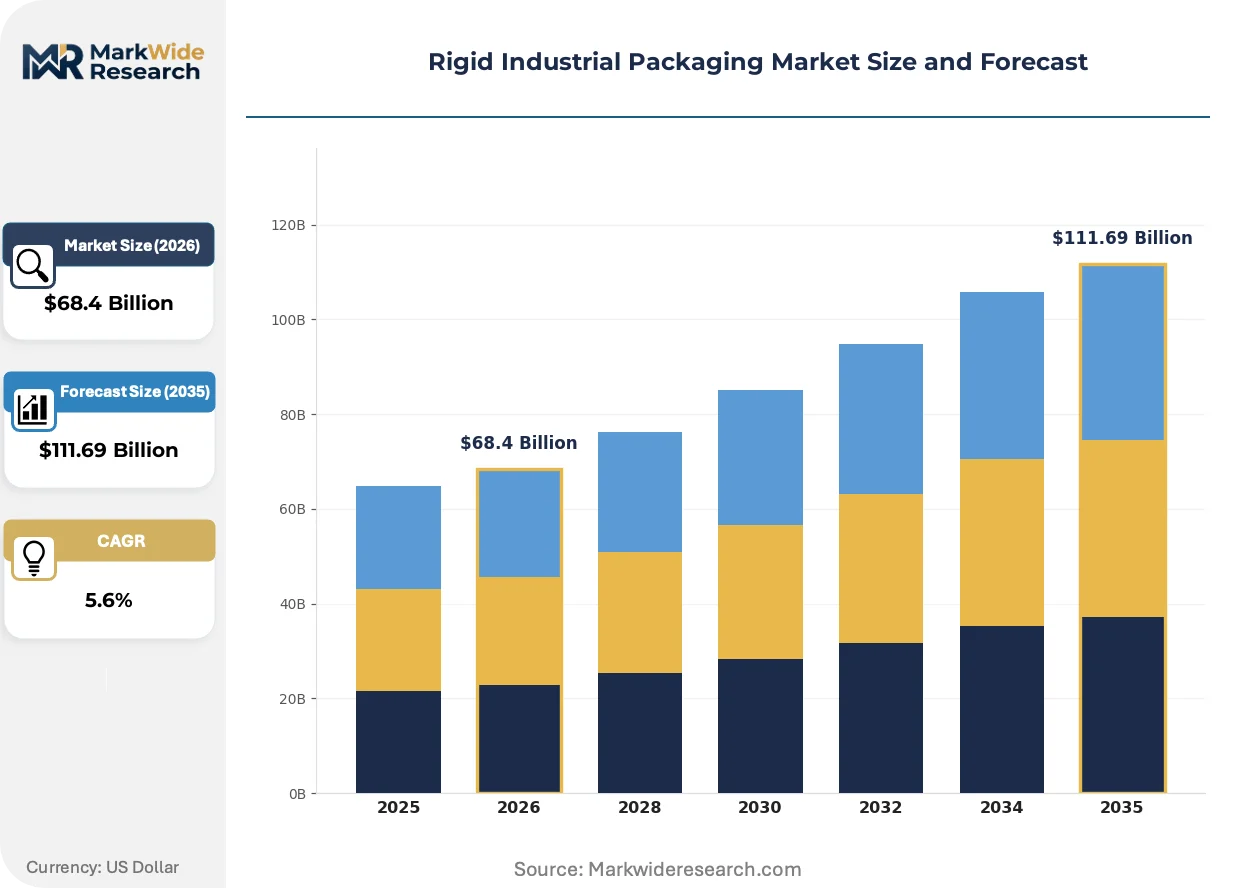
Market Dynamics
EU REACH material migration limits are compressing supplier qualification timelines and forcing reformulation of polyethylene formulations across hazardous chemical applications, while reusable intermediate bulk container networks are capturing service revenue from virgin drum manufacturers.
Growth Catalysts
- REACH Compliance Deadlines:EU hazardous substance transport rules are tightening certification requirements for plastic containers, creating replacement demand for UN-rated packaging that meets updated migration thresholds.
- Automotive Export Logistics:Germany's cross-border component shipments require certified packaging for hazardous lubricants and coatings, concentrating demand for steel drums with thermal stability ratings.
- Polyethylene Recycling Maturation:Closed-loop reprocessing streams for high-density polyethylene are reducing raw material costs for intermediate bulk container production, accelerating substitution away from metal alternatives.
Market Restraints
- Steel Input Volatility:Cold-rolled steel price fluctuations directly compress margins for drum manufacturers serving chemical sector clients on fixed-term contracts.
- Supplier Concentration Risk:UN certification testing capacity concentrates in German and Dutch laboratories, creating bottlenecks for new packaging designs seeking hazardous goods approval.
- Fiberboard Substitution Ceiling:One-way automotive parts exports limit return economics for reusable alternatives, trapping fiberboard demand in low-margin commodity production.
Strategic Opportunities
- Reconditioning Network Expansion:Aftermarket refurbishment services for chemical and food sector totes capture recurring revenue streams independent of virgin material sales cycles.
- Barrier Technology Convergence:Engineered multi-layer films combined with RFID tracking enable real-time content monitoring for sensitive pharmaceutical intermediates.
- Extended Producer Responsibility:EU Packaging and Packaging Waste Directive mandates are shifting liability upstream, creating service contracts for container lifecycle management.
Industry Challenges
- UN Certification Timeline Compression:Performance testing for hazardous goods transport now requires 12-18 month validation cycles, delaying product launches for new container geometries.
- Legacy Fleet Integration:Chemical manufacturers face capital constraints when retrofitting existing drum handling systems for intermediate bulk container formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Industrial Packaging Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $111.69 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Drums, Pallets, Boxes Material: Plastic, Metal, Wood, Fiberboard End User: Manufacturing, Logistics, Chemicals, Food Application: Storage, Shipping, Retail, Transport |
| Companies Covered | Silgan Holdings Inc., Crown Holdings, Amcor Group GmbH, DS Smith PLC, Sealed Air Corporation, Berry Global Inc., Ball Corporation, Greif, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Industrial Packaging Market Strategic Shifts & Innovations
Digital tracking systems and material science advances are restructuring how industrial packaging is specified, monitored, and recovered across chemical and automotive supply chains.
RFID-embedded intermediate bulk containers are virtualizing inventory visibility for chemical manufacturers. Bulk chemical handlers in the coatings sector are deploying sensor-equipped totes at accelerating rates. This technology is virtualizing traditional manual inspection protocols and compressing insurance premiums for hazardous goods carriers.
EPA hazardous waste manifest rules under 40 CFR are tightening cradle-to-grave documentation requirements for U.S. cross-border chemical shipments. The industrial consequence is mandatory electronic tracking integration for all UN-rated containers. Steel drum suppliers serving export markets are retrofitting production lines with serialization equipment to maintain DOT 49 CFR compliance.
Buyers are consolidating vendor relationships around full-service packaging providers that bundle container supply with reconditioning logistics. This consolidation is displacing spot-market drum purchasing in the lubricants sector. The shift is most visible in Germany, where automotive chemical suppliers now specify ten-year total cost of ownership contracts rather than unit pricing.
Rigid Industrial Packaging Market Segmentation
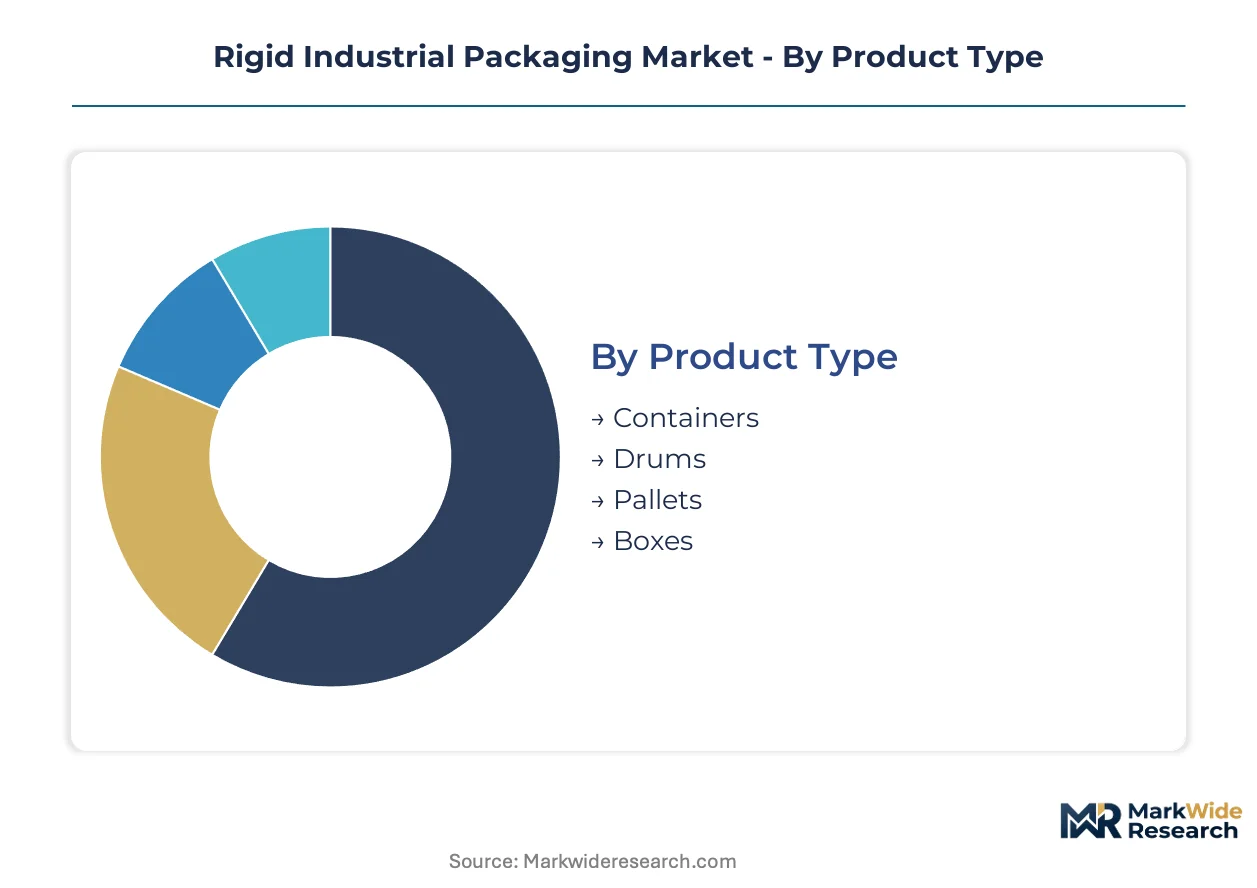
Segmentation in rigid industrial packaging reveals how material specifications, regulatory certifications, and end-use durability requirements fragment demand across incompatible supply chains. Container selection directly determines UN hazardous goods compliance, freight economics, and circular recovery potential.
Product Type:
Mature formats dominate hazardous chemical handling while emerging geometries capture lightweight logistics applications.
- Containers:Intermediate bulk containers engineered from high-density polyethylene or composite materials handle liquid and granular chemical transport with UN-certified stack ratings. German automotive chemical suppliers specify these for cross-border coating shipments under REACH-mandated migration limits.
- Drums:Steel and fiber constructions with 200-250 liter capacities retain thermal stability certification for flammable solvent storage. Demand concentrates in U.S. EPA-regulated hazardous waste manifests where DOT 49 CFR performance testing governs wall thickness specifications.
- Pallets:Load-bearing platforms enable unitized handling of intermediate bulk containers across multi-modal transfers.
- Boxes:Corrugated fiberboard enclosures serve one-way automotive parts exports where return economics fail.
Drums handle the majority of throughput; containers are expanding most quickly on share.
Material:
Cost tiers separate commodity recyclables from engineered barrier substrates with specialized certification pathways.
- Plastic:High-density polyethylene and polypropylene formulations dominate intermediate bulk container production with closed-loop recycling streams reducing virgin resin dependence. EU Packaging and Packaging Waste Directive thresholds are accelerating recycled content integration.
- Metal:Cold-rolled steel and aluminum alloys provide thermal stability for flammable chemical storage with UN-certified seam welding. Steel price volatility compresses margins for drum manufacturers serving fixed-term chemical sector contracts.
- Wood:Hardwood and softwood crates serve machinery export packaging with ISPM-15 heat treatment requirements.
- Fiberboard:Recycled paper pulp constructions occupy stable demand in lightweight automotive component logistics.
Plastic commands the steepest expansion trajectory; metal retains certification-critical applications.
End User:
Customer type determines specification intensity from commodity spot purchasing to integrated service contracts.
- Manufacturing:Automotive and electronics producers specify UN-rated packaging for lubricant and solvent inbound logistics with ten-year total cost of ownership contracting.
- Logistics:Third-party freight operators prioritize container weight reduction and RFID tracking integration for insurance premium compression.
- Chemicals:Coatings and specialty chemical manufacturers drive demand for barrier-engineered intermediate bulk containers with real-time content monitoring.
- Food:Ingredient bulk handlers require FDA-compliant totes with migration-tested polyethylene formulations for edible oil and syrup transport.
Chemicals generates the highest specification intensity; logistics is gaining share fastest through digital integration mandates.
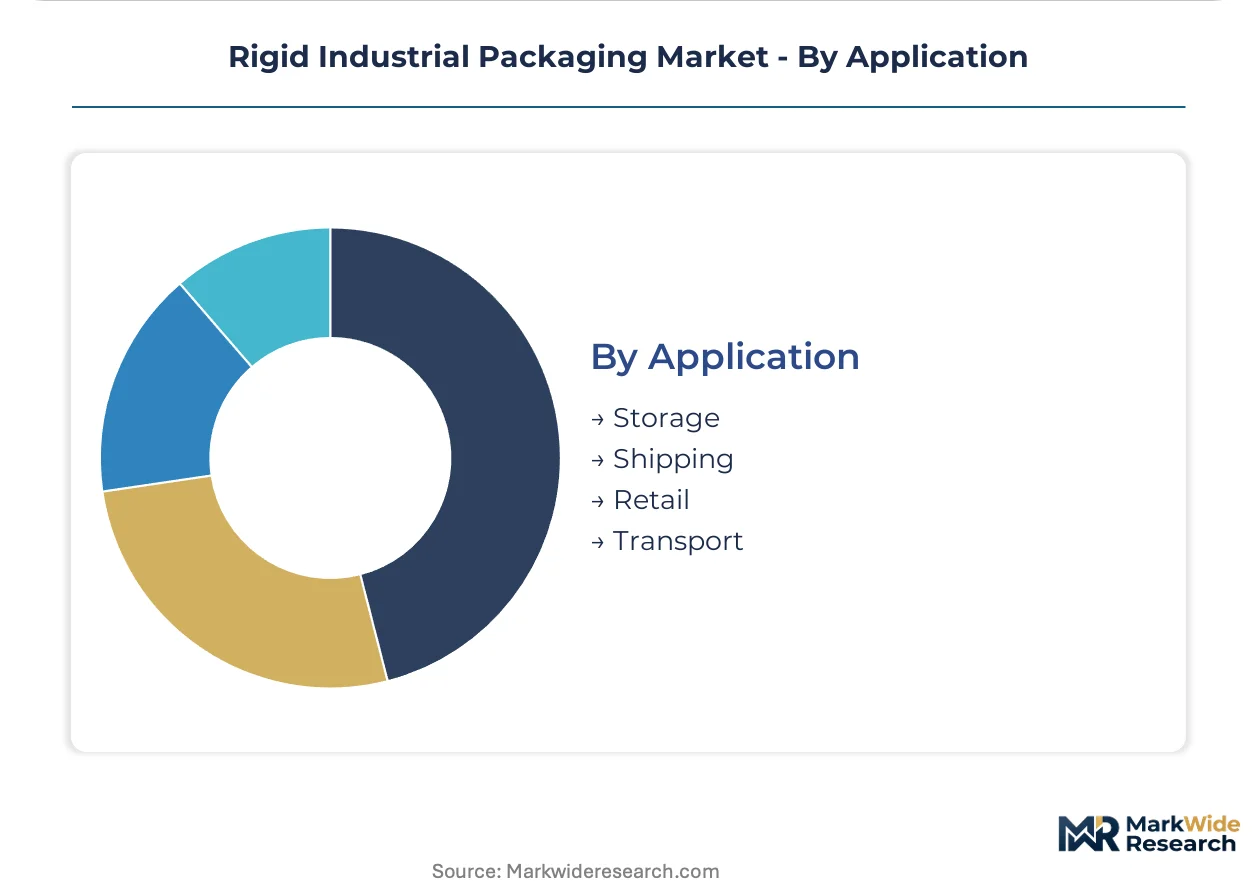
Application:
Volume concentration varies across static storage versus multi-modal transport with divergent durability requirements.
- Storage:Long-duration containment applications demand corrosion-resistant linings and stack stability for warehouse density optimization.
- Shipping:Export-oriented movements require UN-certified performance under vibration, drop, and pressure differential testing protocols.
- Retail:Point-of-sale display packaging integrates branding with protective functions for industrial consumables.
- Transport:Multi-leg freight movements prioritize weight reduction and handling compatibility across rail, road, and vessel transfers.
Shipping handles the majority of certification-intensive volume; transport is climbing the fastest on technology integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany concentrates demand for UN-certified steel drums serving automotive chemical exports. The United States prioritizes EPA-compliant hazardous waste containment with embedded tracking systems. China scales polyethylene intermediate bulk container production for domestic chemical distribution.
Germany
Automotive lubricant and coating exports drive drum specifications with thermal stability ratings. ECHA REACH compliance mandates updated migration thresholds for polyethylene containers. Stuttgart and Wolfsburg chemical suppliers specify ten-year total cost of ownership contracts for cross-border shipments.
United States
EPA hazardous waste manifest rules under 40 CFR govern cradle-to-grave documentation for chemical transport. DOT 49 CFR performance testing requirements compress supplier qualification timelines. Houston and Baton Rouge petrochemical corridors concentrate demand for UN-rated steel drums with serialization equipment.
China
Domestic chemical distribution networks expand polyethylene intermediate bulk container adoption for weight-based freight savings. SAMR quality standards and GB hazardous goods transport regulations shape certification pathways. Yangtze River Delta chemical parks drive volume for reusable tote formats with closed-loop recycling.
India
Specialty chemical manufacturing clusters generate demand for barrier-engineered containers with FDA-compliant linings. BIS certification requirements and DGFT export protocols govern packaging specifications. Gujarat and Maharashtra industrial corridors concentrate drum reconditioning service networks.
Japan
Precision chemical and pharmaceutical intermediates require engineered multi-layer barrier technologies. METI industrial standards and JIS performance specifications dictate container validation protocols. Osaka-Kobe chemical manufacturing belt specifies RFID-embedded totes for real-time content monitoring.
Rigid Industrial Packaging Market Key Industry Players
Capability concentration sits with specialized barrier technology developers; scale advantage sits with integrated metal and plastic fabricators. The market structures around three tiers: global full-service providers with reconditioning networks, regional drum manufacturers serving fixed-term chemical contracts, and niche specialists in pharmaceutical-grade containment. Dominant competitive moves include backward integration into captive steel and resin production, plus geographic expansion of refurbishment service footprints.
Among North American full-service providers, Greif exemplifies the circular service model archetype through its global reconditioning network. Sealed Air Corporation occupies a position representing engineered barrier technology specialization for sensitive industrial contents. Crown Holdings anchors the vertical integration archetype with in-house production of steel and aluminum can manufacturing inputs.
| Leading Market Players |
|---|
| Silgan Holdings Inc. |
| Crown Holdings |
| Amcor Group GmbH |
| DS Smith PLC |
| Sealed Air Corporation |
| Berry Global Inc. |
| Ball Corporation |
| Greif |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
Cold-rolled steel production concentration in China and India directly determines margin compression dynamics for drum manufacturers serving fixed-term chemical sector contracts. Resin supply tethered to Gulf Coast petrochemical complexes feeds polyethylene formulation costs that cascade through intermediate bulk container pricing tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive chemical suppliers and drum manufacturers in Germany, displacing spot-market purchasing that once governed lubricants sector transactions. Price differentiation rests on UN certification tier and thermal stability rating, with REACH-compliant containers commanding sustained premiums over standard-grade alternatives. Cost compression in fiberboard box production is intensifying because one-way automotive export flows eliminate return logistics revenue. Small-batch specialty chemical handlers exhibit highest price sensitivity, while multinational coatings manufacturers prioritize total cost of ownership certainty over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for steel drum suppliers dependent on cross-border metal sourcing. Manufacturing gravity centers on Germany, China, and the United States for certified container production, with raw material feeds drawing from cold-rolled steel mills, high-density polyethylene resin complexes, and recycled pulp processing facilities. Single-source vulnerability concentrates in German and Dutch UN certification laboratories, creating validation bottlenecks for new packaging geometries. Distribution runs through chemical sector distributors bundling container supply with reconditioning logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible intermediate bulk container formats threaten rigid packaging incumbents in non-hazardous chemical applications where UN certification provides no competitive moat. Incumbents must navigate this substitution pressure while defending certification-intensive market positions.
For Market Incumbents: Pre-empt flexible format encroachment by embedding RFID tracking and reconditioning services into ten-year total cost of ownership contracts that lock automotive chemical suppliers into circular recovery programs. Expand backward integration into captive high-density polyethylene recycling streams to neutralize resin cost volatility that compresses margins on fixed-price drum agreements.
For New Entrants and Emerging Players: Barrier-engineered pharmaceutical totes for Japanese precision chemical manufacturers represent the most penetrable entry point, given METI standards complexity that deters commoditized competitors. FDA-compliant food-grade container refurbishment services in India offer secondary white-space, with BIS certification pathways creating defensible positioning against unqualified regional fabricators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed drum manufacturers carrying leveraged balance sheets from prior rollup activity, vulnerable to steel price volatility and contract repricing cycles. Monitor REACH migration limit enforcement intensity as inflection indicator for replacement demand acceleration in European polyethylene container markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Greif's global refurbishment footprint captures recurring service revenue from chemical sector clients. |
| Barrier Technology Development | Sealed Air's multi-layer film engineering enables real-time content monitoring for pharmaceutical intermediates. |
| Backward Integration into Resin | Crown Holdings' captive aluminum supply insulates metal packaging margins from commodity volatility. |
| Certification Laboratory Partnership | UN testing capacity alliances in Germany compress validation timelines for new container geometries. |
| RFID Serialization Deployment | EPA 40 CFR electronic manifest compliance mandates drive tracking infrastructure investment across drum production lines. |
Research Approach
A standing panel of plant managers at chemical manufacturing facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors provided ongoing calibration across the study period. Primary interview findings triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and UN certification registry databases. Bottom-up volume estimates from individual packaging format consumption combined with top-down market sizing from regional production hub analysis.
Scenario-bracketing around REACH enforcement intensity, steel price volatility bands, and polyethylene recycling stream maturation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade tier, end-use industry vertical, packaging format category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year consumption estimates, with cross-validation against chemical sector capital expenditure pipelines and automotive export volume projections.
Practitioners should monitor ECHA migration limit implementation timelines, cold-rolled steel futures curve movements, and EPA electronic manifest rule enforcement for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Rigid Transparent Plastic Market