
 PCR Packaging Market | 2026-2036
PCR Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Packaging Market Analytics
European chemical recyclers is repositioning flake-to-pellet capacity toward food-grade outputs. Amcor plc leverages vertical integration across recycled PET collection and bottle preform production. Berry Global Group anchors North American supply through its network of mechanically recycled PP facilities. Mondi Group competes in industrial kraft-PCR hybrid formats for e-commerce shippers.
Post-consumer recycled packaging incorporates reprocessed polymers derived from discarded plastic waste, typically containing 25-100% recycled content depending on application and regulatory threshold. Manufacturers employ extrusion, injection molding, and thermoforming processes to produce containers, films, and trays that meet functional barrier requirements for food, beverage, and cosmetic applications. Recycled PET dominates beverage bottle demand due to clarity and regulatory acceptance for food contact. Recycled PP commands industrial packaging applications where durability and chemical resistance offset color variability. Films and trays represent the fastest-expanding product category, driven by fresh produce and ready-meal formats requiring modified-atmosphere performance.
The EPA oversees recycled-content claims under environmental marketing guidelines, while the EU Green Deal mandates minimum recycled quotas for plastic packaging placed on European markets. FDA issues letters of no objection for specific recycling processes enabling food-contact compliance, directly determining which PCR streams qualify for beverage and food packaging. California's SB 54 implements phased recycled-content floors for single-use plastics, creating compliance deadlines that reshape supplier qualification criteria. Stakeholders must monitor evolving food-contact regulatory harmonization between FDA process approvals and EU EFSA scientific opinions to secure cross-border supply contracts.
Market Dynamics
Extended producer responsibility laws in California and Germany are forcing packaging buyers to requalify suppliers against recycled-content floors, compressing procurement timelines and concentrating contract awards toward vertically integrated recyclers with food-grade certifications.
Growth Catalysts
- EU Green Deal recycled quotas:Mandated minimums for plastic packaging placed on European markets are pulling forward capital deployment into chemical recycling infrastructure.
- Beverage bottling clusters:California's concentration of beverage producers is scaling procurement of food-grade recycled PET through direct offtake agreements with mechanical recyclers.
- Fresh produce packaging:Modified-atmosphere tray demand from European supermarket chains is accelerating specification of recycled PP films with oxygen barrier coatings.
Market Restraints
- Flake supply concentration:Post-consumer PET bale availability clusters around Germany's industrial packaging corridor and California's deposit-return systems, creating geographic supply risk.
- Food-contact process costs:FDA letters of no objection for advanced recycling require extensive migration testing and challenge validation, adding twelve to eighteen months to qualification timelines.
- Mechanical degradation limits:Repeated thermal cycling of polypropylene reduces molecular weight and impact strength, constraining recycled content ratios in industrial pails and drums.
Strategic Opportunities
- India's emerging EPR framework:Draft extended producer responsibility rules for plastic packaging are creating first-mover advantage for recyclers establishing food-grade rPET capacity ahead of mandate enforcement.
- Chemical recycling convergence:Pyrolysis oil upgrading combined with steam cracker integration is enabling food-contact compliance for polymers previously limited to non-food applications.
- E-commerce shipper formats:Industrial kraft-PCR hybrid constructions for corrugated substitutes are capturing demand from third-party logistics providers seeking lightweight, recyclable cushioning.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for compatibilizing mixed-polymer waste streams is concentrated among a limited pool of specialists, constraining R&D velocity for next-generation barrier films.
- Legacy equipment retrofit costs:Converting extrusion lines from virgin to high-recycled-content feedstock requires screw and die modifications that extend downtime windows during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Packaging Market |
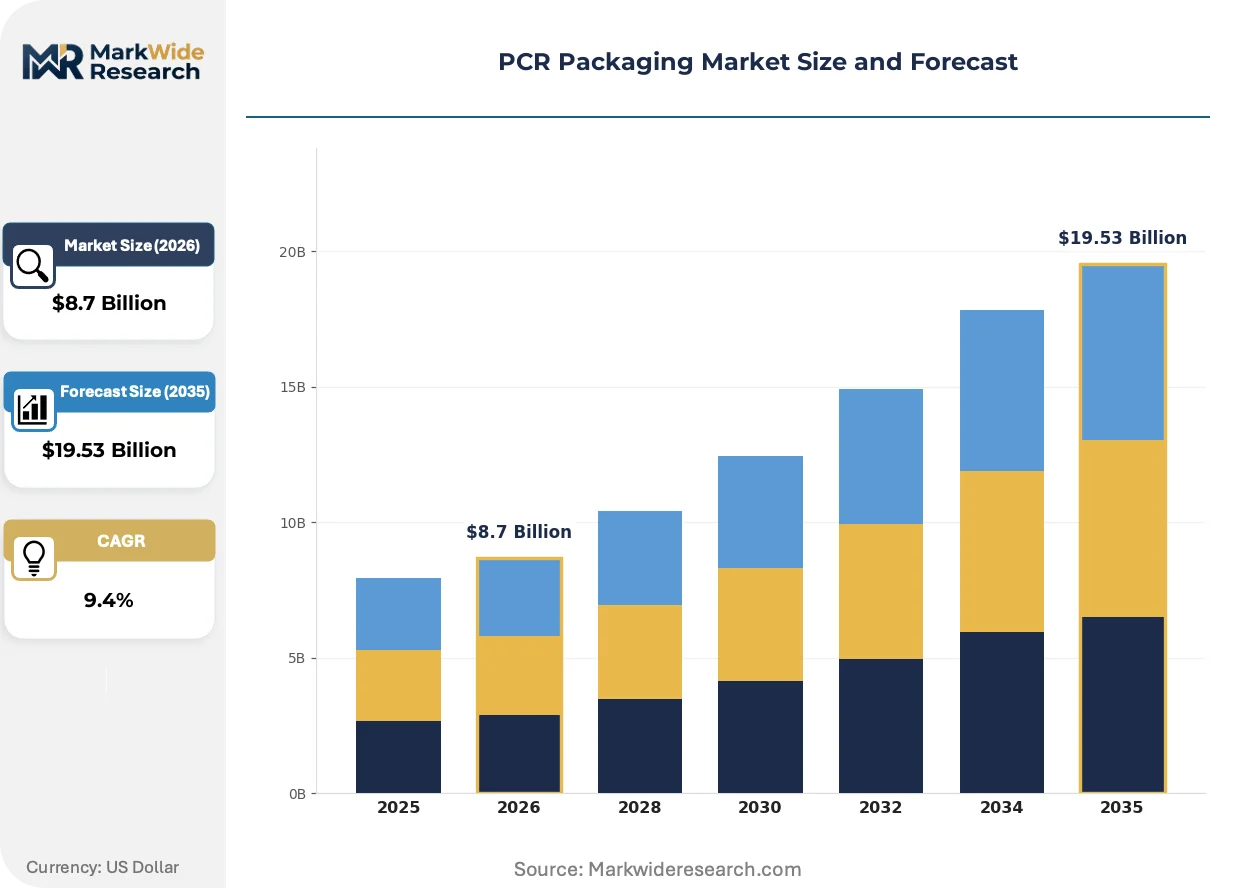
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Recycled PET, Recycled PP, Recycled PS, Recycled PVC Product Type: Bottles, Containers, Trays, Films End Use: Food Packaging, Beverage Packaging, Cosmetic Packaging, Industrial Packaging Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Amcor plc, Berry Global Group, Mondi Group, Sealed Air Corporation, ALPLA Group, Novolex, Transcontinental Inc., ePac Holdings, LLC, Sonoco Product Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Packaging Market Evolving Landscape
Advanced sorting and purification technologies are fragmenting the competitive landscape by lowering minimum efficient scale for food-grade recycled resin production, enabling regional challengers to compete with incumbent integrated producers.
Distributed chemical recycling units using pyrolysis and purification are decentralizing food-grade polymer supply away from coastal mega-facilities toward inland locations proximate to waste generation clusters. Mid-sized beverage bottlers in the US Midwest are piloting container-sized modular systems. This geographic diffusion is compressing logistics costs and shortening bale-to-pellet cycle times.
California's SB 54 phased mandates are forcing single-use plastic suppliers to document recycled-content percentages through third-party certification. Brand owners are responding by pre-purchasing multi-year offtake from qualified mechanical recyclers. The fresh produce sector faces the steepest compliance ramps and is consolidating supplier panels fastest.
Buyers are unbundling packaging specifications from traditional resin supply contracts, creating direct relationships with certified recyclers. European supermarket private-label programs are leading this disintermediation, establishing preferred supplier lists that bypass conventional distributor networks. Germany's discount retail chains have moved earliest, with comparable patterns emerging in France and the Netherlands.
PCR Packaging Market Segmentation
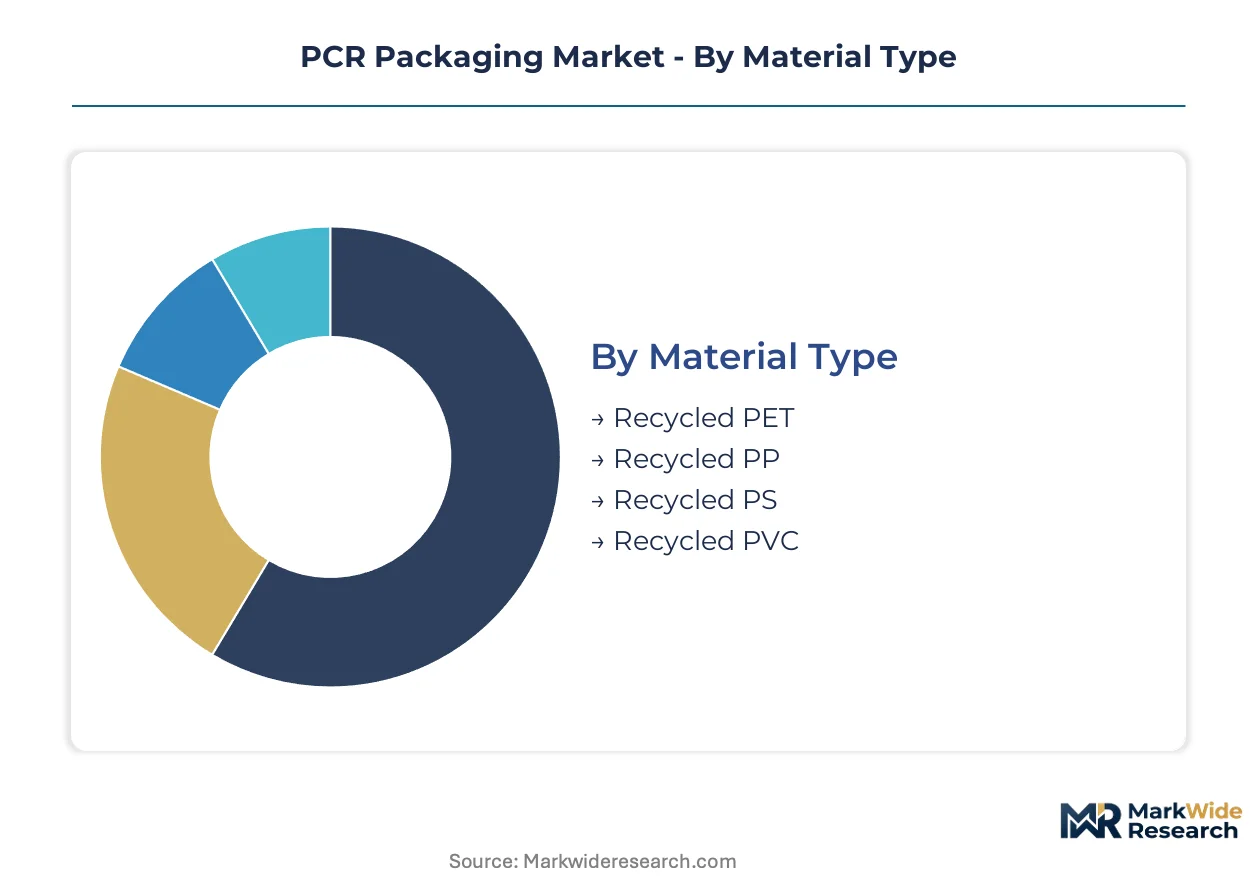
PCR packaging segmentation reveals divergent capital requirements across material purification and conversion technologies. Food-contact compliance drives investment intensity, while non-food applications tolerate lower-grade mechanical recycling infrastructure.
Material Type:
Recycled PET demands the steepest upfront capital due to FDA food-contact validation and super-cleaning equipment requirements.
- Recycled PET:Super-cleaning and solid-state polymerization systems achieve food-contact purity for beverage bottles. California's deposit-return infrastructure and Germany's industrial corridor concentrate flake supply, though bale quality variability constrains yield rates.
- Recycled PP:Mechanical recycling with melt filtration and odor removal serves industrial pails and non-food containers. Chemical recycling investments by European petrochemical clusters are expanding food-grade availability for modified-atmosphere trays.
- Recycled PS:Dissolution-based purification addresses styrene monomer recovery for foam and rigid applications.
- Recycled PVC:Limited food-contact acceptance restricts deployment to construction and non-packaging films.
Recycled PET absorbs the bulk of installed capacity; recycled PP is expanding most quickly through chemical recycling convergence.
Product Type:
Product categories stratify by barrier performance requirements and molding technology complexity.
- Bottles:Stretch blow molding of recycled PET dominates beverage applications where clarity and CO2 retention are critical. California's SB 54 mandates are accelerating preform supplier consolidation around vertically integrated recyclers with FDA letters of no objection.
- Films:Co-extruded and coated constructions for fresh produce and ready-meal formats require oxygen barrier engineering. European supermarket private-label programs are disintermediating traditional distributors to secure certified recycled-content supply.
- Containers:Injection-molded tubs and jars serve dairy and spreads with intermediate barrier demands.
- Trays:Thermoformed modified-atmosphere packaging for protein and produce segments faces steep compliance ramps under EU Green Deal quotas.
Bottles command the highest unit margins; films are climbing the fastest as fresh produce specifications tighten.
End Use:
End-use segmentation reflects divergent regulatory scrutiny and brand-owner risk tolerance.
- Food Packaging:Modified-atmosphere trays, films, and rigid containers face EFSA scientific opinion requirements in Europe and FDA process approvals in the United States. Migration testing timelines of twelve to eighteen months create qualification backlogs for new recycling entrants.
- Beverage Packaging:Carbonated soft drink and water bottles represent the most standardized application with established rPET supply chains. Direct offtake agreements between bottlers and mechanical recyclers are displacing traditional resin distributor relationships.
- Cosmetic Packaging:Premium positioning tolerates higher cost structures for certified ocean-bound or traceable recycled content.
- Industrial Packaging:Pails, drums, and intermediate bulk containers accept lower recycled content ratios due to mechanical degradation tolerance and color variability.
Food packaging concentrates compliance investment; beverage packaging is gaining share fastest through pre-qualified supply base expansion.
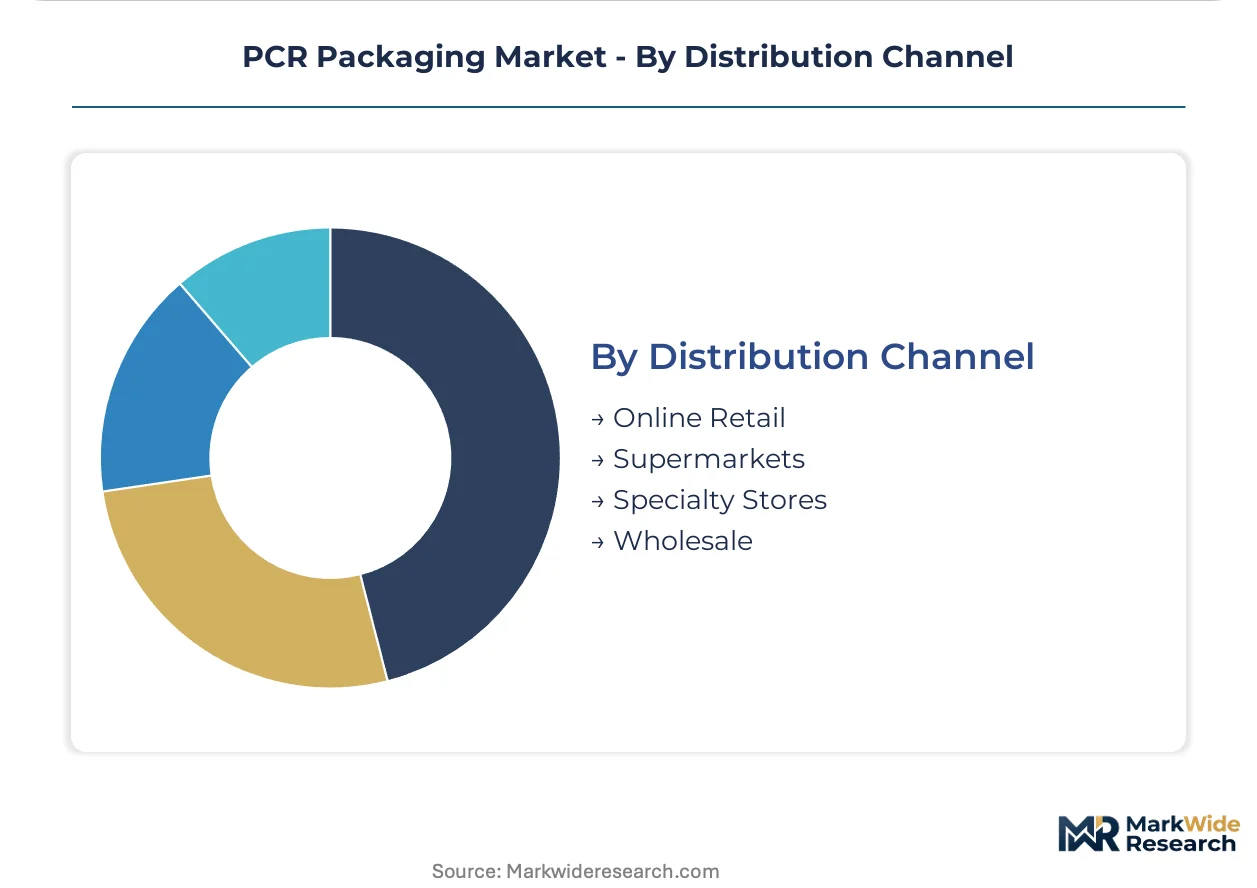
Distribution Channel:
Channel segmentation tracks procurement centralization and certification documentation requirements.
- Supermarkets:Private-label programs in Germany, France, and the Netherlands are establishing preferred supplier lists that bypass conventional distributor networks. Third-party recycled-content certification is becoming a mandatory qualification gate.
- Wholesale:Industrial and food-service buyers procure in bulk with lower documentation thresholds, though California's phased mandates are extending compliance pressure downstream.
- Online Retail:E-commerce shipper formats favor lightweight kraft-PCR hybrid constructions for corrugated substitutes.
- Specialty Stores:Premium cosmetic and gourmet food segments command traceability premiums for certified recycled content.
Supermarkets absorb the bulk of compliance-driven procurement transformation; wholesale channels are adapting fastest to documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer PET bale availability clusters around Germany's industrial packaging corridor and California's deposit-return systems, creating geographic supply anchors that shape regional competitive dynamics.
United States
Beverage bottling clusters in California are scaling procurement of food-grade recycled PET through direct offtake agreements with mechanical recyclers. The EPA oversees recycled-content claims under environmental marketing guidelines, while California's SB 54 implements phased recycled-content floors for single-use plastics. Los Angeles and San Francisco Bay Area recycling infrastructure is consolidating around vertically integrated suppliers with FDA letters of no objection.
Germany
Industrial packaging demand concentrates in the Rhine-Ruhr corridor where chemical recyclers are repositioning flake-to-pellet capacity toward food-grade outputs. The EU Green Deal mandates minimum recycled quotas for plastic packaging placed on European markets. Hamburg and Düsseldorf anchor the country's deposit-return collection density, feeding mechanical recycling lines serving beverage and fresh produce formats.
India
Draft extended producer responsibility rules for plastic packaging are creating first-mover advantage for recyclers establishing food-grade rPET capacity ahead of mandate enforcement. The FSSAI and BIS are developing standards for recycled-content claims in food-contact applications. Maharashtra and Gujarat industrial corridors are attracting pyrolysis-based chemical recycling investments targeting food-grade polymer output.
France
Supermarket private-label programs in Paris and Lyon are establishing preferred supplier lists that bypass conventional distributor networks for certified recycled-content supply. EFSA scientific opinion requirements determine which PCR streams qualify for food packaging under EU harmonized standards. The Île-de-France region hosts the densest concentration of modified-atmosphere tray specification activity.
Japan
METI guidelines on plastic resource circulation are tightening recycled-content expectations for packaging placed on domestic markets. The Kanto region around Tokyo concentrates demand from beverage and cosmetic brand owners seeking traceable recycled content. Osaka-based trading houses are securing long-term offtake from Southeast Asian mechanical recyclers to hedge domestic flake supply constraints.
PCR Packaging Market Competitive Landscape
Global majors compete with regional champions across certification depth and food-grade resin access. The market structure tilts toward consolidation as procurement timelines compress under extended producer responsibility compliance deadlines. Three archetypes dominate: vertically integrated recyclers with FDA/EFSA approvals, mechanical recycling specialists serving industrial non-food segments, and chemical recycling ventures targeting food-contact purity. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure flake supply and downstream offtake.
Within the integrated recycler tier, Amcor plc and Berry Global Group exemplify archetypes combining collection infrastructure with conversion capabilities. Mondi Group occupies a position bridging industrial kraft-PCR hybrid formats with e-commerce shipper demand. These three entities anchor distinct competitive vectors: beverage bottle preform production, mechanically recycled PP facilities, and corrugated substitute development respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Mondi Group |
| Sealed Air Corporation |
| ALPLA Group |
| Novolex |
| Transcontinental Inc. |
| ePac Holdings, LLC |
| Sonoco Product Company |
| Others |
Value Network & Pricing Analysis
Polymer chemist concentration in Germany's Rhine-Ruhr corridor and California's Central Valley widens pricing-tier spreads, as formulation expertise for food-contact compatibilizers commands premium compensation against standardized mechanical recycling labor pools.
Pricing Analysis
Warranty and migration-testing bundling separates premium FDA-validated rPET from unbundled industrial-grade recycled PP, with certification-inclusive contracts commanding substantial markups. Three-tier pricing structure across food-contact certified, industrial-grade, and non-food commodity levels reflects FDA letter-of-no-objection status and EFSA scientific opinion depth. Cost compression in industrial pail segments is intensifying because mechanical degradation limits force virgin resin blending, eroding recycled-content premiums. Small beverage bottlers exhibit highest price sensitivity, while European supermarket private-label programs absorb certification premiums for supply security.
Supply Chain Analysis
Single-source vulnerability sits with Germany's deposit-return flake processors and California's mechanical recyclers, where bale-quality variability constrains yield rates. Raw material flows draw from post-consumer PET bales, pyrolysis oil feedstocks, and industrial kraft fiber streams. Tariff exposure on imported flake from Southeast Asian collectors threatens cost structures for Midwest US converters. Distribution runs through vertically integrated recycler-direct contracts that displace traditional resin distributors, with European supermarket chains pioneering preferred-supplier-list procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade rPET capacity scarcity props pricing premiums, as FDA validation timelines and super-cleaning equipment requirements constrain qualified supply expansion.
For Market Incumbents: Cement backward integration into bale collection infrastructure to secure flake supply against emerging chemical recycling ventures. Expand food-grade pellet capacity in Germany's industrial corridor ahead of EU Green Deal quota enforcement. Prioritize EFSA scientific opinion maintenance to defend European supermarket preferred-supplier status against Asian mechanical recyclers. For New Entrants and Emerging Players: Enter via India's draft EPR framework ahead of mandate enforcement, targeting Maharashtra and Gujarat industrial corridors with pyrolysis-based chemical recycling. Pursue modular container-sized systems for Midwest US beverage bottlers seeking shortened bale-to-pellet cycles. Lead with direct offtake contracting to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with European chemical recyclers achieving food-contact pyrolysis oil upgrading given steam cracker integration catalysts. Five-to-ten-year viability favors ventures with captive waste supply agreements and downstream brand-owner offtake. Monitor FDA letter-of-no-objection issuance velocity as inflection signal for food-grade capacity scarcity easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bale Collection | Captive flake supply secures yield rates against Germany and California supply concentration. |
| Food-Grade Chemical Recycling Scale-Up | Pyrolysis oil upgrading enables EFSA-compliant polymer output from previously excluded waste streams. |
| Direct Offtake Agreement Structuring | Bypassing distributors aligns recyclers with European supermarket private-label procurement transformation. |
| Modular Decentralized Unit Deployment | Container-sized systems compress logistics costs for inland US beverage bottling clusters. |
| Third-Party Certification Pre-Positioning | California SB 54 documentation requirements create qualification gates for supplier panel consolidation. |
Research Methodology
Multi-period observation of FDA letter-of-no-objection issuance rates, EU EFSA scientific opinion timelines, and bale-to-pellet yield metrics anchored the trend analysis, supplemented by interviews with mechanical recycling plant managers, beverage bottler procurement leads, European supermarket category buyers, chemical recycling R&D directors, and extended producer responsibility policy officers. Secondary validation drew from EPA environmental marketing guidelines, EU Green Deal mandate documentation, California SB 54 regulatory filings, FSSAI draft standards, and SEC 10-K disclosures from packaging converters. Bottom-up capacity modeling and top-down demand projection triangulated market sizing.
Input-output matrices mapped recycled PET, PP, PS, and PVC flows across super-cleaning, mechanical recycling, pyrolysis upgrading, and dissolution purification pathways, segmented by food-contact compliance tier, product format, end-use application, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity deployment schedules across the analysis window. Industry-specific inputs included migration testing backlog durations, flake bale quality distributions, and steam cracker integration timelines for chemical recycling ventures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA process approval accelerations or EU Green Deal quota relaxation. Forecasts incorporate documented assumptions regarding EFSA-FDA harmonization progress, bale supply growth from deposit-return expansion, and chemical recycling yield rate maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Global Thin Wall Packaging Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Corrugated Wrap Around Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Primary Packaging Market