
 Netherlands Container Glass Market | 2026-2036
Netherlands Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Container Glass Market Foresight
Lightweight glass technology is narrowing the cost gap between virgin and recycled container production across Dutch manufacturing lines. Ardagh Glass Packaging leverages its European furnace network to sustain high-volume output for beverage clients. O-I Netherlands anchors domestic supply through its Maastricht facility, while Vetropack Holding competes on specialty colored glass for premium spirits.
Container glass consists of silica sand, soda ash, limestone, and cullet, melted at approximately 1,500°C to form rigid, chemically inert vessels for liquid and semi-solid storage. Bottles dominate the product type landscape, though flacons command stronger margins in pharmaceutical and cosmetic applications. The end user base tilts heavily toward food and beverage, where recycled glass formulations are gaining share under retailer sustainability mandates.
The EU Green Deal and Dutch national carbon budgets pressure producers to cut furnace emissions, while REACH compliance governs chemical safety in decorative coatings and inks. The Netherlands' central bank and environmental regulator track industrial energy use, tightening access to gas-fired production capacity. Stakeholders must monitor EU ETS price trajectories and green hydrogen pilot programs to time capital decisions on furnace electrification.
Market Dynamics
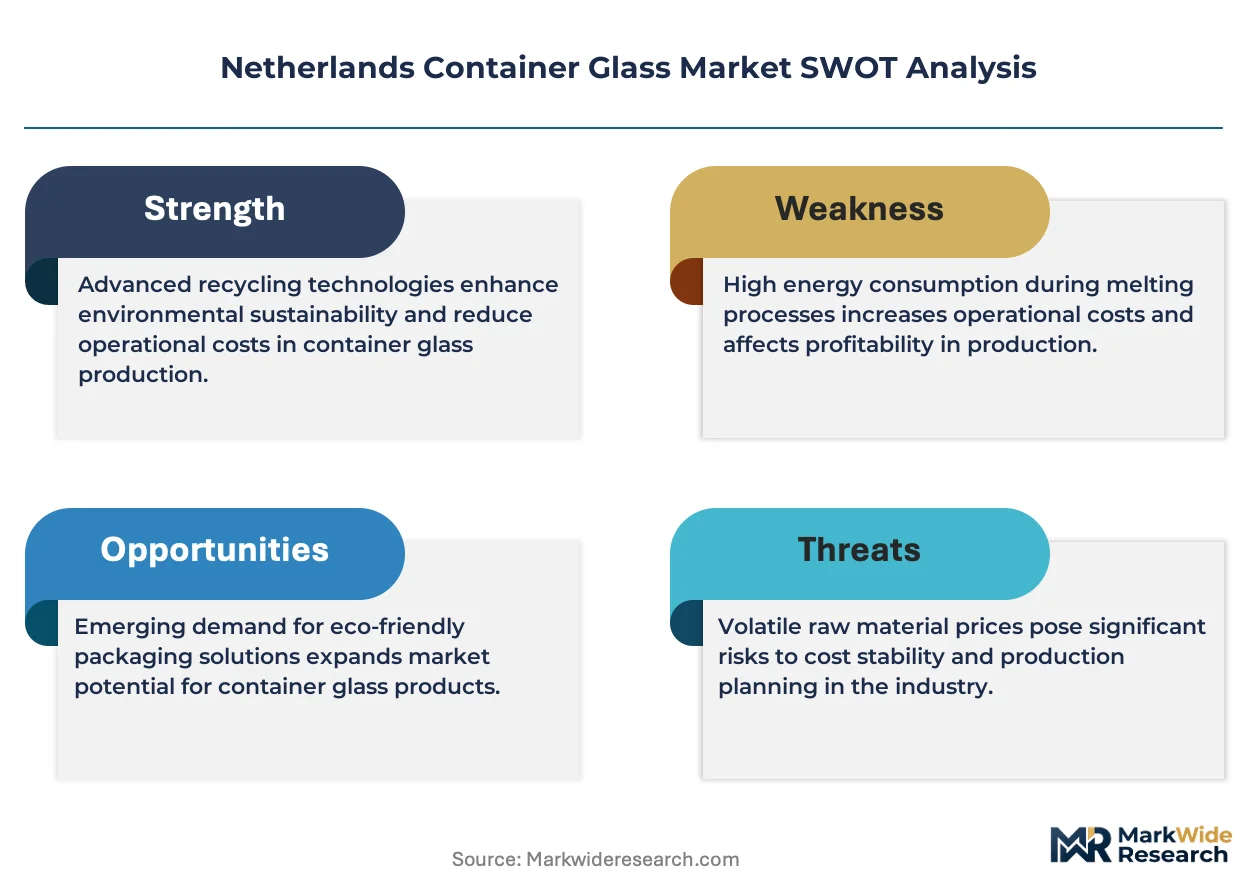
Furnace electrification timelines and EU ETS carbon pricing are compressing capital allocation cycles for Dutch container glass producers, forcing decisions on gas-to-electric conversion before 2030.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding national carbon budgets accelerate lightweight glass adoption across beverage packaging lines. Dutch brewers and distillers source thinner-walled bottles to meet retailer sustainability scorecards.
- Randstad food processing cluster density:Concentrated demand from dairy, sauces, and condiment manufacturers in the urban corridor sustains high-volume procurement of standard amber and flint containers.
- Recycled cullet supply chain maturation:Municipal collection infrastructure improvements in North Holland and South Holland boost post-consumer glass availability for furnace feedstock, narrowing quality variance against virgin silica.
Market Restraints
- Natural gas price volatility:Dutch glass furnaces remain predominantly gas-fired, exposing margins to TTF benchmark fluctuations and grid congestion charges during winter peaks.
- Specialty colorant supply concentration:Cobalt and selenium additives for premium spirits packaging originate from concentrated overseas mining operations, creating input vulnerability.
- Aluminum can substitution in beer:Macro-breweries in the Netherlands are expanding canning lines for export markets, eroding glass share in volume segments.
Strategic Opportunities
- Zeeland and Limburg underpenetrated zones:Peripheral provinces lack localized container glass production, creating logistics arbitrage for new furnace capacity or satellite forming operations.
- Pharmaceutical flacon specialization:Cosmetic and OTC drug brands in Utrecht and Leiden medical corridors seek borosilicate and Type III glass for stability-critical formulations.
- Green hydrogen pilot integration:The Dutch national hydrogen backbone program offers grant pathways for hybrid hydrogen-natural gas furnace trials, positioning early adopters for 2040 net-zero compliance.
Industry Challenges
- Electrical furnace engineering talent scarcity:Deep expertise in resistive and plasma melting systems resides outside the Netherlands, requiring expensive expatriate hiring or German/Danish contractor reliance.
- REACH decorative coating compliance:Heavy-metal-free inks and organic pigments for premium bottle labeling demand extended ECHA registration timelines, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Container Glass Market |
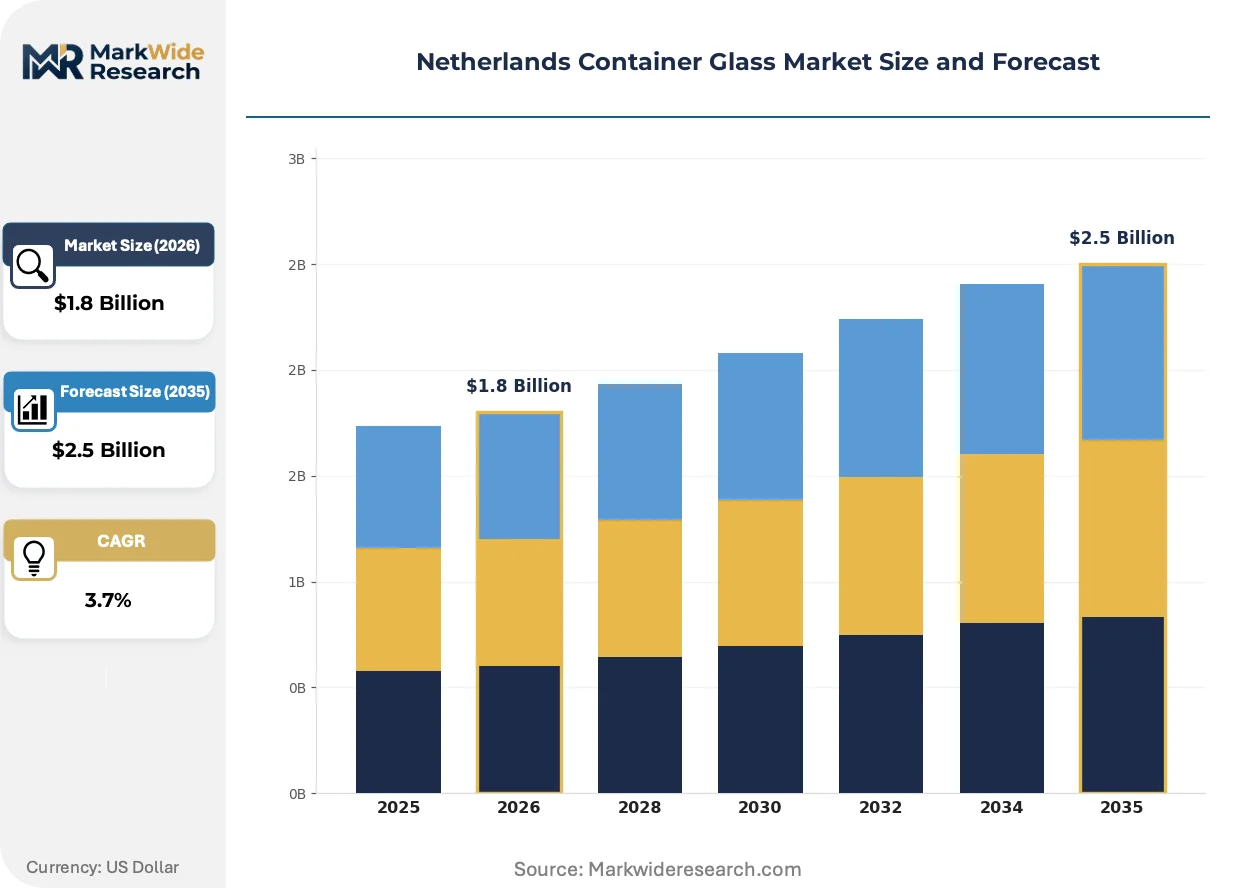
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Flacons End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Form: Glass, Recycled Glass, Lightweight Glass, Colored Glass Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Ardagh Glass Packaging, O-I Netherlands, Vetropack Holding, Verallia Netherlands, BA Glass Netherlands, Stolzle Glass Group, AGC Glass Europe, Miron Violetglass, Berlin Packaging Netherlands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Container Glass Market Shifts & Advancements
Digital furnace control systems and alternative thermal energy sources are restructuring how Dutch producers balance output consistency against carbon intensity targets.
Thin-walled lightweight glass is hybridizing traditional container strength with material efficiency gains. Ardagh and O-I Netherlands deploy laser inspection and predictive thickness algorithms to maintain structural integrity at 15-20% weight reduction. Premium beverage brands in Amsterdam and Rotterdam accept these specifications for domestic craft portfolios, compressing the cost premium against standard-weight alternatives.
EU ETS Phase IV carbon border adjustments are tightening furnace emission accounting requirements. Dutch installations must install continuous emissions monitoring systems and verify Scope 2 electricity provenance. Smaller colored-glass specialists face disproportionate compliance burdens relative to flint-volume leaders, accelerating consolidation pressure in specialty segments.
Direct procurement contracts between Randstad food manufacturers and single-furnace operators are displacing traditional distributor intermediaries. Albert Heijn and Jumbo supermarket chains mandate batch-level carbon disclosure, forcing glass suppliers to integrate blockchain traceability or third-party certification. This pattern concentrates most visibly in the North Holland dairy corridor, where yogurt and dessert brands source transparently for private-label lines.
Netherlands Container Glass Market Segmentation
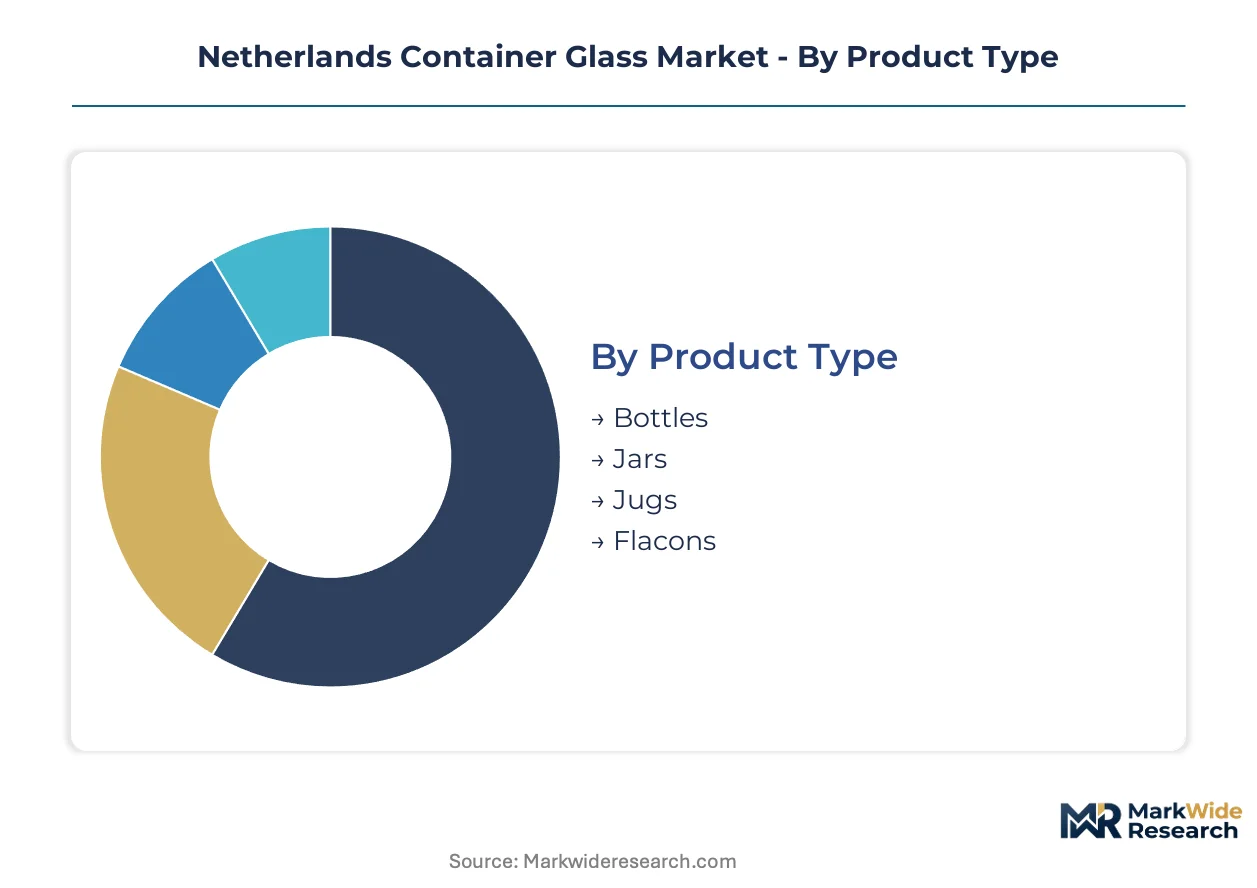
Container glass segmentation in the Netherlands reveals how furnace technology, end-use chemistry, and retail procurement patterns create distinct commercial battlegrounds. Understanding these divides exposes where margin concentrates and where volume growth will accelerate through the forecast window.
Product Type:
Maturity spans from century-old bottle formats to emerging flacon designs serving pharmaceutical precision requirements.
- Bottles:Cylindrical vessels with narrow necks dominate beverage containment, formed through IS machine blowing at Ardagh and O-I Netherlands facilities. Randstad brewers and distillers procure amber and flint variants under retailer sustainability mandates, though aluminum can substitution erodes share in export-focused macro-beer segments.
- Jars:Wide-mouth containers with lug or continuous thread finishes preserve sauces, condiments, and dairy products. North Holland dairy processors source standard amber jars for private-label yogurt lines, with Albert Heijn and Jumbo mandating batch-level carbon disclosure through blockchain traceability.
- Jugs:Large-capacity vessels with handle attachments serve institutional food service and bulk retail formats. Limited domestic production concentrates procurement among specialized importers serving hospitality distributors.
- Flacons:Precision-molded containers with narrow apertures and controlled wall thickness protect pharmaceutical and cosmetic formulations. Leiden and Utrecht medical corridors drive demand for borosilicate and Type III stability-critical variants.
Bottles retain volume leadership; flacons hold the steepest expansion curve.
End User:
Application intensity varies from mass-market beverage throughput to specialized pharmaceutical stability requirements.
- Food & Beverage:The largest consumption block spans craft beer, spirits, sauces, and dairy packaging. Dutch brewers source lightweight glass to meet EU Green Deal carbon budgets, while supermarket chains enforce sustainability scorecards that privilege recycled-content formulations.
- Pharmaceuticals:Stability-critical drug packaging demands Type III soda-lime and borosilicate glass with controlled hydrolytic resistance. EMA compliance and REACH coating regulations govern decorative ink selection for OTC and prescription lines.
- Cosmetics:Premium fragrance and skincare brands in Amsterdam and Rotterdam specify colored glass and heavy-metal-free labeling. REACH registration timelines for organic pigments delay new product launches in this segment.
- Household:Cleaning product and candle containers represent price-sensitive procurement with lower technical specifications. Private-label concentration drives volume through wholesale distributor channels.
Food & Beverage commands absolute volume; Pharmaceuticals delivers the highest margin per ton.
Form:
Material composition tracks the industry's forced march from virgin silica dependence toward circular and lightweight alternatives.
- Glass:Virgin silica-soda-lime formulations remain the baseline for structural integrity and optical clarity. Maastricht facility output anchors domestic supply of standard flint and amber grades.
- Recycled Glass:Post-consumer cullet from North Holland and South Holland municipal collection feeds furnace operations at 60-90% inclusion rates. Quality variance against virgin material narrows as optical sorting technology improves.
- Lightweight Glass:Thin-walled designs achieve 15-20% weight reduction through laser inspection and predictive thickness algorithms. Amsterdam craft brewers accept these specifications, compressing cost premiums against standard-weight alternatives.
- Colored Glass:Cobalt and selenium additives create premium spirits packaging with concentrated overseas mining exposure. Vetropack Holding competes on specialty colored production for distillers seeking differentiation.
Standard glass retains furnace dominance; lightweight variants gain share fastest under carbon pricing pressure.
Distribution Channel:
Channel structure reflects the displacement of intermediaries by direct procurement and digital traceability mandates.
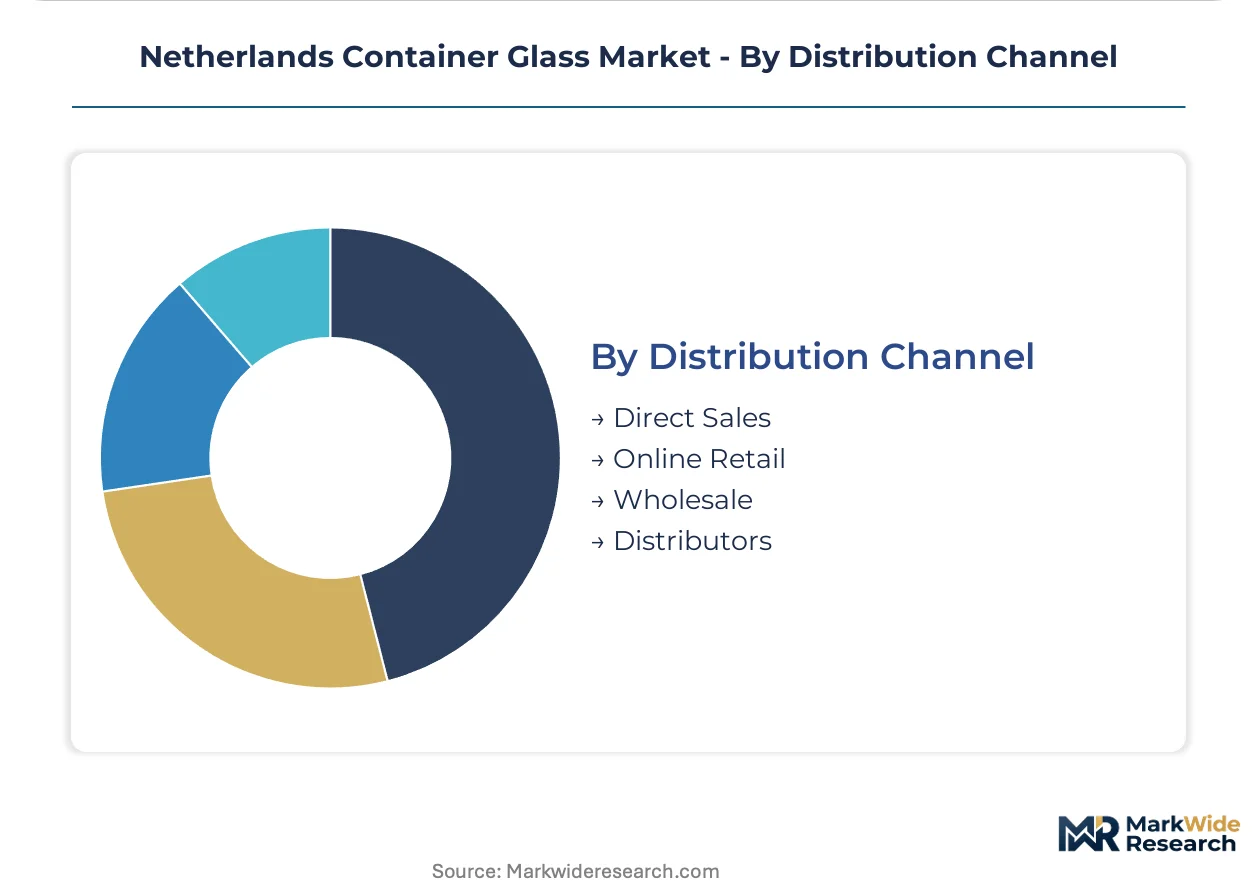
- Direct Sales:Randstad food manufacturers contract single-furnace operators for transparent supply chain documentation. Blockchain-enabled batch tracking satisfies supermarket chain disclosure requirements.
- Online Retail:Digital platforms serve small-batch cosmetic and craft beverage producers with lower minimum order quantities. Logistics complexity limits penetration for heavy, fragile container shipments.
- Wholesale:Aggregated procurement through food service and hospitality distributors serves household and institutional segments. Price competition concentrates volume among standardized jar and jug formats.
- Distributors:Traditional intermediaries retain role in peripheral provinces where localized production gaps create logistics arbitrage opportunities in Zeeland and Limburg.
Direct sales capture margin leadership; online retail shows the most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch container glass exports flow primarily toward Germany and Belgium, with Rotterdam and Antwerp forming a consolidated North Sea distribution corridor for beverage and pharmaceutical packaging.
Randstad
Amsterdam and Rotterdam breweries drive premium lightweight bottle procurement under retailer sustainability mandates. The Dutch environmental regulator enforces industrial carbon budgets that accelerate furnace feedstock shifts. North Holland dairy processors in Alkmaar and Hoorn source amber jars with blockchain-tracked recycled content for Albert Heijn private-label lines.
Brabant
Eindhoven's pharmaceutical corridor demands Type III borosilicate flacons for stability-critical drug formulations. REACH compliance governs decorative coating selection for cosmetic packaging exported to Germany. Tilburg and Breda logistics hubs consolidate container shipments for Limburg and Zeeland peripheral markets lacking localized production.
Eindhoven Region
High-tech manufacturing spillover creates demand for precision-molded laboratory glassware alongside pharmaceutical containers. The national hydrogen backbone program funds pilot trials for hybrid furnace operations in this industrial zone. ASML supplier clusters nearby drive packaging specifications for chemical reagent containment.
Northern Netherlands
Groningen and Friesland food processors rely on imported container supply from Randstad and German facilities. EU ETS carbon border adjustments disadvantage long-haul glass shipments into this underpenetrated zone. Dairy cooperatives in Leeuwarden press for direct procurement contracts to bypass distributor markups on standard jar formats.
Zeeland and Limburg
Peripheral provinces lack domestic furnace capacity, creating logistics arbitrage for Maastricht facility output and Belgian cross-border supply. O-I Netherlands anchors regional availability through its Maastricht forming operation. Borderland distillers in Vaals source specialty colored glass from German and Belgian suppliers to circumvent Randstad procurement bottlenecks.
Netherlands Container Glass Market Competitive Landscape
On the supply side, the industry is consolidating around furnace-scale advantages and sustainability-linked procurement contracts. Three strategic archetypes dominate: integrated European networks with multi-country furnace footprints, domestic single-facility operators serving regional food clusters, and specialty colored-glass specialists competing on premium spirits differentiation. Competitive moves concentrate on lightweight technology licensing partnerships and direct-to-manufacturer sales channel expansion displacing traditional distributors.
Among European-integrated networks, Ardagh Glass Packaging and O-I Netherlands exemplify scale-driven archetypes with cross-border furnace coordination capabilities. Vetropack Holding occupies a specialty-tier position focused on colored glass differentiation for premium beverage segments. These three names anchor the competitive structure through which smaller Dutch and Belgian operators must navigate procurement relationships with Randstad retail chains and pharmaceutical corridors.
| Leading Market Players |
|---|
| Ardagh Glass Packaging |
| O-I Netherlands |
| Vetropack Holding |
| Verallia Netherlands |
| BA Glass Netherlands |
| Stolzle Glass Group |
| AGC Glass Europe |
| Miron Violetglass |
| Berlin Packaging Netherlands |
| Others |
Supply & Pricing Matrix
EU ETS carbon border adjustments compress furnace economics across Dutch container glass production, widening the spread between lightweight premium formulations and standard-weight commodity grades while reshaping procurement geography toward Randstad-adjacent facilities.
Pricing Analysis
Lightweight glass technology premiums against virgin-soda-lime baselines determine current price architecture. Three-tier pricing structure across premium lightweight, standard recycled-content, and economy virgin-glass levels stratifies buyer segments. Pricing pressure stems from supermarket chain sustainability mandates forcing batch-level carbon disclosure investments. Food and beverage manufacturers show highest price sensitivity, while pharmaceutical flacon buyers absorb premiums for borosilicate stability specifications.
Supply Chain Analysis
REACH chemical safety restrictions on decorative coatings and heavy-metal inks constrain cross-border formulation flows into Dutch forming operations. Raw material sourcing draws from German silica sand deposits, Belgian soda ash processing, and overseas cobalt mining for specialty colorants. Single-source vulnerability concentrates in selenium additive supply from concentrated overseas operations. Distribution runs through direct procurement contracts displacing traditional wholesale intermediaries in North Holland dairy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supermarket chain consolidation around Albert Heijn and Jumbo procurement standards shifts negotiating leverage toward buyer-side sustainability scorecards, forcing supplier compliance investments.
For Market Incumbents: Build captive cullet supply moats through backward integration into North Holland and South Holland municipal collection infrastructure. Secure long-term offtake agreements with Randstad dairy processors before competitor furnace electrification timelines compress. Aluminum can substitution in export beer segments and EU ETS Phase IV compliance costs threaten margin stability; prioritize lightweight technology licensing to amortize R&D across European network partners. For New Entrants and Emerging Players: Zeeland and Limburg peripheral provinces offer logistics arbitrage opportunities absent localized furnace capacity. Target pharmaceutical flacon specialization in Utrecht and Leiden medical corridors where Type III glass demand outpaces domestic borosilicate supply. Pursue green hydrogen pilot integration grants through the Dutch national hydrogen backbone program to differentiate against gas-fired incumbents. For Investors and Strategic Acquirers: Single-facility operators with direct procurement relationships to Albert Heijn and Jumbo private-label lines represent consolidation targets. Long-term viability hinges on furnace electrification readiness and blockchain traceability infrastructure deployment across the analysis window. Watch EU ETS price trajectories and green hydrogen pilot scale-up as inflection indicators for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Investment | Positions operators for EU ETS Phase IV compliance and 2040 net-zero alignment under Dutch carbon budgets. |
| Lightweight Technology Licensing | Enables Ardagh and O-I Netherlands to monetize laser inspection and predictive thickness algorithms across European network. |
| Direct Procurement Channel Expansion | Displaces distributor intermediaries serving Randstad food manufacturers under supermarket chain traceability mandates. |
| Green Hydrogen Pilot Integration | Unlocks Dutch national hydrogen backbone grants for hybrid furnace trials in Eindhoven industrial zone. |
| Pharmaceutical Flacon Specialization | Captures margin premiums from Leiden and Utrecht medical corridor demand for borosilicate stability-critical packaging. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork with Randstad brewery procurement managers, North Holland dairy processor supply chain directors, Maastricht facility operations leads, pharmaceutical packaging engineers in Leiden, and Eindhoven logistics hub coordinators. Secondary validation incorporated EU ETS emissions registry data, Dutch environmental regulator industrial energy filings, REACH substance registration databases, and supermarket chain sustainability disclosure requirements. Bottom-up furnace output estimates triangulated against top-down end-use consumption models across beverage, dairy, and pharmaceutical segments.
Calibration against historical capacity utilization and furnace feedstock shifts anchored projection parameters across the modeling period. Segmentation dimensions included product type, end-use application, material composition, and distribution channel structure. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity expansion schedules. Industry-specific inputs encompassed EU carbon price scenarios and lightweight glass adoption curves in craft beverage packaging.
Macroeconomic conditions sit as an overlay; deviation in natural gas price volatility and TTF benchmark fluctuations would shift the trajectory. Forecasts assume sustained EU Green Deal implementation pace and Dutch national carbon budget enforcement. Material shifts in furnace electrification technology readiness or green hydrogen infrastructure deployment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Oman Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Container Glass Coatings Market