
 Plastic Tamper Evident Closures Market | 2026-2036
Plastic Tamper Evident Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Tamper Evident Closures Market Analytics
Pharmaceutical packaging is broadening its share of tamper-evident closure procurement as biologics and self-administered therapies multiply. Berry Global leverages vertical integration from resin to finished closure across North American pharmaceutical corridors. Amcor sustains technology leadership in multilayer oxygen-barrier structures for sensitive liquid formulations. Silgan Holdings anchors its position through dedicated manufacturing scale serving branded and generic drug makers.
Plastic tamper evident closures are injection-molded or compression-molded polymeric sealing devices incorporating breakable bands, tear strips, or indicator rings that reveal prior opening; they typically employ polypropylene or high-density polyethylene formulated for dimensional stability and torque retention. Their primary purpose is to protect packaged contents from contamination, adulteration, or unauthorized access across supply chain handoffs. Screw caps dominate pharmaceutical and beverage applications where resealability and torque consistency matter most, while child-resistant caps command premium positioning due to specialized testing protocols and patent-protected mechanisms. Polypropylene leads material selection for its chemical resistance and living-hinge compatibility in flip-top designs, though polyethylene retains cost advantages in high-volume food segments.
The FDA enforces tamper-evident packaging requirements under 21 CFR 211 for over-the-counter human drug products, while the EU MDR extends similar mandates to medical device kits and combination products. ISO 8317 and US 16 CFR 1700 govern child-resistant closure performance, creating dual compliance burdens that favor suppliers with certified testing laboratories. REACH and RoHS constrain plasticizer and additive chemistries, pushing converters toward validated raw material qualifications. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables, as these will increasingly determine supplier qualification timelines and capital allocation priorities.
Market Dynamics
Pharmaceutical serialization mandates are compressing supplier qualification timelines and forcing converters to pre-validate closure designs against evolving extractables protocols before commercial deployment.
Growth Catalysts
- FDA 21 CFR 211 Enforcement:The regulation mandates tamper-evident features for all over-the-counter human drug products, compelling pharmaceutical packagers to retrofit existing container lines with compliant closure systems.
- Biologics Cold-Chain Expansion:Temperature-sensitive protein therapies require closures with validated seal integrity across freeze-thaw cycles, driving specification upgrades in parenteral packaging.
- Rhine-Main Contract Packaging Cluster:Concentrated pharmaceutical manufacturing and third-party packaging services around Frankfurt generate sustained procurement volume for high-performance tamper-evident solutions.
Market Restraints
- Polypropylene Resin Volatility:Feedstock price swings tied to propylene monomer supply disruptions compress converter margins and complicate long-term contract pricing.
- Dual-Compliance Testing Burden:ISO 8317 child-resistant certification叠加 with FDA tamper-evident validation extends product development cycles and raises fixed qualification costs.
- Aluminum Closure Substitution:Premium beverage and spirits segments retain preference for metal tamper-evident solutions where perceived quality justifies higher unit cost.
Strategic Opportunities
- Indian Pharmaceutical Export Growth:CDSCO alignment with ICH guidelines and expanding US FDA-approved manufacturing sites create demand for export-compliant closure sourcing.
- Smart Closure Convergence:Integration of NFC tags and printed electronics with conventional polypropylene closures enables authentication and supply chain traceability for high-value generics.
- Direct-to-Patient Pharmacy Channels:Mail-order and specialty pharmacy fulfillment requires closures with enhanced drop-shock resilience and intuitive opening mechanics for elderly patient populations.
Industry Challenges
- Extractables Testing Talent Scarcity:Qualified analytical chemists capable of USP <661.1> and <1664> leachables studies command premium compensation and extend staffing timelines.
- Legacy Line Retrofit Complexity:Pharmaceutical packagers face mechanical incompatibility when installing new closure formats on existing capping equipment with fixed torque specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Tamper Evident Closures Market |
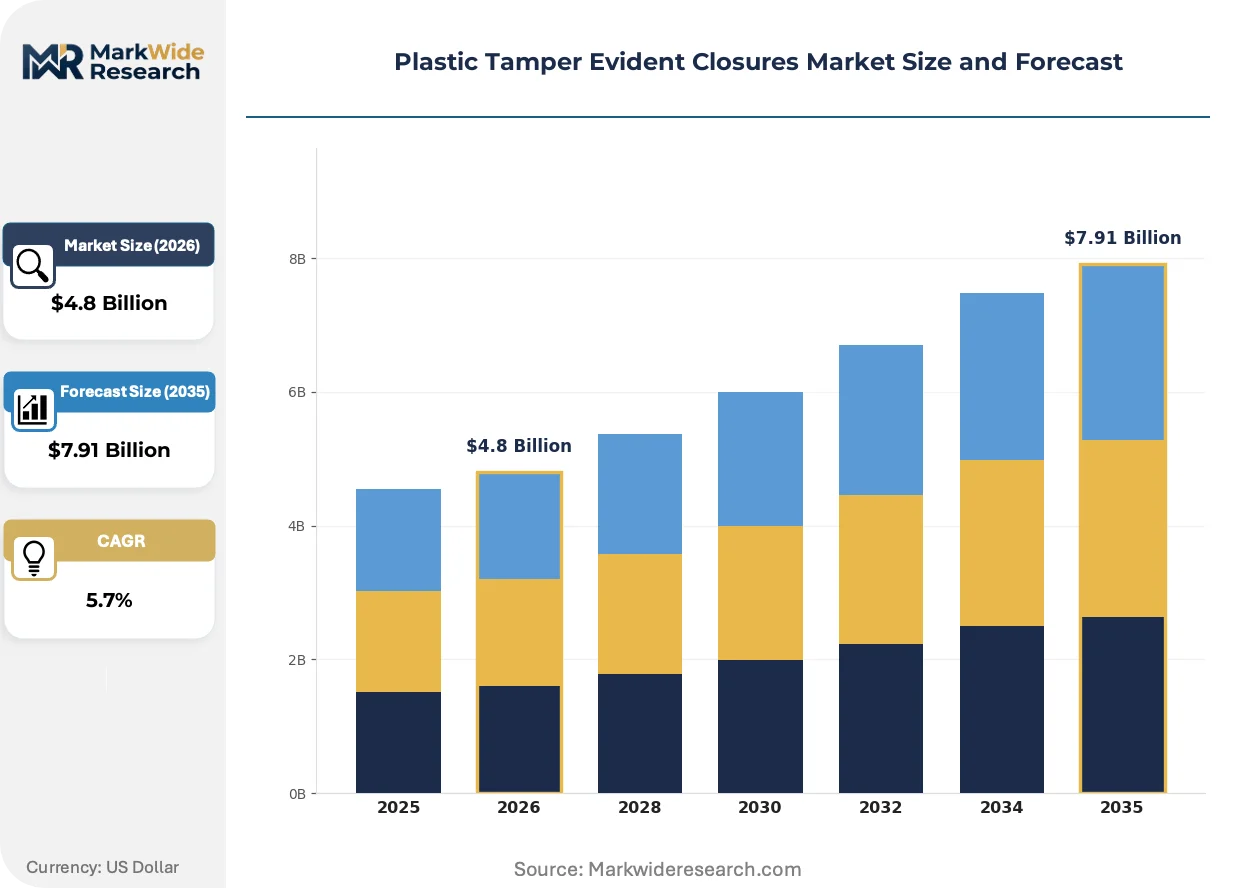
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Screw Caps, Snap-On Caps, Flip-Top Caps, Child-Resistant Caps Material: Polyethylene, Polypropylene, PVC, PET End User: Food Industry, Beverage Industry, Pharmaceutical Sector, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Berry Global, Amcor, Sealed Air, Silgan Holdings, AptarGroup, BERICAP, Guala Closures, Closure Systems International, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Tamper Evident Closures Market Evolving Landscape
Digital authentication technologies are embedding into mechanical closure platforms, while regulatory chemistry standards tighten material qualification protocols across pharmaceutical supply chains.
Multilayer oxygen-barrier structures are converging with tamper-evident band designs to protect oxidation-sensitive liquid formulations. Biologic drug manufacturers in Germany and Switzerland are specifying these hybrid closures for monoclonal antibody vials. The technology is converging with existing screw-cap platforms without requiring line changeovers, compressing adoption barriers for mid-tier generic suppliers.
REACH Article 33 disclosure requirements and RoHS substance restrictions are constraining plasticizer and additive chemistries in European pharmaceutical packaging. Converters must maintain validated raw material qualifications across shifting authorized substance lists. Small and mid-sized molders in Italy and Spain face disproportionate compliance costs relative to integrated multinationals with captive regulatory affairs capabilities.
Consolidated buying by national pharmacy chains and group purchasing organizations is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Regional distributors in the US and Germany are losing share to direct manufacturer relationships with closure converters. This pattern is most visible in the generic oral solid dosage segment where procurement teams prioritize landed cost over localized technical support.
Plastic Tamper Evident Closures Market Segmentation
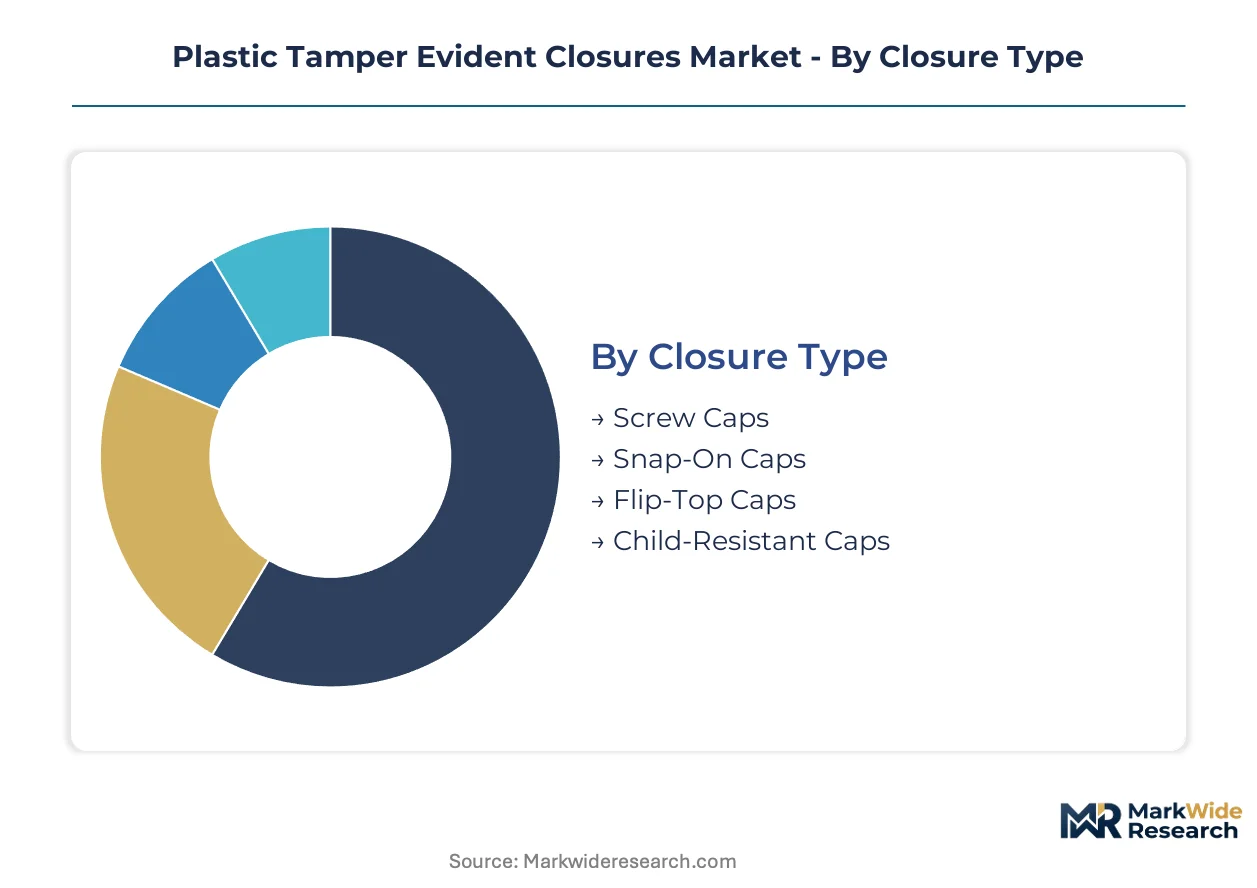
Segmentation in plastic tamper evident closures reveals how specification requirements diverge across regulatory environments and end-use risk profiles. Buyers prioritize torque consistency, chemical compatibility, or child-safety certification depending on whether they package biologics, carbonated beverages, or over-the-counter pharmaceuticals.
Closure Type:
Pharmaceutical packagers select closure formats based on resealability demands and compliance burdens rather than unit cost alone.
- Screw Caps:Threaded polypropylene or HDPE designs deliver precise torque retention for parenteral vials and oral solid dosage bottles. Demand concentrates in Germany's Rhine-Main contract packaging cluster, where FDA 21 CFR 211 compliance mandates uniform breakaway band performance across high-speed capping lines.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms incorporate patent-protected ratchet systems tested to ISO 8317 and US 16 CFR 1700. The dual-certification burden extends development timelines, but generic drug manufacturers in India and the United States absorb these costs to access retail pharmacy chains.
- Snap-On Caps:Compression-molded designs with audible engagement indicators serve single-serve beverage portions where resealability is secondary to tamper evidence.
- Flip-Top Caps:Living-hinge polypropylene constructions integrate tear bands for topical pharmaceutical and cosmetic applications requiring one-handed dispensing.
Screw caps lead volumes today; child-resistant caps are gaining share fastest.
Material:
Resin selection balances chemical resistance against propylene monomer price volatility and REACH-authorized substance constraints.
- Polypropylene:Isotactic homopolymer and random copolymer grades dominate pharmaceutical specifications for their dimensional stability across freeze-thaw cycles and compatibility with living-hinge geometries. Swissmedic and EMA extractables protocols favor validated PP grades with restricted additive packages.
- Polyethylene:HDPE retains cost advantages in high-volume food segments where oxygen barrier demands are modest and torque specifications less stringent. Indian converters serving domestic edible oil and condiment markets specify PE to offset resin price swings.
- PVC:Plasticized formulations persist in specific pharmaceutical applications requiring clarity and gasket compatibility, though REACH Article 33 disclosure requirements constrain plasticizer selection.
- PET:Crystalline and amorphous grades serve cosmetic and premium beverage closures where transparency and surface finish differentiate shelf presence.
Polypropylene commands the premium tier; polyethylene sustains volume leadership in cost-sensitive segments.
End User:
Regulatory intensity and patient risk profiles create divergent specification hierarchies across downstream industries.
- Pharmaceutical Sector:Biologics manufacturers specify multilayer oxygen-barrier closures with validated seal integrity across cold-chain excursions. CDSCO alignment with ICH guidelines and expanding US FDA-approved manufacturing sites in India are broadening export-compliant sourcing demand.
- Food Industry:High-density polyethylene screw caps for condiments and sauces prioritize propylene monomer cost hedging over barrier performance.
- Beverage Industry:Carbonated soft drink and bottled water applications favor lightweight snap-on designs with tear-band tamper evidence.
- Cosmetics:Flip-top and disc-top closures with metallic overcaps serve premium skincare where perceived quality justifies unit cost premiums.
Pharmaceutical procurement expands most quickly; food industry volumes anchor current consumption.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to molding capacity.
- Wholesale Distributors:Regional inventory aggregation serves mid-tier pharmaceutical and food packagers without direct converter relationships. German distributors around Frankfurt maintain stocked closure programs for Rhine-Main contract packagers requiring rapid qualification turnaround.
- Online Retail:E-procurement platforms capture small-batch cosmetic and specialty pharmaceutical orders where specification complexity is low and delivery speed outweighs technical consultation.
- Supermarkets:Private-label food and beverage producers source through retail-linked procurement consortia with consolidated volume commitments.
- Specialty Stores:Regional packaging equipment dealers bundle closure supply with line integration services for legacy retrofit projects.
Wholesale distributors retain volume dominance; online retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting pharmaceutical closure sourcing toward jurisdictions with streamlined compliance pathways and concentrated contract manufacturing infrastructure. Production migration tracks the divergence between FDA 21 CFR 211 enforcement intensity and emerging-market qualification acceleration.
United States
Generic drug manufacturers and mail-order pharmacies drive specification upgrades for child-resistant and senior-friendly closure designs. FDA 21 CFR 211 mandates tamper-evident features across all over-the-counter human drug products. New Jersey and Pennsylvania host dense clusters of pharmaceutical packaging operations serving branded and generic drug makers with validated closure supply chains.
Germany
Biologics cold-chain expansion and export-oriented pharmaceutical manufacturing sustain premium closure procurement. EU MDR extends tamper-evident mandates to medical device kits and combination products. The Rhine-Main region around Frankfurt concentrates contract packaging services and third-party logistics facilities generating sustained demand for high-performance screw-cap systems.
India
US FDA-approved manufacturing site expansion and CDSCO alignment with ICH guidelines are broadening export-compliant closure sourcing. The national pharmaceutical regulator enforces packaging standards converging with international pharmacopeial requirements. Gujarat and Maharashtra host dense networks of generic drug manufacturers and packaging converters serving North American and European export markets.
Switzerland
Monoclonal antibody and protein therapy manufacturers specify multilayer oxygen-barrier closures with validated seal integrity. Swissmedic maintains stringent extractables and leachables protocols favoring pre-validated polypropylene grades. The Basel region anchors biologics manufacturing clusters demanding closure systems compatible with freeze-thaw logistics.
China
Domestic pharmaceutical packaging upgrade cycles and NMPA harmonization with ICH Q3D guidelines are elevating closure quality specifications. The national pharmaceutical regulator enforces container closure integrity standards for sterile drug products. The Yangtze River Delta concentrates pharmaceutical manufacturing and packaging equipment suppliers serving both domestic and export markets.
Plastic Tamper Evident Closures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin-to-closure operators commanding pharmaceutical tier pricing while regional molders compete on food and beverage volumes. The vendor base concentrates around three strategic archetypes: multinational converters with captive regulatory affairs capabilities, mid-tier specialists with certified testing laboratories, and regional molders serving cost-sensitive commodity segments. Consolidation pressures favor backward integration into resin compounding and downstream pre-validation services. Geographic expansion into Indian and Southeast Asian pharmaceutical corridors represents the dominant competitive vector alongside smart closure technology licensing partnerships.
Among North American integrated packaging conglomerates, Berry Global and Amcor exemplify the multinational converter archetype with pharmaceutical corridor presence. Silgan Holdings anchors the dedicated manufacturing scale segment serving branded and generic drug makers. These three entities occupy positions spanning resin formulation through finished closure qualification, representing the vertical integration pattern that compliance-intensive pharmaceutical procurement increasingly favors.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Sealed Air |
| Silgan Holdings |
| AptarGroup |
| BERICAP |
| Guala Closures |
| Closure Systems International |
| CCL Industries |
| Others |
Value Network & Pricing Analysis
Backward integration from resin formulation through finished closure qualification anchors supply positions for pharmaceutical-tier suppliers while compressing margin capture for converters lacking captive compounding capacity. FDA 21 CFR 211 compliance mandates and REACH-authorized substance constraints reward integrated operators with pricing power over mid-tier molders dependent on spot resin markets.
Pricing Analysis
Distributor margin compression dominates channel economics as consolidated pharmacy chains and group purchasing organizations consolidate procurement leverage. Three-tier pricing structure across premium, standard, and economy levels separates ISO 8317-certified child-resistant systems from basic screw-cap configurations, with biologics-grade multilayer oxygen-barrier closures commanding the widest spreads. Pricing pressure stems from polypropylene resin volatility tied to propylene monomer supply disruptions, squeezing converters without long-term feedstock contracts. Generic oral solid dosage manufacturers exhibit highest price sensitivity, while biologics packagers prioritize seal integrity validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with propylene monomer feedstock concentrated in Gulf Coast petrochemical corridors and Middle Eastern integrated complexes. Manufacturing capacity clusters in Germany, India, and the United States, with the Rhine-Main region anchoring European pharmaceutical closure supply. Raw material dependencies encompass isotactic polypropylene homopolymer, random copolymer grades, and validated additive packages constrained by REACH Article 33 disclosure requirements. Regulatory restriction risk intensifies as Swissmedic and EMA extractables protocols tighten authorized substance lists. Distribution runs through direct manufacturer relationships with closure converters, displacing regional distributors in generic drug procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic tamper evident closures market functions as a stable compounder, with regulatory mandates for patient safety creating durable demand visibility across pharmaceutical packaging procurement cycles.
For Market Incumbents: Deepen captive regulatory affairs capabilities to compress qualification timelines for biologics manufacturers facing serialization mandates. Expand certified testing laboratory capacity to capture ISO 8317 and US 16 CFR 1700 dual-certification demand from Indian generic exporters. Aluminum closure substitution in premium beverage segments and polypropylene resin volatility represent persistent margin threats requiring backward integration into resin compounding to defend cost positions. For New Entrants and Emerging Players: Capture white-space in smart closure convergence by licensing NFC tag integration capabilities for high-value generic authentication. Target Indian pharmaceutical export corridors where CDSCO alignment with ICH guidelines is accelerating US FDA-approved site expansion. Pursue direct-to-patient pharmacy channel partnerships requiring drop-shock resilient designs with intuitive opening mechanics for elderly populations. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier specialists with certified testing laboratories because dual-compliance testing burdens are extending product development cycles beyond standalone capital capacity. Five-to-ten year viability hinges on regulatory chemistry standards tightening material qualification protocols. Monitor extractables testing talent scarcity as an inflection signal for acquisition timing, as qualified analytical chemists capable of USP leachables studies command premium compensation and extend staffing timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Closure Technology Licensing | NFC tag integration enables authentication for high-value generics combating counterfeiting. |
| Backward Integration into Resin Compounding | Captive polypropylene formulation insulates margins from propylene monomer price volatility. |
| Certified Testing Laboratory Expansion | ISO 8317 and US 16 CFR 1700 dual-certification capacity captures generic drug manufacturer demand. |
| Direct-to-Patient Channel Partnership | Mail-order pharmacy fulfillment requires senior-friendly closure designs with validated drop-shock resilience. |
| Indian Export Corridor Manufacturing Footprint | CDSCO alignment with ICH guidelines broadens US FDA-compliant closure sourcing from Gujarat and Maharashtra. |
Research Methodology
Direct dialogue with pharmaceutical packaging engineers, regulatory affairs directors at closure converters, procurement leads at generic drug manufacturers, and contract packaging operations managers in the Rhine-Main region grounded qualitative findings. Secondary validation drew from FDA 21 CFR 211 enforcement records, EMA submission databases, Swissmedic extractables protocols, and REACH-authorized substance lists maintained by ECHA. Bottom-up and top-down triangulation reconciled unit-level procurement patterns with aggregate resin consumption data.
Segment-level projections across closure type, material grade, end-use industry, and regional regulatory cluster fed into the analytical framework over the projection horizon. CAGRs were derived from modeled unit demand trajectories and value-per-unit assumptions indexed to resin price scenarios. Forecast inputs incorporated pharmaceutical serialization mandate timelines, biologics cold-chain expansion rates, and CDSCO regulatory harmonization progress.
Polypropylene resin price volatility, REACH substance list revisions, and aluminum closure substitution rates in premium beverage segments are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Fez Caps Market
Caps and Closures
Overcaps Market
Caps and Closures
Metal Closures Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
North America Metal Caps and Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Crimp-On Spouts Market
Caps and Closures
End Cap Market
Caps and Closures
Dual Flap Dispensing Closure Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Flat Valve Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Russia Plastic Caps and Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market