
 Low Density Polyethylene (LDPE) Packaging Market | 2026-2036
Low Density Polyethylene (LDPE) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Low Density Polyethylene (LDPE) Packaging Market Foresight
The capital-intensity divergence between integrated resin-to-film operators and merchant converters is bifurcating competitive returns in LDPE packaging. Amcor plc leverages captive polymer sourcing and blown film capacity across multiple continents to sustain margin stability. Berry Global Inc. anchors its position through injection molding scale for rigid bottles in North American personal care supply chains. Constantia Flexibles specializes in high-barrier extrusion coating formats for European food exporters, occupying a defensible premium niche.
Low Density Polyethylene (LDPE) Packaging denotes polymer-based containment and protection systems fabricated from branched polyethylene with density ranging from 0.910 to 0.940 g/cm³, typically processed via blown film extrusion or injection molding to deliver flexibility, moisture resistance, and seal integrity for perishable and consumer goods. Flexible packaging leads volume consumption across food and beverage distribution networks, while films above 100 microns command superior unit economics in industrial stretch and shrink applications. Blown film dominates form-level output due to its compatibility with high-speed packaging lines, though extrusion coating is gaining traction in multi-layer barrier structures for extended shelf-life dairy and meat products.
The European Chemicals Agency enforces REACH compliance for polymer additives and residual monomer thresholds, while the FDA regulates LDPE food-contact substances under 21 CFR 177.1520 in the United States, collectively elevating testing burdens and reformulation costs for cross-border suppliers. China's SAMR and GB standards for food packaging plastics impose additional migration limits and labeling requirements that shape export-oriented production specifications. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms deliver superior risk-adjusted returns.
Market Dynamics
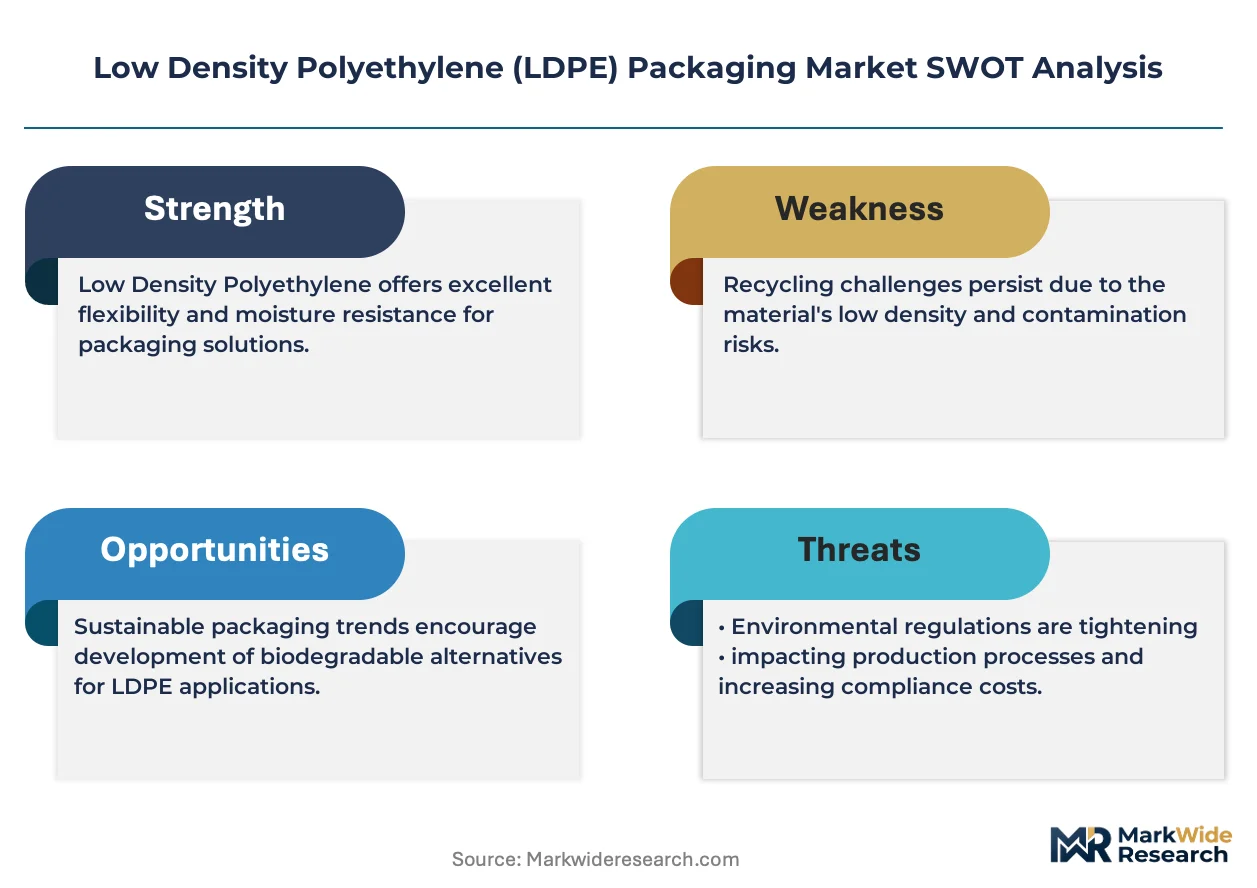
The EU Single-Use Plastics Directive is forcing reformulation across European food-contact LDPE grades while resin-to-film integration concentrates margin capture among captive polymer producers.
Growth Catalysts
- Modified-atmosphere packaging:Food processors in Vietnam and Indonesia are scaling LDPE film purchases for protein and fresh produce shelf-life extension. Blown film lines are running at higher speeds to match this specification demand.
- Extended producer responsibility frameworks:North American state-level EPR mandates are accelerating recyclate-content specifications for flexible packaging. Brand owners are locking in multi-year supply agreements with certified circular resin suppliers.
- Blown film extrusion advances:Gauge control automation is reducing material giveaway in high-volume industrial stretch film. Converters in manufacturing clusters are capturing unit cost advantages against legacy equipment operators.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price swings compress margin predictability for non-integrated converters. Merchant film producers lack pass-through mechanisms with shorter contract tenors.
- Mechanical recycling contamination thresholds:Multi-layer barrier structures incorporating EVOH or nylon layers face technical limitations in conventional reprocessing streams. Sorting infrastructure gaps in municipal waste systems compound this constraint.
- Paper and molded fiber substitution:E-commerce shippers are piloting corrugated alternatives to LDPE mailer films for consumer-facing unboxing experiences. Regulatory nudges in select European markets accelerate this displacement threat.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments are creating feedstock pathways for food-grade LDPE with virgin-equivalent properties. Regulatory tailwinds in the EU Green Deal framework favor this technology convergence.
- Healthcare sterilization packaging:Gamma-stable LDPE formulations for medical device pouches represent an underpenetrated application with premium pricing power. Sterilization validation protocols create incumbent stickiness for early movers.
- Direct-to-film digital printing:Water-based ink systems are eliminating lamination steps in short-run flexible packaging. Brand owners in North American craft food segments are adopting this for SKU proliferation without plate costs.
Industry Challenges
- Extrusion coating technician scarcity:Multi-layer barrier line operators require specialized calibration skills for adhesive tie-layer optimization. Vocational pipeline gaps in European manufacturing regions extend onboarding timelines.
- Migration testing backlog:FDA and ECHA food-contact notification queues are stretching certification timelines for novel additive packages. Reformulation iterations face capital lock-up during regulatory review windows.
- Legacy ERP integration:Batch-level traceability requirements for EPR compliance are clashing with decades-old manufacturing execution systems. Custom middleware development is consuming IT resources at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Density Polyethylene (LDPE) Packaging Market |
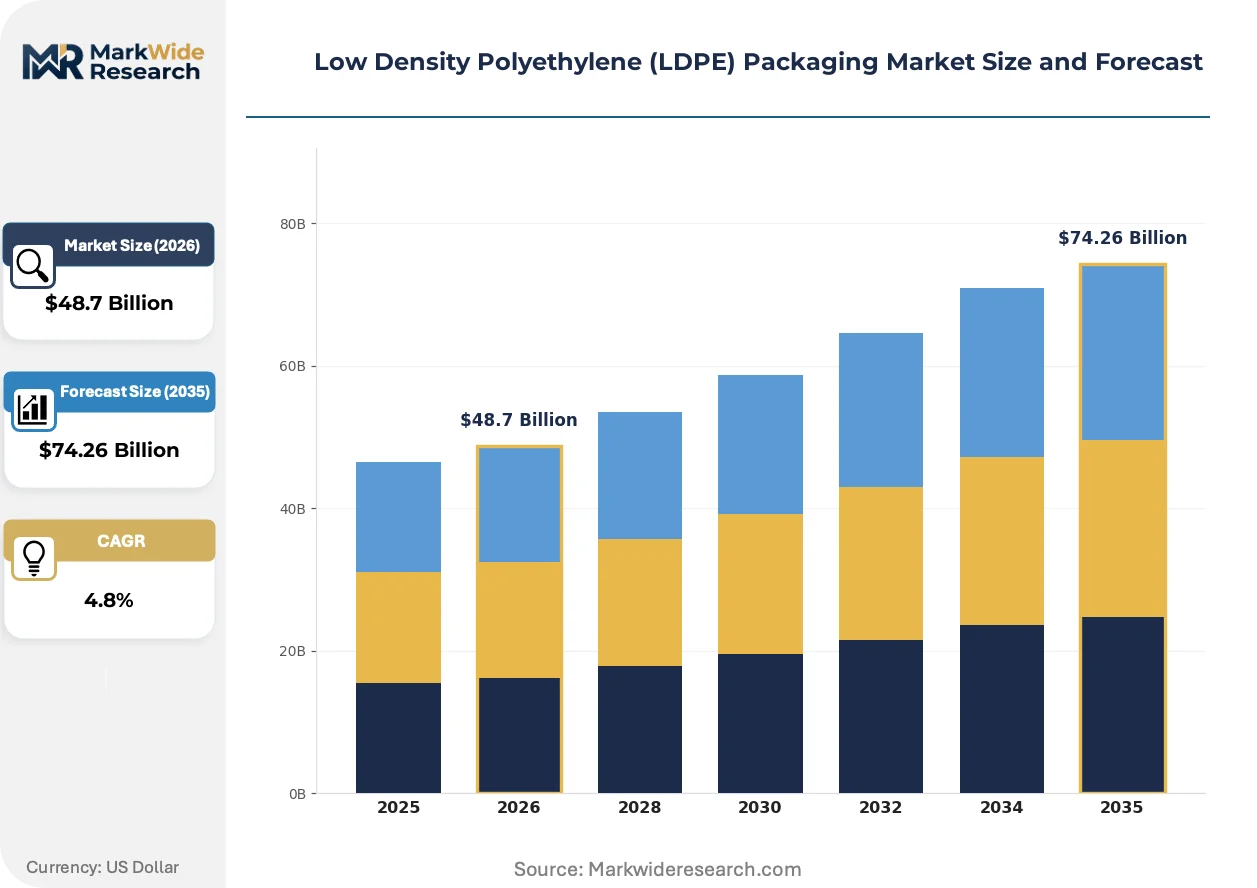
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Bottles, Plastic Sheets, Films End Use Industry: Food & Beverage, Personal Care, Healthcare, Consumer Goods Form: Blown Film, Injection Molding, Extrusion Coating, Blow Molding Thickness: Below 30 Microns, 30-50 Microns, 50-100 Microns, Above 100 Microns |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air, Constantia Flexibles, Mondi, Alpla, Coveris, Sonoco, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Density Polyethylene (LDPE) Packaging Market Shifts & Advancements
Active and intelligent packaging functionalities are converging with LDPE film substrates, reshaping competitive differentiation beyond commodity barrier performance.
Mono-material barrier films incorporating metallized or ceramic oxide coatings are fragmenting the conventional multi-layer laminate market. European meat and dairy exporters are adopting these structures to meet recyclability claims without sacrificing oxygen transmission rates. The shift is compressing demand for ethylene vinyl alcohol copolymer tie-layers in certain application bands.
REACH enforcement on polymer additive migration limits is elevating testing burdens for cross-border suppliers. Reformulation costs are concentrating among smaller merchant converters lacking in-house toxicology resources. Food-contact grade LDPE shipments into the European Union are increasingly contingent on third-party laboratory certification.
Brand owner sustainability scorecards are reshaping supplier selection criteria in North American retail channels. Film converters are responding with mass-balance certified resins and blockchain-tracked recyclate claims. This behavioral shift is most visible in private-label flexible packaging procurement for grocery and convenience store distribution networks.
Low Density Polyethylene (LDPE) Packaging Market Segmentation
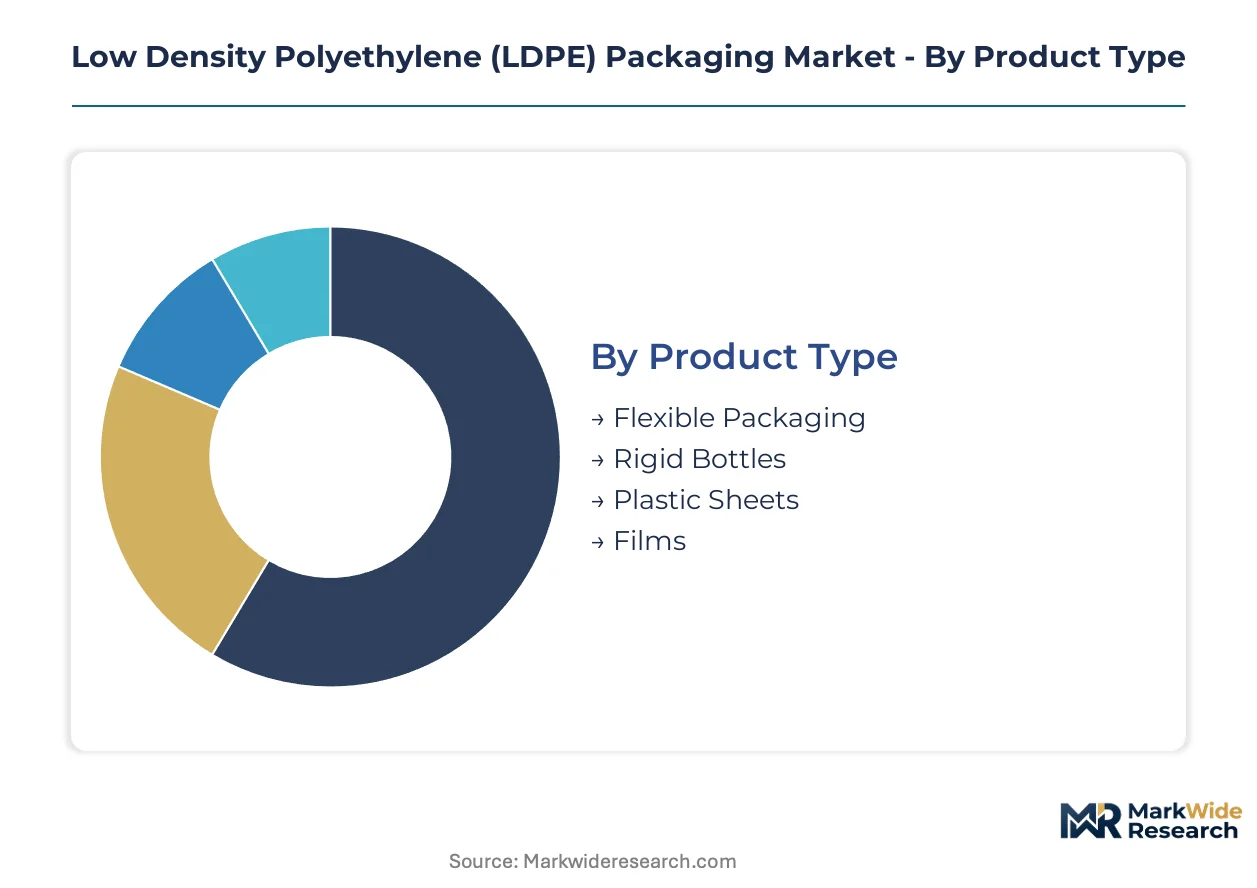
Segmentation in LDPE packaging reveals divergent vulnerability to material substitution and regulatory pressure. Product thickness and end-use application determine exposure to paper and molded fiber alternatives, while form-level processing technology dictates recyclability compliance costs.
Product Type:
Flexible packaging faces the most acute substitution pressure from fiber-based alternatives in e-commerce and retail channels.
- Flexible Packaging:Blown film and extrusion-coated structures dominate food-contact applications. Modified-atmosphere specifications for protein and produce shelf-life extension are driving specification upgrades in Vietnam and Indonesian export facilities.
- Films:Stretch and shrink formats above 100 microns command superior unit economics in palletization and unitization. Gauge control automation is reducing material giveaway for industrial converters running high-speed lines.
- Rigid Bottles:Injection-molded containers serve personal care and household chemical distribution. EPR compliance requirements are elevating post-consumer recyclate mandates for North American supply chains.
- Plastic Sheets:Thermoformed trays and lids for food service applications face competitive displacement from molded pulp in select European quick-service restaurant procurement.
Flexible packaging anchors the volume base while films gain share at the steepest rate.
End Use Industry:
Customer procurement patterns stratify across sustainability maturity tiers, with food and beverage brand owners leading circularity investment.
- Food & Beverage:Processors are locking in multi-year supply agreements for certified circular resin. Barrier specifications for dairy and meat shelf-life extension favor high-performance blown film and extrusion-coated structures.
- Personal Care:Rigid bottle demand concentrates in North American manufacturing clusters. Injection molding scale anchors competitive positioning for mid-volume SKU portfolios.
- Healthcare:Gamma-stable LDPE formulations for medical device sterilization pouches represent premium-priced underpenetrated demand. Validation protocols create incumbent stickiness for qualified suppliers.
- Consumer Goods:E-commerce mailer films face pilot displacement by corrugated alternatives for unboxing experience differentiation. Regulatory nudges in select EU member states accelerate this threat.
Food and beverage procurement sets the sustainability benchmark while healthcare applications expand most quickly.
Form:
Processing technology selection determines capital intensity and margin capture potential across the value chain.
- Blown Film:Dominates flexible packaging output through compatibility with high-speed form-fill-seal lines. Resin-to-film integration concentrates margin stability among captive polymer producers.
- Extrusion Coating:Multi-layer barrier structures for extended shelf-life dairy and meat are gaining specification share. Adhesive tie-layer calibration demands specialized technician skills that constrain European capacity expansion.
- Injection Molding:Rigid container production for personal care and household chemicals runs on shorter contract tenors. Naphtha and ethane price volatility compresses predictability for non-integrated operators.
- Blow Molding:Bottles and hollow containers for liquid packaging face EPR-driven recyclate content thresholds. Legacy equipment retrofit requirements are extending payback periods at mid-scale converters.
Blown film retains the largest installed base while extrusion coating climbs the fastest.
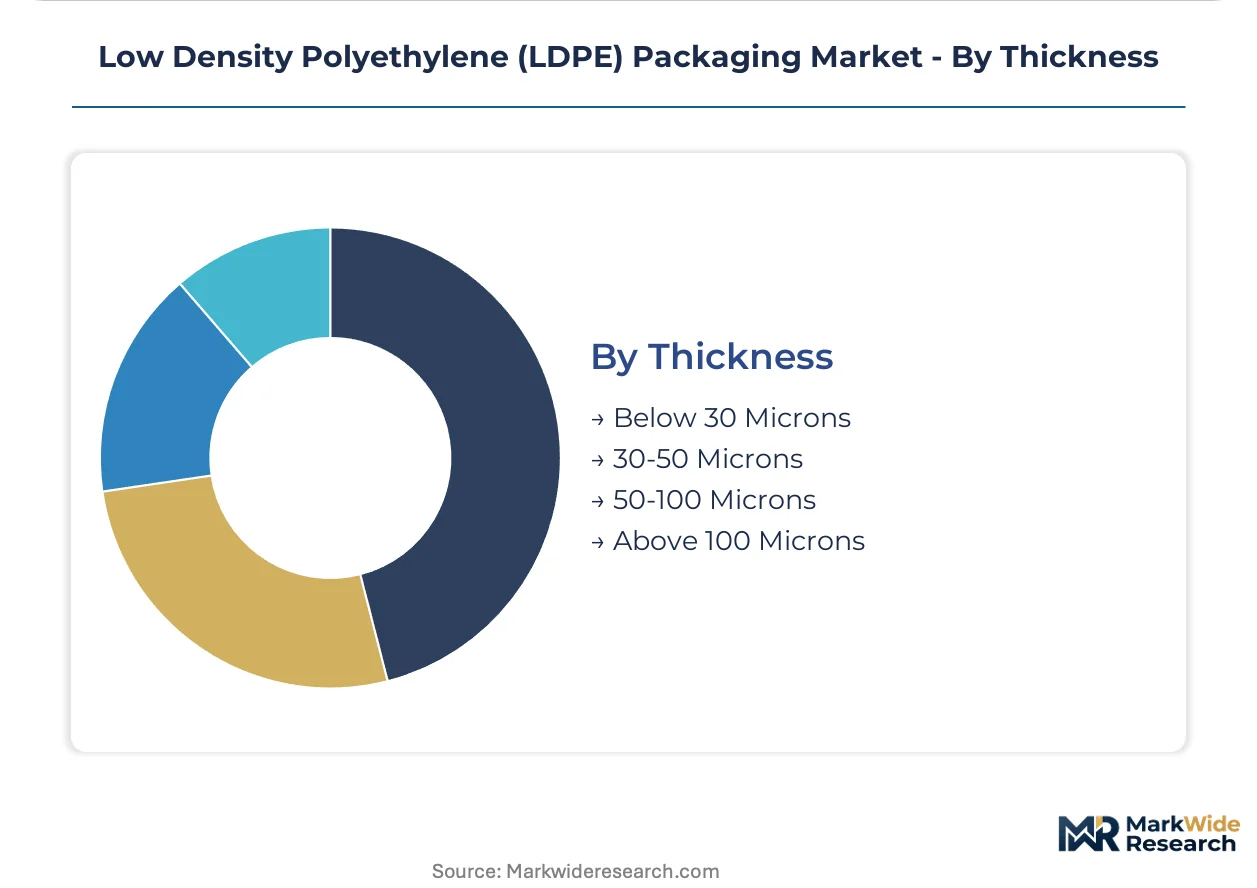
Thickness:
Specification tiering aligns with performance requirements and unit economics differentiation.
- Above 100 Microns:Industrial stretch and shrink films for pallet unitization command premium pricing through gauge consistency and mechanical strength. Automation investments in gauge control are widening cost advantages for leading converters.
- 50-100 Microns:Mid-gauge films balance barrier performance with material efficiency for consumer goods packaging. This band faces the most intense price competition from regional merchant producers.
- 30-50 Microns:Lightweight food-contact applications are migrating toward mono-material structures to satisfy recyclability claims. Metallized and ceramic oxide coatings are displacing conventional multi-layer laminates in certain meat and dairy exports.
- Below 30 Microns:Ultra-thin formats for single-use retail bags face regulatory volume restrictions under EU Single-Use Plastics Directive enforcement. Substitution by paper and reusable alternatives is most advanced in this tier.
Above 100 microns specifications anchor profitability while below 30 microns contracts most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam and Indonesia exhibit the highest price elasticity for LDPE film specifications, while European food exporters absorb premium pricing for REACH-compliant barrier grades. This demand-elasticity contrast shapes regional investment priorities across the value chain.
United States
Food processors in California and the Midwest are scaling modified-atmosphere packaging specifications for protein distribution. FDA regulations under 21 CFR 177.1520 mandate residual monomer thresholds that elevate testing burdens for imported film. The Southeast manufacturing corridor, particularly Georgia and the Carolinas, hosts expanding blown film capacity serving private-label retail channels.
Germany
Extended producer responsibility frameworks under the EU Single-Use Plastics Directive are forcing reformulation of food-contact LDPE grades. ECHA enforcement of REACH additive migration limits concentrates compliance costs among smaller merchant converters. The North Rhine-Westphalia industrial cluster anchors extrusion coating capacity for high-barrier dairy and meat exports.
China
SAMR and GB standards for food packaging plastics impose migration limits that shape export-oriented production specifications. Dual carbon goals are accelerating pyrolysis investments for chemically recycled feedstock. The Yangtze River Delta manufacturing belt, centered on Shanghai and Jiangsu province, concentrates flexible film output for Southeast Asian re-export markets.
Vietnam
Export-oriented processors demonstrate acute price sensitivity for blown film specifications serving Japanese and South Korean food brand owners. The country's central bank maintains currency stability mechanisms that reduce import feedstock volatility for non-integrated converters. Manufacturing parks in Binh Duong and Dong Nai provinces are attracting resin-to-film investments from regional polymer producers.
Indonesia
Fresh produce shelf-life extension specifications are driving LDPE film demand from domestic and export food processors. National regulations on plastic waste management are beginning to mirror EPR structures in developed markets. The Java industrial corridor, particularly around Jakarta and Surabaya, hosts the densest concentration of high-speed blown film lines in Southeast Asia.
Low Density Polyethylene (LDPE) Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LDPE packaging value chain. Integrated resin-to-film operators capture margin stability through captive polymer sourcing, while merchant converters compete on line speed and gauge control automation. Three archetypes dominate: multinational packaging conglomerates with continental-scale blown film networks, regional specialists in high-barrier extrusion coating, and mid-scale injection molders serving personal care supply chains. Consolidation through backward integration and geographic expansion into Vietnamese and Indonesian manufacturing clusters represent the dominant competitive moves.
Within the multinational conglomerate tier, Amcor plc exemplifies resin-to-film integration across multiple continents, while Berry Global Inc. anchors a position through injection molding scale. Constantia Flexibles occupies a defensible premium niche in high-barrier extrusion coating formats for European food exporters. These three entities represent distinct strategic archetypes: captive supply chain control, rigid container manufacturing scale, and specialized barrier technology respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air |
| Constantia Flexibles |
| Mondi |
| Alpla |
| Coveris |
| Sonoco |
| Huhtamaki Oyj |
| Others |
Supply & Pricing Matrix
REACH compliance certification gates both supplier qualification and price differentiation simultaneously, with ECHA-mandated additive migration testing creating tiered entry barriers that separate certified premium-grade LDPE film producers from merchant converters absorbing third-party laboratory costs. Food-contact grade specifications for European dairy and meat exports command measurable premiums over industrial stretch film tiers, while non-integrated converters in Southeast Asian manufacturing clusters compete primarily on gauge control automation and line speed economics.
Pricing Analysis
After-sales revenue from technical service contracts and calibration support drives lifetime value for extrusion coating line operators facing EPR compliance retrofit demands. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and barrier performance specification. Cost compression in below-30-micron retail bag tiers is intensifying because EU Single-Use Plastics Directive volume restrictions accelerate paper substitution. Export-oriented processors in Vietnam exhibit the highest price sensitivity, while European food exporters absorb premium pricing for REACH-compliant barrier grades with minimal elasticity.
Supply Chain Analysis
China and South Korea anchor virgin resin production for Asia-Pacific flexible film manufacturing, with Saudi Arabia and the United States feeding naphtha and ethane derivatives into global polymer supply. LDPE packaging draws from ethylene feedstock, calcium carbonate masterbatch additives, and metallized or ceramic oxide coating substrates. Single-source vulnerability concentrates in specialized adhesive tie-layer chemistries for multi-layer barrier structures. Distribution runs through regional converter networks serving form-fill-seal packaging lines at food processors and brand owner co-manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LDPE packaging sits at a high-growth inflection as chemical recycling scale-up converges with EU Green Deal regulatory tailwinds, creating virgin-equivalent food-grade feedstock pathways that reshape competitive economics across the value chain.
For Market Incumbents: Fortify margin stability through backward integration into captive resin production or blown film capacity expansion in Vietnamese and Indonesian manufacturing clusters. EPR compliance mandates and mechanical recycling contamination thresholds threaten merchant converter economics; certification investment in mass-balance tracking systems anchors supplier stickiness with sustainability-scorecard-driven brand owners. For New Entrants and Emerging Players: Lead with gamma-stable LDPE formulations for healthcare sterilization packaging, the most penetrable premium tier given validation protocol stickiness and incumbent scarcity in medical device pouches. Direct-to-film digital printing capabilities for North American craft food segments offer a defensible go-to-market angle through water-based ink elimination of lamination steps. For Investors and Strategic Acquirers: EU Single-Use Plastics Directive enforcement reshapes the acquisition landscape toward resin-to-film integrated operators with REACH-certified food-contact grade portfolios. Long-term viability over the next decade rests on feedstock flexibility between virgin and chemically recycled inputs. The signal to watch is pyrolysis capacity commissioning timelines and offtake agreement pricing spreads against naphtha-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene sourcing insulates margin stability against naphtha volatility for European converters. |
| Chemical Recycling Scale-Up | Pyrolysis investments under EU Green Deal frameworks unlock food-grade LDPE with virgin-equivalent properties. |
| Healthcare Sterilization Validation | Gamma-stable formulation protocols create incumbent stickiness in medical device pouch supply chains. |
| Direct-to-Film Digital Printing Adoption | Water-based ink systems eliminate lamination costs for short-run craft food packaging in North America. |
| EPR Compliance System Integration | Blockchain-tracked recyclate claims satisfy brand owner sustainability scorecards in retail procurement. |
Research Methodology
Cross-validation between primary interviews with blown film plant managers, extrusion coating technical directors, and food processor procurement leads anchors the qualitative findings against secondary validation from customs trade data, SEC filings of integrated resin producers, and ECHA REACH notification databases. Bottom-up capacity assessments at manufacturing clusters in Germany, Vietnam, and Indonesia triangulate against top-down demand modeling from food and beverage export volumes.
Sensitivity analysis across feedstock price scenarios and regulatory enforcement timelines shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product thickness tiers, form-level processing technology, end-use industry verticals, and regional production hub clusters. CAGRs derive from ethylene derivative demand elasticities and packaging machinery installation rates, with chemical recycling capacity buildouts and EPR mandate phase-ins as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained naphtha-to-ethylene cost spreads or accelerated paper substitution in e-commerce channels would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and pyrolysis yield rate maturation. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and Southeast Asian central bank currency stability mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market