
 Cover Caps Market | 2026-2036
Cover Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Cover Caps Market Analysis
Multi-source procurement for precision-molded closures is pivoting toward regionalized supply networks as OEMs reduce trans-Pacific dependency. Closure Systems International leverages captive resin compounding to sustain margin stability across volatile feedstock cycles. Silgan Holdings anchors North American beverage and industrial packaging through integrated metal forming and plastic injection operations. Amcor PLC competes on barrier-engineered composite structures for pharmaceutical and food-grade applications.
Cover caps are mechanical sealing devices manufactured through injection molding, compression forming, or metal stamping, designed to protect threads, ports, and openings from contamination, corrosion, or unauthorized access during transit, storage, or end-use assembly. Polypropylene and polyethylene formulations dominate snap-on and screw-on variants due to chemical resistance and recyclability, while aluminum and steel persist in high-temperature automotive and aerospace environments. Plastic material segments lead volume shipments across automotive underhood and electronics connector applications, where push-fit configurations are displacing threaded alternatives to reduce assembly time. Screw-on caps retain premium positioning in medical and pharmaceutical packaging, where tamper-evidence and hermetic integrity command higher unit economics.
FDA 21 CFR Part 177 governs indirect food-contact polymers in US-manufactured caps, while REACH and EU MDR constrain substance migration limits for medical-grade closures sold into European healthcare systems. China's GB standards for plastic food-contact materials, enforced by SAMR, create parallel compliance pathways for exporters serving domestic processors. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling quotas, as these mechanisms will determine which material platforms and geographic production footprints retain competitive viability.
Market Dynamics
Lightweight polymer formulations are displacing metal stampings across automotive underhood applications as OEMs pursue gram-level weight reduction targets for electric vehicle range optimization.
Growth Catalysts
- EU Single-Use Plastics Directive:Accelerates material transitions toward recyclable and bio-based alternatives, compelling compounders to certify post-consumer recycled content grades for food-contact closures.
- East Asian electronics corridors:Demand concentrates around Shenzhen and Seoul manufacturing clusters where push-fit connector caps reduce assembly time in smartphone and semiconductor packaging.
- Injection molding automation:Servo-electric presses with in-mold labeling capability cut cycle times for tamper-evident pharmaceutical closures, expanding unit economics for sterile barrier applications.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in the US Gulf Coast and Northwest Europe compress margin stability for polypropylene compounders serving high-volume snap-on cap contracts.
- Automotive supply concentration:Tier-1 sealing system procurement in Germany and China depends on three dominant resin compounders, creating bottleneck risk during force majeure events.
- Aluminum substitution ceiling:High-temperature aerospace and powertrain applications resist polymer conversion above 150°C continuous service, preserving metal forming demand in narrow specification bands.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO's tightening traceability mandates for exported generics create demand for serialized tamper-evident closures with embedded holographic authentication features.
- Dual-carbon policy alignment:China's MEE enforcement of polymer recycling quotas positions domestic bio-based PLA cap producers for preferential procurement in state-owned beverage distribution channels.
- Direct-to-manufacturer platforms:Digital procurement portals bypass traditional distribution layers for standardized industrial thread protectors, compressing lead times for mid-volume automotive suppliers.
Industry Challenges
- Multi-jurisdiction compliance cadence:Simultaneous FDA 21 CFR Part 177 renewals, REACH SVHC list updates, and SAMR GB standard revisions strain regulatory affairs bandwidth at mid-sized molders.
- Hot-runner retrofit capex:Conversion from cold-runner to valve-gate systems for thin-wall pharmaceutical caps demands tooling investments that exceed depreciation schedules at family-owned processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cover Caps Market |
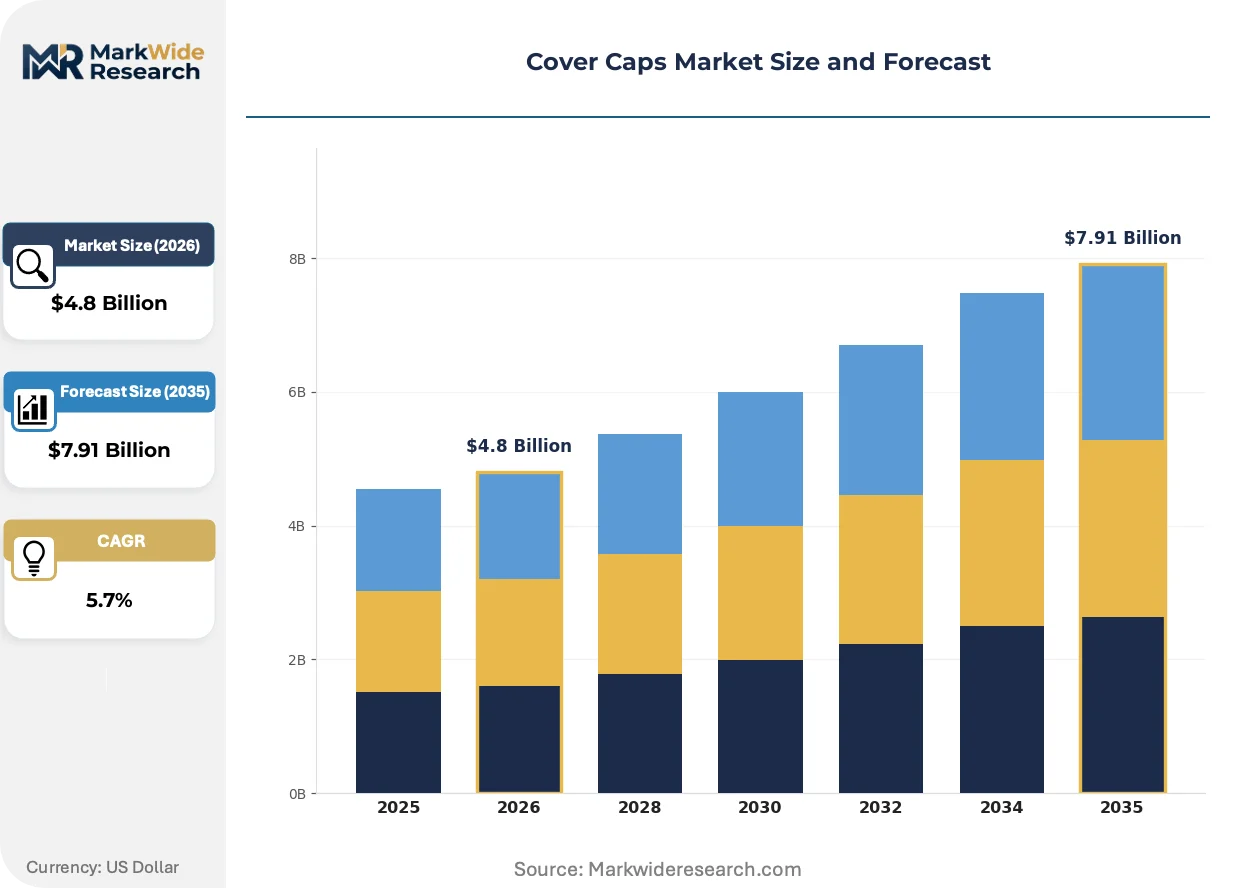
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snap-on Caps, Screw-on Caps, Push-fit Caps, Protective Caps Material: Plastic, Metal, Rubber, Composite Application: Automotive, Electronics, Packaging, Medical End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Closure Systems International, Inc., Silgan Holdings Inc., Aptar Group Inc., Nippon Closures Co., Ltd., Berry Global Group Inc., Amcor PLC, BERICAP GmbH & Co. KG, Caplugs LLC, Mold-Rite Plastics, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cover Caps Market Emerging Trajectories
Active material science and digital manufacturing integration are compressing development cycles for precision-molded closures while regulatory fragmentation forces parallel certification pathways.
Modular mold-base systems with quick-change cavity inserts are modularizing production economics for low-volume pharmaceutical SKUs. Contract manufacturers serving orphan drug packaging adopt these configurations to amortize tooling costs across shorter production runs. The technology is modularizing what were previously dedicated high-volume lines into flexible cells serving multiple drug-device combinations.
REACH Article 33 disclosure obligations for SVHC content above 0.1% w/w are forcing resin suppliers to requalify additive packages in medical-grade polypropylene. Compounders serving the EU healthcare market now submit full material composition datasets to notified bodies prior to MDR technical documentation review. Small molders lacking in-house regulatory chemistry expertise outsource substance screening to specialized laboratories, adding cost layers to each new colorant or processing aid introduction.
Automotive OEMs now specify lot-level resin traceability for underhood sealing components, replacing certificate-of-analysis spot checks with blockchain-anchored supply chain records. Tier-1 suppliers in Germany and Japan retrofit existing contracts with data-sharing clauses that extend upstream to monomer producers. This audit intensity is most visible in electric vehicle battery pack venting applications where thermal runaway liability drives material documentation requirements beyond incumbent automotive quality standards.
Cover Caps Market Segmentation
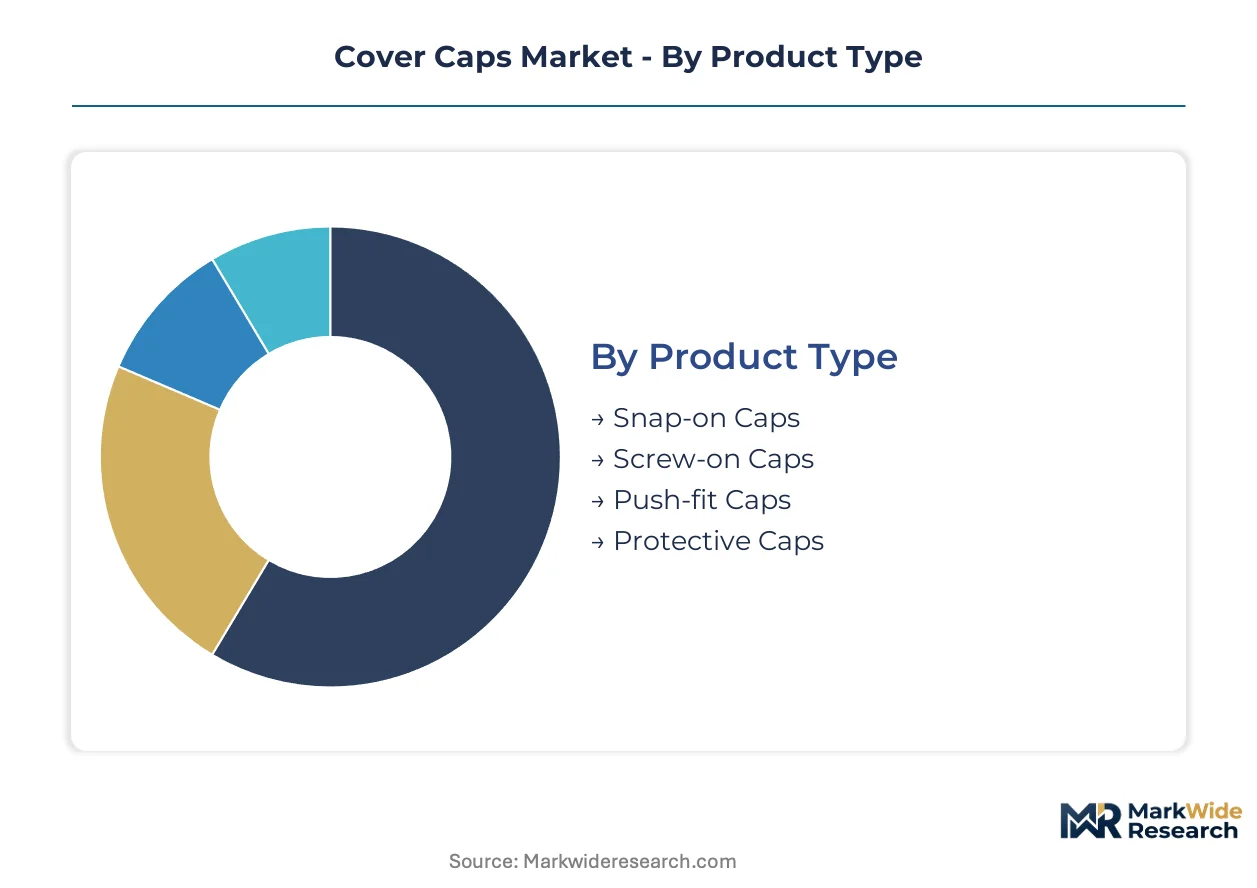
Cover caps serve divergent functional requirements across sealing, protection, and assembly applications. Segmentation by product mechanism, material platform, and end-use vertical reveals distinct procurement patterns and margin structures that suppliers must navigate.
Product Type:
Buyers select closure mechanisms based on assembly speed, reusability needs, and regulatory compliance burdens.
- Push-fit Caps:Friction-based retention eliminates threading operations, cutting assembly time by half in high-volume electronics manufacturing. Shenzhen and Seoul corridor demand concentrates here for smartphone connector protection where line speed determines contract awards.
- Screw-on Caps:Threaded engagement delivers hermetic integrity and tamper-evidence required for pharmaceutical and medical device packaging. FDA 21 CFR Part 177 compliance costs elevate unit economics, preserving premium positioning despite slower application speed.
- Snap-on Caps:Radial interference fits suit automotive underhood applications where tool-free installation reduces warranty labor exposure.
- Protective Caps:Oversized geometries shield ports and threads during transit and storage, dominating industrial machinery and aerospace logistics.
Volume sits with Push-fit Caps; growth tilts toward Screw-on Caps.
Material:
Material selection trades thermal performance against weight targets and recycling compliance obligations.
- Plastic:Polypropylene and polyethylene formulations dominate through injection molding economies, chemical resistance, and alignment with EU Single-Use Plastics Directive recyclability mandates. Automotive underhood applications drive gram-level weight reduction programs.
- Metal:Aluminum and steel stampings retain 150°C+ continuous service applications in powertrain and aerospace environments where polymer substitution hits thermal ceilings.
- Rubber:EPDM and silicone compounds seal against moisture ingress in outdoor electrical enclosures and marine hardware.
- Composite:Fiber-reinforced thermoplastics bridge stiffness and weight requirements in electric vehicle battery pack venting assemblies.
Plastic commands shipment volumes; composites gain share fastest in thermal management applications.
Application:
Application verticals impose distinct certification, traceability, and lot-size requirements on molders.
- Automotive:OEM lot-level resin traceability mandates now extend to blockchain-anchored supply chain records for underhood sealing components, exceeding incumbent quality documentation standards.
- Electronics:Miniaturization trends in semiconductor packaging favor push-fit configurations that protect fragile connector arrays during surface-mount assembly.
- Packaging:Beverage and food-grade closures face REACH SVHC disclosure obligations and SAMR GB standard compliance for exporters serving Chinese processors.
- Medical:MDR technical documentation review demands full material composition datasets, forcing compounders to requalify additive packages in medical-grade polypropylene.
Automotive generates the largest contract values; medical applications carry the steepest margin expansion trajectory.
End User:
Procurement scale and technical specification authority vary sharply across the value chain.
- Manufacturers:Tier-1 automotive and electronics assemblers specify resin grades and cavity configurations directly, leveraging volume concentration to extract tooling amortization concessions.
- Distributors:Industrial thread protector specialists aggregate mid-volume demand across maintenance, repair, and operations channels, compressing lead times through digital procurement portals.
- Retailers:Private-label beverage and consumer goods channels prioritize post-consumer recycled content certifications for shelf positioning advantages.
- Consumers:Aftermarket replacement demand concentrates in specialty automotive and hobbyist electronics segments with low volume but high margin tolerance.
Manufacturers anchor volume procurement; distributor digitalization is reshaping mid-tier sourcing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability along the US Gulf Coast anchors North American compounding capacity for polypropylene snap-on caps. German automotive OEMs source lightweight sealing solutions from resin compounders concentrated in the Rhine-Ruhr industrial corridor. East Asian electronics manufacturing clusters in Shenzhen and Seoul drive push-fit cap demand for smartphone connector protection.
United States
FDA 21 CFR Part 177 compliance mandates shape food-contact polymer specifications for domestic beverage and pharmaceutical packaging. Naphtha-cracker output fluctuations in Texas and Louisiana compress margin stability for polypropylene compounders serving high-volume automotive contracts. Detroit-area Tier-1 suppliers specify lot-level resin traceability with blockchain-anchored documentation for electric vehicle battery pack venting applications.
Germany
KBA vehicle certification requirements accelerate polymer substitution in underhood sealing systems as OEMs pursue gram-level weight reduction targets. REACH SVHC disclosure obligations force resin suppliers to requalify additive packages in medical-grade polypropylene for export markets. Stuttgart and Munich automotive clusters source precision-molded closures from captive resin compounders with integrated hot-runner injection capabilities.
China
SAMR enforcement of GB standards for plastic food-contact materials creates parallel compliance pathways for exporters serving domestic processors. MEE polymer recycling quotas under dual-carbon policy alignment position bio-based PLA cap producers for preferential procurement in state-owned beverage distribution channels. Shenzhen electronics manufacturers specify push-fit configurations that reduce assembly time in smartphone and semiconductor packaging operations.
India
CDSCO tightening of traceability mandates for exported generics creates demand for serialized tamper-evident closures with embedded holographic authentication features. BIS certification requirements for food-contact materials constrain imported resin grades serving domestic pharmaceutical packaging. Mumbai-Pune pharmaceutical corridor contract manufacturers adopt modular mold-base systems to amortize tooling costs across shorter orphan drug production runs.
South Korea
MFDS medical device regulations enforce MDR-aligned substance migration limits for healthcare-grade closures sold into European markets. Seoul semiconductor packaging clusters favor miniaturized push-fit caps protecting fragile connector arrays during surface-mount assembly. Busan-Ulsan petrochemical complex supplies specialty polypropylene grades with enhanced chemical resistance for automotive underhood applications.
Cover Caps Market Vendor Landscape
Capacity expansion dominates the current landscape as compounders retrofit cold-runner systems with valve-gate hot-runner technology for thin-wall pharmaceutical production. The vendor base organizes around three strategic archetypes: integrated resin compounders with captive feedstock positions, specialized precision molders serving medical and automotive certification tiers, and regional fabricators aggregating mid-volume industrial demand. M&A activity concentrates among European and North American players seeking geographic coverage in Asian electronics corridors. Strategic partnerships between resin suppliers and Tier-1 automotive sealing system providers secure long-term offtake agreements with embedded price volatility clauses.
Among integrated packaging specialists, Closure Systems International, Silgan Holdings, and Amcor PLC exemplify divergent competitive positioning. Closure Systems International represents the captive resin compounding archetype, sustaining margin stability across volatile feedstock cycles through backward integration into polymer production. Silgan Holdings anchors North American beverage and industrial packaging through metal forming and plastic injection operations that span multiple material platforms. Amcor PLC occupies a position emphasizing barrier-engineered composite structures, aligning with pharmaceutical and food-grade applications where hermetic integrity commands premium unit economics. These three entities illustrate how scale, material breadth, and application specialization segment competitive terrain without exclusive territorial claims.
| Leading Market Players |
|---|
| Closure Systems International, Inc. |
| Silgan Holdings Inc. |
| Aptar Group Inc. |
| Nippon Closures Co., Ltd. |
| Berry Global Group Inc. |
| Amcor PLC |
| BERICAP GmbH & Co. KG |
| Caplugs LLC |
| Mold-Rite Plastics, LLC |
| Others |
Supply Flow & Price Mechanics
Tier-1 automotive OEM procurement concentration in Germany and China anchors contract-based long-term offtake agreements for precision-molded closures, with pricing power gravitating toward resin compounders capable of certifying lot-level traceability. This buyer archetype's specification authority compresses margin flexibility for mid-volume molders lacking backward integration into polymer production.
Pricing Analysis
Warranty and service bundling remains unbundled in standard industrial thread protector contracts, with after-sales support priced separately from unit shipments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical closures from automotive underhood grades and generic industrial snap-ons. Price differentiation hinges on certification grade and volume scale, with CDSCO-mandated holographic authentication features commanding substantial premiums. Cost compression in commodity polypropylene snap-ons is intensifying because naphtha-cracker volatility transfers feedstock risk downstream. Mid-volume automotive suppliers exhibit highest price sensitivity, while orphan drug packaging contractors tolerate premium positioning for modular mold-base flexibility.
Supply Chain Analysis
Propylene feedstock supply rests on naphtha-cracker output concentrated along the US Gulf Coast, in Northwest Europe, and within China's petrochemical corridors. Raw material dependencies encompass polymer-grade propylene, specialty additive packages for medical-grade formulations, and aluminum coil stock for high-temperature aerospace applications. Single-source vulnerability concentrates in German and Chinese Tier-1 sealing system procurement, where three dominant resin compounders control critical supply nodes. Distribution runs through direct-to-manufacturer digital portals for standardized industrial thread protectors, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH SVHC disclosure obligations and parallel FDA 21 CFR Part 177 compliance create a cost-of-compliance moat that favors incumbent compounders with dedicated regulatory affairs bandwidth, erecting barriers that strain mid-sized molders without in-house chemistry expertise.
For Market Incumbents: Lock in long-term offtake agreements with embedded price volatility clauses to defend against propylene feedstock swings. Prioritize captive resin compounding investments in the Rhine-Ruhr corridor and Shenzhen-adjacent manufacturing zones to secure geographic coverage. Extend blockchain-anchored traceability systems upstream to monomer producers, converting OEM audit intensity into contractual stickiness.
For New Entrants and Emerging Players: Enter via India's CDSCO-tightened pharmaceutical packaging corridor, where serialized tamper-evident closure demand outpaces domestic molding capacity. Target Mumbai-Pune contract manufacturers serving orphan drug production runs with modular mold-base configurations that amortize tooling across shorter batches. Pursue digital procurement portal partnerships to compress lead times for mid-volume automotive suppliers underserved by incumbent distributor networks.
For Investors and Strategic Acquirers: The window for entry favors specialized precision molders with MDR technical documentation capabilities and established EU healthcare market access. Over the projection horizon, acquisition targets should demonstrate validated hot-runner conversion for thin-wall pharmaceutical production and existing notified body relationships. Watch for MEE enforcement intensity on polymer recycling quotas as the signal indicating preferential procurement shifts toward bio-based PLA producers in Chinese state-owned beverage channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Runner Retrofit Investment | Valve-gate conversion enables thin-wall pharmaceutical cap production cycles competitive with European molders. |
| Backward Integration into Resin Compounding | Captive polymer production insulates margin stability from US Gulf Coast naphtha-cracker volatility. |
| Blockchain-Anchored Traceability Deployment | Lot-level documentation satisfies Detroit-area Tier-1 EV battery pack venting specifications. |
| Modular Mold-Base System Adoption | Quick-change cavity inserts amortize tooling costs across orphan drug packaging's shorter production runs. |
| Bio-Based PLA Capacity Addition | Dual-carbon policy alignment positions producers for preferential procurement in Chinese state beverage distribution. |
Methodological Framework
Multi-period observation of propylene feedstock pricing spreads, automotive OEM gram-reduction targets, and regulatory filing cadences anchored the trend analysis, supplemented by interviews with injection molding plant managers, Tier-1 automotive procurement leads, pharmaceutical regulatory affairs directors, and resin distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated packaging specialists, SAMR GB standard revision notices, and ECHA SVHC list updates. Bottom-up shipment estimates by product mechanism and material platform triangulated against top-down macroeconomic demand indicators.
Input-output matrices modeled capacity utilization rates, feedstock cost pass-through coefficients, and substitution elasticities between polymer and metal stampings across the projection horizon. Segmentation dimensions encompassed closure mechanism type, material platform chemistry, end-use vertical certification tier, and geographic production cluster. CAGRs derived from trend-line extrapolation of historical shipment volumes adjusted for regulatory inflection points and OEM platform transition schedules. Industry-specific forecast inputs included electric vehicle battery pack venting specification trajectories and semiconductor packaging miniaturization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under force majeure events affecting concentrated German and Chinese resin compounders. Projections reflect assumptions regarding REACH SVHC list expansion cadence, MEE recycling quota enforcement intensity, and propylene cracker operating rates. A small set of triggers—CDSCO serialization mandate acceleration, EU extended producer responsibility framework implementation, and automotive OEM blockchain traceability standard adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Heat Induction Cap Liner Market
Caps and Closures
Spout Closures Market
Caps and Closures
Sterile Lids Market
Caps and Closures
Plastic Tamper Evident Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
Crown Caps Market
Caps and Closures
Colombia Plastic Caps and Closures Market
Caps and Closures
Laminated Tube Closure Market
Caps and Closures
Lined Lug Caps Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Nordic Plastic Caps and Closures Market
Caps and Closures
APAC Plastic Caps and Closures Market