
 Pesticides Packaging Market | 2026-2036
Pesticides Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pesticides Packaging Market Analytics
Buyer concentration in the crop protection sector is consolidating around large-scale agricultural cooperatives and integrated pest management service providers across North America and Latin America. Amcor Limited leverages its global film extrusion network to supply multilayer barrier laminates for agrochemical containment. Scholle IPN anchors the bag-in-box segment for bulk liquid herbicide distribution to commercial farming operations. Greif dominates industrial drum supply for concentrated pesticide formulations requiring UN-certified transport packaging.
Pesticides packaging encompasses engineered containment systems designed to preserve active ingredient stability, prevent environmental contamination, and comply with hazardous material handling protocols through features such as fluoropolymer barrier layers, child-resistant closures, and UN performance-tested construction. Its primary commercial purpose centers on ensuring safe distribution, measured application, and regulatory-compliant storage of synthetic and biological crop protection agents from manufacture through field deployment. Plastic material types lead volume due to HDPE and fluorinated bottle dominance in liquid formulations, while laminated pouches represent the fastest-growing package format as growers shift toward water-soluble granule and powder delivery modes. Metal drums retain margin concentration in bulk industrial segments where chemical compatibility and reuse cycles justify premium pricing over single-use alternatives.
The EPA regulates pesticide container residue standards and containment pad requirements under FIFRA, while REACH and the EU F-Gas Regulation restrict certain fluoropolymer barrier chemistries in European markets. India's Central Insecticides Board mandates specific packaging integrity tests under the Insecticides Act, creating divergent compliance pathways across major producing regions. Stakeholders must monitor evolving extended producer responsibility frameworks and substance restriction lists that will determine material substitution timelines and capital allocation for barrier technology redevelopment.
Market Dynamics
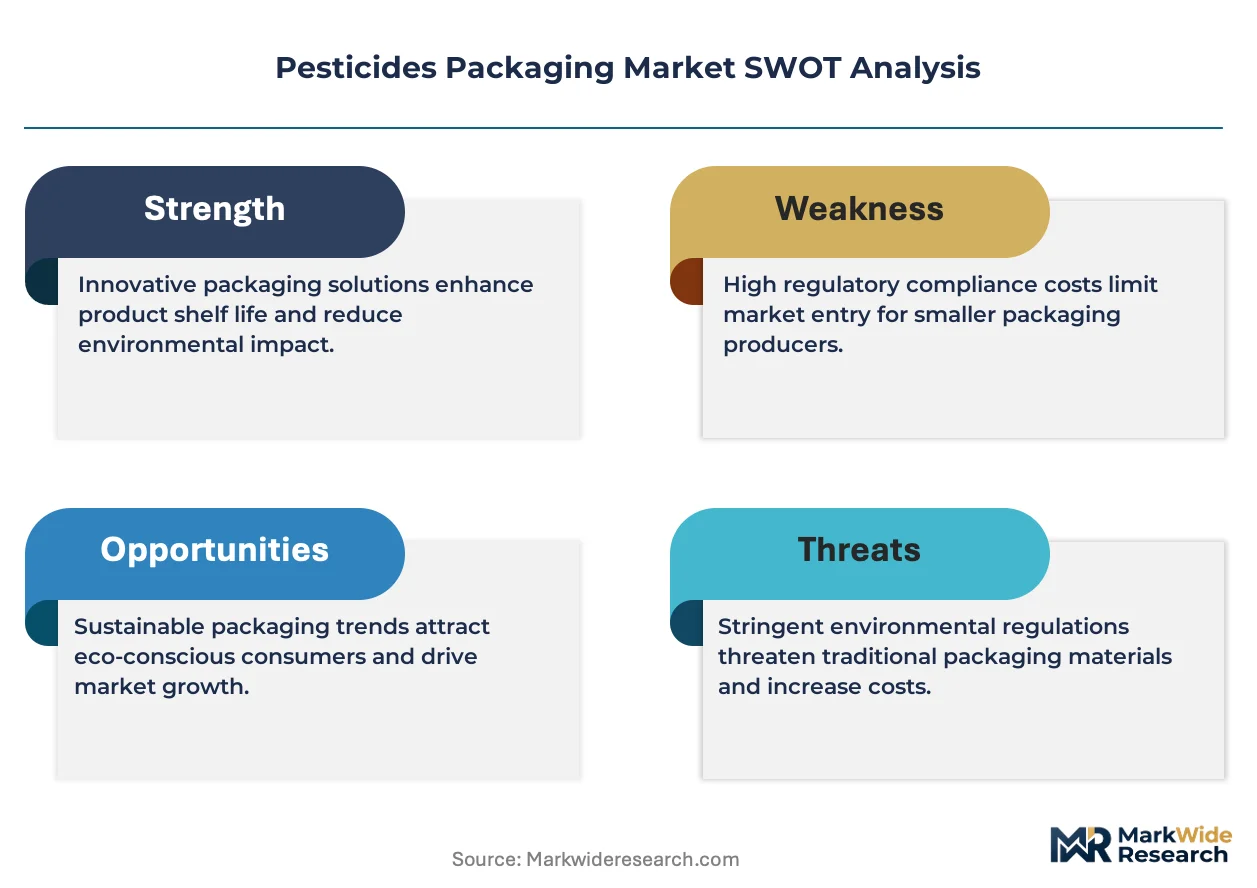
Fluoropolymer phase-out mandates across European regulatory frameworks are forcing material substitution investments throughout the pesticides packaging value chain, compressing barrier technology development timelines while opening competitive space for multilayer laminate alternatives.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving candidate list is accelerating R&D into fluoropolymer-free barrier films, creating first-mover advantage for compliant packaging suppliers.
- Water-soluble granule adoption:Specialty crop programs in Brazil are expanding laminated pouch procurement for precision application systems.
- Integrated pest management subsidies:India's state-level agricultural support programs are standardizing HDPE bottle and pouch procurement volumes across the Indo-Gangetic belt.
Market Restraints
- Fluorinated raw material cost volatility:Barrier resin supply concentration in East Asian petrochemical complexes exposes converters to input price swings.
- UN certification bottlenecks:Performance testing backlog at accredited laboratories extends time-to-market for new industrial drum designs.
- Rigid plastic substitution pressure:Returnable intermediate bulk containers are capturing share in concentrated formulation segments previously served by single-use drums.
Strategic Opportunities
- Biopesticide packaging white space:Microbial and biochemical crop protection agents require oxygen-sensitive barrier systems that incumbent suppliers have underdeveloped.
- Digital printing convergence:Variable-data labeling technology enables lot-level traceability compliance without pre-printed inventory risk.
- Extended producer responsibility frameworks:Emerging collection and recycling mandates in EU member states create service-revenue potential for packaging-as-a-service models.
Industry Challenges
- Multilayer film recycling infrastructure gaps:Post-consumer collection systems lack technical capacity to separate barrier laminates, complicating circularity claims.
- Child-resistant closure certification timelines:ISO 8317 testing protocols require 12-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pesticides Packaging Market |
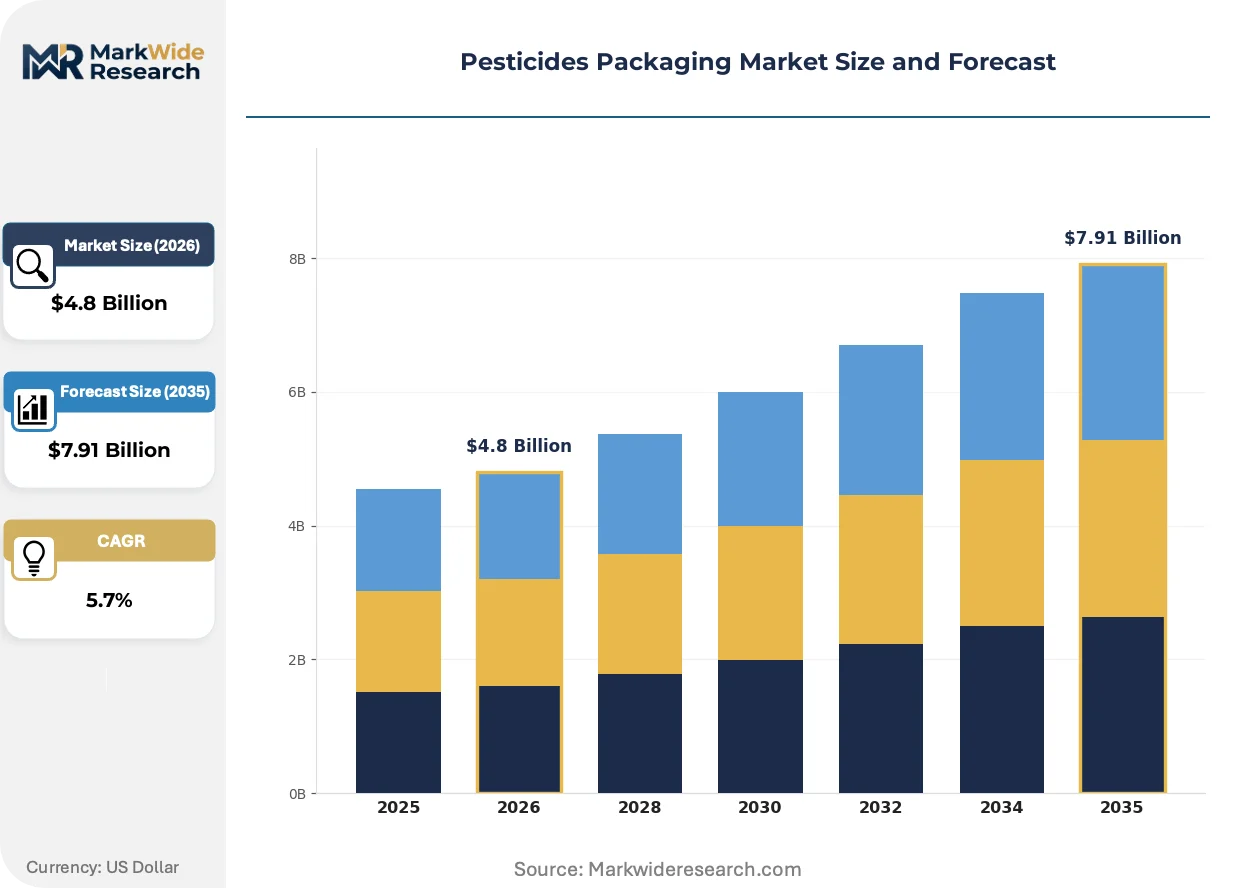
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paper Package Type: Bottles, Bags, Drums, Pouches End User: Agriculture, Horticulture, Forestry, Turf Management Delivery Mode: As a Liquid, As a Granule, As a Powder, Others |
| Companies Covered | Ardagh Group, Scholle IPN, Amcor Limited, DS Smith Plc, Silgan Holdings, Greif, Ball Corporation, Huhtamaki Oyj, Mauser Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pesticides Packaging Market Evolving Landscape
Barrier material science is diverging along two paths: fluoropolymer elimination for regulatory compliance and bio-based feedstock integration for sustainability positioning. Both trajectories demand capital deployment into coextrusion and lamination assets.
Coextruded EVOH barrier structures are integrating oxygen and moisture protection layers into HDPE bottles without fluorinated chemistries. Brazilian agricultural cooperatives are qualifying these alternatives for glyphosate and 2,4-D formulations under accelerated procurement timelines. The technology is integrating high-barrier performance into existing blow-molding infrastructure, compressing capital requirements for regional converters.
EU F-Gas Regulation amendments are restricting per- and polyfluoroalkyl substances in food-contact and agricultural packaging films. Formulators must validate alternative barrier chemistries against active ingredient migration standards. The agrochemical sector is responding with multilayer pouch designs that substitute metallized films for fluoropolymer layers.
Precision agriculture service providers are consolidating procurement decisions for packaging systems alongside application equipment. Large-scale farming operations in the US Corn Belt are negotiating multi-year supply agreements that bundle container supply with closed-loop collection services. This concentration is most visible in Iowa and Illinois, where cooperative buying groups now specify UN-certified containers with embedded RFID traceability.
Pesticides Packaging Market Segmentation
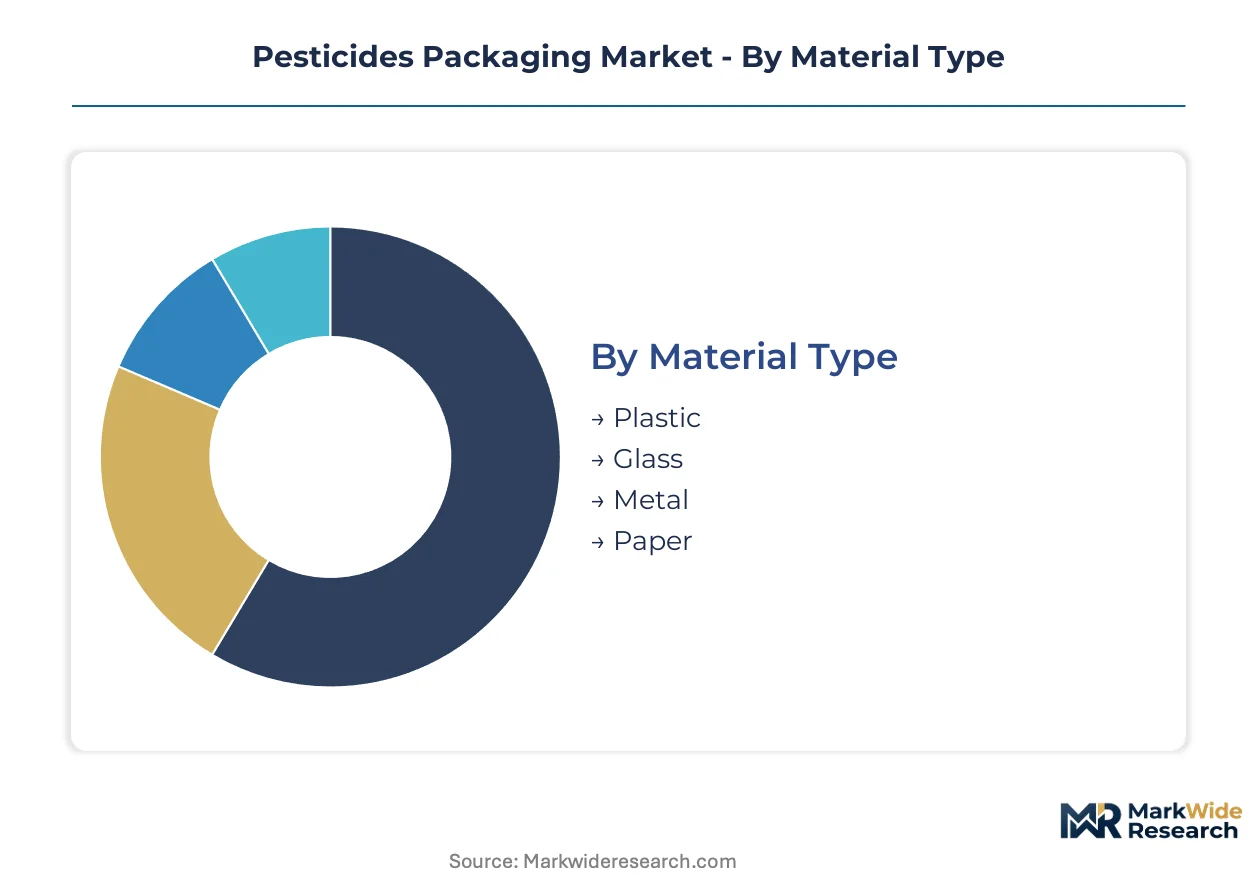
Pesticides packaging segmentation reflects divergent containment requirements across formulation chemistries, application scales, and regulatory jurisdictions. Material selection and package geometry must align with active ingredient stability needs, transport safety protocols, and end-user handling preferences.
Material Type:
Standalone barrier materials dominate liquid agrochemical containment, while composite structures embed functional layers for oxygen-sensitive biological formulations.
- Plastic:HDPE bottles incorporate fluoropolymer or EVOH barrier layers to prevent active ingredient permeation in glyphosate and 2,4-D formulations. Brazilian agricultural cooperatives are accelerating procurement of fluoropolymer-free multilayer alternatives under EU F-Gas Regulation compliance timelines.
- Metal:Cold-rolled steel drums with epoxy phenolic linings serve concentrated industrial formulations requiring UN-certified transport integrity. Reuse cycles and chemical compatibility justify premium positioning in bulk herbicide and fungicide distribution.
- Glass:Borosilicate containers retain niche positioning for laboratory reference standards and specialty biochemical formulations demanding inert contact surfaces.
- Paper:Multiwall sacks with polymer barrier coatings package water-soluble granules for precision agriculture applications in India's Indo-Gangetic belt.
Plastic leads volumes today; paper-based alternatives are gaining share fastest.
Package Type:
Volume concentration follows application scale: retail-sized units for smallholder farms versus bulk containment for commercial operations.
- Bottles:Blow-molded HDPE containers with child-resistant closures dominate liquid pesticide retail distribution. India's state-level integrated pest management subsidies standardize procurement of one-liter and five-liter formats across agricultural extension networks.
- Pouches:Laminated multilayer structures with metallized or coextruded barriers package water-soluble granules and powders. Brazilian specialty crop programs are expanding laminated pouch procurement for precision application systems.
- Drums:200-liter steel and plastic drums serve concentrated formulation bulk distribution to commercial farming operations and blending facilities.
- Bags:Woven polypropylene with polyethylene liners handles solid formulation transport at intermediate volumes between retail and bulk segments.
Bottles retain the largest installed base; pouches demonstrate the steepest expansion trajectory.
End User:
Customer scale determines packaging specification complexity, from standardized smallholder formats to customized closed-loop systems.
- Agriculture:Row crop and broadacre farming drives volume demand for HDPE bottles, drums, and laminated pouches. US Corn Belt cooperatives negotiate multi-year supply agreements bundling container procurement with RFID traceability and collection services.
- Horticulture:Specialty fruit and vegetable production requires smaller-format precision packaging with measured-dispensing features for high-value crop protection programs.
- Forestry:Aerial and mechanized application systems favor bulk liquid containment in intermediate bulk containers and specialized drum formats.
- Turf Management:Golf course and landscape maintenance segments procure mid-volume bottles and pouches with ergonomic handling features for frequent application cycles.
Agriculture commands the dominant revenue share; horticulture is expanding most quickly on per-hectare packaging intensity.
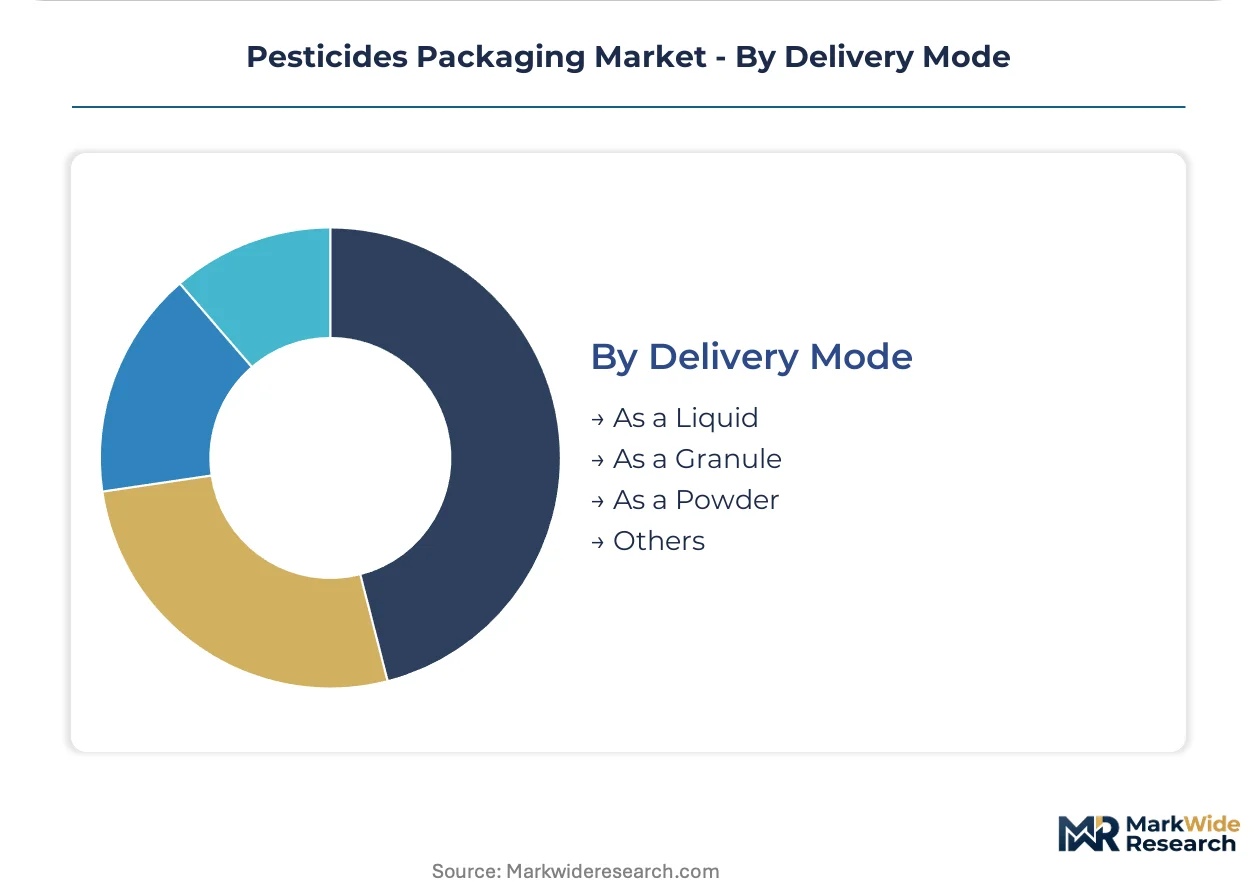
Delivery Mode:
Physical state at point of application dictates barrier requirements, with liquid formulations demanding permeation resistance and solids requiring moisture protection.
- As a Liquid:Emulsifiable concentrates and suspension concentrates require fluoropolymer-free barrier evolution under REACH and EU F-Gas Regulation mandates. Coextruded EVOH structures are qualifying for glyphosate containment in Brazilian and European markets.
- As a Granule:Water-soluble and controlled-release granules drive laminated pouch adoption for precision metering and reduced dust exposure during handling.
- As a Powder:Wettable powders and dust formulations package in multiwall paper sacks with moisture barrier coatings for tropical storage conditions.
- Others:Gel and tablet formulations occupy emerging niches in biological crop protection requiring oxygen-scavenging barrier systems.
Liquid formats maintain volume leadership; granule delivery is climbing the fastest on precision agriculture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian agricultural cooperatives outpace Indian state procurement programs in laminated pouch adoption, while EU regulatory pressure accelerates fluoropolymer phase-out timelines faster than North American compliance schedules.
United States
Corn Belt cooperatives in Iowa and Illinois bundle container procurement with RFID traceability services. EPA FIFRA regulations mandate residue standards and containment pad requirements for bulk herbicide storage. Midwestern agricultural buying groups now specify UN-certified containers with embedded tracking for closed-loop collection systems.
Brazil
Specialty crop protection programs in São Paulo and Minas Gerais drive laminated pouch procurement for precision application systems. ANVISA alignment with EU F-Gas Regulation timelines accelerates fluoropolymer-free packaging qualification. São Paulo-based agricultural cooperatives are qualifying coextruded EVOH barrier structures for glyphosate containment ahead of regulatory deadlines.
Germany
REACH substance restrictions and EU F-Gas Regulation amendments force material substitution investments across the Rhine-Ruhr industrial corridor. ECHA's evolving candidate list accelerates R&D into fluoropolymer-free barrier films. Bavarian packaging converters are deploying multilayer lamination assets to serve agrochemical formulators seeking compliant alternatives.
India
State-level integrated pest management subsidies standardize HDPE bottle and pouch procurement across the Indo-Gangetic belt. The Central Insecticides Board mandates specific packaging integrity tests under the Insecticides Act. Haryana and Punjab agricultural extension networks are driving volume procurement of one-liter and five-liter standardized formats.
China
Yangtze River Delta petrochemical complexes concentrate fluorinated raw material supply for barrier resin production. MEE environmental standards and dual carbon goals pressure converters toward lower-emission production methods. Zhejiang and Jiangsu provinces host the majority of multilayer film extrusion capacity serving domestic agrochemical packaging demand.
Pesticides Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material technologies and geographic footprints. The market structure shows moderate consolidation around global packaging conglomerates with dedicated agrochemical divisions, alongside regional converters serving localized formulation markets. Three archetypes dominate: integrated rigid packaging suppliers with drum and bottle capabilities, flexible film specialists with barrier lamination expertise, and hybrid players spanning both rigid and flexible formats. Competitive moves center on M&A activity to acquire fluoropolymer-free barrier technology and strategic partnerships with agricultural cooperatives for closed-loop collection services.
Among diversified packaging conglomerates, Amcor Limited and Greif exemplify scale-driven positioning across multiple containment formats. Scholle IPN occupies a specialist position within the bag-in-box segment for bulk liquid distribution. These three companies represent the dominant competitive anchors in a market where material compliance capabilities and UN certification breadth determine procurement decisions.
| Leading Market Players |
|---|
| Ardagh Group |
| Scholle IPN |
| Amcor Limited |
| DS Smith Plc |
| Silgan Holdings |
| Greif |
| Ball Corporation |
| Huhtamaki Oyj |
| Mauser Packaging Solutions |
| Others |
Value Network & Pricing Analysis
Fluoropolymer resin price indices from Yangtze River Delta petrochemical complexes cascade through multilayer film converters into tiered pricing structures, where EU F-Gas Regulation compliance premiums separate certified barrier laminates from commodity HDPE bottles serving Indian state procurement programs.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for EVOH barrier structures as converters compete for Brazilian agricultural cooperative contracts. Three-tier pricing structure across premium, standard, and economy levels reflects UN certification grade and embedded RFID traceability features. Cost compression in standard HDPE bottles is intensifying because Indian volume procurement aggregates demand around standardized one-liter and five-liter formats. Smallholder agricultural extension networks exhibit highest price sensitivity, while US Corn Belt cooperatives negotiating closed-loop collection bundles show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German agrochemical formulators mandate multi-supplier qualification across Zhejiang fluoropolymer resin producers and Bavarian multilayer lamination specialists. Raw material flows draw from Chinese petrochemical complexes for barrier resins, Indian HDPE granule suppliers, and German coextrusion equipment manufacturers. Single-source vulnerability concentrates in fluorinated chemistries facing REACH substance restrictions. Distribution runs through agricultural cooperative procurement networks in Brazil and state-level extension systems in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in fluoropolymer-free barrier technologies where EVOH coextrusion investments capture EU F-Gas Regulation compliance premiums ahead of phase-out deadlines.
For Market Incumbents: Anticipate laminated pouch substitution pressure from Brazilian precision agriculture adoption by accelerating coextruded EVOH qualification timelines. Anchor defensive positioning through backward integration into multilayer lamination assets in Bavaria and São Paulo to control barrier technology deployment. Child-resistant closure certification bottlenecks threaten product launch velocity; secure ISO 8317 testing capacity through exclusive laboratory partnerships. For New Entrants and Emerging Players: EU F-Gas Regulation amendments in Germany open a window for metallized film barrier specialists to capture agrochemical formulator switching costs. Target biopesticide packaging white space where oxygen-sensitive microbial formulations lack incumbent supplier coverage. Enter through precision agriculture service provider partnerships bundling container supply with closed-loop collection services in Iowa and Illinois. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap flexible film converters possessing fluoropolymer-free barrier R&D capabilities and existing UN certification breadth. Long-term viability hinges on extended producer responsibility framework positioning across EU member states. Watch ECHA candidate list expansion velocity as inflection indicator for material substitution investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer-Free Barrier R&D Investment | EVOH coextrusion capabilities capture EU F-Gas Regulation compliance premiums ahead of deadlines. |
| Multilayer Lamination Capacity Expansion | Bavarian and São Paulo assets serve German and Brazilian agrochemical formulator switching demand. |
| Closed-Loop Collection Service Launch | RFID-enabled container tracking meets US Corn Belt cooperative procurement bundling requirements. |
| Biopesticide Packaging Development | Oxygen-scavenging barrier systems address microbial crop protection agent stability requirements. |
| UN Certification Portfolio Broadening | Performance-tested construction expands addressable market into concentrated industrial formulations. |
Research Methodology
Direct dialogue with multilayer film plant managers, agrochemical procurement leads at Brazilian cooperatives, Indian state agricultural extension officers, and barrier technology R&D directors grounded qualitative findings. Secondary validation drew from ECHA substance restriction filings, EPA FIFRA containment pad guidance, Indian Central Insecticides Board test protocols, and customs trade data for fluoropolymer resin flows. Bottom-up volume modeling triangulated against top-down agrochemical formulation production estimates.
Top-down market sizing segmented across material type, package geometry, end-user scale, and delivery mode physical state throughout the forecast period. CAGRs derived from regression analysis against agricultural input expenditure trends and regulatory compliance investment cycles. Modeled inputs included laminated pouch adoption rates in Brazilian specialty crop programs and HDPE bottle standardization velocity across Indian state subsidy schemes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas Regulation amendment timelines or prolonged UN certification laboratory backlogs. Deviation in REACH candidate list expansion velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Industrial Pails Market
Packaging
Utility Grade Duct Tapes Market
Packaging
Latin America Pharmaceutical Packaging Market
Packaging
Envelope Market
Packaging
Buttress Closures Market
Packaging
Cosmetic Bottles Packaging Market
Packaging
Cold Chain Packaging Materials Market
Packaging
Tube and Stick Packaging Market
Packaging
Pre-Made Pouch Packaging Machines Market
Packaging
Global Laminated Labels Market
Packaging
North America Beverage Packaging Market
Packaging
Pet Food Packaging Market
Packaging
Desiccant Market
Packaging
ISO Container Market
Packaging
Container Washing System Market
Packaging
Global Beverage Carton Packaging Machinery Market