
 Foam Mesh Sleeves Market | 2026-2036
Foam Mesh Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Mesh Sleeves Market Foresight
ISO 9001 certification is rotating as a baseline qualifier for supplier qualification programs across major buyers. Sealed Air Corporation leverages its global manufacturing footprint to sustain consistent supply to electronics OEMs. Pregis Corporation anchors its position through specialized protective packaging systems for fragile components. UFP Technologies differentiates via custom-engineered foam solutions targeting medical device applications.
Foam mesh sleeves are cylindrical protective coverings manufactured from expanded polyethylene or polyurethane foam matrices, typically featuring open-cell structures with mesh reinforcement for tear resistance and cushioning performance. These products absorb impact energy and prevent surface abrasion during transit, storage, and handling of delicate components. Polyurethane foam variants command premium positioning due to superior resilience and chemical stability, while protective packaging applications generate the largest volume demand across the value chain. Flexible foam formats are gaining share in cable management and sporting goods protection where conformability matters.
FDA regulations govern foam materials contacting medical devices, while REACH restricts hazardous substance content in European-sourced products, and California Proposition 65 drives reformulation of certain blowing agents in US-bound shipments. Compliance costs are shifting procurement criteria toward suppliers with pre-certified material streams. Stakeholders must evaluate how evolving extended producer responsibility frameworks will reshape recycling obligations and material recovery economics.
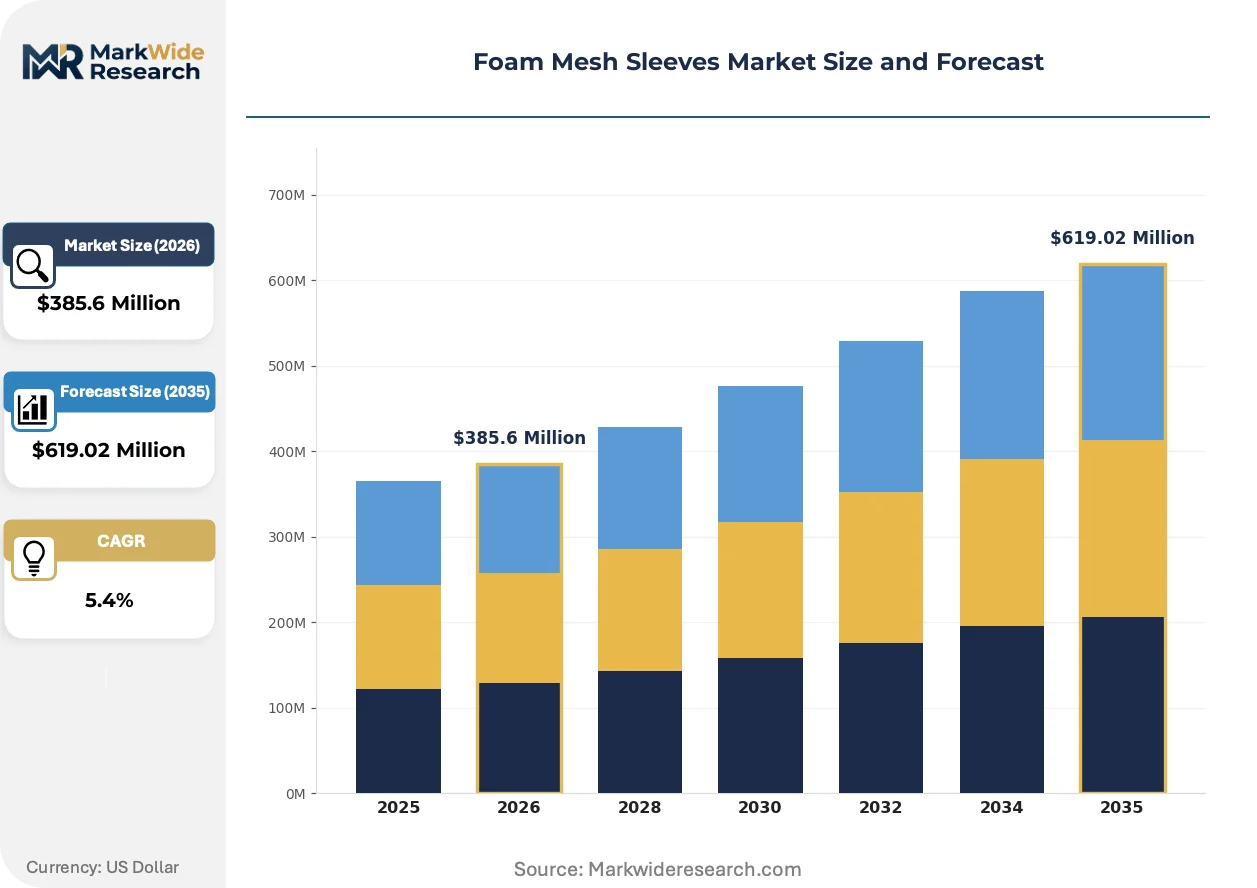
Market Dynamics
Electronics supply chain regionalization is forcing foam mesh sleeve manufacturers to establish distributed production footprints closer to final assembly locations, compressing lead times and altering procurement patterns across the protective packaging value chain.
Growth Catalysts
- Consumer electronics manufacturing:Smartphone and laptop OEMs in Vietnam and Mexico require conformable protective solutions for fragile component transit, driving volume contracts with foam sleeve suppliers.
- REACH compliance frameworks:European chemical safety mandates are eliminating hazardous blowing agents from foam formulations, creating certified material streams that command preference from multinational buyers.
- Expanded polyethylene formulations:Open-cell EPE variants with mesh reinforcement deliver superior tear resistance for cable management applications, penetrating industrial equipment supply chains.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price swings directly compress margins on polyurethane foam variants, forcing reformulation toward lower-density polyethylene alternatives.
- East Asian supply concentration:Overreliance on Chinese and South Korean foam extrusion capacity creates vulnerability to shipping disruptions and trade policy friction.
- Mechanical substitution:Injection-molded plastic clamshells and paper-based molded pulp solutions are capturing share in lower-value electronics segments where cushioning demands moderate.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for smartphone and semiconductor assembly are creating virgin demand for protective packaging with no incumbent supplier relationships.
- Medical device cold chain:Temperature-stable foam mesh configurations for biologic shipment protection represent an underdeveloped application with premium pricing potential.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks will reward suppliers with closed-loop recycling infrastructure and certified recycled content streams.
Industry Challenges
- ISO 9001 certification timelines:Smaller foam converters face 12-18 month qualification periods to meet electronics OEM vendor requirements, freezing out regional players from tier-one supply chains.
- Multi-material separation:Mesh-reinforced foam sleeves combine incompatible polymer streams, complicating mechanical recycling and raising compliance costs under evolving EPR schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Mesh Sleeves Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Core, Flexible Foam, Rigid Foam, Elastic Mesh, Polyurethane Foam Application: Protective Packaging, Cable Management, Medical Device Covers, Automotive Component Insulation, Sporting Goods Protection End User: Consumer Electronics Manufacturers, Medical Equipment Suppliers, Industrial Component Assemblers, Sports Equipment Producers, Electrical Contractors Distribution Channel: Direct Sales, E-commerce, Distributors, Industrial Suppliers, Specialty Retailers |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, UFP Technologies, Sonoco Products Company, Suyog Plastics, Hefei Better Technology Co., Ltd., Unipack Pte Ltd., Paramount Packaging, Industrial Netting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Mesh Sleeves Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to reshape foam formulation strategies, while buyer consolidation in downstream electronics is compressing supplier negotiation leverage.
Bio-based polyurethane foam derived from castor oil and sugarcane feedstocks is decomposing the petroleum-dependent cost structure of conventional sleeve production. Medical device manufacturers in Germany and Switzerland are piloting these formulations for single-use surgical instrument protection. The technology is decomposing historical raw material cost volatility while opening premium positioning for sustainability-certified suppliers.
California Proposition 65 enforcement is tightening disclosure requirements for toluene diisocyanate residuals in polyurethane foam bound for US consumer products. Manufacturers serving the North American market are accelerating TDI-free formulation shifts and third-party testing investments. Sporting goods and juvenile product categories face the steepest compliance ramps, with several major retailers now mandating Prop 65-compliant documentation for all foam-containing shipments.
Consolidated procurement desks at major electronics contract manufacturers are compressing supplier rosters and demanding vendor-managed inventory arrangements. Direct material sourcing relationships are displacing distributor intermediaries in high-volume sleeve categories. This concentration is most visible in Shenzhen and Ho Chi Minh City manufacturing corridors, where Foxconn and Luxshare Precision have reduced qualified foam packaging vendors by half since 2022.
Foam Mesh Sleeves Market Segmentation
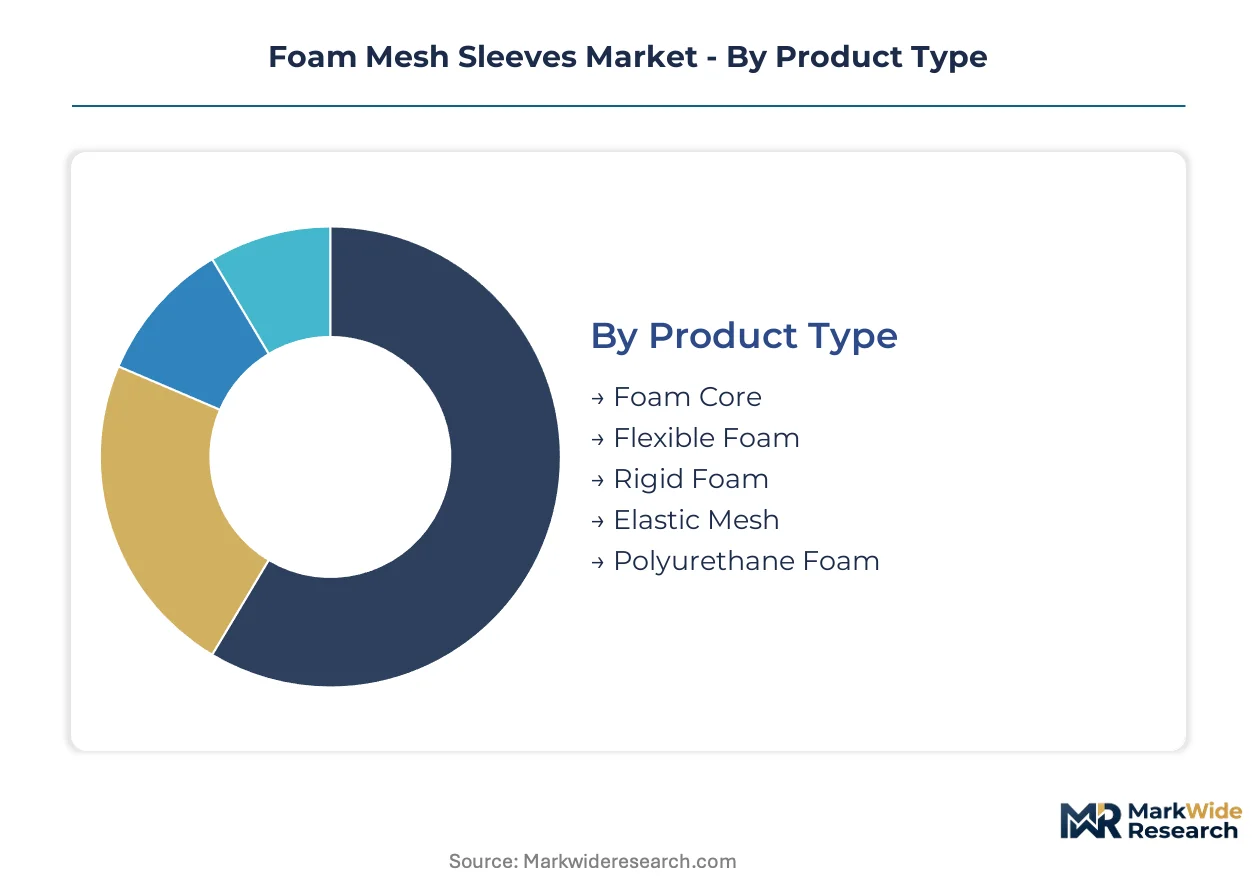
Foam mesh sleeve procurement patterns diverge sharply across material grades and end-use specifications. Electronics OEMs demand certified material streams while medical buyers prioritize temperature-stable configurations. Understanding segment-level demand drivers exposes where supplier margins concentrate versus where volume contracts dominate.
Product Type:
Domestic production concentrates on commodity polyethylene grades, while polyurethane and specialty mesh variants flow through import-dependent supply chains serving premium applications.
- Polyurethane Foam:Closed-cell formulations deliver superior chemical stability and resilience for repeated-use medical device covers. German and Swiss surgical instrument manufacturers specify castor-oil-derived bio-based variants to satisfy EU Green Deal circularity mandates.
- Foam Core:Expanded polyethylene matrices with mesh reinforcement dominate consumer electronics protective packaging. Vietnam and Mexico assembly plants source these through regional extrusion facilities to compress lead times.
- Flexible Foam:Open-cell conformable structures penetrate cable management and sporting goods where deformation recovery matters.
- Rigid Foam:Dense compression-molded configurations serve automotive component insulation against thermal and vibrational stress.
- Elastic Mesh:Hybrid constructions combining foam substrates with woven reinforcement target high-tear-resistance industrial applications.
Polyurethane Foam holds the largest share; momentum sits with Flexible Foam as cable management applications expand.
Application:
Cost tier stratification separates commodity protective packaging from premium medical and automotive specifications requiring certified material documentation.
- Protective Packaging:Volume leader generating largest demand across the value chain. Smartphone and laptop OEMs in Shenzhen and Ho Chi Minh City corridors specify conformable sleeves for fragile component transit.
- Medical Device Covers:Temperature-stable foam mesh configurations for biologic shipment protection command premium positioning. FDA regulations govern materials contacting devices, while EMA frameworks apply to European-bound products.
- Cable Management:Industrial equipment supply chains adopt tear-resistant EPE variants with mesh reinforcement for harness organization.
- Automotive Component Insulation:NVH suppression and thermal management applications favor dense foam formulations.
- Sporting Goods Protection:Juvenile product categories face steep California Proposition 65 compliance ramps for TDI residuals.
Protective Packaging anchors volume; Medical Device Covers are climbing the fastest on cold chain expansion.
End User:
Customer type determines procurement modality, with consolidated electronics OEMs demanding vendor-managed inventory while fragmented electrical contractors purchase through distributor intermediaries.
- Consumer Electronics Manufacturers:Foxconn and Luxshare Precision procurement desks compress supplier rosters and mandate ISO 9001 certification. Direct material sourcing relationships displace distributors in high-volume categories.
- Medical Equipment Suppliers:German and Swiss manufacturers pilot bio-based polyurethane formulations for single-use surgical instrument protection.
- Industrial Component Assemblers:Fragmented demand across machinery and automation equipment favors distributor-served procurement.
- Sports Equipment Producers:California-bound shipments face tightening Prop 65 disclosure requirements for toluene diisocyanate residuals.
- Electrical Contractors:Small-batch cable management sleeve purchases flow through industrial suppliers and specialty retailers.
Consumer Electronics Manufacturers command the deepest supplier relationships; Medical Equipment Suppliers represent the steepest expansion trajectory on sustainability-certified material adoption.
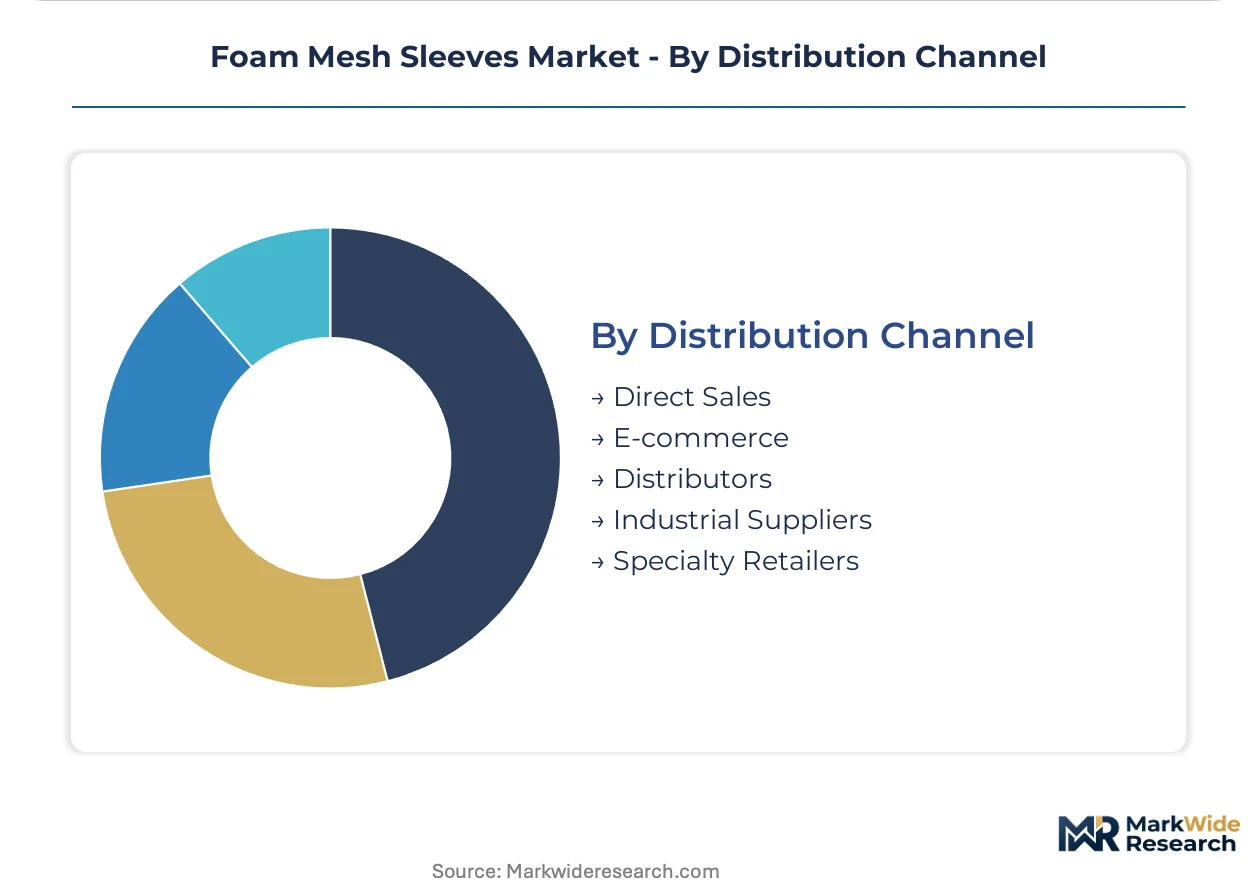
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shapes channel preference, with direct sales dominating high-volume electronics corridors while fragmented geographies sustain distributor relevance.
- Direct Sales:Electronics contract manufacturers in Vietnam and Mexico establish direct material sourcing relationships to secure consistent supply and compress lead times.
- Distributors:Regional foam converters serve fragmented industrial and electrical contractor demand where order quantities fall below direct sales thresholds.
- E-commerce:Small-batch procurement for prototyping and maintenance-repair-operations applications.
- Industrial Suppliers:Integrated catalog distribution serving multi-product procurement for facility maintenance.
- Specialty Retailers:Niche sporting goods and consumer-facing protective sleeve applications.
Direct Sales captures the largest volume; E-commerce is gaining share fastest on digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics contract manufacturers in Vietnam, Mexico, and India are compressing supplier lead times through regional foam extrusion partnerships. German medical device producers pilot bio-based formulations to satisfy EU circularity mandates. Shenzhen and Ho Chi Minh City manufacturing corridors anchor procurement volume concentration.
China
Foxconn and Luxshare Precision procurement desks in Shenzhen have halved qualified foam packaging vendors since 2022. The country's MIIT enforces GB standards for materials contacting electronic components. Pearl River Delta extrusion facilities supply conformable EPE sleeves to smartphone assembly plants.
Vietnam
Smartphone OEMs relocating from China require protective packaging for fragile component transit. The country's Ministry of Industry and Trade administers import substitution incentives for packaging materials. Ho Chi Minh City industrial zones host regional foam converters serving Samsung and Apple contract manufacturers.
Germany
Surgical instrument manufacturers pilot castor-oil-derived bio-based polyurethane formulations. ECHA REACH restrictions eliminate hazardous blowing agents from foam formulations destined for European markets. Bavaria's medical technology cluster drives premium pricing for temperature-stable cold chain configurations.
United States
California Proposition 65 enforcement tightens toluene diisocyanate disclosure requirements for polyurethane foam. The EPA oversees chemical safety in manufacturing processes. Texas and Arizona electronics assembly corridors source sleeves through Mexico-based regional extrusion to compress landed costs.
India
PLI scheme incentives for smartphone and semiconductor assembly create virgin demand without incumbent supplier relationships. BIS certification governs material standards for electronics packaging. Karnataka and Tamil Nadu manufacturing clusters attract direct investment from foam sleeve suppliers establishing regional production.
Foam Mesh Sleeves Market Competitive Landscape
Player mix skews toward diversified packaging conglomerates with global manufacturing footprints. Mid-scale regional converters occupy fragmented niches serving distributor channels. Three archetypes dominate: integrated protective packaging systems providers, custom-engineered foam specialists, and commodity polyethylene extruders. Competitive moves center on geographic expansion toward electronics manufacturing relocation corridors and formulation shifts to satisfy bio-based and chemical compliance mandates.
Within the integrated systems tier, Sealed Air Corporation and Pregis Corporation represent global-scale positioning through established electronics OEM relationships. UFP Technologies occupies a specialist position in custom-engineered configurations. Regional converters including Suyog Plastics and Hefei Better Technology Co., Ltd. exemplify proximity-based supply models serving Asian manufacturing clusters. Sonoco Products Company anchors diversified industrial packaging exposure across multiple material formats.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| UFP Technologies |
| Sonoco Products Company |
| Suyog Plastics |
| Hefei Better Technology Co., Ltd. |
| Unipack Pte Ltd. |
| Paramount Packaging |
| Industrial Netting |
| Others |
Supply & Pricing Matrix
ISO 9001 certification gates supplier qualification and price differentiation simultaneously, compressing margins for uncertified converters while rewarding pre-certified material streams with premium positioning in electronics OEM vendor programs.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate polyurethane foam procurement, exposing margins to petrochemical feedstock volatility. Three-tier pricing structure across premium bio-based, standard REACH-compliant, and economy polyethylene grades separates certified medical device suppliers from commodity electronics packaging vendors. Cost compression in standard-grade EPE sleeves is intensifying because injection-molded plastic clamshells capture share in lower-value electronics segments. Electrical contractors purchasing through distributor channels exhibit highest price sensitivity; German surgical instrument manufacturers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Inventory buffers and lead-time compression are reshaping procurement patterns as Foxconn and Luxshare Precision mandate vendor-managed inventory arrangements in Shenzhen and Ho Chi Minh City corridors. Extrusion capacity concentrates in China, South Korea, and Vietnam, drawing from polyethylene resin, toluene diisocyanate, and castor oil bio-feedstock inputs. Single-source vulnerability in Chinese foam extrusion creates exposure to shipping disruptions and trade policy friction. Distribution runs through direct sales relationships with electronics contract manufacturers, with distributor intermediaries serving fragmented industrial and electrical contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foam mesh sleeve demand tracks consumer electronics manufacturing cycles, with procurement desks at contract manufacturers signaling recovery through expanded vendor qualification programs.
For Market Incumbents: Compound certification advantages by accelerating REACH-compliant and bio-based formulation capacity additions in Germany and Switzerland. Anchor backward integration into castor oil bio-feedstock supply to defend margin position against petrochemical volatility. Capture stranded regional converter capacity through selective acquisition of ISO 9001-certified extrusion facilities in Vietnam and Mexico.
For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors where smartphone and semiconductor assembly creates virgin demand without incumbent supplier relationships. Target medical device cold chain configurations for biologic shipment protection as the most penetrable premium segment. Establish direct sales relationships with Karnataka and Tamil Nadu manufacturing clusters, bypassing distributor intermediaries entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed packaging conglomerates seeking exit liquidity from foam sleeve portfolios. Five-to-ten year viability hinges on circularity infrastructure investments satisfying EU Green Deal extended producer responsibility mandates. Watch for EPR scheme enforcement intensity in Germany as the inflection signal for recycled content premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock Supply | Castor oil sourcing decomposes petroleum cost volatility for polyurethane variants. |
| REACH-Compliant Formulation Certification | ECHA chemical safety mandates eliminate hazardous blowing agents from European-bound production. |
| Regional Extrusion Capacity in Vietnam | Samsung and Apple contract manufacturers compress lead times through proximity supply. |
| Closed-Loop Recycling Infrastructure | EU Green Deal circularity mandates reward suppliers with certified recycled content streams. |
| Direct Sales Relationship with Electronics OEMs | Foxconn procurement desks displace distributor intermediaries in high-volume sleeve categories. |
Research Methodology
A standing panel of foam extrusion plant managers, electronics OEM procurement leads, medical device packaging engineers, and distributor channel partners provided ongoing calibration against operational realities. Primary interviews combined with secondary validation from customs trade data, SEC 10-K filings of packaging conglomerates, and ECHA REACH substance restriction notifications. Bottom-up volume triangulation across material grades and end-use applications converged with top-down value estimates derived from regional manufacturing cluster analysis.
Consistency checks validated volume and value outputs against external benchmarks including regional electronics production data and protective packaging trade flows. Segmentation dimensions modeled encompass material chemistry tier, end-use application specification, certification compliance level, and regional manufacturing hub. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating inputs from smartphone assembly relocation patterns and medical device cold chain expansion trajectories.
Material uncertainties — petrochemical feedstock price swings, EPR scheme enforcement timelines, and electronics manufacturing relocation velocity — sit outside the modeled envelope. Forecasts reflect assumptions about sustained REACH compliance investment and bio-based formulation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Insulated Styrofoam Shipping Boxes Market
Protective Packaging
Insulated Shipping Boxes Market
Protective Packaging
Bubble Wrap Packaging Market
Protective Packaging
High Pressure Protective Packaging Film Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Secondary Containment Trays Market
Protective Packaging
Adhesive Bubble Wrap Market
Protective Packaging
North America Insulated Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Protective Packaging Market
Protective Packaging
North America Protective Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Foam Protective Packaging Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Inflatable Packaging Market