
 Reconditioned IBC Market | 2026-2036
Reconditioned IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Reconditioned IBC Market Outlook
Automated high-pressure wash systems with integrated RFID tracking is reconfiguring reconditioning workflows across the IBC supply chain. Snyder Industries, Inc. leverages its rotational molding expertise to control captive refurbishment networks in North American chemical corridors. TranPak Inc. specializes in closed-loop pooling programs that anchor long-term contracts with agricultural distributors. Container Exchanger operates a digital marketplace that extends geographic reach beyond traditional distributor territories.
A reconditioned intermediate bulk container is a reused, cleaned, and pressure-tested vessel typically constructed from high-density polyethylene or stainless steel, designed to transport and store 200 to 1,000 liters of liquid or granular materials across industrial supply chains. Plastic IBC dominates volume flows due to lower reconditioning energy costs and broader chemical compatibility, though metal IBC commands premium positioning in solvent and high-temperature applications. The 1000-liter capacity segment leads absolute unit demand from chemical end users, while flexible IBC reconditioning represents the fastest-growing sub-category as food-grade bulk liquid shippers seek collapsible return packaging. Direct sales channels capture the largest margin pools through multi-year service contracts with integrated chemical producers, even as distributor networks retain volume leadership among small and mid-sized agricultural buyers.
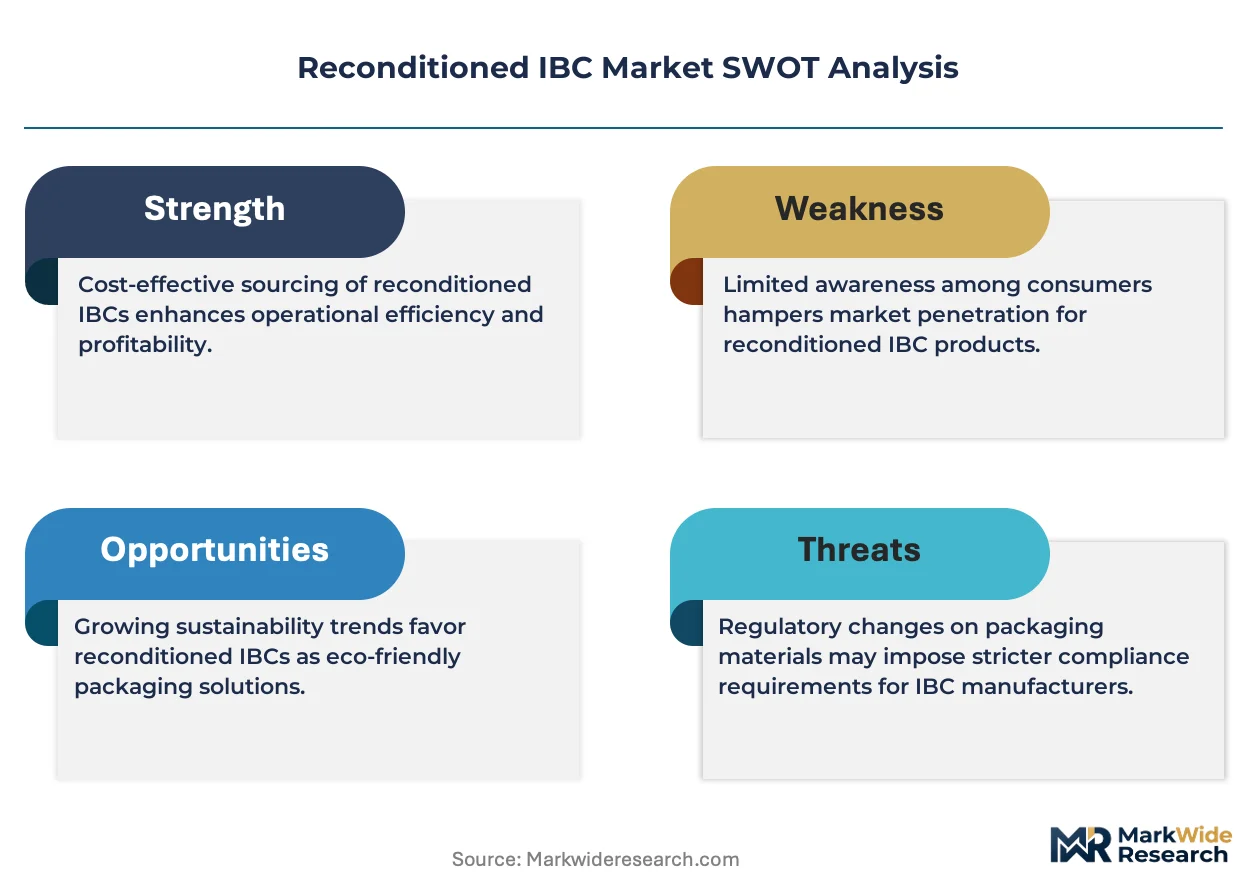
The EPA regulates reconditioned IBC handling under RCRA hazardous waste protocols, while DOT enforces UN-certified retesting intervals that determine container eligibility for continued chemical transport. OSHA mandates specific cleaning validation procedures that shape facility capital requirements and operational compliance costs. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could mandate minimum reconditioning rates or impose fees on virgin container production.
Market Dynamics
Automated high-pressure wash systems with integrated RFID tracking are compressing reconditioning cycle times while elevating traceability requirements across chemical supply chains. This technology shift is forcing capital redeployment from manual cleaning bays toward continuous-flow automated lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory reuse targets for industrial packaging are redirecting procurement budgets from virgin IBC purchases toward certified reconditioning services.
- US Gulf Coast petrochemical corridor:Cluster density of chemical processors reduces empty container collection distances, lowering per-unit logistics costs below threshold for economic viability.
- Automated wash systems:RFID-integrated high-pressure cleaning protocols are standardizing throughput rates and enabling real-time compliance documentation for UN-certified reconditioners.
Market Restraints
- Stainless steel feedstock volatility:Nickel price swings directly compress margins for metal IBC reconditioners serving solvent and high-temperature applications.
- Single-use flexible IBC substitution:Collapsible virgin containers are capturing food-grade bulk liquid shipments where reconditioning certification complexity exceeds buyer risk tolerance.
- OSHA cleaning validation mandates:Capital requirements for facility upgrades to meet specified cleaning validation procedures are consolidating reconditioning capacity toward larger operators.
Strategic Opportunities
- China hazardous material transport:GB standards elevation is creating demand for UN-certified reconditioning capacity that domestic suppliers currently underserve.
- Agricultural closed-loop pooling:Long-term service contracts with agricultural distributors remain underpenetrated relative to chemical sector penetration rates.
- Digital marketplace channels:Geographic reach extension beyond traditional distributor territories enables direct matching of empty container supply with regional demand clusters.
Industry Challenges
- UN-certified retesting technician scarcity:DOT-mandated inspection intervals require specialized certification that training pipelines are not replenishing at replacement rates.
- Legacy ERP integration:RFID tracking data streams from automated wash lines are forcing reconditioners to reconfigure inventory management systems for real-time container lifecycle visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconditioned IBC Market |
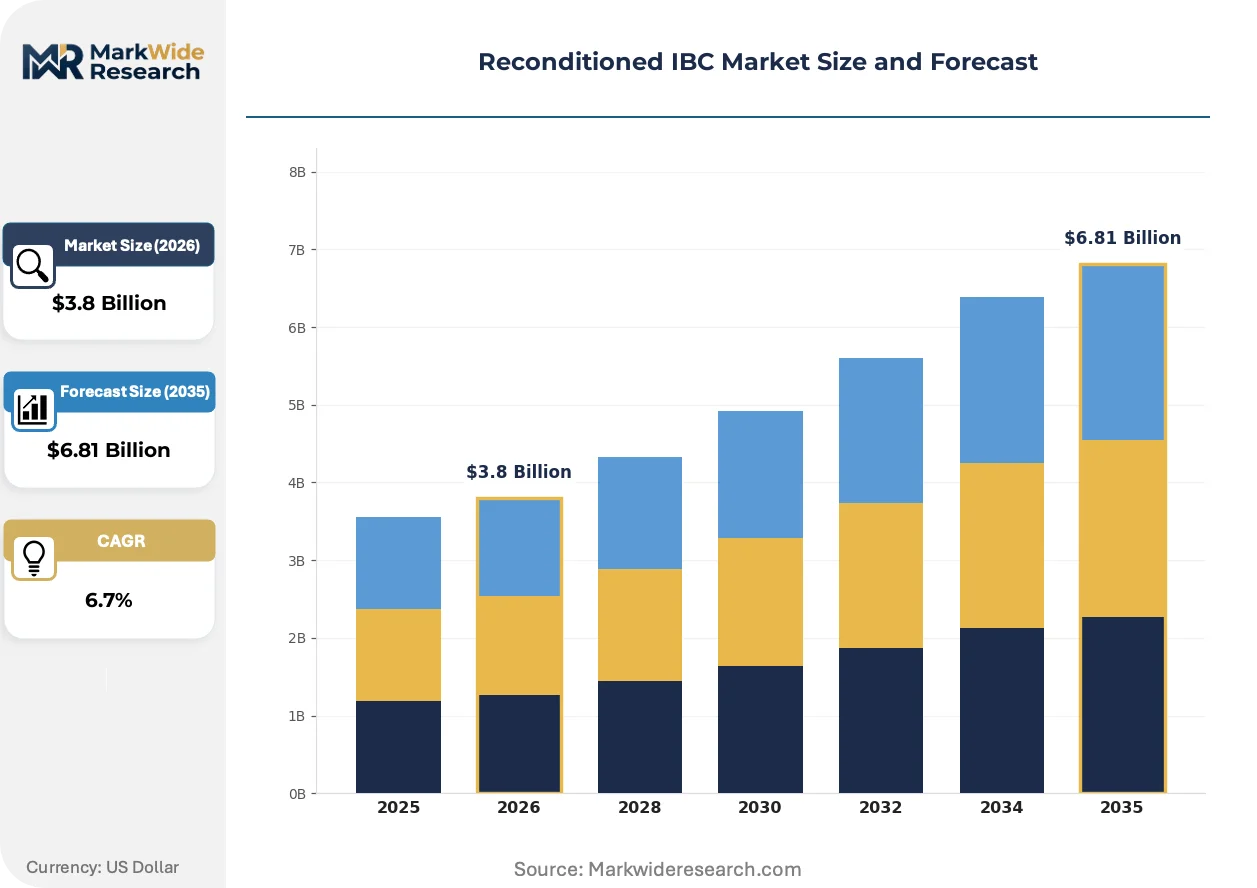
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic IBC, Metal IBC, Composite IBC, Flexible IBC End User: Chemicals, Food & Beverage, Pharmaceuticals, Agriculture Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Capacity: 1000 Liters, 600 Liters, 400 Liters, 200 Liters |
| Companies Covered | American Surplus, Inc., MH Containers & Equipment Co., Inc., TranPak Inc., Container Exchanger, McManus Drum Co. Inc., Snyder Industries, Inc., National Tank Outlet, Coastal Container Services, BWAY Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconditioned IBC Market Strategic Shifts
Digital tracking infrastructure is fusing with automated cleaning hardware to transform reconditioning from a commodity service into a data-enriched logistics function. This convergence is compressing asset turnaround times while generating compliance documentation streams that chemical buyers now require as standard procurement terms.
RFID-integrated wash systems are embedding transponder tags during the reconditioning sequence to create immutable container history records. Chemical processors in the US and Germany are mandating this traceability layer for hazardous material shipments. The technology is virtualizing compliance documentation from paper-based certificate exchange toward automated regulatory filing.
REACH authorization requirements for chemical substances are tightening documentation burdens on packaging reuse cycles. Industrial consequence includes mandatory residue testing protocols that extend reconditioning facility certification timelines. Food-grade bulk liquid shippers in Europe are responding by accelerating adoption of dedicated-use container pools with segregated cleaning lines.
Long-term service contracting is displacing spot-market container procurement among integrated chemical producers. Multi-year agreements with guaranteed availability terms are replacing transactional distributor purchases. This pattern is most visible across the US Gulf Coast petrochemical corridor where supply security concerns outweigh price optimization in procurement criteria.
Reconditioned IBC Market Segmentation
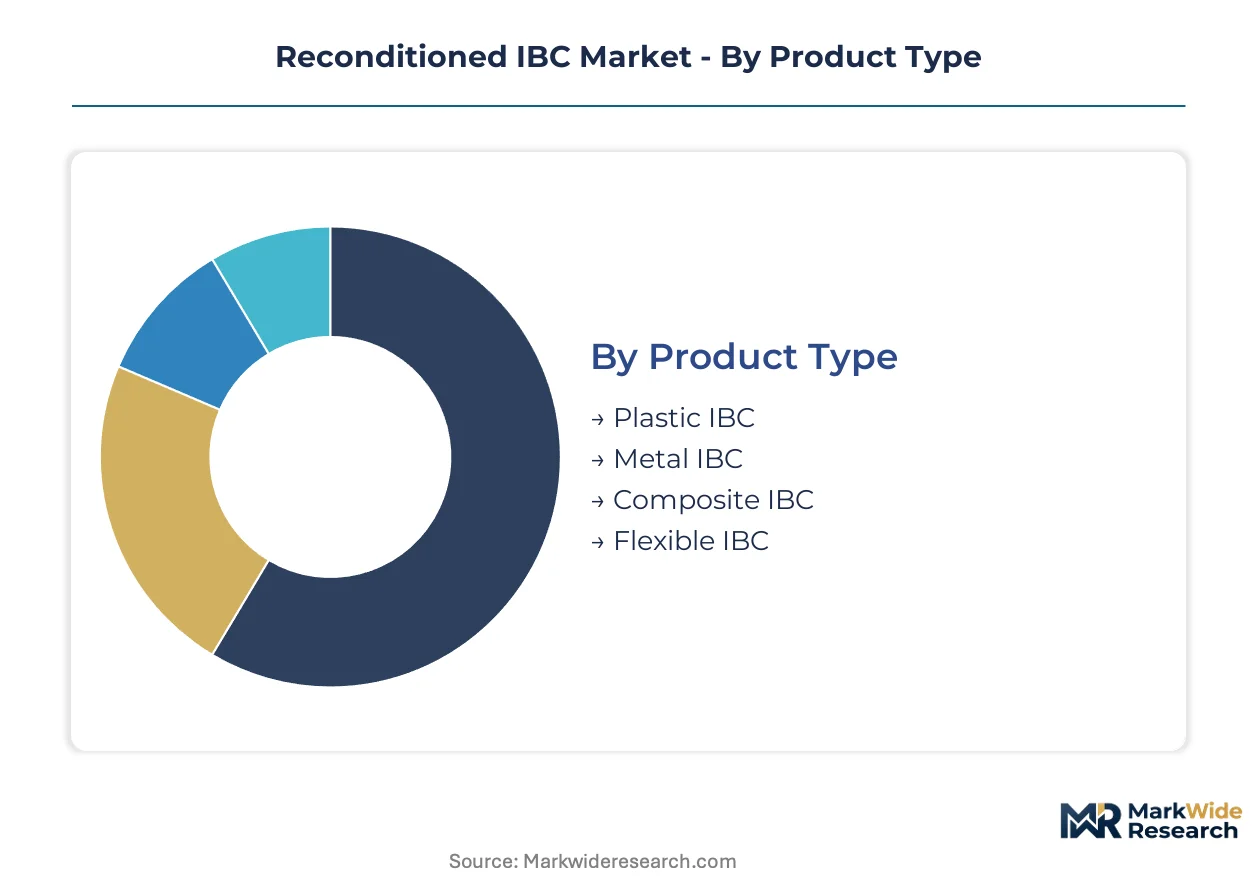
Reconditioned IBC procurement patterns diverge sharply across material composition, end-use chemistry, and channel economics. Segmentation reveals where automated cleaning investments concentrate and which buyer categories are migrating from spot purchases toward multi-year service contracts.
Product Type:
Material composition determines reconditioning energy intensity, chemical compatibility breadth, and residual value recovery rates across the installed base.
- Plastic IBC:High-density polyethylene construction enables lower-temperature wash cycles that reduce energy costs per reconditioning sequence. Chemical processors across the US Gulf Coast corridor favor plastic IBC for broad-spectrum solvent compatibility, though REACH authorization requirements are tightening residue documentation burdens for cross-border shipments.
- Metal IBC: Stainless steel vessels command premium positioning in high-temperature and solvent-intensive applications where polyethylene degrades. Nickel price volatility directly compresses reconditioning margins for metal IBC operators serving specialty chemical producers in Germany.
- Composite IBC: Hybrid construction layers steel caging with plastic liners to balance structural integrity against chemical resistance. Food-grade bulk liquid shippers in China are testing composite designs under evolving GB standards for hazardous material transport.
- Flexible IBC: Collapsible woven polypropylene containers minimize return logistics costs for agricultural distributors operating seasonal collection networks.
Plastic IBC holds installed capacity. Flexible IBC is rotating up the share rankings.
End User:
Application chemistry dictates cleaning protocol stringency, certification documentation depth, and contract structure preferences across buyer categories.
- Chemicals:Petrochemical processors and specialty chemical manufacturers generate the highest volume flows through reconditioning networks. UN-certified retesting intervals mandated by DOT shape procurement terms, with integrated producers along the US Gulf Coast corridor locking in multi-year availability guarantees.
- Food & Beverage: Bulk liquid shippers demand segregated cleaning lines and dedicated-use container pools to prevent cross-contamination. European food-grade operators are accelerating adoption of closed-loop pooling programs as REACH residue testing protocols extend facility certification timelines.
- Pharmaceuticals: Stringent cleaning validation requirements per OSHA mandates elevate capital barriers for reconditioners serving this segment. Container history documentation via RFID tracking is becoming standard procurement terms for hazardous pharmaceutical ingredient shipments.
- Agriculture: Fertilizer and crop protection chemical distributors favor flexible IBC formats with seasonal return logistics. Closed-loop pooling penetration remains underdeveloped relative to chemical sector adoption rates, presenting contract growth potential.
Chemicals anchors volume demand. Food & Beverage is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, geographic concentration, and preference for transactional flexibility versus supply security guarantees.
- Direct Sales:Multi-year service contracts with integrated chemical producers capture the largest margin pools through guaranteed availability terms. Direct relationships enable real-time RFID data integration into buyer ERP systems for container lifecycle visibility.
- Distributors: Regional inventory positioning serves small and mid-sized agricultural buyers with fragmented demand patterns. Distributor networks retain volume leadership among buyers lacking scale to justify dedicated fleet investments.
- Online Sales: Digital marketplaces extend geographic reach beyond traditional distributor territories by matching empty container supply with regional demand clusters. Container Exchanger operates this channel for spot-market procurement.
- Retail: Limited penetration for reconditioned IBC due to certification complexity and buyer risk tolerance thresholds; primarily serves small-volume maintenance chemical purchases.
Direct Sales commands margin concentration. Online Sales is gaining share fastest.
Capacity:
Volume specification aligns with transport economics, handling equipment standardization, and end-use consumption rates across industrial supply chains.
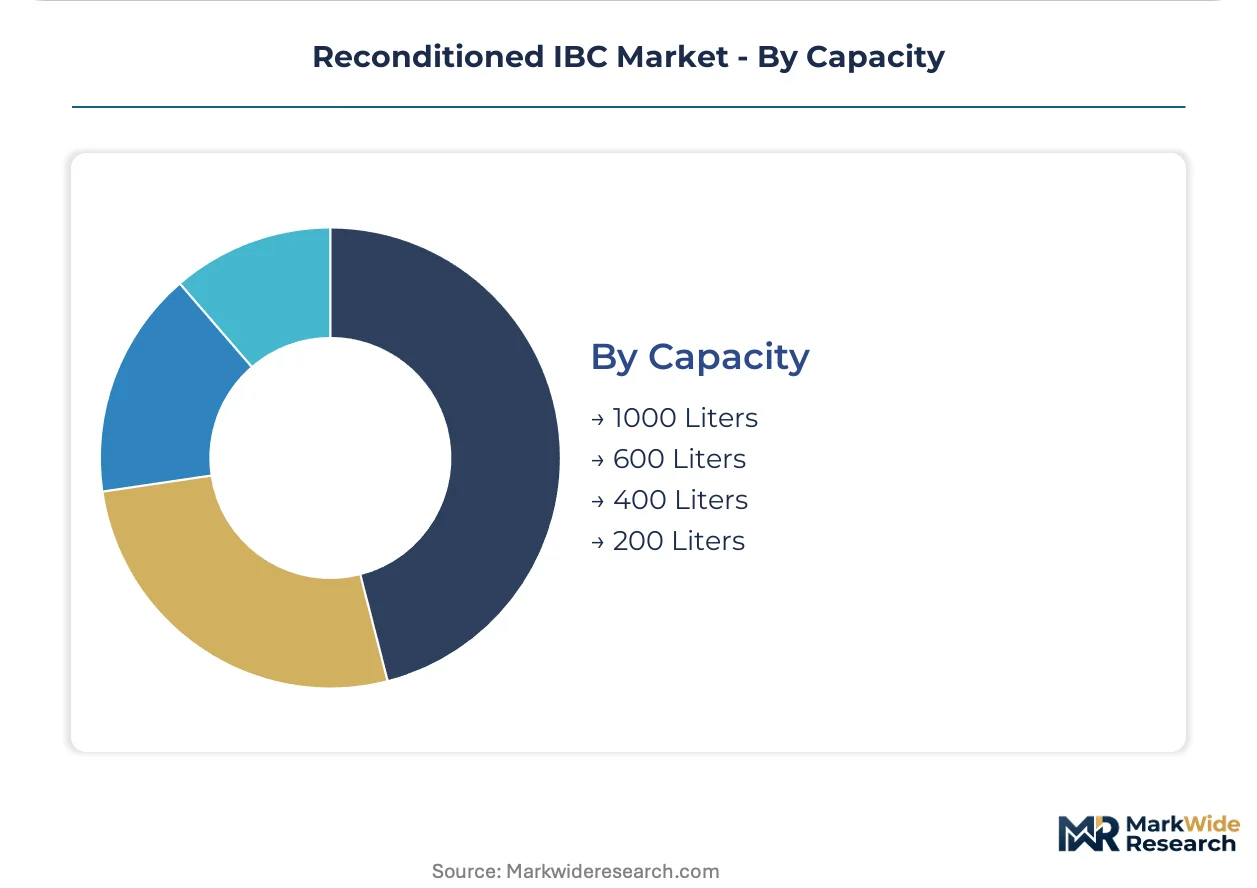
- 1000 Liters:The standard capacity for chemical bulk liquid transport optimizes pallet cube utilization and forklift handling efficiency. Chemical end users in the US and Germany concentrate absolute unit demand at this specification.
- 600 Liters: Intermediate capacity serves pharmaceutical batch processes and specialty chemical production runs with scaled-down throughput requirements. German chemical processors are expanding procurement of this format for flexible manufacturing lines.
- 400 Liters: Reduced volume supports agricultural chemical packaging where seasonal demand fluctuations favor smaller lot sizes. Chinese agricultural distributors are testing 400-liter flexible IBC formats under GB standards evolution.
- 200 Liters: Mini-bulk format aligns with food-grade ingredient shipments and limited-space storage constraints. European food processors are adopting 200-liter dedicated-use pools with segregated cleaning infrastructure.
1000 Liters dominates installed base. 600 Liters is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in reconditioned IBC trade, exporting certified containers to Latin American chemical processors while importing specialty metal IBC from German fabricators. Germany and China represent the other two poles of this triangular flow, each with distinct regulatory drivers shaping domestic reconditioning capacity.
United States
Petrochemical processors along the US Gulf Coast corridor drive concentrated demand for plastic IBC reconditioning, with cluster density reducing empty container collection logistics costs below economic thresholds elsewhere. EPA RCRA hazardous waste protocols govern facility permitting, while DOT enforces UN-certified retesting intervals that determine container eligibility for continued chemical transport. Houston and Corpus Christi anchor the highest reconditioning throughput volumes, where integrated producers lock in multi-year service contracts with guaranteed availability terms.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr and Bavarian industrial belts generate premium demand for stainless steel IBC reconditioning, where REACH authorization requirements tighten documentation burdens on packaging reuse cycles. ECHA oversight extends facility certification timelines through mandatory residue testing protocols. Ludwigshafen and Leverkusen concentrate metal IBC reconditioning capacity serving solvent-intensive applications where polyethylene degrades.
China
Agricultural chemical distributors in the Yangtze River Delta and Shandong Peninsula are expanding procurement of flexible IBC formats with seasonal return logistics. GB standards for hazardous material transport elevate reconditioning requirements that domestic suppliers currently underserve. Qingdao and Ningbo testing facilities are upgrading to UN-certified protocols to capture demand from chemical exporters facing EU Packaging and Packaging Waste Regulation compliance.
India
Fertilizer and crop protection chemical distributors in Gujarat and Maharashtra favor 400-liter flexible IBC formats for fragmented rural delivery networks. BIS standards for industrial packaging safety shape domestic reconditioning facility investments, though enforcement remains uneven across state jurisdictions. Ahmedabad and Mumbai chemical corridors are attracting pooled container service providers seeking to replicate US closed-loop contracting models.
Reconditioned IBC Market Competitive Environment
On the supply side, the industry is consolidating toward operators with captive refurbishment networks and automated wash infrastructure. Mid-sized regional reconditioners face capital barriers from OSHA cleaning validation mandates that favor continuous-flow automated lines over manual cleaning bays. Three archetypes dominate: rotational molding specialists controlling captive networks, closed-loop pooling program operators, and digital marketplace platforms extending geographic reach. Competitive moves center on backward integration into container manufacturing and technology licensing for RFID-integrated tracking systems.
Among North American operators, Snyder Industries, Inc. and TranPak Inc. exemplify divergent strategic positions. Snyder anchors the captive network archetype through rotational molding expertise applied to refurbishment operations. TranPak occupies the closed-loop pooling tier with long-term agricultural distributor contracts. Container Exchanger represents the digital marketplace vector, matching empty container supply with regional demand clusters beyond traditional distributor territories. McManus Drum Co. Inc. and BWAY Corporation sit within the diversified industrial packaging segment, where reconditioned IBC complements broader container service portfolios.
| Leading Market Players |
|---|
| American Surplus, Inc. |
| MH Containers & Equipment Co., Inc. |
| TranPak Inc. |
| Container Exchanger |
| McManus Drum Co. Inc. |
| Snyder Industries, Inc. |
| National Tank Outlet |
| Coastal Container Services |
| BWAY Corporation |
| Others |
Value Chain & Pricing Dynamics
Houston anchors the densest reconditioning capacity corridor in North America, where cluster economics compress collection logistics costs and amplify pricing power for operators serving integrated petrochemical buyers. Automated wash infrastructure investments at Gulf Coast facilities are creating tiered service differentiation that separates multi-year contract holders from spot-market purchasers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where multi-year service agreements with guaranteed availability terms command premium positioning over transactional spot purchases. Price differentiation centers on UN certification grade and RFID traceability integration, with food-grade segregated cleaning lines extracting additional margin. Cost compression in standard plastic IBC reconditioning is intensifying because manual cleaning bay operators face OSHA-mandated facility upgrade requirements. Small and mid-sized agricultural distributors exhibit highest price sensitivity, while integrated chemical producers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Rotational molding specialists Snyder Industries and captive network operators hold concentrated refurbishment capacity across the US Gulf Coast and German Rhine-Ruhr industrial belts. Geographic supply concentration centers on the United States, Germany, and China, where evolving GB standards and REACH authorization requirements are elevating certification complexity. Raw material dependencies rest on high-density polyethylene resin, stainless steel feedstock, and woven polypropylene for flexible formats. Single-source vulnerability runs through UN-certified retesting technician pipelines that training institutions are not replenishing at replacement rates. Distribution runs through direct sales channels for integrated chemical producers and regional distributor networks for fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use flexible IBC substitution represents the immediate threat that incumbent reconditioners must navigate through certification complexity reduction and closed-loop pooling penetration.
For Market Incumbents: Insulate market position by deepening backward integration into rotational molding capacity and accelerating RFID-integrated wash system deployment to capture multi-year chemical processor contracts. Counter single-use flexible IBC substitution by simplifying food-grade certification pathways for agricultural distributors. Geographic capacity addition in China's Yangtze River Delta addresses underserviced GB standards demand. For New Entrants and Emerging Players: Mid-market agricultural distributors in India and Southeast Asia represent the most penetrable entry point where closed-loop pooling penetration lags chemical sector adoption rates. Digital marketplace infrastructure for spot-market container matching offers lower capital barriers than automated wash facility investment. Target seasonal return logistics optimization as the initial go-to-market angle for flexible IBC formats. For Investors and Strategic Acquirers: Long-term, this sits as a circular infrastructure play because regulatory reuse mandates across the EU and China are structurally expanding addressable demand beyond organic industrial growth. Acquisition targets should prioritize operators with captive refurbishment networks and UN-certified technician training pipelines. Monitor nickel price volatility and state-level extended producer responsibility legislation adoption as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rotational Molding | Snyder Industries leverages captive HDPE production to control refurbishment network margins across North American chemical corridors. |
| RFID-Integrated Wash System Deployment | Automated cleaning with embedded transponder tags generates real-time compliance documentation that EU REACH authorization now mandates. |
| Closed-Loop Pooling Program Expansion | TranPak's agricultural distributor contracts demonstrate underpenetrated white-space relative to chemical sector penetration rates. |
| Digital Marketplace Channel Development | Container Exchanger's spot-market matching platform extends geographic reach beyond traditional distributor inventory positioning. |
| UN-Certified Technician Training Pipeline | DOT-mandated retesting intervals face scarcity risk as certification programs fail to replenish technician replacement rates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with reconditioning facility managers, chemical processor procurement leads, agricultural distributor logistics heads, and regulatory compliance officers at UN-certified testing facilities. Secondary validation drew from EPA RCRA facility permitting databases, DOT hazmat transportation filings, EU Packaging and Packaging Waste Regulation implementation guidance, customs trade data for IBC container flows, and SEC 10-K disclosures from diversified industrial packaging operators. Bottom-up triangulation across facility throughput estimates and top-down reconciliation against end-use chemical production volumes ensured cross-verified demand quantification.
Calibration against historical capacity utilization rates and documented reconditioning cycle times anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition tier, end-use application chemistry, distribution channel structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated nickel price volatility indices for metal IBC margins and petrochemical cluster density metrics for logistics cost modeling.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, energy costs for automated wash operations, or trade policy affecting cross-border container flows would shift the trajectory. Quarterly review of UN certification audit backlogs, state-level extended producer responsibility legislation adoption, and agricultural chemical shipment seasonality patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Foldable Large Containers Market
Containers
Soup Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Takeaway Containers Market
Containers
Wooden Barrels Market
Containers
In-Mold Labelled Containers Market
Containers
Grab and Go Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Screw Top Pails Market
Containers
Stack and Nest Containers Market
Containers
Americas Container Technology Market
Containers
EMEA Container Technology Market
Containers
Sandwich Containers Market
Containers
Snap-Lock Container Market
Containers
Water Resistant Packing Cubes Market
Containers
Vials Market