
 Rigid Sleeve Boxes Market | 2026-2036
Rigid Sleeve Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Sleeve Boxes Market Outlook
Paperboard is expanding its share in rigid sleeve construction as brands abandon heavier chipboard to cut freight costs and satisfy retailer sustainability scorecards. WestRock Company leverages its integrated pulp-to-box network across the southeastern United States to secure cost-advantaged supply for cosmetics clients. DS Smith Plc anchors European demand through its recycled-content specialization and closed-loop partnerships with luxury houses in France and Italy. Bleubird Packaging competes on short-run customization velocity, serving direct-to-consumer beauty brands that refresh packaging seasonally.
A rigid sleeve box consists of a separate outer sleeve that slides over an inner tray or base, typically manufactured from paperboard between 18 and 24 points, with structural rigidity achieved through SBS (solid bleached sulfate) or CCNB (clay-coated news back) substrates and optional film lamination for scuff resistance. The design enables premium unboxing experiences while permitting efficient flat storage and assembly. Paperboard leads by volume across the material type dimension, though polypropylene sustains growth in electronics applications where moisture barrier properties outweigh recyclability premiums. The e-commerce end user segment represents the fastest-expanding demand pool, driven by influencer-driven unboxing content that converts packaging into shareable brand assets. Magnetic closure types command the strongest margin pools, as hidden neodymium inserts justify price premiums in the luxury design category.
The EU Packaging and Packaging Waste Regulation and California's SB 54 extended producer responsibility framework are reshaping substrate selection, with both mandating minimum recycled content thresholds and standardized recyclability labeling. The US Federal Trade Commission's Green Guides constrain environmental marketing claims, forcing converters to substantiate biodegradability assertions with third-party certification. Stakeholders must monitor evolving state-level packaging EPR bills and assess whether regional compliance investments outweigh centralized production economies.
Market Dynamics
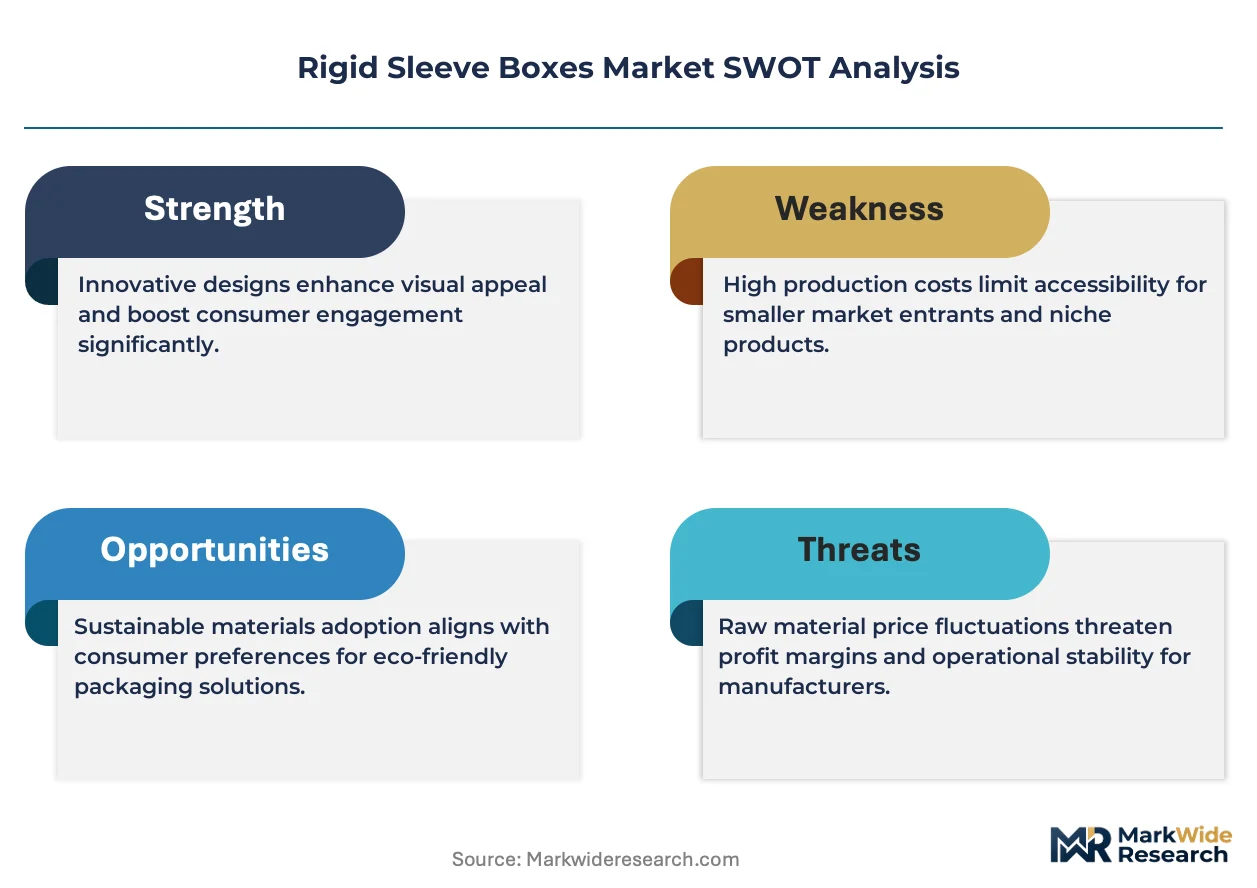
The EU Packaging and Packaging Waste Regulation is compressing substrate choice timelines, forcing converters to abandon virgin chipboard for recycled-content paperboard ahead of 2030 material recovery targets.
Growth Catalysts
- California SB 54 EPR framework:Extended producer responsibility mandates in California's beauty cluster accelerate premium rigid sleeve adoption as brands redesign packaging for recyclability scorecards.
- E-commerce unboxing content:Influencer-driven social media is expanding into a primary demand driver, converting packaging into shareable brand assets that justify magnetic closure premiums.
- Germany's Rhine-Ruhr corridor:Concentrated converter capacity and closed-loop partnerships with French and Italian luxury houses anchor European supply security.
Market Restraints
- Pulp input volatility:Solid bleached sulfate paperboard pricing fluctuates with Nordic pulp contract settlements, compressing converter margins on fixed-price annual contracts.
- Neodymium supply concentration:Hidden magnetic closure inserts depend on rare earth processing concentrated in China's Sichuan and Inner Mongolia refining complexes.
- Polypropylene substitution in electronics:Moisture barrier requirements in consumer electronics sustain plastic sleeve demand despite paperboard recyclability premiums.
Strategic Opportunities
- Direct-to-consumer seasonal refresh cycles:Short-run customization velocity serves beauty brands that rotate packaging quarterly, bypassing traditional minimum order quantity constraints.
- EU Green Deal circularity incentives:Closed-loop partnerships with luxury houses qualify for green financing subsidies that offset recycled-content paperboard cost premiums.
- Smart packaging convergence:NFC-enabled sleeves integrating digital authentication are expanding into anti-counterfeiting applications for high-value cosmetics.
Industry Challenges
- Recycled-content certification timelines:Third-party verification for biodegradability claims under FTC Green Guides extends new product development cycles by 4-6 months.
- Flat storage automation integration:Sleeve-and-tray designs require specialized pick-and-place robotics that legacy fulfillment centers struggle to retrofit cost-effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Sleeve Boxes Market |
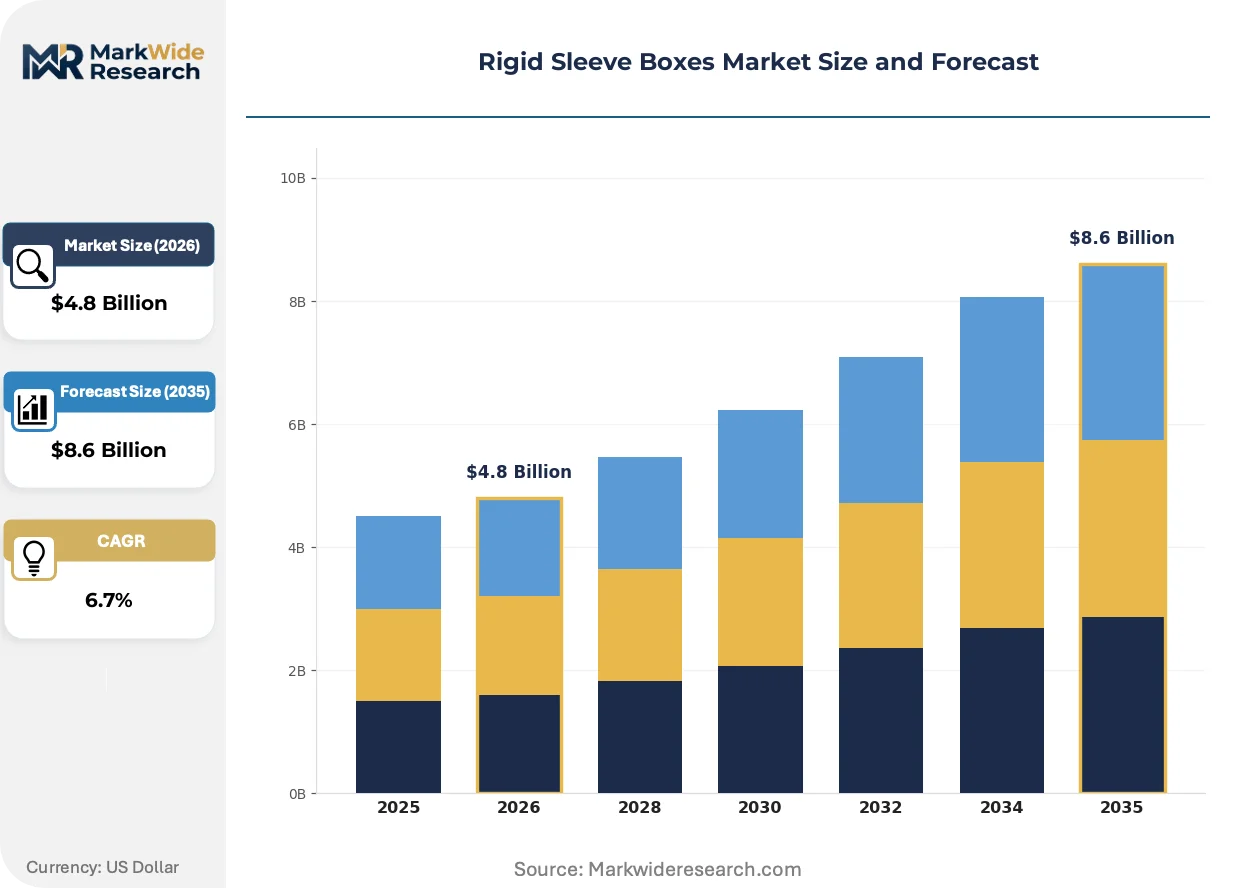
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, PVC, Polypropylene, Chipboard End User: Cosmetics, Electronics, Food & Beverage, E-commerce Design Type: Customized, Standard, Eco-friendly, Luxury Closure Type: Magnetic, Sliding, Tuck-end, Seal |
| Companies Covered | Bleubird Packaging, Pak Factory, BlueBox Packaging, Brimar Packaging, WestRock Company, DS Smith Plc, Emenac Packaging, Packaging Corporation of America, Madovar Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Sleeve Boxes Market Strategic Shifts
Paperboard substrate engineering is displacing legacy materials through weight reduction and surface treatment advances that preserve structural rigidity at lower freight cost.
Water-based barrier coatings are expanding into moisture-sensitive applications previously reserved for film-laminated constructions. Cosmetics brands in Germany and France are adopting these coatings at pilot scale for skincare lines. The technology is expanding into electronics-adjacent segments where moderate humidity protection suffices.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant treatments from food-contact sleeve applications. Converters serving the premium chocolate and confectionery segment must reformulate barrier chemistries by 2025. Italian and Belgian luxury food brands are accelerating qualification of cellulose-based alternatives ahead of enforcement deadlines.
Brand procurement teams now specify unboxing experience metrics alongside unit economics, compressing supplier selection cycles. Direct-to-consumer beauty channels in California and New York demand seasonal design refreshes that displace traditional 12-18 month packaging lifecycles. Influencer content performance in these geographies now determines sleeve specification priorities ahead of retail buyer preferences.
Rigid Sleeve Boxes Market Segmentation
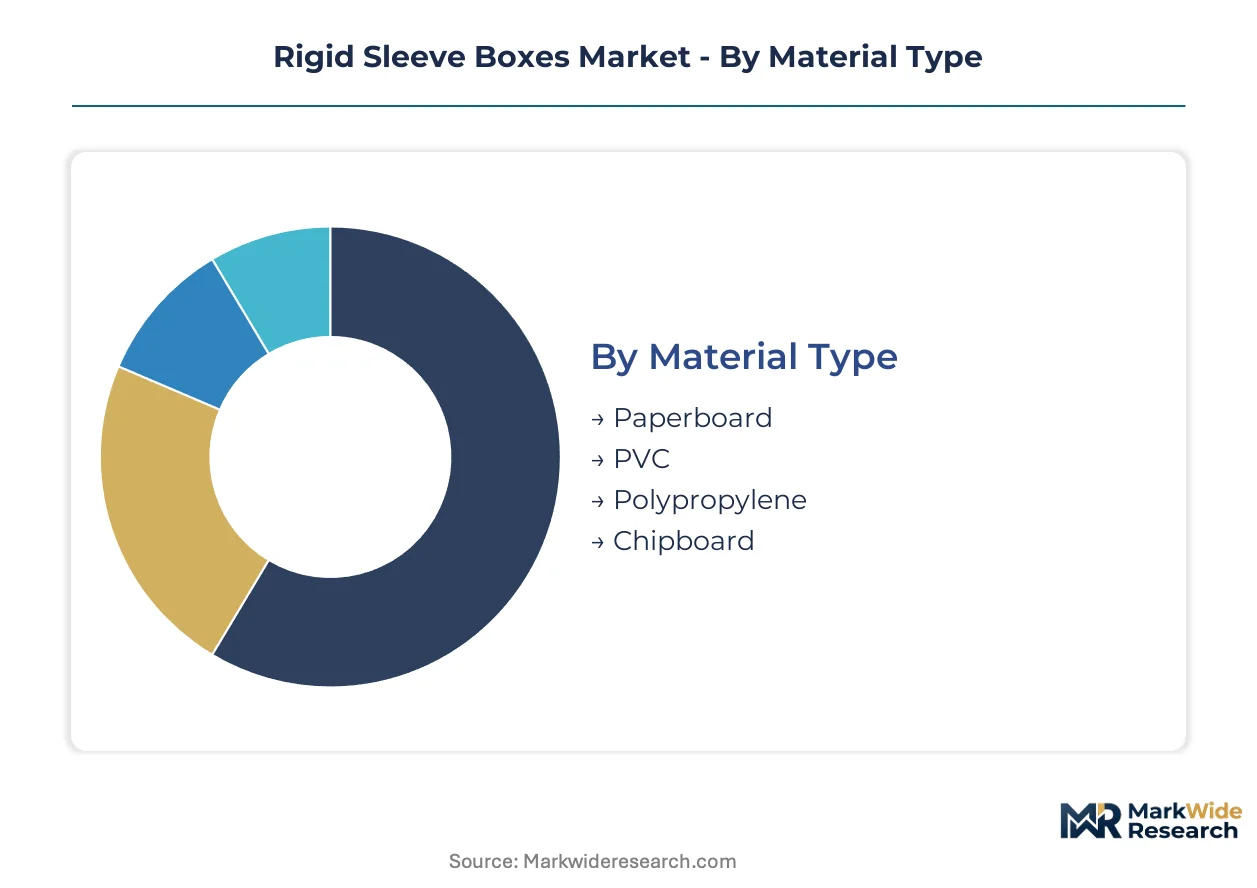
Converters configure rigid sleeve production lines around material caliper, closure mechanics, and brand positioning tiers. Procurement teams in California's beauty cluster and Germany's Rhine-Ruhr corridor now specify unboxing experience metrics alongside unit economics, compressing supplier selection cycles.
Material Type:
Purchasing managers select substrates based on freight cost exposure, retailer sustainability scorecards, and moisture barrier requirements.
- Paperboard:SBS and CCNB substrates between 18-24 points deliver structural rigidity with lower freight cost than legacy chipboard. California cosmetics brands and French luxury houses are accelerating adoption ahead of EU Packaging and Packaging Waste Regulation material recovery targets.
- Polypropylene:Thermoplastic construction provides moisture barrier properties essential for electronics applications where recyclability premiums are outweighed by humidity protection needs. Demand concentrates in consumer electronics clusters where film lamination alternatives fail environmental testing protocols.
- PVC:Rigid vinyl substrates serve specialty pharmaceutical and industrial applications requiring chemical resistance and dimensional stability under temperature fluctuation.
- Chipboard:Heavier recycled-content board persists in economy-tier packaging where freight cost sensitivity is offset by structural load-bearing requirements for dense products.
Volume sits with Paperboard; growth tilts toward Polypropylene in electronics-adjacent segments.
End User:
Demand intensity varies by channel velocity, unboxing content value, and regulatory exposure across product categories.
- Cosmetics:Premium skincare and fragrance brands in France, Italy, and California deploy magnetic closure sleeves as shareable brand assets. Influencer-driven content performance now determines packaging specification priorities ahead of retail buyer preferences.
- E-commerce:Direct-to-consumer channels demand seasonal design refreshes that displace traditional 12-18 month packaging lifecycles. Short-run customization velocity serves beauty brands rotating packaging quarterly.
- Electronics:Moisture barrier requirements sustain plastic sleeve demand despite paperboard recyclability premiums. REACH substance restrictions are eliminating conventional grease-resistant treatments from adjacent food-contact applications.
- Food & Beverage:Premium chocolate and confectionery segments in Italy and Belgium must reformulate barrier chemistries ahead of per- and polyfluoroalkyl substances enforcement deadlines.
Cosmetics commands volume concentration; E-commerce climbs the fastest as unboxing content converts packaging into marketing infrastructure.
Design Type:
Brand positioning tiers determine tooling investment, print complexity, and certification requirements.
- Luxury:Hidden neodymium magnetic inserts and specialty substrates justify price premiums through tactile differentiation and anti-counterfeiting potential. French and Italian houses anchor European demand through closed-loop partnerships qualifying for EU Green Deal circularity subsidies.
- Eco-friendly:Water-based barrier coatings and cellulose-based grease resistance are expanding into moisture-sensitive applications previously reserved for film-laminated constructions. German skincare brands are adopting these coatings at pilot scale.
- Customized:Short-run digital print and rapid die-change capabilities serve direct-to-consumer channels requiring quarterly seasonal refreshes.
- Standard:Catalog configurations with minimal setup time serve volume retailers and economy-tier product lines where unit cost minimization dominates procurement criteria.
Standard designs hold volume share; Eco-friendly specifications are gaining share fastest under tightening EPR frameworks.
Closure Type:
Mechanical differentiation drives margin stratification and automation compatibility in fulfillment operations.
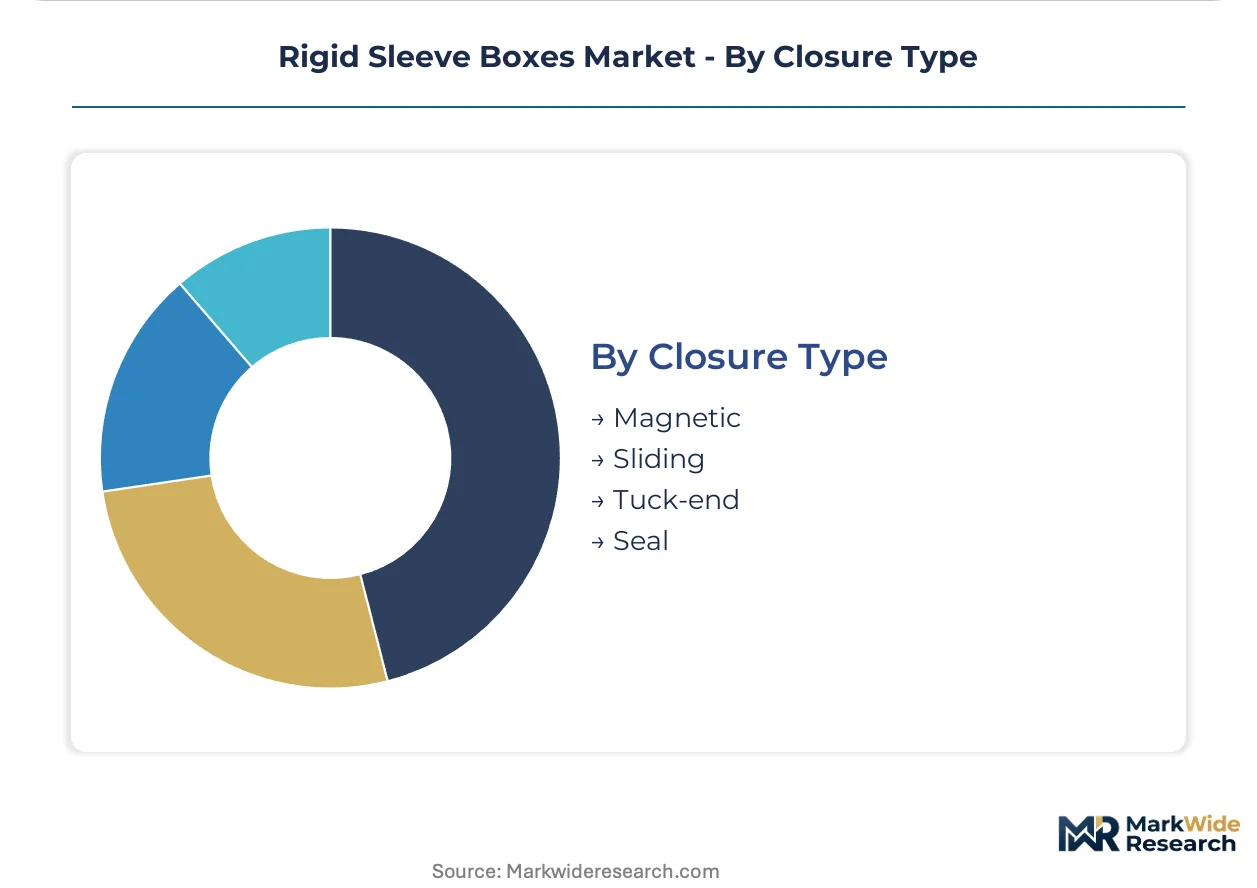
- Magnetic:Hidden neodymium inserts command the strongest margin pools in luxury design categories. Supply concentration in China's Sichuan and Inner Mongolia refining complexes creates procurement risk exposure.
- Sliding:Sleeve-over-tray construction enables premium unboxing experiences while permitting efficient flat storage. Specialized pick-and-place robotics requirements challenge legacy fulfillment center retrofit economics.
- Tuck-end:Friction-fit paperboard tabs serve economy-tier applications where assembly speed and material minimization outweigh experiential premiums.
- Seal:Adhesive or heat-sealed closures provide tamper-evidence for pharmaceutical and high-value consumer goods requiring supply chain integrity verification.
Magnetic closures dominate margin capture; Sliding designs show steepest expansion trajectory as e-commerce fulfillment automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics brands in California and France concentrate premium rigid sleeve demand through influencer-driven unboxing specifications. E-commerce fulfillment networks in Germany and China are retrofitting automation for sleeve-and-tray configurations. Regulatory tightening across these markets is compressing substrate selection timelines ahead of 2030 compliance deadlines.
United States
California's beauty cluster drives magnetic closure adoption as shareable brand assets. The FTC Green Guides constrain environmental marketing claims, forcing third-party biodegradability certification. Los Angeles and New York Metro direct-to-consumer brands rotate packaging quarterly, bypassing traditional minimum order quantities.
Germany
Rhine-Ruhr packaging corridor anchors European converter capacity for luxury houses. The EU Packaging and Packaging Waste Regulation mandates recycled-content thresholds by 2030. Düsseldorf and Cologne facilities specialize in closed-loop partnerships qualifying for EU Green Deal circularity subsidies.
France
Paris-based luxury cosmetics houses specify unboxing experience metrics alongside unit economics. REACH substance restrictions eliminate per- and polyfluoroalkyl substances from food-contact applications by 2025. Lyon and Marseille converters pilot water-based barrier coatings for skincare lines.
China
Sichuan and Inner Mongolia refining complexes concentrate neodymium supply for magnetic closure inserts. The country's dual carbon goals push converters toward lighter paperboard substrates. Shenzhen electronics clusters sustain polypropylene sleeve demand for moisture barrier applications.
Italy
Milan and Turin luxury food brands accelerate cellulose-based grease resistance qualification ahead of enforcement deadlines. The EU Green Deal incentivizes recycled-content paperboard through green financing subsidies. Bologna converters serve premium chocolate segment seasonal packaging refreshes.
Rigid Sleeve Boxes Market Competitive Environment
Capacity expansion dominates the current landscape as converters retrofit lines for water-based barrier coatings and recycled-content substrates. The vendor base separates into three tiers: integrated pulp-to-box networks securing cost-advantaged supply, recycled-content specialists with closed-loop partnerships, and short-run customization shops serving seasonal refresh cycles. Strategic archetypes include scale-driven integrated producers, sustainability-certified regional players, and velocity-focused digital print shops. M&A activity concentrates on automation technology acquisitions, while geographic expansion targets California and Germany's regulatory-compliant demand clusters.
Among North American integrated producers, WestRock Company exemplifies the pulp-to-box archetype through southeastern United States network control. DS Smith Plc anchors European positioning through recycled-content specialization. Bleubird Packaging occupies the short-run velocity tier, serving direct-to-consumer beauty brands with rapid seasonal turnaround requirements.
| Leading Market Players |
|---|
| Bleubird Packaging |
| Pak Factory |
| BlueBox Packaging |
| Brimar Packaging |
| WestRock Company |
| DS Smith Plc |
| Emenac Packaging |
| Packaging Corporation of America |
| Madovar Packaging LLC |
| Others |
Value Chain & Pricing Dynamics
Magnetic closure premium tiers diverge sharply from tuck-end economy segments, with neodymium insert costs and water-based coating certifications creating parallel supply chains that serve distinct buyer archetypes. California cosmetics procurement teams prioritize unboxing metrics that justify magnetic premiums, while mass-market distributors in the southeastern United States minimize unit costs through chipboard consolidation.
Pricing Analysis
Volume concentrates in standard tuck-end configurations where freight-optimized paperboard and minimal tooling sustain thin margins, while magnetic closure variants capture margin premiums through hidden neodymium inserts and specialty substrate sourcing. Price differentiation rests on certification grade—FTC Green Guides compliance and EU Packaging and Packaging Waste Regulation alignment command premiums—and customization velocity, with quarterly refresh cycles pricing above annual contracts. Cost compression in SBS paperboard is intensifying because Nordic pulp contract volatility squeezes converter margins on fixed-price agreements. Mass retailers exhibit highest price sensitivity, whereas French and Italian luxury houses accept premiums for closed-loop partnership credentials.
Supply Chain Analysis
Dual-sourcing requirements from California beauty brands and German luxury houses mandate multi-supplier qualification across both Nordic pulp networks and Chinese neodymium refining corridors. Raw material dependencies center on solid bleached sulfate paperboard from Scandinavian mills, neodymium processed in China's Sichuan and Inner Mongolia complexes, and water-based barrier coating chemistries from German specialty chemical producers. Supply chain risk concentrates in single-source vulnerability for rare earth magnetic inserts given geopolitical concentration. Distribution runs through converter-direct relationships for luxury tiers and wholesale packaging distributors serving volume retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as EU recycled-content mandates and FTC certification timelines force sub-scale converters into acquisition or exit. Regulatory compliance investments favor integrated players with captive pulp supply and established third-party verification relationships.
For Market Incumbents: Extend closed-loop partnership coverage into Italian and Belgian luxury food segments ahead of per- and polyfluoroalkyl substances enforcement deadlines. Acquire water-based coating automation capabilities to defend margin position against specialty chemical entrants. Vertical integration into southeastern United States pulp networks secures cost-advantaged SBS supply as Nordic contract volatility intensifies.
For New Entrants and Emerging Players: Begin with short-run digital print velocity serving California direct-to-consumer beauty channels that rotate packaging quarterly. Target the eco-friendly design tier where water-based barrier coatings and cellulose-based grease resistance are displacing film-laminated incumbents. Position around rapid die-change capabilities and seasonal refresh expertise rather than scale economics.
For Investors and Strategic Acquirers: Re-rating potential sits with recycled-content specialists possessing EU Green Deal circularity subsidies and established French luxury house relationships given tightening material recovery targets. Long-term viability favors converters with backward integration into pulp supply and automation technology for sleeve-and-tray fulfillment. Watch for inflection in California SB 54 enforcement intensity as the signal for accelerated premium rigid sleeve adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Scale-Up | Qualification of moisture barrier chemistries displaces film lamination in German skincare packaging. |
| Neodymium Supply Diversification | Dual-sourcing magnetic inserts reduces concentration risk in China's Sichuan refining corridor. |
| Closed-Loop Partnership Expansion | EU Green Deal subsidies offset recycled-content paperboard premiums for French luxury houses. |
| Short-Run Automation Investment | Pick-and-place robotics for sleeve-and-tray configurations serves California quarterly refresh cycles. |
| Recycled-Content Certification | Third-party verification under FTC Green Guides compresses new product development timelines. |
Study Parameters
Multi-period observation of pulp contract settlements, neodymium pricing indices, and EU regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with packaging procurement managers at California cosmetics brands, converter operations directors in Germany's Rhine-Ruhr corridor, and sustainability compliance officers at French luxury houses. Secondary validation drew from SEC filings of integrated paperboard producers, EU Packaging and Packaging Waste Regulation impact assessments, and Nordic pulp industry trade data. Bottom-up segment sizing triangulated against top-down market value estimates derived from converter capacity and utilization rates.
Input-output matrix framing connected raw material cost drivers—SBS and CCNB substrate pricing, neodymium magnetic insert supply, water-based coating chemical inputs—to finished rigid sleeve pricing across premium, standard, and economy tiers. Segmentation dimensions modeled included material type, closure mechanics, design tier, and end-use channel velocity. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated EU material recovery target implementation schedules and California SB 54 extended producer responsibility framework adoption curves.
Pulp input volatility, neodymium supply disruption, and accelerated EU enforcement timelines are the dominant revision risks that could compress converter margins or accelerate substrate substitution faster than modeled. A model refresh is warranted upon material change in Nordic pulp contract settlement patterns or California regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market