
 Global Squash Drinks Market | 2026-2036
Global Squash Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Squash Drinks Market Intelligence
FSSC 22000 certification is unwinding the established supplier base, forcing greater transparency in ingredient sourcing. Britvic PLC leverages its long-standing brand presence in the United Kingdom to maintain market share. The Coca-Cola Company extends its powerful distribution channels to introduce localized squash flavors in new markets. Meanwhile, Unilever PLC differentiates through its focus on herbal-infused and wellness-oriented concentrate products.
Squash drinks are concentrated non-alcoholic syrups, primarily composed of fruit juice, water, and sweetening agents. These formulations are designed for dilution before consumption and are often characterized by their high fruit-to-water concentrate ratio. The market's product evolution shows a clear shift towards sugar-free and vitamin-enriched variants, driven by health-conscious consumerism. In packaging, a transition from traditional plastic bottles to cartons and reusable containers is notable, reflecting sustainability concerns.
Regulations like the UK's Soft Drinks Industry Levy and the US FDA's rules on added sugar labeling directly impact product development. Concurrently, standards from India's FSSAI and Brazil's ANVISA set strict guidelines on fruit content and approved additives. Navigating the balance between health-driven reformulation, cost management, and established consumer taste preferences remains the central strategic challenge for all producers.
Market Dynamics
The central tension shaping the squash drinks market is the conflict between consumer demand for familiar, sweet taste profiles and escalating regulatory pressure for sugar reduction. This dynamic forces constant reformulation, directly impacting cost structures, ingredient sourcing, and brand positioning across all price tiers.
Growth Catalysts
- Expansion in Fitness and Wellness Centers:The proliferation of gyms and health clubs, particularly in urban areas, creates concentrated points of consumption for vitamin-enriched and low-calorie squash drinks as a post-workout hydration option.
- Demand in High-Growth Economies:In countries like India, the demand for affordable and convenient beverage concentrates is rising, positioning squash as an economical alternative to ready-to-drink juices and carbonated soft drinks.
- Health-Driven Product Fortification:Regulatory encouragement and consumer interest in functional foods support the addition of vitamins and minerals, allowing brands to market their products on a health and wellness platform beyond simple refreshment.
Market Restraints
- Input Cost Volatility:The market is highly susceptible to fluctuations in the price of raw materials, particularly fruit concentrates and sugar, which are subject to agricultural yields, climate events, and global commodity market dynamics.
- Threat from RTD Alternatives:The convenience of ready-to-drink (RTD) beverages, including iced teas, flavored waters, and cold-pressed juices, presents a significant substitution threat, especially among consumers prioritizing portability.
- Inconsistent Global Food Standards:Divergent regulations on additives, preservatives, and minimum fruit content from bodies like the US FDA and India's FSSAI complicate product formulation and export strategies for multinational producers.
Strategic Opportunities
- Herbal and Botanical Infusions:There is a clear opportunity to develop concentrates infused with ingredients like ginger, turmeric, and elderflower, catering to consumer interest in natural remedies and sophisticated, adult-oriented flavor profiles.
- Sustainable Packaging Formats:A transition towards bag-in-box, glass, or recycled PET packaging can appeal to environmentally conscious consumers and create a premium brand image, differentiating products from standard plastic bottles.
- Direct-to-Consumer Channels:Developing online subscription services for concentrates allows brands to build direct relationships with consumers, gather valuable data on flavor preferences, and secure recurring revenue streams.
Industry Challenges
- Stringent Food Safety Compliance:Achieving and maintaining certifications like FSSC 22000 demands significant operational overhead and rigorous supply chain vetting, which can be a barrier for smaller manufacturers and disrupt established supplier networks.
- Reformulation without Taste Compromise:The technical challenge of reducing sugar content using alternative sweeteners while maintaining the expected taste and mouthfeel of traditional squash formulations remains a primary hurdle for product developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Squash Drinks Market |
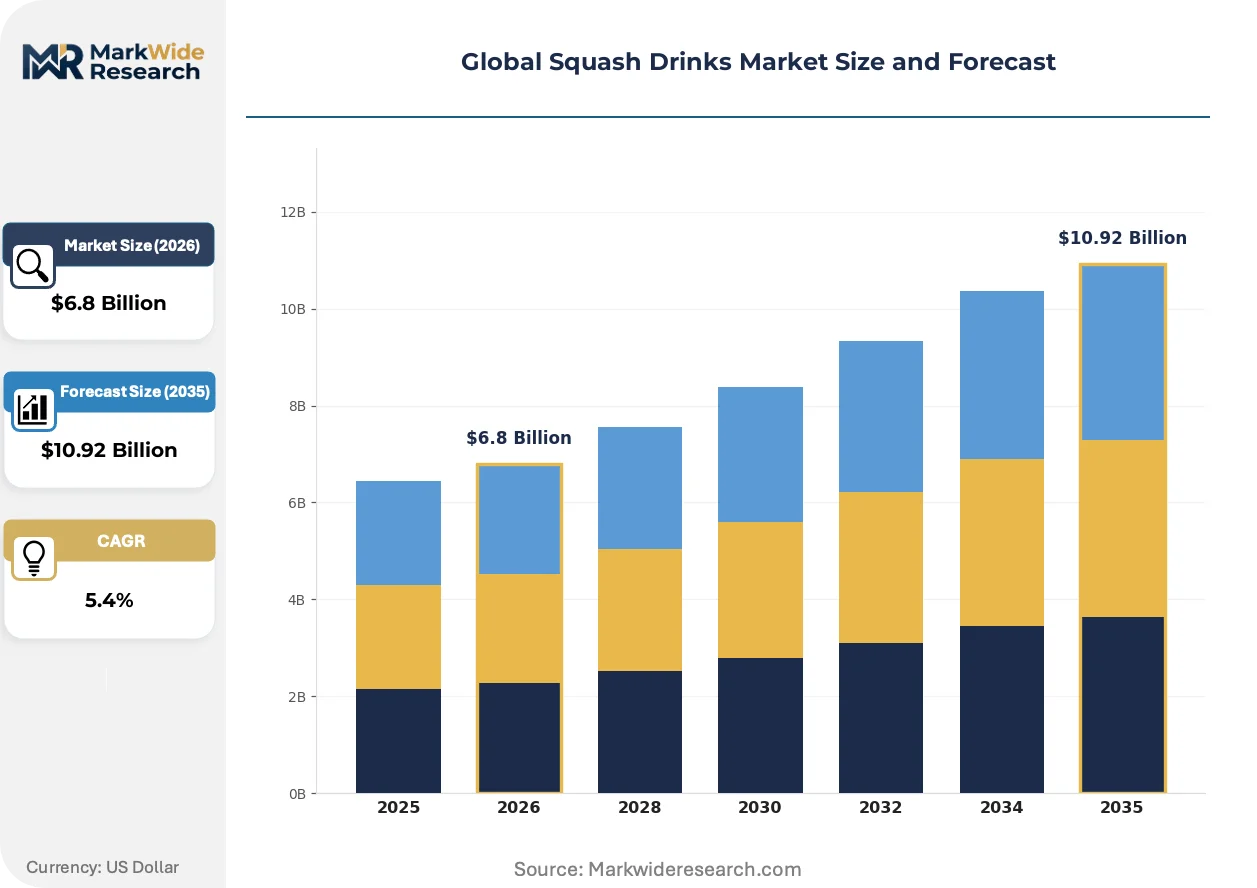
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Herbal Infused, Vitamin Enriched, Sugar-Free, Organic, Energy Boost Packaging Type: Bottle, Carton, Sachet, Can, Reusable Container, Tetra Pak Application: Sports Nutrition, Ready-to-Drink Beverages, Health & Wellness, Hospitality, Food Service Customer Type: Supermarkets, Convenience Stores, Fitness Centers, Corporate Offices, Educational Institutions |
| Companies Covered | Britvic PLC, The Coca-Cola Company, PepsiCo Inc., Unilever PLC, Nichols PLC, Carlsberg Breweries A/S, Harboe's Brewery, Suntory Group, Tovali Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Squash Drinks Market Strategic Shifts & Innovations
Product evolution is defined by a push towards functional ingredients and clean labels, directly responding to health-conscious consumerism. This shift is mirrored by packaging innovations that prioritize sustainability and convenience, moving beyond traditional bulk formats to cater to modern lifestyles and consumption habits.
High-pressure processing (HPP) is a non-thermal pasteurization method that preserves the nutrients, color, and flavor of fruit concentrates more effectively than traditional heat treatments. Premium and health-focused brands are adopting HPP to market their products as fresher and more natural. This technology is fragmenting the concentrate category by creating a distinct, high-margin tier for cold-pressed squashes that appeals to discerning consumers.
Mandatory front-of-pack labeling (FOPL) systems, including Nutri-Score in several European countries and warning labels in Brazil, are directly influencing product design. This regulatory pressure compels manufacturers to lower sugar and sodium levels to avoid poor ratings or explicit warnings on packaging. The segments most affected are traditional, high-sugar fruit squashes, which are undergoing rapid reformulation to align with healthier public-facing metrics.
Consumption patterns are shifting as consumers use squash concentrates in more versatile ways, such as bases for homemade mocktails or as flavor enhancers for sparkling water. This behavior disrupts the product's traditional positioning as a simple children's drink, expanding its use into adult social settings and personalized hydration. This trend is most visible in North American and European markets where at-home mixology and wellness culture are prevalent.
Global Squash Drinks Market Segmentation
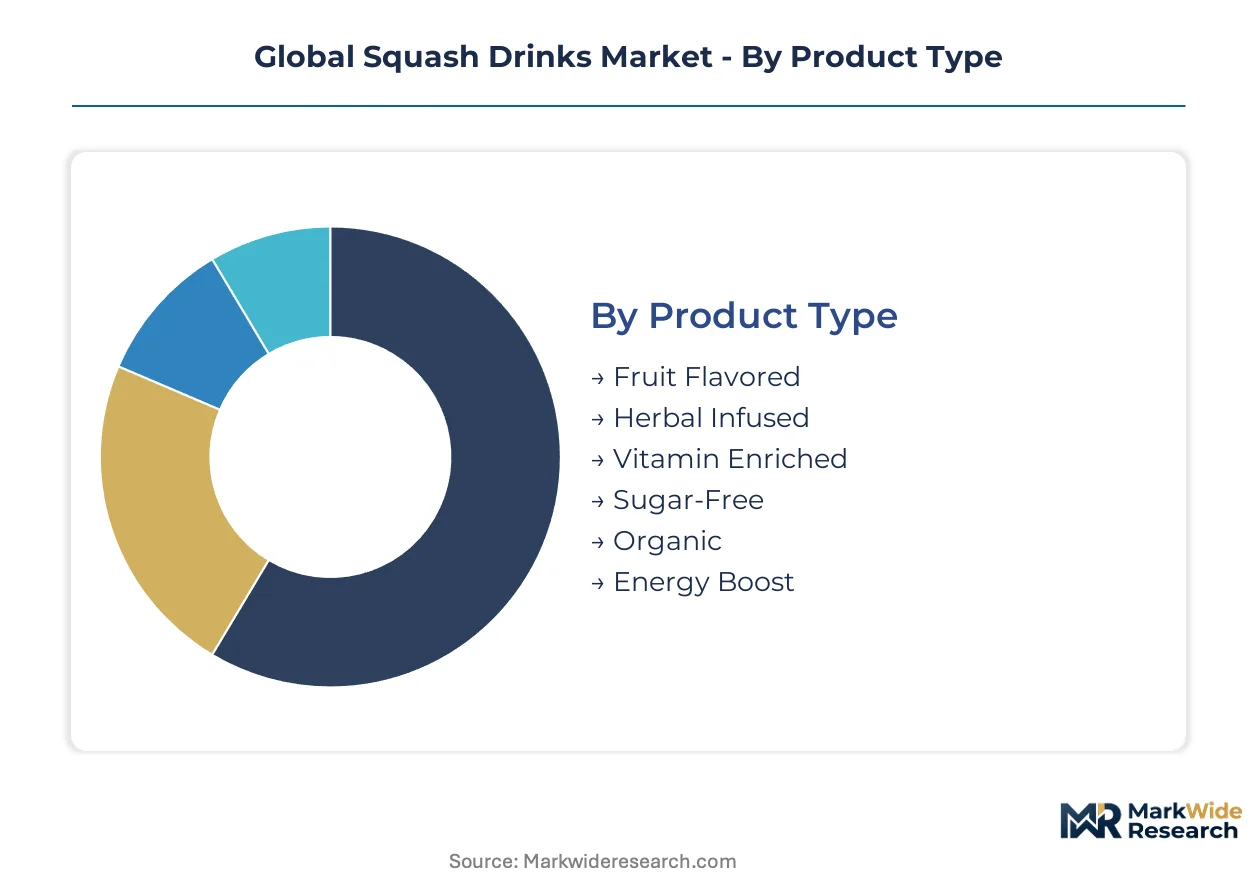
Market segmentation provides a critical framework for understanding varied consumer preferences and operational dynamics within the squash drinks industry. This differentiation allows producers to tailor product development, packaging solutions, and distribution strategies to specific market niches. Analyzing these segments reveals where value concentration occurs and where future growth is most likely to emerge.
Product Type:
Regulatory mandates for healthier food options drive differentiation in product formulations across the global market.
- Sugar-Free:These concentrates utilize artificial sweeteners or natural alternatives to reduce caloric content. Demand for sugar-free options is strong in the United Kingdom due to the Soft Drinks Industry Levy.
- Fruit Flavored:Traditional squash products are primarily composed of fruit juice concentrates and water. These remain popular in India, where affordability and familiar taste profiles are significant purchase drivers.
- Herbal Infused:Products containing natural extracts like ginger or elderflower cater to adult palates.
- Vitamin Enriched:Fortified formulations offer added health benefits, appealing to wellness-focused consumers.
- Organic:These squashes are made from organically certified fruit and ingredients, attracting health-conscious buyers.
- Energy Boost:Formulations include ingredients like B vitamins or guarana for an energizing effect.
Sugar-Free options handle the majority of throughput; Herbal Infused is the fastest mover on share.
Packaging Type:
Packaging choices reflect diverse consumer needs for portability, bulk purchase, and environmental considerations.
- Bottle:Plastic or glass bottles represent the most common packaging format for squash drinks. Convenience stores and supermarkets stock bottles widely for household consumption.
- Reusable Container:These formats, often refillable glass or bag-in-box systems, reduce waste. Environmentally conscious consumers in Europe increasingly favor reusable options.
- Carton:Aseptic cartons offer extended shelf life and are common for multi-serve family packs.
- Sachet:Small, single-serve sachets are popular in high-growth economies for affordability.
- Can:Aluminum cans offer portability and are sometimes used for pre-mixed or single-serve concentrates.
- Tetra Pak:This multi-layered packaging provides protection and is used for various concentrate volumes.
Bottle formats dominate the market volume; Reusable Containers are gaining share most quickly.
Application:
Different consumption scenarios dictate product formulation and marketing approaches for squash drinks.
- Ready-to-Drink Beverages:While primarily concentrates, some squash brands offer pre-diluted, ready-to-drink formats. These cater to immediate consumption needs in urban settings.
- Health & Wellness:Squash drinks fortified with vitamins or natural ingredients target consumers seeking functional benefits. This segment sees significant interest from consumers in North America.
- Sports Nutrition:Concentrates provide quick hydration and electrolyte replenishment for athletes.
- Hospitality:Hotels and restaurants use concentrated syrups for cost-effective beverage service.
- Food Service:Cafeterias and catering companies utilize squash concentrates for bulk drink preparation.
Ready-to-Drink Beverages represent the largest application volume; Health & Wellness applications show the steepest expansion trajectory.
Customer Type:
Distribution channels vary significantly, influencing product visibility and consumer access across different retail environments.
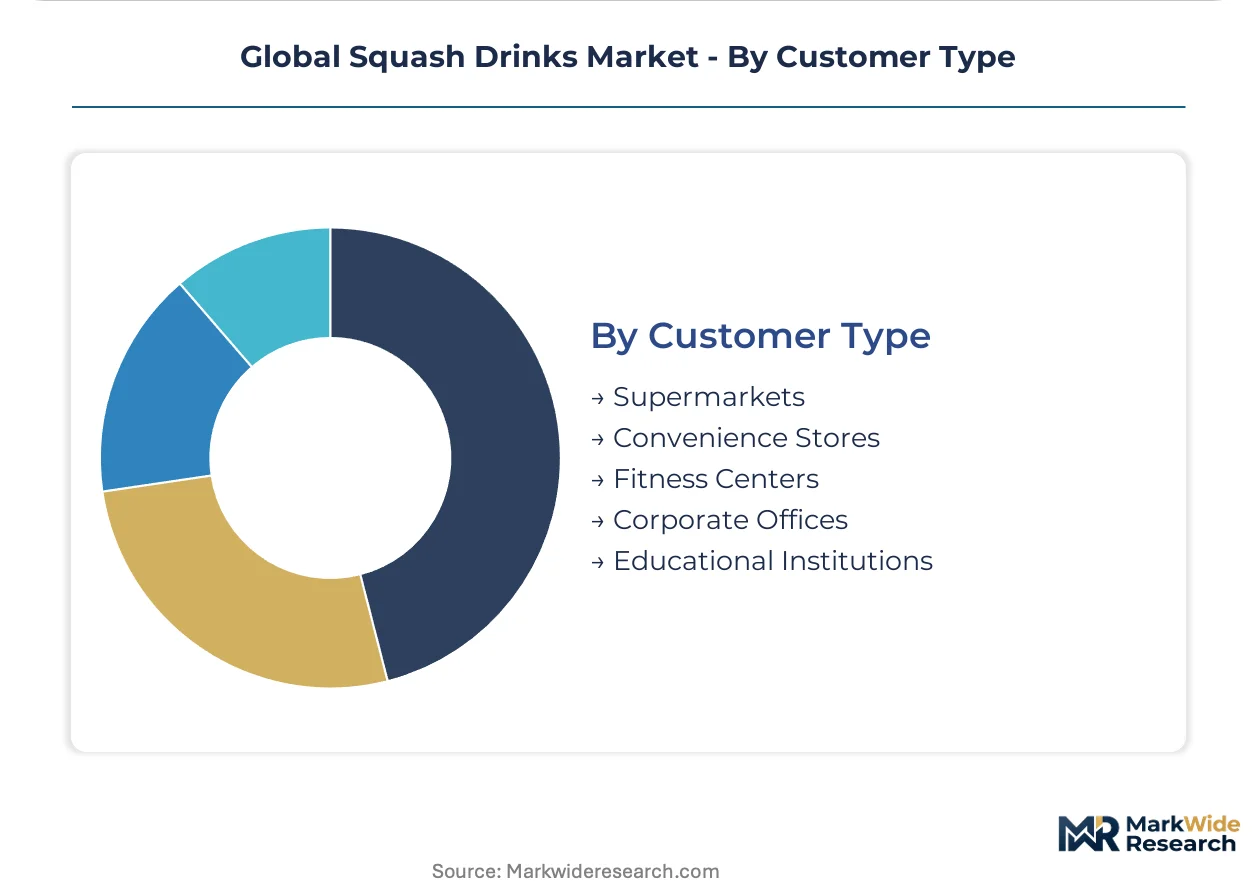
- Supermarkets:Large grocery chains serve as the primary retail channel for household squash purchases. These stores offer a wide selection of brands and product types to mass consumers.
- Fitness Centers:Gyms and health clubs provide a focused consumption point for low-calorie and vitamin-enriched squash. Post-workout hydration drives sales in these specialized environments.
- Convenience Stores:These smaller outlets offer quick purchase options for individual squash bottles or sachets.
- Corporate Offices:Workplaces provide concentrates for employee refreshment and meeting services.
- Educational Institutions:Schools and universities offer squash drinks in cafeterias and vending machines.
Supermarkets account for the majority of sales volume; Fitness Centers are expanding their share rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory mandates for sugar reduction and health-driven product fortification significantly shape the global squash drinks market dynamics. Governments worldwide encourage reformulation efforts through levies and labeling requirements, influencing product development. This regulatory environment drives innovation in healthier and more sustainable beverage options across diverse geographies.
United Kingdom
Demand for sugar-free squash options is particularly robust due to the Soft Drinks Industry Levy. This tax encourages manufacturers to reduce sugar content, directly impacting product formulations. London-based beverage companies actively reformulate their product lines to comply with these health standards.
India
Affordability and convenience drive significant consumption of fruit-flavored squash concentrates in India. The FSSAI sets strict guidelines on fruit content and approved additives, ensuring product quality and safety. Mumbai's burgeoning urban population represents a key market for economical and easily prepared beverage solutions.
Brazil
ANVISA regulations on food additives and fruit content heavily influence product development for squash drinks in Brazil. Consumers increasingly seek healthier options, prompting brands to offer fortified or naturally sweetened variants. São Paulo's beverage industry focuses on adapting traditional flavors to meet evolving health standards and regulatory frameworks.
United States
Health-conscious consumerism and FDA rules on added sugar labeling are reshaping the squash drinks market in the United States. Brands emphasize functional benefits and natural ingredients to attract wellness-focused buyers. New York City's diverse consumer base drives demand for innovative, premium, and vitamin-enriched concentrate products.
Germany
Sustainability concerns are driving a shift towards reusable and eco-friendly packaging formats for squash drinks in Germany. Strict EU regulations on food safety and environmental impact guide manufacturing practices. Berlin's urban consumers demonstrate a strong preference for organic and sustainably packaged beverage concentrates.
Global Squash Drinks Market Key Industry Players
Listed leaders compete with private specialists across distribution scale and product innovation within the global squash drinks market. The market exhibits a tiered structure, with established multinational corporations holding significant brand recognition. Smaller, agile players often focus on niche segments like organic or herbal-infused concentrates. Strategic archetypes include global beverage giants leveraging extensive distribution networks and regional specialists catering to local taste preferences. Companies engage in portfolio diversification and geographic expansion to capture new consumer bases.
Global beverage powerhouses like The Coca-Cola Company and Britvic PLC leverage their extensive brand portfolios and distribution channels to maintain market dominance. These corporations often drive product reformulation in response to regulatory shifts and evolving consumer health trends. Unilever PLC exemplifies a multinational consumer goods conglomerate, focusing on differentiating through wellness-oriented and herbal-infused concentrate products. Such entities occupy a premium position, investing heavily in marketing and sustainable packaging initiatives. Their strategies often involve expanding into high-growth economies and adapting localized flavors to capture new market segments.
| Leading Market Players |
|---|
| Britvic PLC |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Unilever PLC |
| Nichols PLC |
| Carlsberg Breweries A/S |
| Harboe's Brewery |
| Suntory Group |
| Tovali Limited |
| Others |
Cost & Logistics Intelligence
The UK's Soft Drinks Industry Levy directly influences squash drink pricing by mandating sugar reduction, which impacts ingredient costs and formulation. This regulatory pressure simultaneously gates supplier qualification and shapes price differentiation across the market.
Pricing Analysis
FSSC 22000 certification creates the primary spread in squash drink pricing, segmenting the market into premium and standard tiers. Pricing follows a premium-mid-economy differentiation, driven by factors like brand recognition, organic claims, and functional fortifications. Input cost volatility, particularly for fruit concentrates and sugar, exerts significant cost compression across all segments. Consumers in high-growth economies like India exhibit high price sensitivity, while wellness-focused consumers in North America accept higher prices for vitamin-enriched or herbal-infused variants.
Supply Chain Analysis
Just-in-time inventory strategies dominate the squash drinks market, requiring efficient sourcing of key raw materials. The supply chain sources heavily from fruit concentrate producers in Brazil and and India, alongside global sugar markets, creating dependencies on these agricultural commodities. Input cost volatility, stemming from agricultural yields and climate events, represents a primary structural risk for manufacturers. Distribution runs through mass retail channels like supermarkets and convenience stores, with specialized routes emerging for fitness centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The squash drinks market is experiencing a cyclical recovery, primarily driven by renewed consumer focus on health and wellness. This shift is accelerating demand for functional and low-sugar beverage options.
For Market Incumbents: Secure supply chain resilience against input cost volatility by diversifying fruit concentrate sourcing from multiple geographies. Incumbents must also invest in R&D for next-generation natural sweeteners to maintain taste profiles under sugar reduction mandates, thereby countering the threat from RTD alternatives. Expanding localized flavor portfolios in high-growth economies like India will defend market share. Control over distribution channels in fitness centers offers a strategic advantage.
For New Entrants and Emerging Players: Expedited FSSC 22000 certification provides a fast-track for new entrants to establish credibility in the premium squash segment. Target wellness-focused consumers in North America and Europe with innovative herbal-infused or organic concentrate products. A direct-to-consumer subscription model can build brand loyalty and gather valuable preference data. Focus on sustainable packaging formats like reusable containers to differentiate from established players.
For Investors and Strategic Acquirers: Mandatory front-of-pack labeling expansion reshapes the acquisition landscape, favoring companies adept at reformulation and clean-label production. The long-term viability of the squash drinks market rests on health-conscious consumerism and ongoing regulatory pressure for healthier options. Target agile specialists with strong R&D in natural sweeteners, herbal infusions, or sustainable packaging solutions. Monitor the continued adoption rate of high-pressure processing technology among premium brands as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Introduce Herbal-Infused Concentrates | Captures sophisticated adult palates seeking natural, wellness-oriented beverage options. |
| Implement High-Pressure Processing (HPP) | Preserves natural nutrients and flavors, creating a premium, fresh-tasting product tier. |
| Expand Fitness Center Distribution | Addresses concentrated demand for low-calorie, vitamin-enriched post-workout hydration. |
| Launch Reusable Packaging Systems | Appeals to environmentally conscious consumers and enhances brand image through sustainability. |
| Scale Sugar-Free Production | Meets regulatory mandates and health-driven consumer demand for reduced sugar content. |
Research Approach
A standing panel of product developers, procurement managers, brand managers, and retail buyers provided ongoing calibration for market insights. Primary interviews with these industry stakeholders were rigorously validated against extensive secondary research. Secondary sources included regulatory body publications from FSSAI and FDA, industry association reports, and company financial statements. This approach utilized both bottom-up market sizing and top-top validation for robust data triangulation.
Forecast outputs underwent consistency checks against external benchmarks and competitor growth trajectories over the projection horizon. The analytical framework modeled segmentation dimensions including product type, packaging type, application, and customer type across various geographic regions. Compound Annual Growth Rates were derived from historical trends and projected impacts of health-driven consumerism. Key industry-specific forecast inputs included anticipated sugar reduction mandates and fruit concentrate price trends.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility. Forecasts reflect these assumptions, acknowledging potential impacts from evolving health regulations and sudden shifts in consumer preferences. Practitioners should keep alternative scenarios live as global economic conditions and regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Foaming Creamer Market
Beverages
North America Fruit Juice Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Juice Concentrates Market
Beverages
Japan Energy Drink Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Blenders Market
Beverages
Wellness Water Market
Beverages
Collagen-Infused Water Market
Beverages
Sports Drink Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Bubble Food and Beverages Market
Beverages
Germany Probiotic Drinks Market
Beverages
Dairy Based Beverages Market
Beverages
Canned Beverages Market
Beverages
United States Recovery Drinks Market