
 Fermented Food and Drinks Market | 2026-2036
Fermented Food and Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Food and Drinks Market Intelligence
The displacement of high-sugar soft drinks with probiotic-rich alternatives like kombucha and kefir is restructuring beverage category economics. Danone S.A. leverages its extensive dairy fermentation expertise to lead in yogurt and probiotic drinks globally. GT's Living Foods specializes in the premium kombucha category, building a strong brand around organic, raw ingredients. Yakult Honsha Co., Ltd. sustains its market position through a focused strategy on its signature probiotic dairy drink.
Fermented foods and drinks are products created through controlled microbial growth and the enzymatic conversion of food components like carbohydrates. This process, often involving specific strains of bacteria and yeast, serves to preserve the food, enhance its flavor profile, and increase nutritional bioavailability. Fermented dairy products, including yogurt and kefir, constitute a mature and large market segment. The application for digestive health represents the fastest-growing driver of consumer purchases across all product types.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern health claims and labeling for probiotic content. In countries like India, the FSSAI sets strict standards for fermented product safety and quality, influencing market access for imports. Navigating the evolving science and regulatory approval for strain-specific health benefits will determine future competitive differentiation for brands.
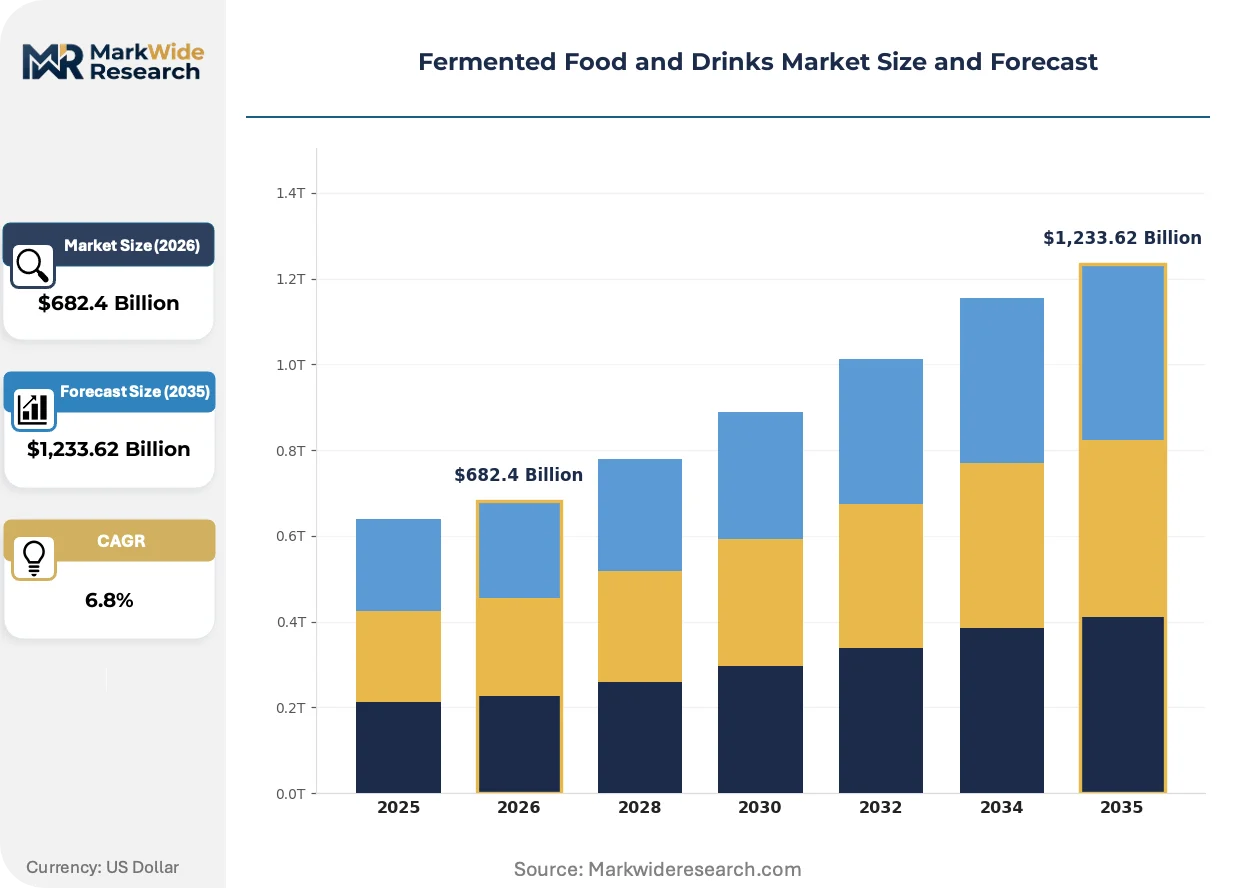
Market Dynamics
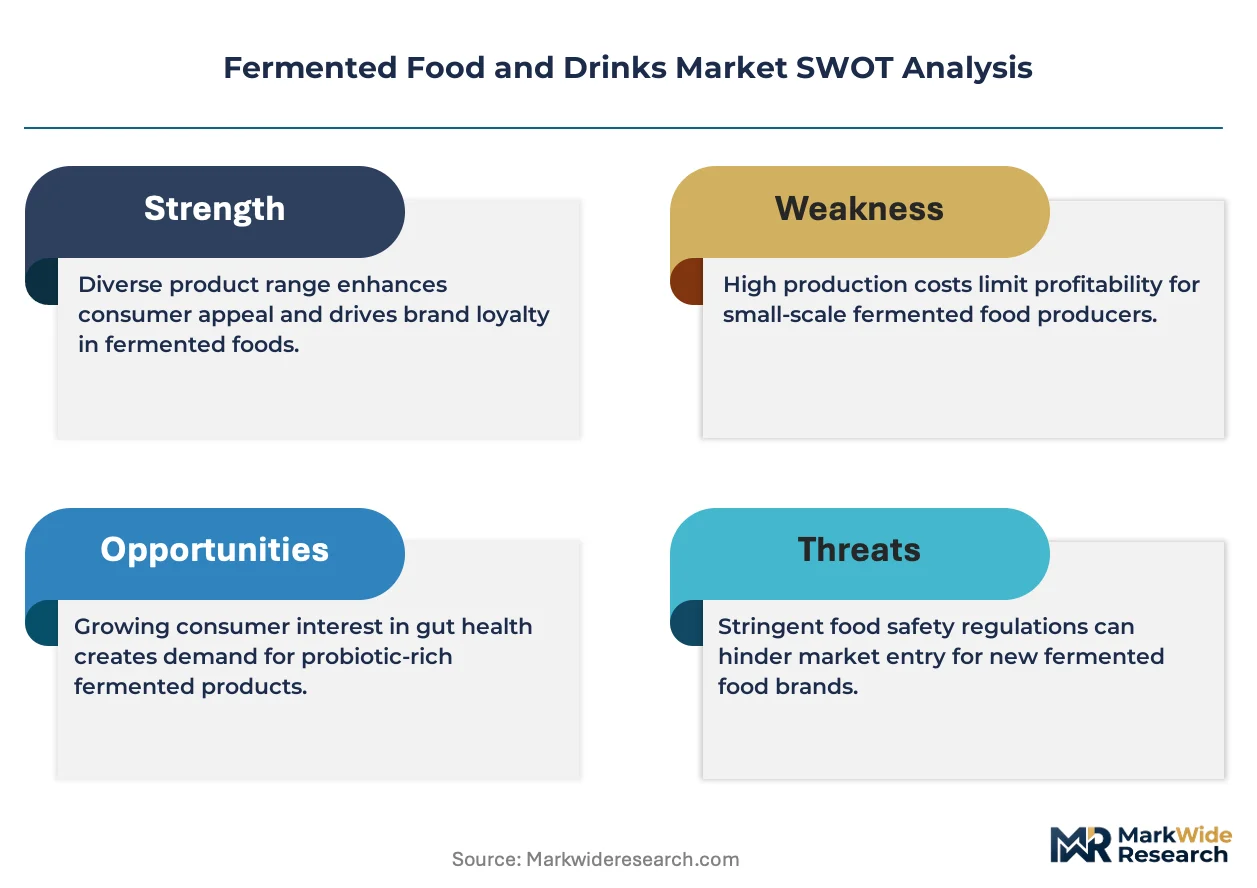
The convergence of consumer health consciousness with scientific validation of the gut microbiome's role in overall wellness is the central force shaping the market. This shift reframes fermented products from traditional foods into functional health tools, driving demand for evidence-backed benefits.
Growth Catalysts
- Scientific Validation:Advancements in microbiome research are substantiating the health benefits, particularly for digestive wellness, associated with specific probiotic strains. This evidence builds consumer trust and justifies premium pricing for functional fermented foods and drinks.
- Wellness Culture in Developed Economies:Health-focused lifestyles in the United States and Western Europe drive the substitution of high-sugar beverages with functional alternatives like kombucha and kefir, integrating them into daily routines.
- Regulatory Frameworks for Labeling:Evolving standards from the FDA and EFSA, while strict, create clearer pathways for brands to communicate probiotic content and function, helping consumers make more informed purchasing decisions.
Market Restraints
- Strain-Specific Efficacy Hurdles:The high cost and long timelines of clinical trials required to prove the health benefits of specific microbial strains create significant barriers to entry and limit the scope of permissible marketing claims.
- Cold-Chain Infrastructure Dependency:The necessity for refrigerated logistics to preserve the viability of live cultures increases distribution costs and restricts market penetration in regions with underdeveloped cold-chain networks.
- Substitution by Probiotic Supplements:The availability of probiotic supplements in capsule or powder form presents a convenient alternative for consumers seeking digestive health benefits without the taste or dietary considerations of fermented foods.
Strategic Opportunities
- Non-Dairy Fermentation:Developing fermented products from plant-based sources like vegetables, grains, and legumes caters to growing vegan, flexitarian, and lactose-intolerant consumer segments, opening new product categories.
- Personalized Nutrition Platforms:The convergence of at-home gut microbiome testing with customized fermented food subscription services presents a high-margin opportunity to deliver personalized health solutions directly to consumers.
- Market Expansion in Southeast Asia:Rising disposable incomes and a cultural history of consuming fermented foods in countries like Vietnam and Indonesia offer significant growth potential for branded probiotic products.
Industry Challenges
- Production Consistency and Quality Control:Maintaining uniform microbial activity, flavor profiles, and shelf-life stability across large-scale production batches poses a significant technical challenge requiring specialized process controls and expertise.
- Consumer Education Gap:A widespread lack of consumer understanding about the differences between various fermented products, microbial strains, and their specific health benefits necessitates substantial investment in marketing and education.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Food and Drinks Market |
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,233.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Vegetables, Fermented Dairy, Fermented Beverages, Fermented Soy Products, Fermented Meat Application: Digestive Health, Immune Support, Weight Management, Nutrient Enhancement, Flavoring Agent Packaging Type: Glass Bottles, Plastic Jars, Tetra Packs, Metal Cans, Paper Cartons Customer Type: Health-conscious Consumers, Specialty Food Stores, Foodservice Providers, Organic Markets, Gourmet Retailers |
| Companies Covered | Yakult Honsha Co., Ltd., Fonterra Co-operative Group Limited, Danone S.A., Lifeway Foods, Inc., GT's Living Foods, Nestlé S.A., The Coca-Cola Company, Brew Dr. Kombucha, PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Food and Drinks Market Strategic Shifts & Innovations
Fermentation science is evolving from a traditional preservation method into a sophisticated biotechnology platform for delivering functional ingredients and novel sensory experiences. This transition is powered by advancements in microbiology and bioprocessing, enabling the design of products with targeted nutritional and health attributes.
Precision fermentation uses microbial hosts as cellular factories to produce specific compounds like proteins, enzymes, and vitamins. Food technology companies and ingredient suppliers are adopting this process to create novel, non-animal-derived functional ingredients for the plant-based and alternative dairy sectors. This bio-manufacturing capability is absorbing the role of conventional agricultural inputs, enabling the creation of customized, nutrient-dense fermented products with high consistency.
The European Food Safety Authority (EFSA) enforces a stringent approval process for health claims related to probiotics, demanding extensive, strain-specific clinical data. This high evidentiary standard compels manufacturers to invest significantly in research to substantiate any link between their product and a specific health outcome. Consequently, the European yogurt and probiotic drink segments are most affected, with brands often pivoting to general wellness messaging over specific, unapproved health claims.
A significant behavioral shift involves consumers actively substituting conventional snacks and beverages with fermented alternatives to achieve a specific functional goal. This "functional swap" disrupts legacy categories, with kombucha replacing sugary sodas for gut health and kefir displacing traditional yogurts for higher probiotic counts. This consumption pattern is most visible among health-aware consumers in North American and Western European metropolitan areas.
Fermented Food and Drinks Market Segmentation
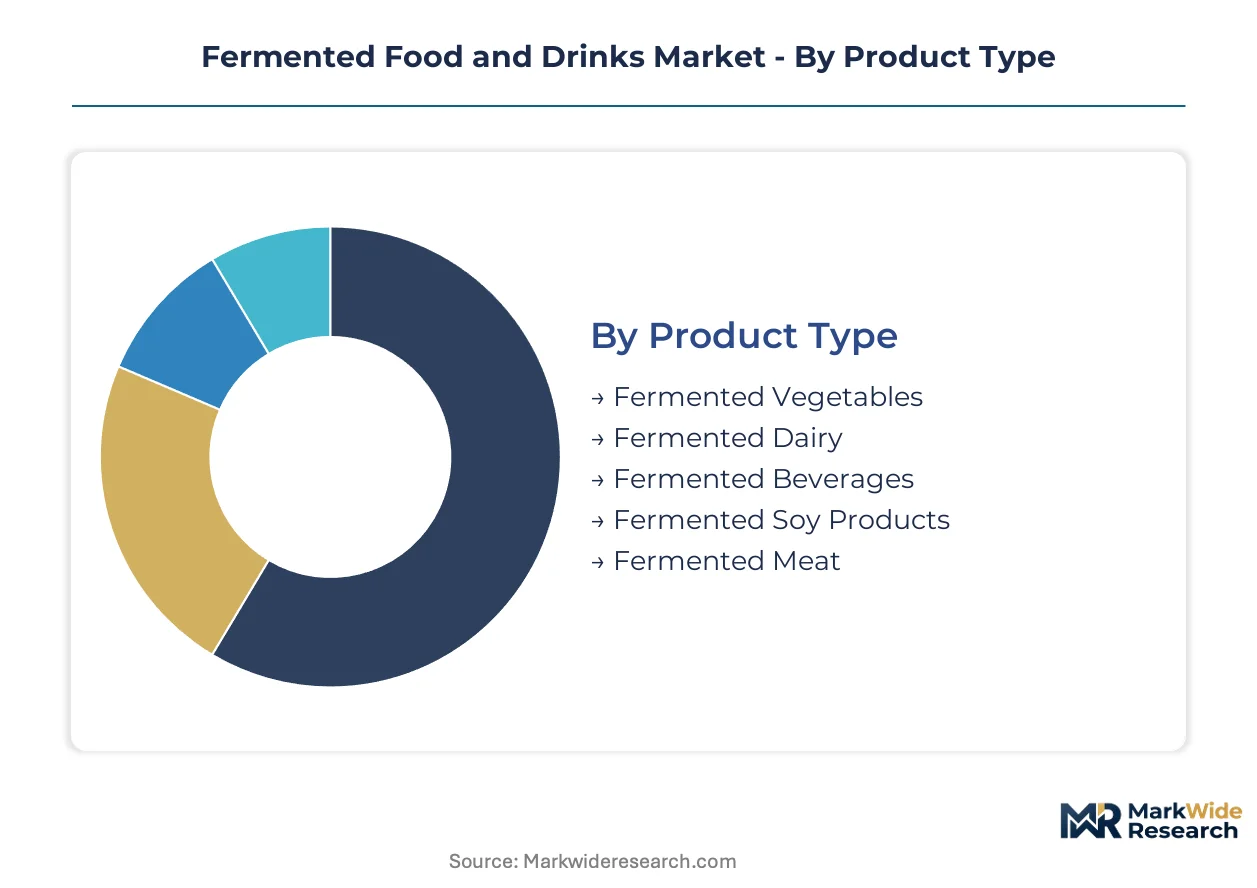
Market segmentation provides a granular view of product diversification and consumer engagement within the fermented food and drinks sector. Understanding these distinct categories helps stakeholders identify specific growth opportunities and tailor product development strategies effectively. The analysis highlights where investment is concentrated and where new demand is emerging across various product forms and consumer needs.
Product Type:
Segments within product type demand varying levels of capital investment for production infrastructure and supply chain complexity.
- Fermented Dairy:This segment includes products like yogurt and kefir, created through the fermentation of milk by specific bacterial cultures. Demand concentrates in established markets like Western Europe, driven by its perceived digestive benefits and widespread consumer acceptance.
- Fermented Beverages:This category encompasses drinks such as kombucha, kvass, and water kefir, typically produced by fermenting tea, fruit juices, or other sugary liquids with SCOBY or specific yeast strains. North American and European metropolitan areas show strong demand for these functional alternatives to high-sugar soft drinks.
- Fermented Vegetables:This segment includes products like sauerkraut, kimchi, and pickles, made by fermenting vegetables, often with lactic acid bacteria.
- Fermented Soy Products:Tempeh, miso, and natto represent this category, produced through the fermentation of soybeans using specific molds or bacteria.
- Fermented Meat:This segment involves cured sausages and other meat products fermented by bacterial cultures, enhancing preservation and flavor.
Fermented Dairy absorbs the bulk of installed capacity; Fermented Beverages is expanding most quickly.
Application:
The market segments by application, reflecting the functional utility consumers seek from fermented products.
- Digestive Health:Products targeting this application contain specific probiotic strains known to support gut microbiome balance and improve digestive functions. Consumer purchases in the United States and Germany are heavily influenced by these evidence-backed benefits.
- Immune Support:Fermented foods and drinks often contain compounds and probiotics that contribute to a healthy immune system, a benefit increasingly sought by wellness-focused consumers. Demand for these products is strong across Western Europe.
- Weight Management:Certain fermented products can contribute to satiety and metabolic health, offering a functional benefit for individuals managing their weight.
- Nutrient Enhancement:Fermentation can increase the bioavailability of vitamins, minerals, and other nutrients in food, making products more nutritionally dense.
- Flavoring Agent:Fermented ingredients like soy sauce or miso are widely used to impart umami and complex flavors to various dishes.
Digestive Health applications drive significant new product development; Immune Support benefits are gaining traction rapidly.
Packaging Type:
Packaging type segmentation reflects the diverse volumes and distribution requirements across the market.
- Glass Bottles:This packaging is frequently used for premium fermented beverages like kombucha and kefir, preserving product freshness and offering a high-quality aesthetic. Demand for glass-bottled products is particularly pronounced in specialty food stores.
- Plastic Jars:Widely adopted for fermented dairy products such as yogurt and some types of kefir, plastic jars offer durability, cost-effectiveness, and convenience for consumers. This format dominates the mainstream dairy aisle.
- Tetra Packs:This aseptic packaging is utilized for certain shelf-stable fermented beverages or dairy alternatives, offering extended shelf life without refrigeration until opened.
- Metal Cans:Some niche fermented drinks, particularly those targeting convenience or single servings, are beginning to utilize metal cans for portability and recyclability.
- Paper Cartons:Similar to Tetra Packs, paper cartons are used for larger format fermented dairy or plant-based fermented drinks, offering an eco-conscious packaging option.
Plastic Jars dominate high-volume dairy fermentation; Glass Bottles are experiencing rapid growth in premium beverage segments.
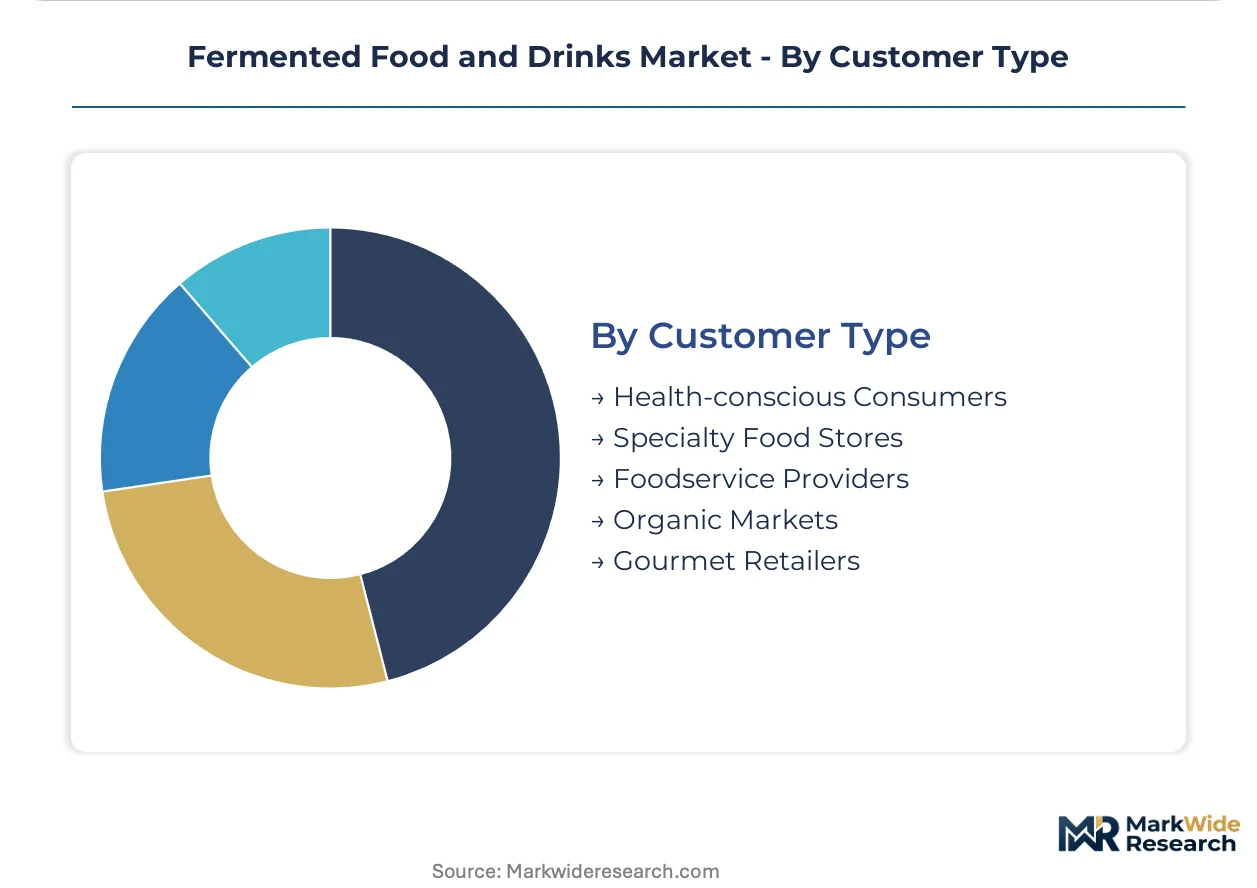
Customer Type:
Customer types delineate purchasing behavior and distribution channel preferences for fermented foods and drinks.
- Health-conscious Consumers:This segment actively seeks out fermented products for their perceived functional benefits, particularly digestive health and immune support. This consumer group in the United States drives innovation and premium pricing.
- Specialty Food Stores:These retailers cater to consumers looking for unique, organic, or gourmet fermented products, often stocking a wider variety of niche brands. Such stores in Germany and France contribute to market diversity.
- Foodservice Providers:Restaurants, cafes, and institutional kitchens incorporate fermented ingredients and drinks into their menus, offering convenience and functional options to their patrons.
- Organic Markets:Stores focusing on organic and natural products provide a dedicated channel for fermented foods and drinks that align with their ethical and health-oriented ethos.
- Gourmet Retailers:These outlets target consumers interested in high-quality, artisanal, and often imported fermented products, emphasizing unique flavors and traditional preparation methods.
Health-conscious Consumers represent the largest purchasing segment; Specialty Food Stores are seeing the steepest expansion trajectory for niche products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fermented food and drinks concentrates significantly in the United States and parts of Western Europe. Wellness trends in these regions strongly support market expansion, driving consumer interest in functional health products. Scientific advancements further validate health benefits, accelerating product development.
United States
Health-conscious consumers drive demand for probiotic-rich alternatives, particularly for digestive health benefits. The U.S. Food and Drug Administration (FDA) regulates health claims and labeling for probiotic content, impacting market communication. California's metropolitan areas actively innovate in plant-based fermented beverages and functional food solutions.
Germany
Consumers in Germany seek fermented products for immune support and traditional health benefits. The European Food Safety Authority (EFSA) enforces strict standards for health claims, influencing product development. Berlin's metropolitan food scene fosters innovation in artisanal fermented beverages and specialty dairy alternatives.
India
Rising disposable incomes and a strong cultural history of fermented foods drive market potential for branded probiotic products. The FSSAI sets strict standards for fermented product safety and quality, influencing import access. Major urban centers like Mumbai are experiencing rapid growth in demand for packaged fermented beverages.
Vietnam
A rich cultural history of consuming fermented foods, combined with increasing health awareness, fuels market expansion. Local food safety authorities ensure product quality and consumer protection for traditional and modern fermented items. Ho Chi Minh City's urban consumers increasingly purchase modern fermented dairy products and functional drinks.
France
An established market for fermented dairy products and a strong demand for functional foods underpin market growth. European Food Safety Authority (EFSA) regulations significantly impact permissible health claims for probiotic ingredients. Normandy's dairy industry focuses on developing advanced yogurt and kefir products with targeted benefits.
Fermented Food and Drinks Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting diverse market maturity and consumer preferences. The fermented dairy sector shows consolidation around large food conglomerates, while the emerging fermented beverages segment remains more fragmented with numerous niche players. Strategic archetypes include global food giants leveraging existing distribution, specialized probiotic drink manufacturers, and regional artisanal producers. Portfolio diversification into plant-based alternatives, strategic partnerships for ingredient sourcing, and geographic expansion are dominant competitive moves.
Global food giants like Danone S.A. exemplify established players, leveraging extensive dairy fermentation expertise and vast distribution networks for broad market reach. GT's Living Foods occupies a significant position among premium kombucha specialists, emphasizing organic and raw ingredients to cultivate a distinct brand identity within the functional beverage segment. Yakult Honsha Co., Ltd. represents a highly focused strategy, anchoring its market presence around its signature probiotic dairy drink through consistent messaging and scientific validation. These companies collectively showcase the diverse approaches to market penetration and brand building.
| Leading Market Players |
|---|
| Yakult Honsha Co., Ltd. |
| Fonterra Co-operative Group Limited |
| Danone S.A. |
| Lifeway Foods, Inc. |
| GT's Living Foods |
| Nestlé S.A. |
| The Coca-Cola Company |
| Brew Dr. Kombucha |
| PepsiCo, Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists often shape supply behavior and pricing discipline in niche fermented categories. These entities balance premium ingredient costs with consumer willingness to pay for functional benefits.
Pricing Analysis
Volume-driven fermented dairy segments operate on tighter margins, while premium fermented beverages command higher price points. Pricing stratifies across premium, standard, and economy tiers, reflecting ingredient quality and brand perception. Price differentiation drivers include specific probiotic strain validation and organic certifications. Pricing pressure stems from the rising cost of organic raw materials and cold-chain logistics. Health-conscious consumers show lower price sensitivity for products with evidence-backed digestive benefits, whereas mainstream buyers prioritize affordability.
Supply Chain Analysis
High logistics and freight costs, particularly for refrigerated transport, impact the distribution of live-culture fermented products. Geographic supply concentration for dairy inputs remains strong in Western Europe, while plant-based alternatives source from diverse agricultural regions. Raw material dependencies include specific milk types, organic teas, and fruit concentrates. Single-source vulnerability for proprietary microbial strains presents a structural supply chain risk. Distribution runs through both large retail chains and specialized health food stores, utilizing established cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is rapidly becoming a vertical-integration race, as players pursue in-house production of specialized microbial strains to control quality and intellectual property.
For Market Incumbents:
Deploy strategic acquisitions of niche plant-based fermentation companies to diversify product portfolios. Consolidate market share in mature dairy segments through aggressive marketing and product innovation to counter competition from probiotic supplements. Invest in clinical trials for new strain-specific health claims, mitigating the threat of stricter regulatory frameworks from bodies like the EFSA. Expand cold-chain infrastructure to support broader geographic reach for existing product lines.
For New Entrants and Emerging Players:
Launch via direct-to-consumer platforms for personalized nutrition solutions, targeting the underpenetrated segment of consumers seeking customized gut health interventions. Focus on non-dairy fermentation using plant-based sources like legumes or grains to capture the growing vegan and flexitarian consumer base. Develop strong brand narratives around organic, locally sourced ingredients to differentiate from established players. Leverage social media and influencer marketing for a cost-effective go-to-market angle.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor private equity firms in fragmented emerging beverage markets like kombucha, offering consolidation opportunities. The long-term viability of this market hinges on continued scientific validation of microbiome benefits over the next decade. Target acquisition archetypes include specialized ingredient suppliers and regional craft fermenters with strong intellectual property in unique strains. A signal to watch is the approval of new, specific health claims by regulatory bodies such as the FDA or EFSA.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expands consumer appeal beyond traditional dairy to include plant-based fermented options. |
| Clinical Trial Investment | Substantiates health claims for specific probiotic strains, building consumer trust and premium pricing. |
| Cold-Chain Logistics Optimization | Reduces distribution costs and extends market reach, especially in developing regions. |
| Direct-to-Consumer Channel Development | Captures high-margin personalized nutrition opportunities and strengthens brand loyalty. |
| Ingredient Sourcing Partnerships | Secures access to high-quality organic raw materials and proprietary microbial cultures. |
Research Approach
Academic journals, government health reports, and industry association publications formed the secondary backbone of this analysis. This foundational data was rigorously cross-referenced with insights from primary interviews. We engaged with product development executives, regulatory affairs specialists, and retail category managers across the fermented food and drinks sector. Bottom-up market sizing was then triangulated against top-down industry revenue figures for validation.
Historical trendline analysis established baseline growth trajectories for each market segment across the modeling period. The analytical framework incorporated segmentation dimensions including product type, application, packaging format, and regional consumer preferences. Compound Annual Growth Rates were derived from a weighted average of historical performance and projected demand drivers. Key forecast inputs included evolving consumer health consciousness and advancements in microbiome research.
Unforeseen regulatory changes, scientific breakthroughs, and shifts in consumer dietary trends are the dominant revision risks for these forecasts. The projections reflect assumptions about market dynamics and technological progression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Block Margarine Market
Processed Foods
Pea Processed Ingredients Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Soup & Broth Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Fat Free Soup Market
Processed Foods
Noodles Market
Processed Foods
North America Soup Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Africa Soup Market
Processed Foods
Soup Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Asia-Pacific Food Spread Market
Processed Foods
Spray Cheese Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Global Potato Flake Market