
 Turmeric Market | 2026-2036
Turmeric Market Size, Share, and Industry Trends Forecast 2026-2036
Turmeric Market Analysis
Organic certification tiers is reorganizing procurement priorities across the turmeric value chain. Everest Spices leverages its integrated sourcing network across Indian growing belts to secure consistent organic volumes. Sabinsa Corporation anchors its competitive position through specialized extraction capabilities for standardized curcuminoids. McCormick & Company, Inc. controls premium retail shelf space in North American supermarkets through branded turmeric blends.
Turmeric denotes the rhizome of Curcuma longa, typically containing 2-7% curcuminoids by dry weight, with commercial grades differentiated by volatile oil content and chromatographic purity profiles for food, pharmaceutical, and cosmetic applications. The nutraceuticals application segment leads value generation due to curcumin's validated bioactive properties, while organic product types command expanding acreage as processors respond to clean-label procurement mandates. Conventional turmeric still dominates volume throughput in wholesale channels serving restaurant and industrial manufacturing end users.
India's FSSAI enforces pesticide residue and aflatoxin thresholds that directly determine export eligibility for turmeric consignments. The US FDA regulates curcumin dietary supplements under DSHEA, requiring substantiation of structure-function claims that shapes formulation R&D investment. Stakeholders must monitor evolving curcumin bioavailability patent landscapes and synthetic biology alternatives that could disrupt botanical extraction economics.
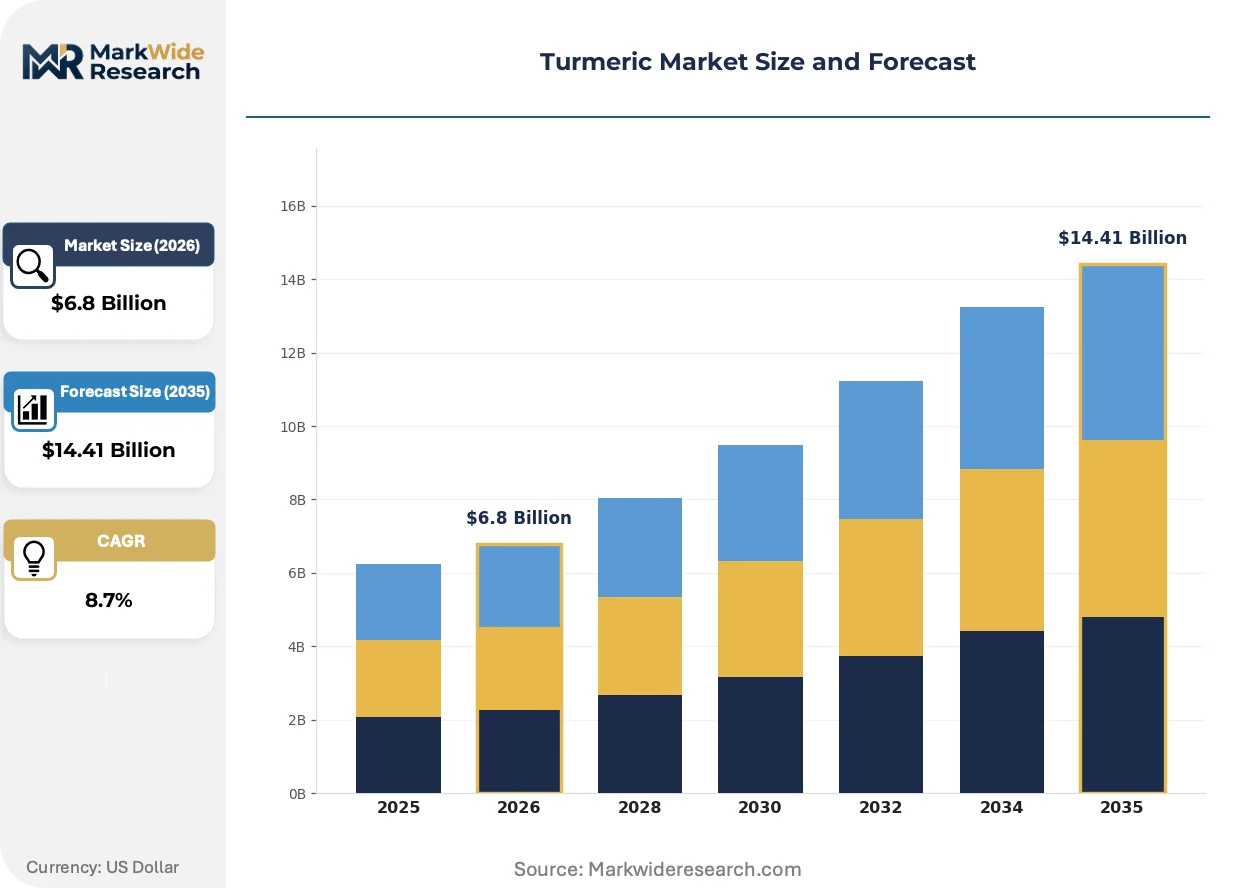
Market Dynamics
India's FSSAI contaminant limits are forcing processors to rebuild quality assurance infrastructure, while nutraceuticals buyers demand certified organic volumes that conventional supply chains cannot deliver at scale.
Growth Catalysts
- DSHEA substantiation requirements:US FDA structure-function claim rules are driving curcumin formulation R&D investment into standardized bioavailability enhancement.
- Clean-label procurement mandates:North American retail chains now require organic certification tiers that Kerala and Tamil Nadu processors are racing to secure.
- Volatile oil extraction technology:Supercritical CO2 methods are unlocking pharmaceutical-grade curcuminoid purity profiles previously unattainable through solvent extraction.
Market Restraints
- Input cost volatility:Rhizome prices swing with monsoon-dependent yields across India's growing belts, compressing processor margins unpredictably.
- Supply concentration risk:Over 80% of traded volume originates from Indian sub-regions vulnerable to climate disruption and export policy shifts.
- Regulatory friction:EFSA novel food approvals for enhanced bioavailability formulations create 18-24 month market entry delays for European nutraceuticals.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA is streamlining botanical supplement registrations, opening South American demand for standardized curcumin extracts.
- Emerging application:Cosmetic formulators in South Korea are integrating curcuminoids into anti-aging topicals, creating premium ingredient demand.
- Regulatory tailwind:India's PLI scheme for food processing is subsidizing organic certification and cold chain infrastructure in Andhra Pradesh and Karnataka.
Industry Challenges
- Certification timeline compression:USDA Organic and India Organic dual certification requires 36-month field conversion cycles that outpace buyer contract windows.
- IP licensing complexity:Bioavailability enhancement patents held by specialized extraction firms fragment formulation freedom and royalty structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turmeric Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Extracts, Curcumin Application: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Households, Restaurants, Health Institutions, Manufacturers |
| Companies Covered | McCormick & Company, Inc., Everest Spices, MDH Spices, Synthite Industries Ltd., Arjuna Natural Pvt. Ltd., Sabinsa Corporation, DS Group, Olam International, Biomax Life Sciences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turmeric Market Emerging Trajectories
Synthetic biology alternatives and precision fermentation are entering commercial viability, threatening to disrupt botanical extraction economics while clean-label mandates accelerate organic acreage conversion.
Supercritical CO2 extraction is decomposing the traditional solvent-based processing hierarchy by enabling pharmaceutical-grade curcuminoid recovery without residual chemical markers. Nutraceuticals contract manufacturers in the United States and Germany are adopting these systems within 24-month equipment replacement cycles. This technology is decomposing the competitive advantage of established solvent-extraction specialists who lack capital for infrastructure overhaul.
REACH registration requirements for novel curcumin derivatives are tightening purity documentation standards across European cosmetic and pharmaceutical applications. ECHA substance evaluation protocols now demand full toxicological profiles for modified bioavailability forms. German and Swiss formulators are responding by consolidating supplier relationships to processors with in-house analytical capabilities.
Direct-procurement contracts between nutraceuticals brands and Indian organic cooperatives are displacing multi-layered spice trading networks. Kerala-based farmer producer companies now ship containerized lots to North American supplement manufacturers, bypassing Mumbai and Kochi auction houses. This channel compression is most visible in high-curcumin organic grades where traceability commands 15-20% price premiums.
Turmeric Market Segmentation
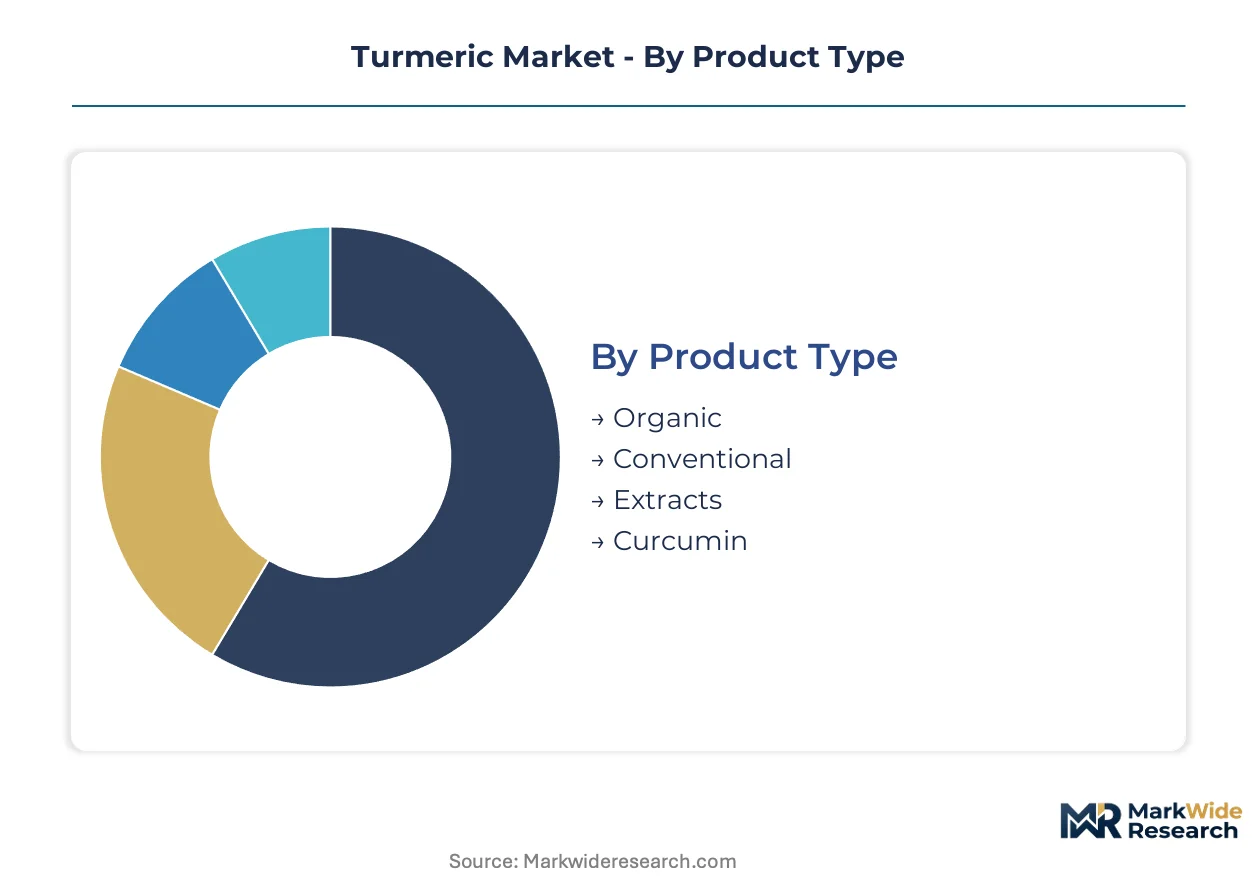
Turmeric segmentation reflects divergent quality standards and extraction intensity across end-use applications. Procurement specifications vary sharply between pharmaceutical-grade curcuminoid requirements and conventional food-grade rhizome sourcing.
Product Type:
Synthetic biology fermentation of curcuminoids is exerting substitution pressure most acutely on standardized extract segments, while whole-rhizome categories face lower near-term displacement risk.
- Organic:Field conversion cycles span 36 months under USDA Organic and India Organic dual certification, constraining supply elasticity. Kerala and Tamil Nadu cooperatives are securing direct-procurement contracts with North American nutraceuticals brands seeking traceability premiums.
- Conventional:Monsoon-dependent yields across Maharashtra and Andhra Pradesh growing belts drive input cost volatility. This grade dominates volume throughput in wholesale channels serving restaurant and industrial manufacturing end users where certification premiums are non-recoverable.
- Extracts:Supercritical CO2 methods are displacing solvent-based processing for volatile oil recovery.
- Curcumin:Standardized curcuminoid purity profiles determine pharmaceutical versus nutraceutical grade eligibility.
Conventional retains volume leadership; organic holds the steepest expansion curve.
Application:
Margin structures stratify sharply between commoditized food-grade usage and value-added bioactive formulations.
- Nutraceuticals:DSHEA structure-function claim substantiation requirements are driving R&D investment into bioavailability enhancement technologies. German and U.S. contract manufacturers are consolidating supplier relationships around processors with in-house analytical capabilities for full toxicological documentation.
- Pharmaceuticals:REACH registration demands for novel curcumin derivatives require complete purity documentation under ECHA substance evaluation protocols. Swiss and German formulators are restricting procurement to extraction specialists with pharmaceutical-grade certification.
- Food & Beverage:FSSAI contaminant limits on pesticide residues and aflatoxins determine export eligibility for Indian consignments.
- Cosmetics:South Korean formulators are integrating curcuminoids into anti-aging topicals, creating premium ingredient demand.
Food & Beverage retains volume leadership; nutraceuticals commands the highest value per kilogram.
Distribution Channel:
Channel compression is reshaping traditional multi-layered trading networks into direct procurement relationships.
- Wholesalers:Mumbai and Kochi auction houses still dominate conventional grade aggregation, though volume is fragmenting as farmer producer companies develop containerized export capabilities.
- Online Retail:Direct-to-consumer supplement brands are bypassing retail intermediaries, capturing margin that previously accrued to supermarket slotting fees.
- Supermarkets:North American retail chains are mandating organic certification tiers that outpace Kerala processor conversion timelines.
- Specialty Stores:Ayurvedic and wellness-focused retailers command premium pricing for traceable single-origin sourcing.
Wholesalers retain volume leadership; online retail is climbing the fastest.
End User:
Specification intensity varies from household bulk purchasing to pharmaceutical-grade documentation requirements.
- Manufacturers:Nutraceuticals and cosmetics formulators are driving demand for certified organic volumes with chromatographic purity profiles. These buyers now require 15-20% traceability premiums that conventional supply chains cannot deliver at contract scale.
- Health Institutions:Hospital and clinical nutrition procurement is standardizing on curcuminoid-standardized extracts for therapeutic applications.
- Restaurants:Ethnic cuisine operators in North American and European metropolitan markets source conventional grades through wholesale distributors.
- Households:Retail turmeric powder purchasing concentrates in South Asian diaspora communities and wellness-oriented consumer segments.
Manufacturers retain volume leadership; health institutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's growing belts generate over four-fifths of internationally traded turmeric volume, concentrating supply risk in sub-regions vulnerable to monsoon disruption and export policy shifts.
India
Kerala and Tamil Nadu processing clusters dominate organic certification conversion as cooperatives secure direct-procurement contracts with North American nutraceuticals brands. FSSAI tightened pesticide residue and aflatoxin thresholds, forcing exporters to rebuild quality assurance infrastructure. Andhra Pradesh and Karnataka expanding acreage under the PLI scheme for food processing.
United States
DSHEA structure-function claim substantiation requirements drive curcumin formulation R&D investment into bioavailability enhancement technologies. FDA regulates dietary supplements under existing frameworks, shaping contract manufacturer consolidation around processors with in-house analytical capabilities. Nutraceuticals brands in New Jersey and California bypass traditional import channels for direct farmer producer company relationships.
Germany
REACH registration demands for novel curcumin derivatives require complete purity documentation under ECHA substance evaluation protocols. Swiss and German formulators restrict procurement to extraction specialists with pharmaceutical-grade certification. Supercritical CO2 extraction equipment replacement cycles concentrate in Baden-Württemberg chemical processing corridors.
South Korea
Cosmetic formulators integrate curcuminoids into anti-aging topicals, creating premium ingredient demand distinct from commoditized food-grade sourcing. MFDS regulates functional cosmetics claims, influencing documentation standards for bioactive botanical imports. Seoul-based contract manufacturers develop specialized extraction partnerships with Indian organic cooperatives.
Brazil
ANVISA streamlines botanical supplement registrations, opening South American demand for standardized curcumin extracts previously blocked by regulatory complexity. São Paulo nutraceuticals distributors establish direct sourcing relationships with Maharashtra growing belts. Local processors invest in solvent extraction capacity to capture import substitution margins.
Turmeric Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with extraction specialists commanding premium positioning while integrated spice houses dominate volume throughput. The vendor base stratifies into three tiers: pharmaceutical-grade extraction specialists, branded retail conglomerates, and commodity trading networks. Archetypes include backward-integrated agricultural processors, formulation-focused nutraceuticals laboratories, and multi-category spice conglomerates. Dominant competitive moves center on organic certification acquisition and supercritical CO2 extraction infrastructure deployment.
Within the extraction specialist tier, Sabinsa Corporation and Arjuna Natural Pvt. Ltd. exemplify technology-forward positioning through specialized curcuminoid standardization capabilities. Everest Spices occupies a position bridging integrated sourcing networks and branded retail presence across Indian growing belts. McCormick & Company, Inc. anchors the North American premium retail vector through supermarket shelf space control for branded turmeric blends.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Everest Spices |
| MDH Spices |
| Synthite Industries Ltd. |
| Arjuna Natural Pvt. Ltd. |
| Sabinsa Corporation |
| DS Group |
| Olam International |
| Biomax Life Sciences Ltd. |
| Others |
Supply Flow & Price Mechanics
USDA Organic and India Organic dual certification gates both supply qualification and price differentiation simultaneously, forcing 36-month field conversion cycles that outpace buyer contract windows while commanding 15-20% traceability premiums in direct-procurement channels.
Pricing Analysis
FSSAI contaminant limits dictate the pricing tier structure across Indian export consignments. Three-tier pricing stratifies across pharmaceutical-grade, nutraceutical-standardized, and conventional food-grade levels. Certification premiums widen as Kerala cooperatives secure North American direct contracts, while restaurant and industrial buyers absorb monsoon-driven rhizome cost volatility without margin recovery. Price compression runs through conventional grades where auction-house aggregation still dominates.
Supply Chain Analysis
Strategic stockpiling of certified organic inventory dominates procurement behavior as 36-month conversion cycles eliminate just-in-time flexibility for premium grades. Supply concentrates in India's Maharashtra, Andhra Pradesh, and Tamil Nadu growing belts, with secondary sourcing from Bangladesh and Myanmar. Rhizome quality, volatile oil content, and chromatographic purity profiles anchor input specifications. Single-source vulnerability intensifies as over 80% of traded volume originates from Indian sub-regions. Distribution runs through Mumbai and Kochi auction houses for conventional grades, while containerized direct shipments bypass traditional layers for organic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label procurement mandates fragment demand into certifiable niches that incumbent solvent-extraction specialists cannot serve, creating entry points for technology-forward processors with supercritical CO2 infrastructure.
For Market Incumbents: Secure dual certification pipelines across Andhra Pradesh and Karnataka growing belts before PLI scheme subsidies expire. Synthetic biology alternatives threaten botanical extraction economics; backward integration into farmer producer companies locks organic volume. Supercritical CO2 equipment replacement cycles in German and U.S. contract manufacturing compress the competitive window for solvent-dependent processors.
For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade purity documentation for European REACH-registered cosmetic applications. Brazil's ANVISA streamlining presents the most penetrable geography for standardized extract registration. Seoul-based cosmetic formulators offer premium ingredient demand distinct from commoditized food-grade sourcing. Direct-procurement contracting with Kerala cooperatives bypasses entrenched auction-house networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as 24-month equipment replacement cycles concentrate in Baden-Württemberg and New Jersey processing corridors. Five-to-ten year viability favors extraction specialists with in-house analytical capabilities over commodity trading networks. Target acquisition archetype: mid-tier Indian processors with partial organic certification and stranded solvent-extraction assets. Watch for EFSA novel food approval timelines as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acquisition | USDA Organic and India Organic dual certification unlocks 15-20% traceability premiums in North American nutraceuticals procurement. |
| Supercritical CO2 Infrastructure Deployment | Pharmaceutical-grade curcuminoid recovery without residual chemical markers displaces solvent-extraction specialists lacking capital for overhaul. |
| Direct-Procurement Contracting | Farmer producer companies in Kerala bypass Mumbai and Kochi auction houses, compressing channel margins into processor control. |
| REACH Registration Completion | ECHA substance evaluation protocols demand full toxicological profiles that fragment supplier relationships toward analytical-capable processors. |
| Synthetic Biology Alternative Monitoring | Precision fermentation viability threatens botanical extraction economics; early positioning determines obsolescence risk exposure. |
Methodological Framework
Initial hypotheses were tested against primary input from extraction technology directors, organic certification auditors, nutraceuticals procurement managers, and spice trading house operators and refined through secondary validation. Bottom-up volume modeling drew from FSSAI export registration databases, India Organic certification records, and U.S. FDA DSHEA structure-function claim filings. Top-down demand triangulation incorporated ECHA REACH substance evaluation protocols, ANVISA botanical supplement registration trends, and MFDS functional cosmetics claim standards.
Variance decomposition across the projection horizon isolates segment-specific growth drivers from macroeconomic noise. Modeled dimensions span organic versus conventional product type, nutraceuticals versus food-grade versus pharmaceutical application, and direct-procurement versus auction-house distribution channel. CAGRs derive from log-linear trend fitting adjusted for certification conversion cycle constraints and regulatory approval timeline delays. Forecast inputs incorporate monsoon yield volatility coefficients and supercritical CO2 equipment adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained clean-label procurement mandate intensity or accelerated synthetic biology cost parity would require recalibration. Forecasts reflect documented assumptions regarding FSSAI enforcement continuity, PLI scheme subsidy duration, and EFSA novel food approval velocity. Revision becomes warranted when Brazil's ANVISA registration streamlining crosses threshold volume or South Korean cosmetic curcuminoid integration rates exceed baseline projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market
Spices and Seasonings
Espresso Salt Market