
 Germany Probiotic Drinks Market | 2026-2036
Germany Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Probiotic Drinks Market Insights
Market Context
Bavaria is fragmenting as a production hub for fermented beverages, with traditional dairies and craft kombucha breweries expanding side by side. Danone leverages its dairy heritage to sustain shelf presence across German retail chains. Ehrmann SE anchors its position through refrigerated logistics networks that reach into eastern federal states. ROY Kombucha differentiates via small-batch brewing and regional ingredient sourcing.
Technical Definition and Segment Structure
Germany probiotic drinks are non-alcoholic or low-alcohol beverages containing live microbial cultures, typically maintained at colony-forming unit counts exceeding 10^6 CFU per milliliter at consumption, designed to deliver gastrointestinal or immune-modulating benefits through regular intake. Kombucha formulations occupy the fastest-growing margin pool as German consumers gravitate toward low-sugar fermented alternatives. Health food stores and specialty retailers control the premium channel for kefir and functional smoothies, while supermarkets dominate volume throughput for probiotic yogurt drinks. Elderly and fitness enthusiast end users represent the most concentrated demand segments, with children-oriented formulations remaining underdeveloped relative to Nordic benchmarks.
Regulatory Framework and Outlook
Germany's Federal Office of Consumer Protection and Food Safety (BVL) enforces LFGB compliance on live culture stability claims, while EU EFSA health claim regulations restrict specific probiotic benefit messaging on packaging. The EU F-Gas Regulation and national packaging laws (VerpackG) are forcing reformulation of carbonated variants and driving shifts toward returnable glass and biodegradable materials. Stakeholders must monitor pending amendments to EU organic labeling criteria and Germany's national nutrition strategy, as these will determine which formulations qualify for preferential retail placement and public procurement channels.
Market Dynamics
EU EFSA health claim restrictions on live culture stability messaging are compressing margin pools for German probiotic drink manufacturers, forcing reformulation investments and claim repositioning across refrigerated beverage portfolios.
Growth Catalysts
- Fitness Enthusiast Demand:Gym-goers in Berlin and Munich are integrating kefir and kombucha into post-workout recovery routines, expanding the addressable base beyond traditional dairy consumers.
- LFGB Compliance Infrastructure:Germany's established refrigerated logistics networks for live culture products enable faster shelf-to-consumer transit times than southern European markets.
- Novel Food Pathway Clarity:EU-level regulatory frameworks for fermented beverages provide predictable approval timelines for new strain introductions.
Market Restraints
- Glass Packaging Cost Volatility:Returnable bottle systems under Germany's VerpackG face rising energy and transport expenses that squeeze mid-tier brand economics.
- Live Culture Stability Limitations:CFU count degradation during ambient temperature excursions restricts direct-to-consumer shipping options outside cold chain networks.
- Dairy-Based Substitution:Plant-based fermented alternatives using oat and coconut bases are capturing shelf space in organic retail channels.
Strategic Opportunities
- Elderly Nutrition White Space:Saxony and Brandenburg present underdeveloped retail coverage for senior-targeted probiotic smoothies compared to Bavarian penetration rates.
- EU Organic Labeling Expansion:Pending amendments to organic certification criteria will unlock preferential placement in German public hospital and care facility procurement.
- Functional Ingredient Convergence:Kombucha brewers are integrating adaptogenic herbs with live cultures to capture wellness crossover demand.
Industry Challenges
- Microbiology Talent Scarcity:German universities produce insufficient fermentation science graduates to staff quality control functions at expanding craft breweries.
- Cold Chain Capex Intensity:Establishing refrigerated distribution into eastern federal states requires substantial fleet investment without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Probiotic Drinks Market |
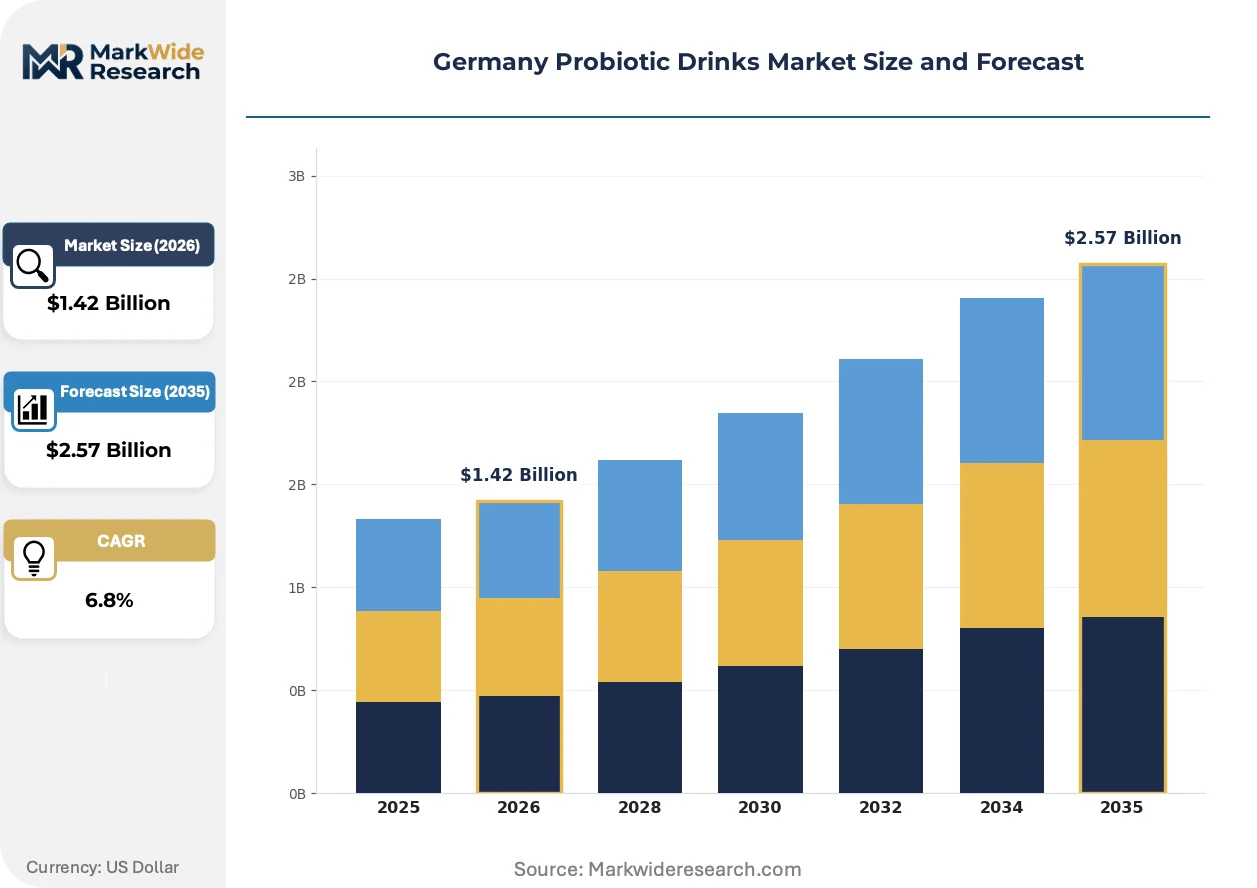
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Probiotic Yogurt, Functional Smoothies End User: Fitness Enthusiasts, Health-Conscious Consumers, Elderly, Children Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores Formulation: Liquid, Powder, Ready-to-Drink, Carbonated |
| Companies Covered | Ehrmann SE, PepsiCo, Inc., Danone, ROY Kombucha, Kanne Brottrunk, Yakult Honsha Co., Ltd., Lifeway Foods, Inc., Fischer Fermentgetränke GmbH, Nestlé, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Probiotic Drinks Market Trends and Innovations
Live culture beverage production is fragmenting across multiple technological frontiers simultaneously, with traditional dairy processors and craft fermenters pursuing divergent innovation pathways that reshape competitive boundaries.
Precision fermentation is hybridizing conventional dairy processing with cell-culture-derived protein bases, enabling German manufacturers to reduce reliance on raw milk supply fluctuations while maintaining live culture viability. Mid-sized Bavarian dairies are piloting these systems to stabilize input costs. The technology is compressing the traditional divide between dairy heritage and biotechnology capabilities in regional production clusters.
Germany's Federal Office of Consumer Protection and Food Safety is tightening LFGB enforcement on ambient-stable probiotic claims, requiring reformulation of shelf-stable kombucha variants. Manufacturers are responding by shifting carbonated lines toward refrigerated-only distribution. Bavarian craft brewers face the steepest compliance costs as they lack the R&D infrastructure of national dairy conglomerates.
Direct subscription models are displacing traditional retail stocking agreements for premium fermented beverages, with urban consumers in Hamburg and Cologne accepting longer delivery windows for customized strain combinations. Health food stores are losing traffic to specialized e-commerce platforms. This channel rotation is most pronounced among fitness enthusiasts seeking specific CFU concentrations unavailable in supermarket assortments.
Germany Probiotic Drinks Market Segmentation
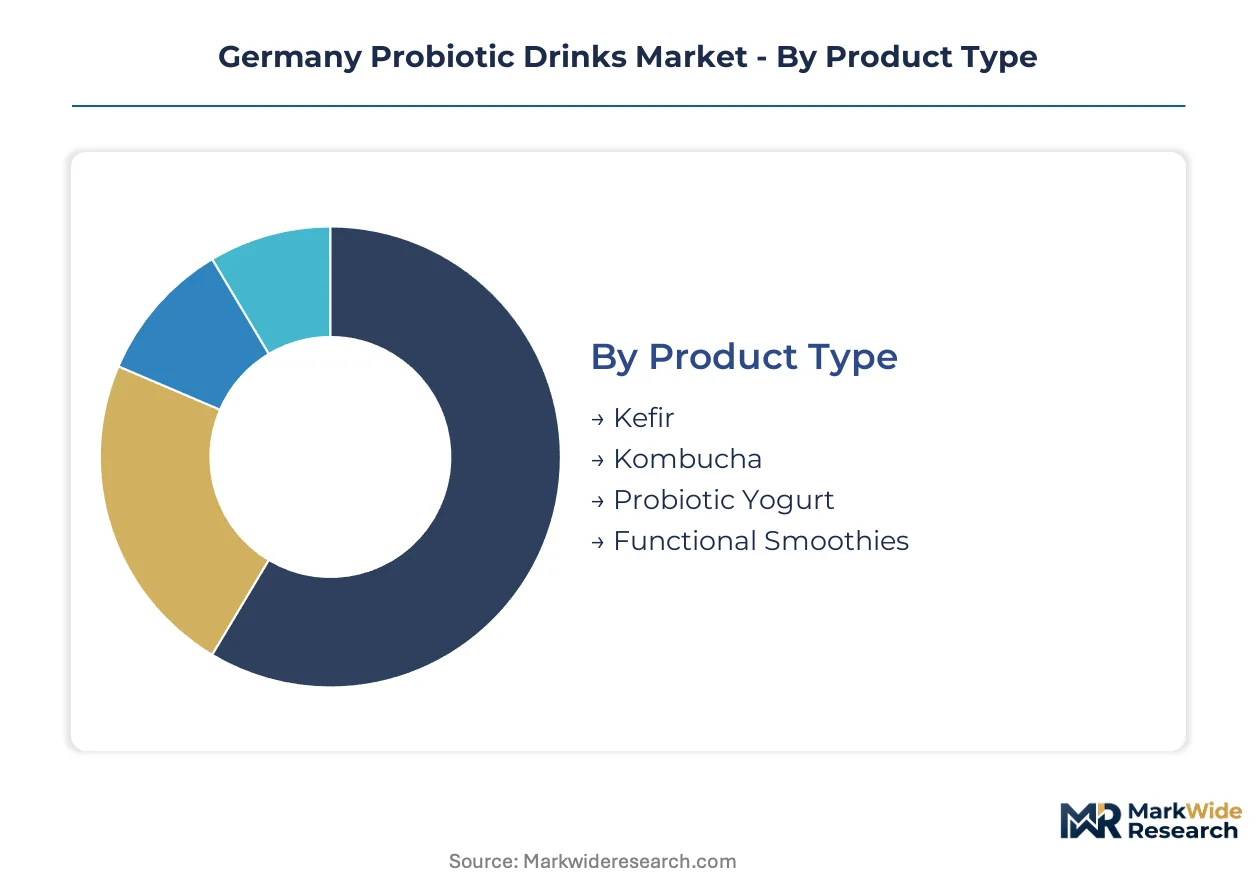
Segmentation in Germany's probiotic drinks market reveals divergent margin profiles and cold chain requirements across product formats. Manufacturers must calibrate formulation investments and distribution partnerships against distinct end-user willingness to pay for live culture stability.
Product Type:
After-sales intensity varies sharply across fermented beverage categories, with refrigerated logistics demands and culture viability monitoring creating divergent service cost structures.
- Kombucha:Fermented tea-based beverages with acetic acid bacteria and yeast cultures, typically 2-5% ABV, requiring cold stabilization to arrest fermentation. Berlin and Munich health food retailers report strongest velocity for low-sugar variants among millennials seeking alternatives to alcoholic social beverages.
- Kefir:Fermented milk drink containing kefir grains with 10-12 microbial species, traditionally 2-3% ABV, sustaining higher CFU counts through shelf life. Bavarian dairy processors leverage existing refrigerated networks to dominate supermarket placement, though craft brewers in Saxony are gaining traction in specialty channels.
- Probiotic Yogurt:Drinkable yogurt formulations with added Lactobacillus and Bifidobacterium strains, positioned as meal replacements or digestive aids. Ehrmann SE and Danone anchor retail presence through multi-SKU refrigerated sets.
- Functional Smoothies:Blended fruit and vegetable bases with probiotic fortification, targeting on-the-go consumption. ROY Kombucha and regional craft producers experiment with seasonal ingredient sourcing.
By volume, Probiotic Yogurt leads. By growth pace, Kombucha is ahead.
End User:
Cost tier stratification separates premium-positioned formulations from mass-market alternatives, with elderly and fitness segments commanding highest per-liter pricing.
- Fitness Enthusiasts:Post-workout recovery seekers prioritizing protein-probiotic combinations and specific CFU concentrations. Hamburg and Cologne gym partnerships drive subscription model adoption for customized strain blends unavailable in conventional retail.
- Elderly:Consumers over 65 seeking digestive regularity and immune support, concentrated in Bavaria and Baden-Württemberg. Saxony and Brandenburg present underdeveloped retail coverage relative to southern penetration rates.
- Health-Conscious Consumers:Broad middle segment incorporating probiotic drinks into preventive wellness routines, price-sensitive but responsive to organic certification.
- Children:Pediatric formulations with palatability masking and lower culture counts, significantly underdeveloped versus Nordic market benchmarks.
By volume, Health-Conscious Consumers dominate. By margin contribution, Fitness Enthusiasts command premium positioning.
Distribution Channel:
Application-specific fulfillment requirements fragment channel economics, with live culture stability dictating permissible transit windows and storage conditions.
- Supermarkets:Volume throughput leader with refrigerated dairy sections controlling kefir and yogurt drink placement. Edeka and Rewe chains demand consistent supply reliability and promotional participation.
- Health Food Stores:Premium channel for kombucha and functional smoothies, with Alnatura and regional cooperatives emphasizing organic certification and local sourcing narratives.
- Online Retailers:Direct-to-consumer platforms capturing fitness enthusiast demand for strain-specific formulations, though ambient temperature excursions during shipping constrain addressable geography.
- Specialty Stores:Craft fermentation boutiques and farmers market presences supporting small-batch producers with higher price tolerance and education-intensive selling.
By volume, Supermarkets lead. By growth pace, Online Retailers are expanding most quickly.
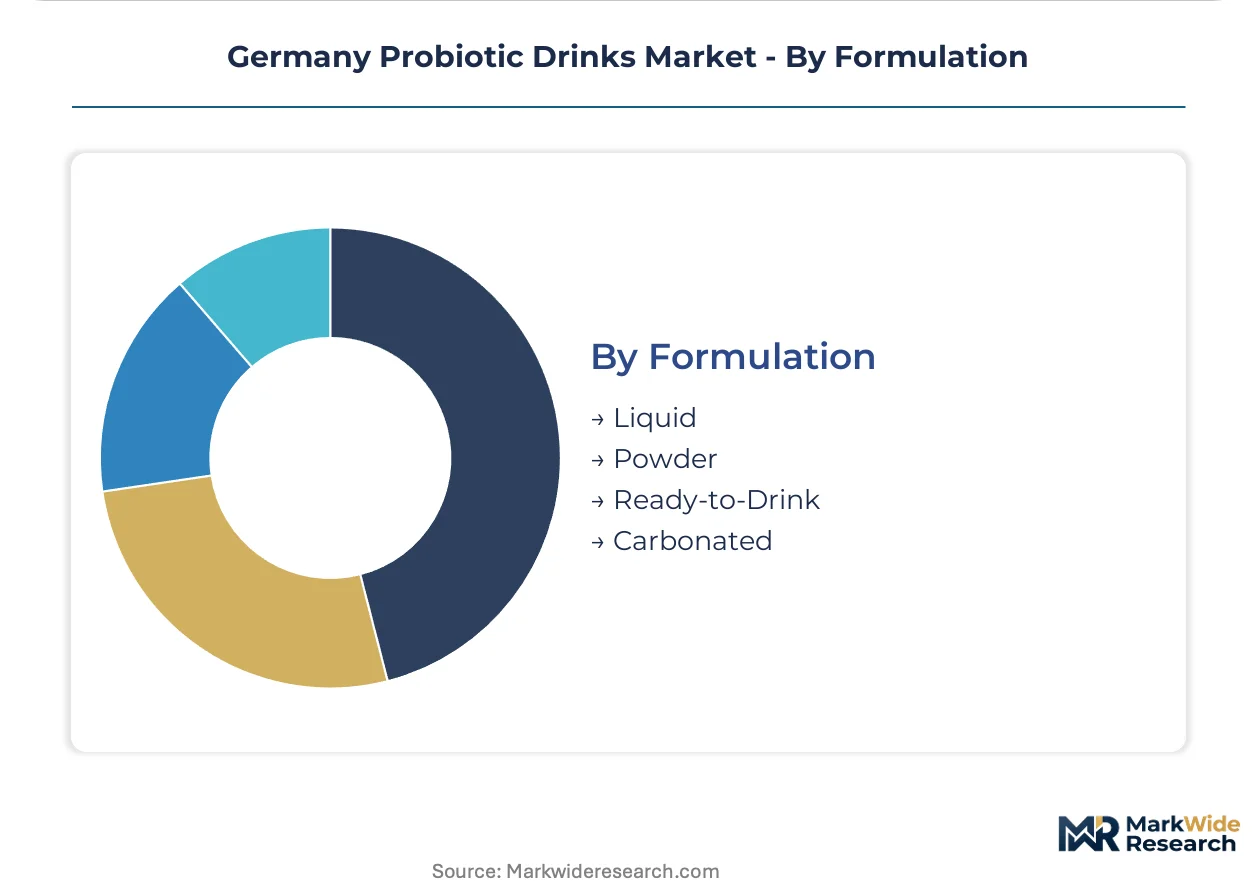
Formulation:
Supply concentration in refrigerated liquid formats contrasts with emerging powder alternatives that bypass cold chain constraints.
- Liquid:Traditional refrigerated beverages with live culture counts maintained above 10^6 CFU/ml, dominating German retail and foodservice.
- Ready-to-Drink:Ambient-stable variants with spore-forming strains or post-biotic positioning, gaining traction in convenience channels despite LFGB claim restrictions.
- Carbonated:Effervescent kombucha and kefir variants, facing VerpackG packaging compliance costs and F-Gas Regulation reformulation pressures.
- Powder:Sachet and bulk formats for home reconstitution, circumventing refrigerated logistics but requiring consumer education on proper hydration and temperature control.
By volume, Liquid leads. By innovation intensity, Powder formats show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's refrigerated rail corridors and dense autobahn network sustain cold chain integrity for live culture beverages moving from Bavarian production clusters to urban consumption centers. The federal logistics infrastructure enables shelf-to-consumer transit times unmatched in southern European markets.
Bavaria
Traditional dairies in Upper Bavaria process kefir and yogurt drinks for nationwide supermarket distribution. Germany's LFGB enforcement by the BVL mandates live culture stability documentation for all refrigerated exports leaving Munich logistics hubs. Ingolstadt and Rosenheim anchor precision fermentation pilot programs that hybridize dairy heritage with cell-culture protein bases.
North Rhine-Westphalia
Fitness enthusiasts in Cologne and Düsseldorf drive subscription demand for kombucha with specific CFU concentrations. The EU F-Gas Regulation pressures carbonated variant producers in the Ruhr industrial belt to reformulate packaging. Düsseldorf's refrigerated distribution terminals serve as consolidation points for eastern federal state expansion.
Baden-Württemberg
Organic retail cooperatives in Stuttgart prioritize locally sourced functional smoothies with probiotic fortification. Germany's VerpackG returnable bottle systems face rising energy costs that squeeze mid-tier craft brewers in the Black Forest region. Freiburg's university fermentation science programs supply quality control talent to regional producers.
Berlin-Brandenburg
Millennial consumers in Berlin health food stores gravitate toward low-sugar kombucha as alternatives to alcoholic social beverages. Pending EU organic labeling amendments will determine procurement eligibility for public hospital channels in Brandenburg. Small-batch breweries in Potsdam experiment with adaptogenic herb integration for wellness crossover positioning.
Lower Saxony
Elderly nutrition demand concentrates in Hanover and Brunswick, though retail coverage lags Bavarian penetration rates. The BVL's LFGB compliance infrastructure enables faster strain approval timelines than peripheral EU markets. Wolfsburg's automotive logistics networks are repurposing refrigerated capacity for probiotic beverage distribution.
Germany Probiotic Drinks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. Germany's probiotic drinks sector exhibits consolidated dairy conglomerates alongside fragmented craft fermentation boutiques. Three archetypes dominate: multinational refrigerated beverage platforms with legacy dairy infrastructure, regional kombucha specialists leveraging small-batch narratives, and precision fermentation technology adopters bridging biotechnology with traditional processing. Competitive moves center on cold chain capacity expansion into eastern federal states and portfolio diversification toward plant-based fermented bases.
Among Germany-based producers, Ehrmann SE anchors refrigerated logistics networks reaching into Saxony and Brandenburg, while ROY Kombucha exemplifies the craft specialist archetype through regional ingredient sourcing and Berlin health food store penetration. Danone occupies the multinational platform position, leveraging dairy heritage for supermarket shelf presence across federal retail chains. These three represent divergent strategic postures within a market where live culture stability claims and cold chain reliability determine competitive viability.
| Leading Market Players |
|---|
| Ehrmann SE |
| PepsiCo, Inc. |
| Danone |
| ROY Kombucha |
| Kanne Brottrunk |
| Yakult Honsha Co., Ltd. |
| Lifeway Foods, Inc. |
| Fischer Fermentgetränke GmbH |
| Nestlé |
| Others |
Pricing and Supply Chain Analysis
Germany's refrigerated autobahn corridors linking Bavarian production clusters to Berlin and Hamburg distribution hubs impose differential freight costs that concentrate supply-side power among dairies with captive logistics networks while fragmenting pricing power for craft kombucha brewers dependent on third-party cold chain providers.
Pricing Analysis
Volume-discount tiering structures separate Edeka and Rewe supermarket chains commanding pallet-level rebates from health food stores absorbing single-case premiums for organic-certified kombucha. Certification under EU organic labeling criteria and LFGB live culture stability documentation drive price spreads between refrigerated dairy-based kefir and ambient-stable plant-based alternatives. Cost compression in mid-tier kombucha intensifies because returnable glass systems under VerpackG face rising energy expenses. Health-conscious consumers in organic retail channels exhibit highest price sensitivity, while fitness enthusiasts seeking strain-specific formulations show lowest elasticity.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment from Switzerland and the Netherlands constrain Bavarian dairies piloting cell-culture protein hybridization. Raw milk supply from Upper Bavarian cooperatives, live culture strains from Danish biotech suppliers, and organic fruit concentrates from Italian processors anchor input dependencies. Single-source vulnerability concentrates in refrigerated logistics fleets serving eastern federal states. Distribution runs through multi-tier consolidation: Bavarian production hubs feed Düsseldorf terminals for western retail, while Berlin health food stores source directly from Potsdam craft breweries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's probiotic drinks sector is accelerating through precision fermentation disruption, with EU organic labeling amendments poised to reshape procurement eligibility across public hospital and care facility channels.
For Market Incumbents: Harden cold chain infrastructure into Saxony and Brandenburg through refrigerated fleet investment or third-party logistics partnerships, as elderly nutrition coverage gaps present vulnerability to craft entrants. Secure LFGB compliance documentation ahead of BVL enforcement tightening on ambient-stable claims, locking in retail shelf stability. Acquire precision fermentation capabilities to reduce raw milk cost exposure.
For New Entrants and Emerging Players: Build out direct subscription platforms targeting Hamburg and Cologne fitness enthusiasts with customized CFU concentration offerings unavailable in supermarket assortments. Exploit underdeveloped elderly nutrition coverage in eastern federal states through pharmacy channel partnerships. Position on adaptogenic herb integration for wellness crossover demand in Berlin health food stores.
For Investors and Strategic Acquirers: Regional craft kombucha specialists with established Berlin health food store penetration and organic certification infrastructure represent priority acquisition archetypes. Monitor BVL enforcement actions on live culture stability claims as inflection signal for consolidation pressure on non-compliant mid-tier producers. Long-term viability hinges on cold chain scalability and regulatory compliance infrastructure rather than brand narrative alone.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Capacity Expansion | Refrigerated logistics investment into Saxony unlocks elderly nutrition white space beyond Bavarian saturation. |
| Precision Fermentation Adoption | Cell-culture protein hybridization at Ingolstadt pilots stabilizes input costs against raw milk volatility. |
| EU Organic Certification Investment | Pending labeling amendments determine eligibility for German public hospital and care facility procurement channels. |
| Direct-to-Consumer Platform Launch | Subscription models in Hamburg and Cologne capture fitness enthusiast demand for strain-specific formulations. |
| Adaptogenic Ingredient Integration | Kombucha brewers in Potsdam differentiate via wellness crossover positioning with herbal fortification. |
Research Methodology
Cross-validation between fermentation science faculty at Freiburg University and BVL compliance officers anchors the qualitative findings on live culture stability enforcement trends. Primary interviews with Bavarian dairy plant managers, Alnatura category buyers, refrigerated logistics operators, and LFGB regulatory consultants combined with secondary validation from EU organic labeling amendment drafts, BVL guidance documents, and German customs trade data. Bottom-up strain-level production estimates triangulate against top-down retail velocity data from Nielsen refrigerated beverage audits.
Calibration against historical LFGB enforcement intensity and cold chain infrastructure buildout patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end-user archetype, distribution channel, and formulation type, with regional production hub differentiation. CAGRs derive from trend extrapolation moderated by regulatory friction coefficients. Forecast inputs incorporate precision fermentation technology adoption curves and VerpackG packaging cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive fleet expansion by Ehrmann SE or Danone into eastern federal states would shift outcomes. Material shifts in EU EFSA health claim restrictions or BVL live culture stability enforcement thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Rose Floral Water Market
Beverages
Soft Serves Market
Beverages
Drinking Water Market
Beverages
Fermented Foods and Beverages Market
Beverages
Sparkling Water Machine Market
Beverages
North America Yerba Mate Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Europe Smoothies Market
Beverages
Hydrogen Water Bottle Market
Beverages
Europe Probiotic Drinks Market
Beverages
Middle East Energy Drinks Market
Beverages
Victorian Jars Market