
 Wellness Water Market | 2026-2036
Wellness Water Market Size, Share, and Industry Trends Forecast 2026-2036
Wellness Water Market Analysis
The U.S. FDA's updated bottled water quality standards is realigning filtration and labeling costs for new entrants. Nestle S.A. leverages its global spring-source portfolio to sustain premium positioning across multiple continents. PepsiCo Inc. anchors volume through direct-store-delivery infrastructure that dominates North American convenience channels. Danone S.A. differentiates via specialized mineral compositions tailored to regional taste profiles and health positioning.
Wellness water comprises potable water enhanced with minerals, electrolytes, vitamins, or functional compounds, typically processed through reverse osmosis, ionization, or natural mineral infusion to achieve specified pH levels or nutritional profiles; its primary commercial purpose is to deliver hydration with claimed health benefits beyond basic thirst quenching. Functional water leads margin pools as consumers pay premiums for added vitamins, electrolytes, or adaptogens, while sparkling water competes aggressively with traditional soft drinks in restaurant and retail channels. Plastic bottles still dominate packaging type volumes, though glass bottles command higher per-unit margins in premium retail and hospitality settings.
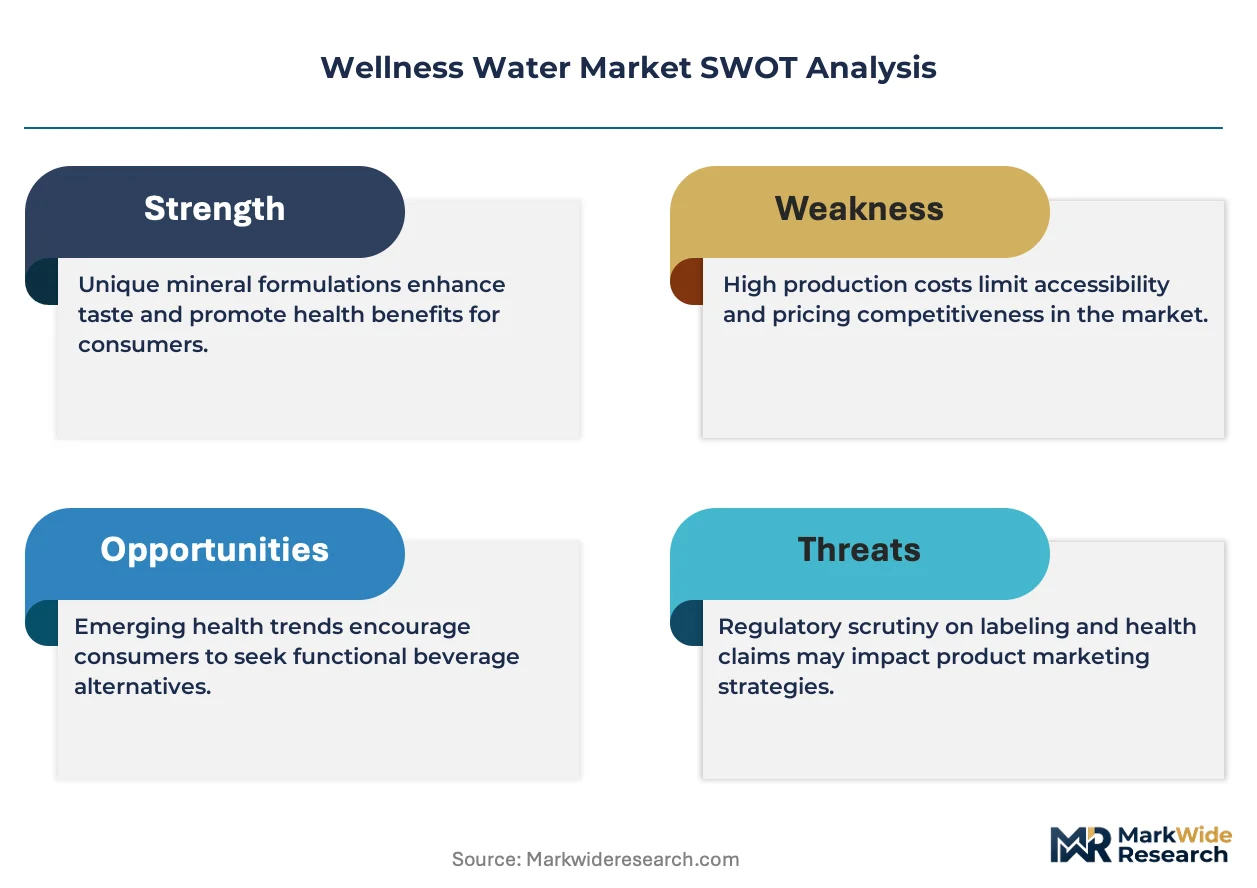
The EPA enforces source protection and contaminant limits that shape extraction site viability and treatment capital requirements, while the EU's REACH and single-use plastic directives are forcing packaging redesigns across export-oriented producers. Health Canada and the FSSAI in India maintain divergent additive approval lists that complicate global formulation strategies. Stakeholders must monitor pending regulations on microplastic thresholds and health-claim substantiation to avoid stranded inventory or reformulation costs.
Market Dynamics
Wellness water producers face intensifying purification technology costs as the U.S. FDA and EPA tighten contaminant thresholds and labeling substantiation requirements, forcing capital reallocation from marketing to compliance infrastructure.
Growth Catalysts
- Functional Additive Demand:Fitness and lifestyle consumers in Germany and China now prioritize electrolyte and adaptogen-infused waters, expanding the addressable consumer base beyond traditional hydration buyers.
- REACH Packaging Directives:The EU's single-use plastic regulations are accelerating rPET and glass adoption, creating first-mover advantages for producers with certified sustainable supply chains.
- Reverse Osmosis Advancement:Membrane filtration efficiency gains are reducing energy inputs per liter, enabling margin recovery for mid-tier brands competing against premium mineral sources.
Market Restraints
- Spring Source Concentration:Viable extraction sites cluster in specific alpine and volcanic regions, constraining new entrants without established water rights or long-term lease agreements.
- Aluminum Input Volatility:Can packaging adoption faces cost pressure from aluminum tariff fluctuations and alloy availability, complicating format diversification strategies.
- FSSAI Additive Divergence:India's divergent approved ingredient lists versus FDA and EFSA standards force parallel formulation runs, inflating inventory complexity for exporters.
Strategic Opportunities
- Direct-to-Consumer Hydration Subscriptions:Urban households in China and the United States are adopting recurring delivery models, bypassing traditional retail slotting fees and building proprietary customer data assets.
- Adaptogen Convergence:Functional water formulations incorporating ashwagandha and L-theanine are capturing crossover demand from supplement and beverage categories simultaneously.
- Health Canada Natural Health Product Pathway:The regulatory framework for functional claims provides a template for brands seeking differentiated positioning in North American pharmacy and wellness retail channels.
Industry Challenges
- Microplastic Detection Capability Gap:Analytical laboratories with ISO 17025 accreditation for sub-micron particle quantification remain scarce, delaying compliance verification for premium glass and aluminum formats.
- pH Stability Shelf-Life Engineering:Maintaining advertised alkaline levels through temperature-variable distribution requires buffer system R&D that strains technical teams without beverage chemistry specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellness Water Market |
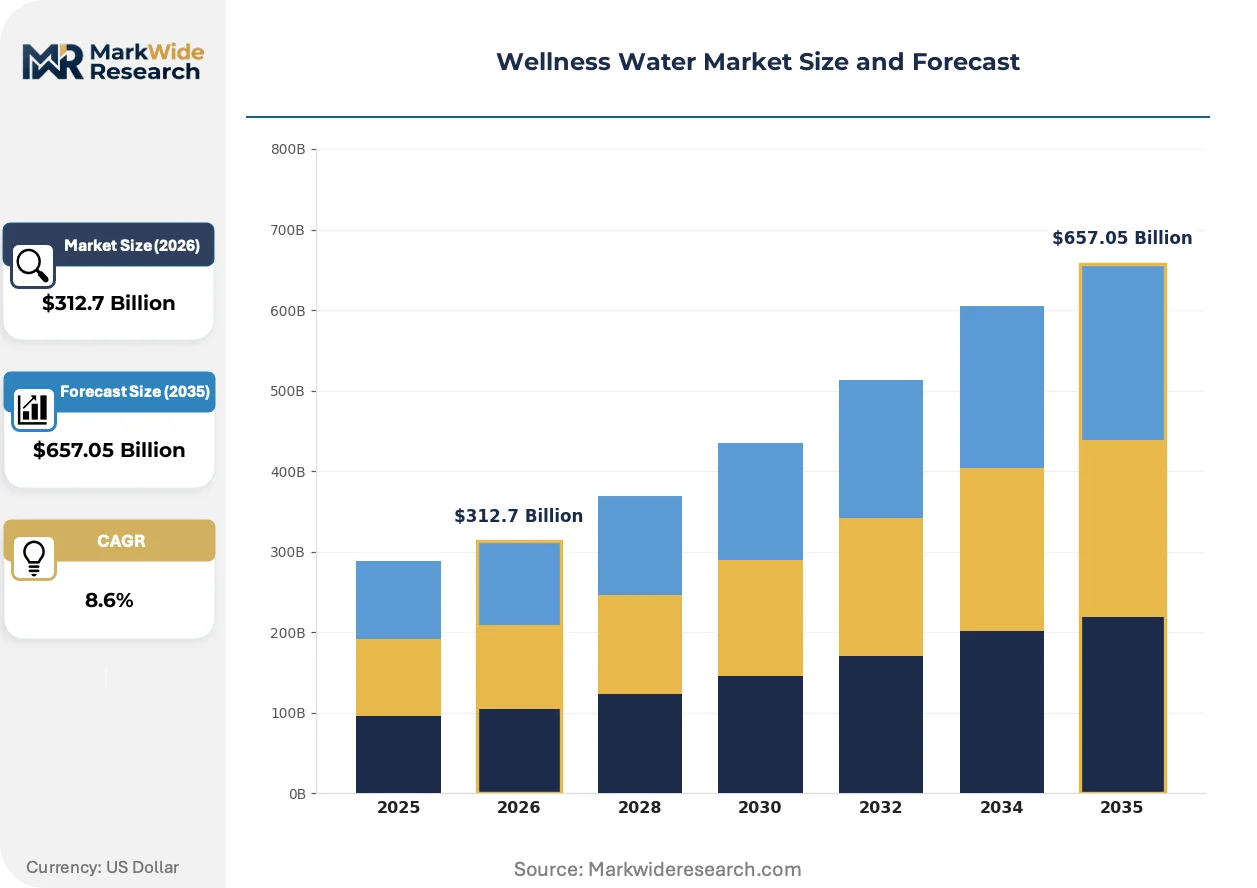
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Water, Flavored Water, Sparkling Water, Functional Water Distribution Channel: Retail Stores, Online Platforms, Vending Machines, Health Clubs End User: Health Conscious Consumers, Athletes, Senior Citizens, Families Packaging Type: Plastic Bottles, Glass Bottles, Tetra Packs, Bulk Containers |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Nestle S.A., Danone S.A., Keurig Dr Pepper, Hint Water Inc, The Alkaline Water Co., Tata Group, Nirvana Water Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellness Water Market Emerging Trajectories
Electrolyte personalization and on-demand mineral dosing systems are fragmenting the traditional one-formula-fits-all model, while regulatory scrutiny of health claims forces substantiation investments that favor scaled producers.
Electrodialysis remineralization is overtaking conventional limestone bed filtration for precise mineral profile control. Mid-tier wellness brands in Germany and the United States are adopting stack-based ion exchange to replicate regional spring compositions without geographic dependency. This precision is compressing the traditional advantage of heritage source-based positioning.
The EU's Single-Use Plastics Directive and accompanying Extended Producer Responsibility frameworks are mandating recycled content minimums and deposit-return infrastructure. Export-oriented bottlers must redesign label adhesives and cap tethering systems to maintain EU market access. Premium glass formats are gaining share in hospitality channels as operators preempt compliance costs.
Subscription-based hydration programs with personalized mineral dosing are displacing conventional retail replenishment cycles. Fitness studios and corporate wellness programs in China and the United States are contracting directly with regional bottlers for customized electrolyte blends. This channel shift concentrates volume with flexible co-manufacturers capable of small-batch formulation changes.
Wellness Water Market Segmentation
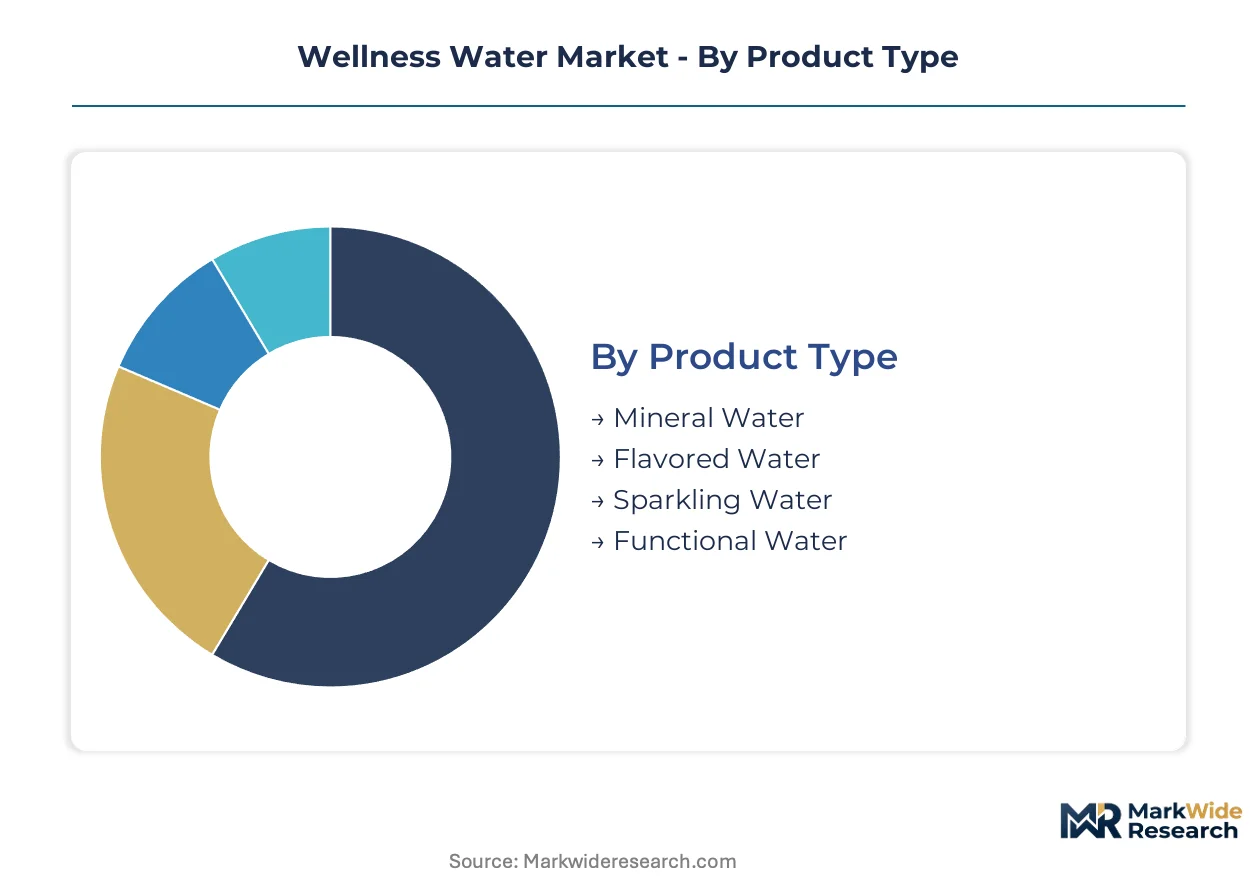
Wellness water segmentation reveals how purification technology, packaging compliance costs, and channel access barriers create divergent margin structures across product formats. Producers must align segment-specific positioning with regulatory requirements in the United States, Germany, and China to avoid stranded capacity.
Product Type:
Supply concentration for functional and enhanced water formulations clusters with producers possessing certified mineral dosing capabilities and validated health-claim substantiation infrastructure.
- Mineral Water:Naturally sourced or artificially remineralized water containing specified calcium, magnesium, and bicarbonate levels. Demand concentrates in German pharmacy channels and Chinese premium retail where consumers verify TDS specifications against regional spring benchmarks. Source certification and extraction rights create supply-side moats for established bottlers.
- Functional Water:Water enhanced with vitamins, electrolytes, adaptogens, or probiotics through post-filtration dosing. Fitness studios in the United States and corporate wellness programs in China now specify custom electrolyte profiles, compressing traditional retail replenishment cycles. Formulation flexibility and small-batch capability determine supplier selection.
- Flavored Water:Low- or zero-calorie water with natural or artificial flavoring systems, typically positioned between plain water and soft drinks. FSSAI-approved flavor additive lists constrain export formulations targeting Indian households.
- Sparkling Water:Carbonated still or mineral water competing directly with traditional soft drinks in restaurant and hospitality channels. On-premise fountain systems in German urban centers are displacing packaged formats.
Today's leader: Functional Water. Tomorrow's challenger: Sparkling Water.
Distribution Channel:
Cost tier stratification separates high-touch retail placement from automated replenishment models, with capital requirements scaling from slotting fees to last-mile logistics infrastructure.
- Retail Stores:Supermarkets, convenience stores, and specialty beverage retailers commanding placement fees and promotional calendar coordination. United States direct-store-delivery networks dominate shelf positioning through refrigerated cold-chain reliability.
- Online Platforms:E-commerce marketplaces and direct-to-consumer websites enabling subscription-based replenishment with personalized mineral dosing. Urban households in China bypass traditional retail through platform-integrated recurring delivery, building proprietary customer data assets for formulation refinement.
- Vending Machines:Automated dispensing units in transit hubs, offices, and educational institutions. High-touchpoint density in Japanese metropolitan corridors supports premium pricing for temperature-controlled formats.
- Health Clubs:Fitness centers, yoga studios, and athletic facilities contracting directly for branded co-manufactured electrolyte blends. German boutique fitness operators specify pH stability through variable climate conditions.
Volume concentrates in Retail Stores. Margin expansion concentrates in Online Platforms.
End User:
Application-specific hydration requirements fragment formulation strategies, with performance-oriented users demanding validated electrolyte recovery metrics versus general wellness positioning.
- Health Conscious Consumers:Individuals prioritizing clean-label hydration with verified contaminant thresholds and transparent sourcing. United States consumers cross-reference EPA Safe Drinking Water Act compliance with third-party purity certifications.
- Athletes:Competitive and recreational performers requiring sodium, potassium, and magnesium replenishment calibrated to sweat-rate loss. Chinese marathon training communities specify osmolality ranges for gastric emptying optimization.
- Senior Citizens:Demographic segment prioritizing mineral bioavailability and medication interaction safety. German pharmacy-channel positioning requires Health Canada-equivalent natural health product substantiation.
- Families:Household purchasers balancing cost-per-liter with multi-generational safety and convenience requirements. Bulk container adoption in Indian metropolitan households reduces per-unit packaging waste.
Revenue concentration favors Athletes. Penetration headroom sits with Senior Citizens.
Packaging Type:
Margin tier separation between commodity formats and compliance-forward alternatives accelerates as EU REACH directives and pending microplastic thresholds reshape capital allocation.
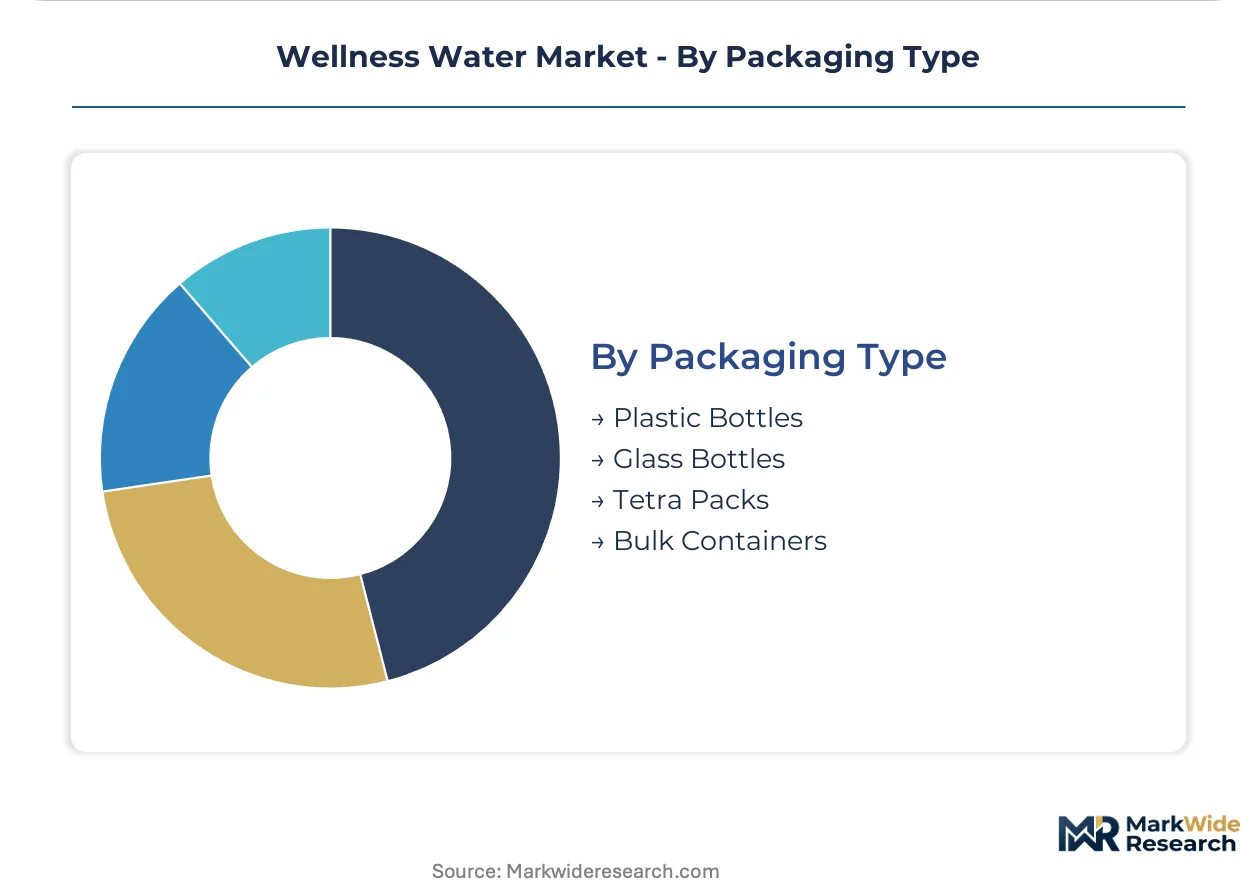
- Plastic Bottles:PET and rPET containers dominating unit volumes with lightweight logistics efficiency. EU Single-Use Plastics Directive recycled content minimums are forcing label adhesive and cap tethering redesigns for export-oriented producers.
- Glass Bottles:Premium-positioned packaging commanding hospitality channel placement and deposit-return system compatibility. German restaurant operators preempt compliance costs through format conversion ahead of regulatory deadlines.
- Tetra Packs:Aseptic carton formats with lower carbon footprint credentials in lifecycle assessments. Limited penetration in wellness water due to oxygen barrier performance constraints for pH-sensitive formulations.
- Bulk Containers:Refillable dispensers and bag-in-box systems for commercial and household high-volume consumption. Corporate wellness programs in the United States specify stainless-steel reservoir compatibility.
Volume dominance: Plastic Bottles. Regulatory tailwind: Glass Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized beverage chemists and filtration engineers concentrate in Germany's Rhine-Ruhr corridor, China's Yangtze Delta manufacturing belts, and the U.S. Great Lakes water technology hubs. These talent clusters anchor formulation innovation and regulatory compliance infrastructure for wellness water producers.
United States
Fitness studios and corporate wellness programs in Los Angeles and New York Metro drive demand for custom electrolyte profiles. The FDA's updated bottled water quality standards force capital reallocation toward compliance infrastructure. Direct-store-delivery networks dominate refrigerated cold-chain reliability in Chicago and Atlanta distribution corridors.
Germany
Pharmacy-channel consumers in Munich and Hamburg verify TDS specifications against regional spring benchmarks. REACH and single-use plastic directives mandate recycled content minimums and deposit-return infrastructure. Boutique fitness operators in Berlin specify pH stability through variable climate conditions.
China
Marathon training communities in Shanghai and Beijing specify osmolality ranges for gastric emptying optimization. SAMR maintains divergent additive approval lists versus FDA standards. Platform-integrated recurring delivery in Shenzhen builds proprietary customer data assets for formulation refinement.
India
Metropolitan households in Mumbai and Delhi shift from sugary beverages to wellness-oriented hydration. FSSAI-approved flavor additive lists constrain export formulations targeting Indian consumers. Bulk container adoption reduces per-unit packaging waste in Bangalore corporate campuses.
Canada
Senior citizens in Toronto and Vancouver prioritize mineral bioavailability and medication interaction safety. Health Canada's natural health product pathway provides differentiated positioning in pharmacy channels. Western Canada spring extraction sites face EPA-equivalent source protection enforcement.
Wellness Water Market Vendor Landscape
The competitive structure tilts toward diversified beverage conglomerates with captive distribution infrastructure. Three tiers separate heritage mineral source owners, functional formulation specialists, and private-label co-manufacturers. Dominant competitive moves include portfolio diversification into adaptogen-infused lines and strategic partnerships with fitness channel operators.
Among diversified beverage conglomerates, The Coca-Cola Company, PepsiCo Inc., and Nestle S.A. exemplify archetypes spanning global spring-source portfolios, direct-store-delivery dominance, and premium mineral positioning respectively. Danone S.A. occupies a specialist tier focused on regional taste profile tailoring. Keurig Dr Pepper represents the mid-market consolidation vector.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Nestle S.A. |
| Danone S.A. |
| Keurig Dr Pepper |
| Hint Water Inc |
| The Alkaline Water Co. |
| Tata Group |
| Nirvana Water Sciences |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmacy-channel mineral water and convenience-store functional water manifests in parallel supply chain configurations. Premium German and Chinese pharmacy formats command source-provenance premiums through alpine extraction rights and TDS-verified spring portfolios. Mass-market functional water competes on electrodialysis efficiency and rPET packaging compliance costs.
Pricing Analysis
Bundled subscription services versus unbundled retail transactional purchases split pricing architectures across wellness water tiers. Three-tier pricing structure across premium, standard, and economy levels reflects source certification status, with Health Canada-equivalent natural health product substantiation commanding pharmacy placement premiums. Pricing pressure stems from EU REACH recycled-content mandates inflating rPET and glass conversion costs. Corporate wellness programs in China exhibit lowest price sensitivity due to bulk contracting power, while Indian metropolitan households demonstrate highest sensitivity to per-liter packaging economics.
Supply Chain Analysis
Domestic-content rules in China and India's FSSAI additive approval frameworks are reshaping regional formulation sourcing. Spring extraction concentrates in Germany, China, and the United States, with alpine and volcanic water rights clustering in Bavarian and Yangtze Delta corridors. Raw material dependencies span membrane filtration systems, mineral dosing compounds, and pharmaceutical-grade buffer chemicals. Single-source vulnerability runs through certified analytical laboratories for ISO 17025 microplastic quantification. Distribution runs through direct-store-delivery networks in North America and platform-integrated subscription logistics in Chinese urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wellness water functions as a stable compounder anchored by irreversible consumer migration from sugary beverages toward functional hydration. Regulatory tightening on health-claim substantiation reinforces incumbent advantages while fragmenting marginal competitors.
For Market Incumbents: Cement source-provenance advantages through long-term alpine and volcanic water rights renewals in Germany and China. Expand electrodialysis capacity to compress mid-tier competitors' mineral replication capabilities. Defend against adaptogen-infused entrants by accelerating Health Canada natural health product pathway certifications for existing electrolyte portfolios.
For New Entrants and Emerging Players: Senior citizens in Canadian and German pharmacy channels represent an underserved buyer archetype with mineral bioavailability priorities and low incumbent loyalty. Target corporate wellness programs in Shenzhen and Dallas-Fort Worth with customizable osmolality specifications. Bypass retail slotting fees through direct-to-consumer subscription platforms with personalized mineral dosing interfaces.
For Investors and Strategic Acquirers: Consolidation pressure builds where FSSAI-EU-FDA formulation divergence forces parallel inventory runs that strain mid-tier working capital. Long-term viability favors producers with certified sustainable supply chains and small-batch co-manufacturing flexibility. Acquisition targets include regional bottlers with Health Canada-equivalent substantiation infrastructure and established fitness channel contracts. Watch for EU microplastic threshold finalization as margin compression inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Source Rights Acquisition | Long-term alpine extraction leases in Germany secure pharmacy-channel TDS verification advantages. |
| Electrodialysis Scale-Up | Precision mineral profile control displaces heritage spring dependency for mid-tier positioning. |
| Subscription Platform Launch | Recurring delivery models in China and the United States build proprietary customer data assets. |
| Adaptogen Formulation Pipeline | Ashwagandha and L-theanine integration captures crossover demand from supplement categories. |
| rPET Supply Chain Certification | EU REACH compliance for recycled content minimums preserves export market access. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged beverage chemists, pharmacy category managers, fitness studio procurement leads, and regulatory affairs directors at spring extraction operators. Secondary validation drew from FDA bottled water quality standards filings, EPA Safe Drinking Water Act enforcement records, EU REACH directive implementation guidance, and FSSAI additive approval registers. Bottom-up volume modeling across purification technology tiers and top-down macroeconomic anchoring were cross-checked for consistency.
Historical reference periods established baseline penetration rates for functional versus mineral water formats across the projection horizon. Segmentation dimensions included product type, distribution channel, end-user application, and packaging compliance tier. CAGRs were derived from elasticity-calibrated demand curves incorporating urbanization patterns and regulatory phase-in schedules. Industry-specific inputs encompassed membrane filtration cost curves and deposit-return system adoption trajectories.
Underlying measurement precision varies by segment; functional water with validated health claims carries tighter precision than flavored water with discretionary purchase patterns. Forecasts reflect assumptions on additive approval harmonization timelines and aluminum tariff stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Drinking Bottled Mineral Water Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Global Soda Maker Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Europe Smoothies Market
Beverages
Germany Probiotic Drinks Market
Beverages
GCC Coconut Water Market
Beverages
Europe Beverage Market
Beverages
Powdered Beverages Market
Beverages
Crystal Boba Market
Beverages
Coconut Water Market
Beverages
Grab and Go Bottles Market
Beverages
South America Mate Market
Beverages
Sparkling Juice Drinks Market
Beverages
GCC Juice Market
Beverages
Craft Soda Market