
 Asia-Pacific Vinegar Market | 2026-2036
Asia-Pacific Vinegar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vinegar Market Outlook
Chinese artisanal producers is realigning capacity toward aged Shanxi-style fermentation, shifting supply-side investment away from mass white vinegar output. Mizkan Holdings Co. Ltd. leverages its rice vinegar heritage to dominate Japan's premium condiment shelf space. Jiangsu Hengshun anchors the Yangtze River Delta with vertically integrated grain-to-bottle operations. Shanxi Shuita Vinegar competes through protected geographical indication status and heritage process certification.
Vinegar is an aqueous solution containing acetic acid (typically 4-8% by volume) produced through double fermentation of ethanol substrates, used as a food preservative, flavoring agent, and pH regulator across commercial and industrial applications. Balsamic and rice variants command the strongest margin pools due to aging requirements and origin-linked scarcity, while apple cider vinegar is expanding fastest through health-positioned retail channels. The barrel and bottle packaging formats still dominate institutional procurement, though sachet formats are penetrating South Asian household segments where single-use affordability shapes purchase behavior.
China's SAMR enforces GB standards on acetic acid thresholds and additive disclosure, while India's FSSAI mandates labeling integrity for fermented condiments sold through modern retail. Japan's METI coordinates with JIS standards bodies to preserve traditional brewing nomenclature against diluted imports. Stakeholders must monitor how Australia's national food regulator calibrates import parity rules as Pacific trade flows intensify.
Market Dynamics
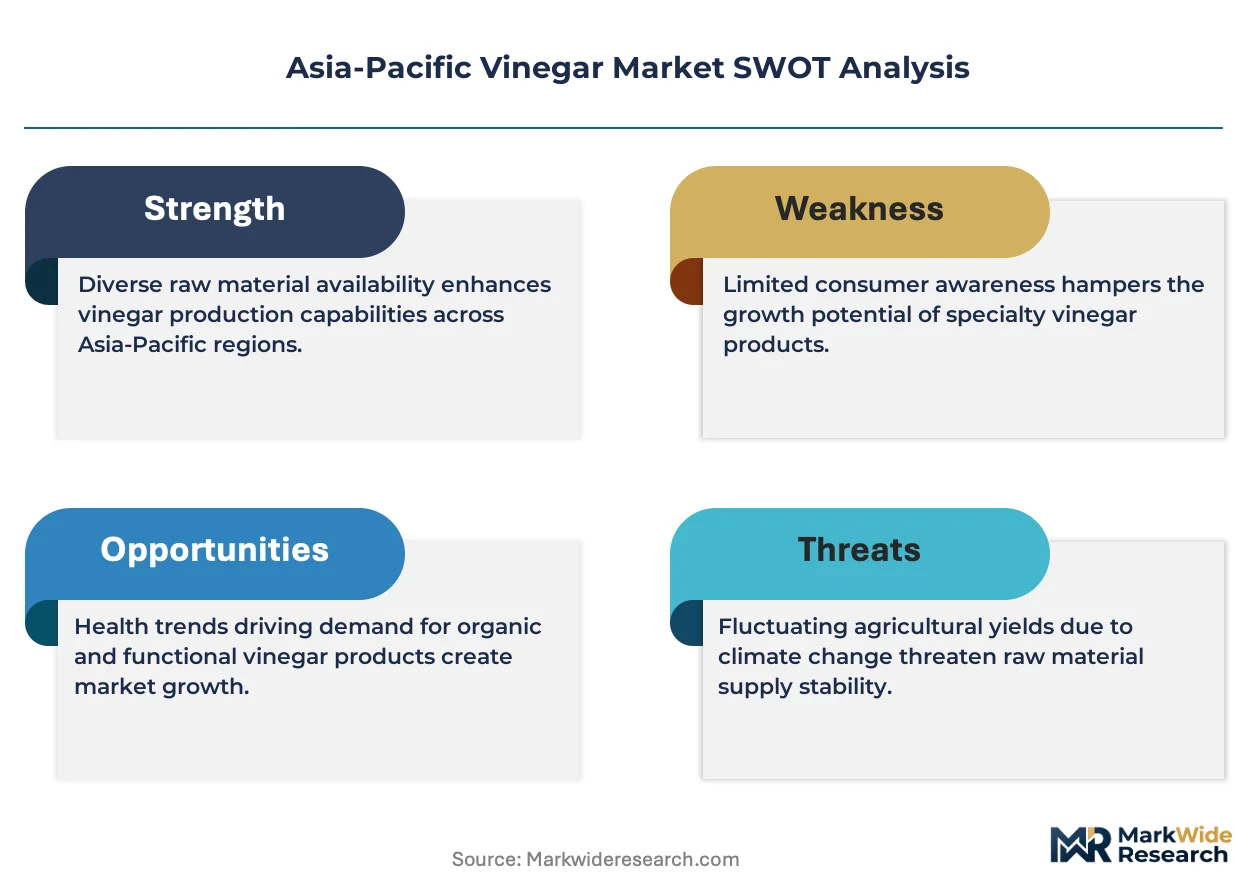
China's SAMR is tightening GB standards on acetic acid thresholds and additive disclosure, forcing fermentation-based producers to recalibrate aging protocols and quality-assurance systems across the supply base.
Growth Catalysts
- Urban retail corridor expansion:India's modern trade formats displace traditional loose-vinegar channels in Delhi, Mumbai, and Bangalore, consolidating branded purchase behavior.
- FSSAI labeling mandates:India's fermented condiment regulations drive integrity investments by domestic packagers seeking shelf space in organized retail.
- Food service procurement scale-up:Southeast Asian restaurant chains expand fermentation-based cuisine menus, pulling bulk vinegar contracts from centralized distributors.
Market Restraints
- Grain input cost volatility:Sorghum and rice price swings in the Yangtze River Delta compress margin buffers for heritage-process producers.
- Supply concentration risk:Shanxi Province's protected geographical indication producers control aged-stock inventory, creating procurement bottlenecks for premium-positioned brands.
- Technical limitation:Traditional solid-state fermentation requires 12-24 month aging cycles, constraining volume responsiveness to demand spikes.
Strategic Opportunities
- Vietnam underpenetration:Northern Vietnamese urban households show rising condiment premiumization, with modern trade vinegar SKUs below 15% penetration.
- Health-positioned channel innovation:Australian pharmacy and wellness retail chains expand apple cider vinegar SKUs, bypassing conventional grocery gatekeepers.
- METI-JIS nomenclature protection:Japan's traditional brewing certification creates import barriers that domestic heritage producers can leverage for margin defense.
Industry Challenges
- Master brewer talent scarcity:Shanxi-style fermentation expertise concentrates among aging practitioners, with limited apprenticeship pipeline replenishment.
- Certification timeline compression:GB standard compliance audits for SAMR approval extend 8-14 months, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vinegar Market |
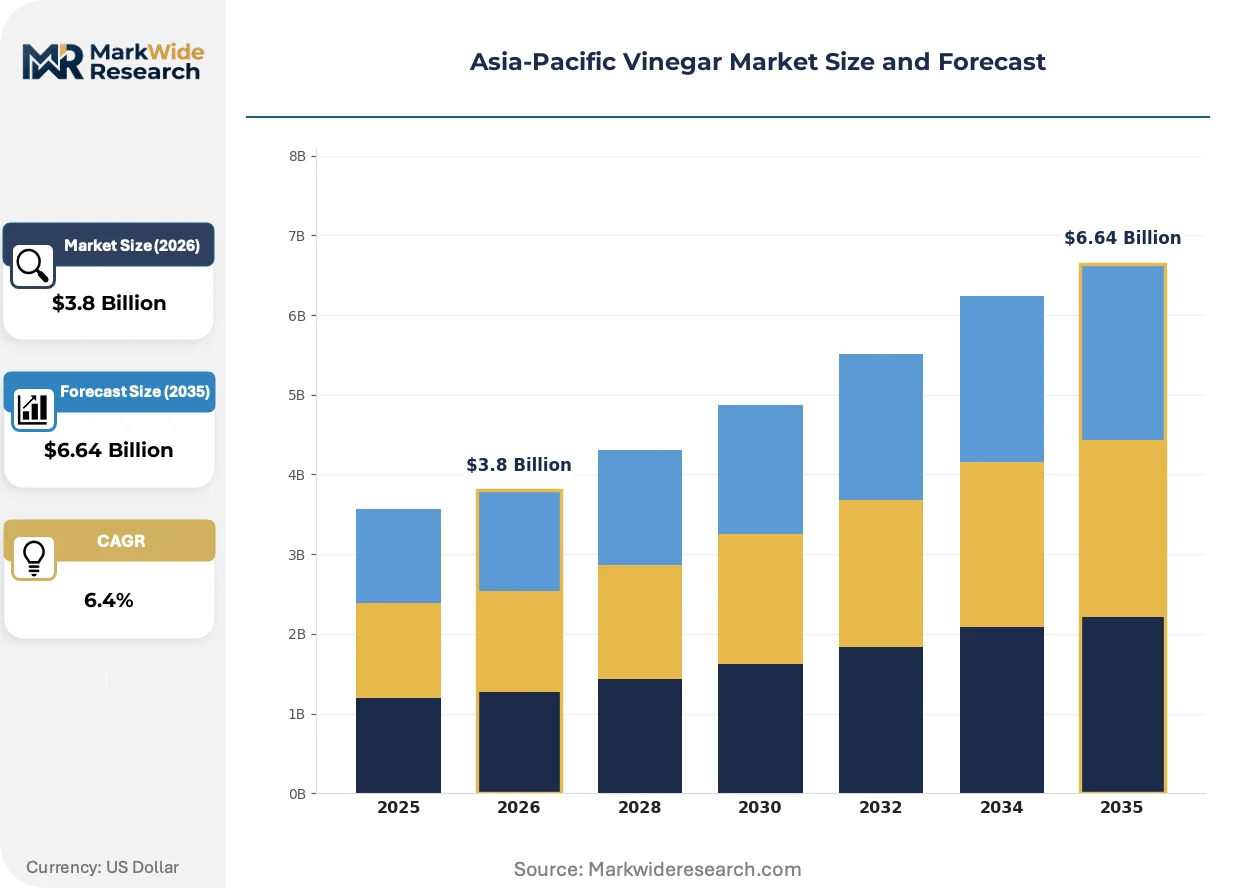
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsamic, Apple Cider, White Wine, Rice End User: Food Industry, Food Service, Retail, Household Packaging Type: Bottle, Barrel, Sachet, Drum Distribution Channel: Online, Retail Stores, Supermarkets, Direct Sales |
| Companies Covered | Australian Vinegar, Carl Kühne KG, Mizkan Holdings Co. Ltd., HPMC, Borges International Group S.L., Shanxi Shuita Vinegar, Jiangsu Hengshun, St. Botanica, The Kraft Heinz Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vinegar Market Strategic Shifts
Controlled fermentation technologies and packaging format experimentation are compressing production cycles while expanding access points. These shifts reconfigure how heritage producers defend positioning against industrial scale competitors.
Automated temperature-controlled fermentation is converging with IoT sensor arrays to enable real-time acetic acid monitoring. Mid-scale Japanese producers deploy these systems to reduce batch-to-batch variation without abandoning JIS-certified process nomenclature. The technology is converging with heritage branding requirements, allowing simultaneous quality consistency and origin-story preservation.
China's SAMR GB standard revisions mandate additive disclosure down to 0.01% thresholds for imported and domestic vinegar alike. Packagers must redesign label artwork and reformulate color-stabilizing inputs to maintain shelf presence. Aged balsamic and rice variants face the steepest compliance costs due to complex barrel-transfer histories.
Single-serve sachet formats now penetrate South Asian household segments where 200ml bottle price points previously excluded mass-market participation. Modern trade distributors in Indonesia and Philippines prioritize sachet SKUs for kirana store penetration. Procurement behavior shifts most visibly in tier-2 Indian cities where monthly condiment budgeting favors unitized affordability over bulk economy.
Asia-Pacific Vinegar Market Segmentation
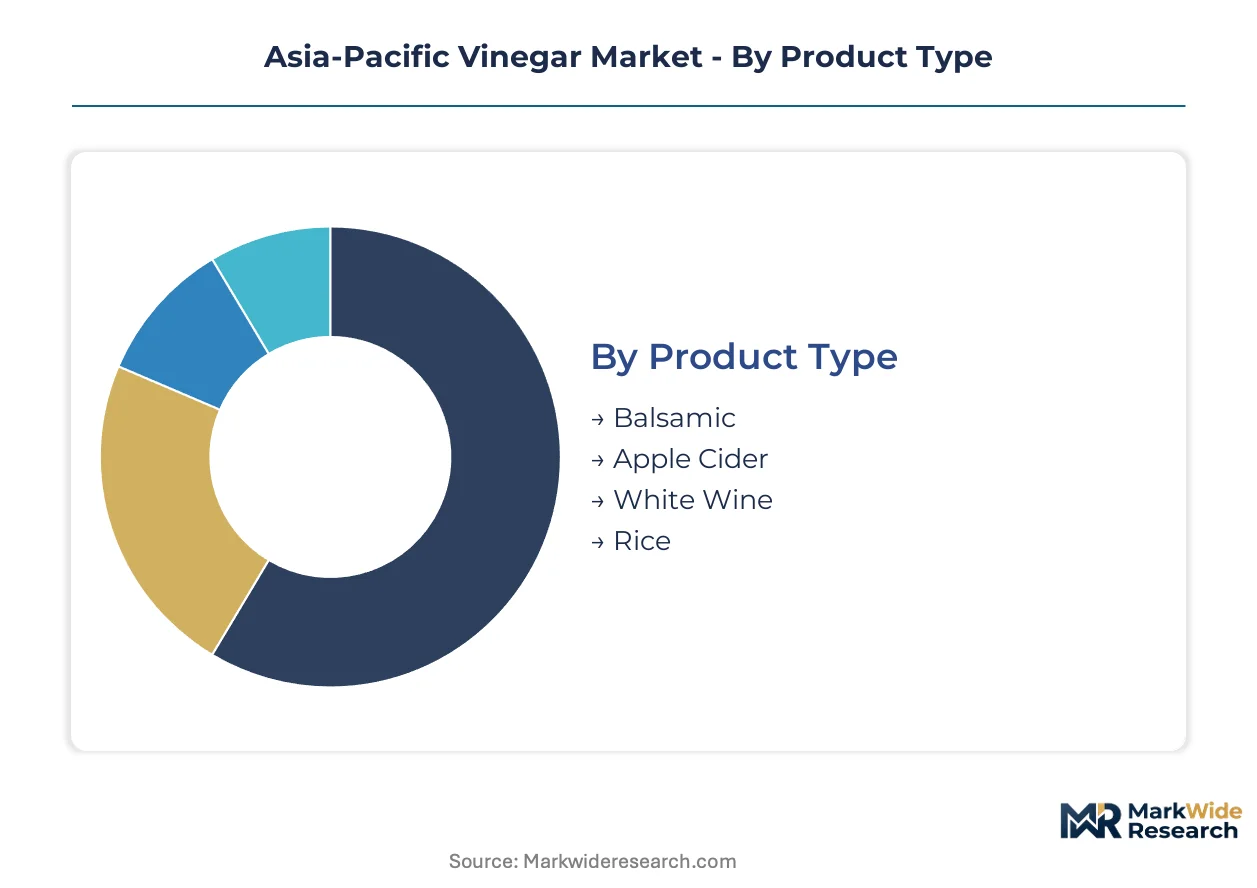
Vinegar segmentation in Asia-Pacific reflects divergent consumption rituals across fermentation traditions and modern trade formats. Category boundaries shift as health-positioned variants penetrate pharmacy channels while heritage producers defend origin-linked scarcity. Understanding these divides exposes where margin pools concentrate versus where volume expansion occurs.
Product Type:
Replacement cycles vary sharply by aging protocol, with barrel-matured stocks requiring multi-year inventory commitment versus rapid-turn industrial white variants.
- Balsamic:Aged grape must fermented through sequential acetification in wooden barrels, typically 12-25 years for tradizionale grades. Demand concentrates in Japan's premium condiment retailers and Australia's specialty grocers, where METI-JIS nomenclature protection and import scarcity sustain price premiums.
- Apple Cider:Fermented apple juice with 5-6% acetic acid, often unpasteurized for wellness-positioned SKUs. Australian pharmacy chains and Indian urban wellness platforms are pulling this segment fastest, bypassing conventional grocery gatekeepers with functional health claims.
- White Wine:Fast-fermentation grain or ethanol-derived vinegar with minimal aging. China's mass-market food processors and Southeast Asian pickling operations dominate procurement.
- Rice:Double-fermented rice substrate following JIS-certified brewing protocols. Mizkan Holdings and domestic Japanese artisans anchor supply, with heritage process certification limiting import substitution.
White Wine sits at the top of the volume ranking, with Apple Cider climbing the fastest.
End User:
Cost tier stratification separates bulk fermentation contracts from premium retail positioning, with food service operators capturing scale advantages unavailable to household channels.
- Food Industry:Bulk acetic acid procurement for sauce manufacturing, pickling operations, and preservative applications. China's Yangtze River Delta processing clusters and Vietnam's emerging condiment factories drive contract concentration.
- Food Service:Restaurant chains and centralized kitchen operations sourcing 20-200 liter formats. Southeast Asian fermentation-based cuisine expansion—Vietnamese nuoc mam derivatives, Korean jeotgal preparations—pulls volume through regional distributors.
- Retail:Branded bottle and specialty formats through modern trade. India's FSSAI-compliant packagers displace loose-vinegar channels in Delhi and Mumbai corridors.
- Household:Sachet and small-format procurement in South Asian tier-2 cities. Monthly condiment budgeting favors unitized affordability over bulk economy in Indonesia and Philippines kirana stores.
Food Industry commands the largest contract values, though Food Service is expanding most quickly through Southeast Asian chain proliferation.
Packaging Type:
Application requirements dictate format selection, with shelf stability and handling logistics overriding unit cost in institutional settings.
- Bottle:Standard 200-500ml glass or PET formats for retail shelf presence. China's SAMR GB labeling mandates force artwork redesigns for additive disclosure compliance.
- Barrel:Wooden casks for aging balsamic and heritage rice variants. Shanxi Province's protected geographical indication producers control aged-stock inventory, creating procurement bottlenecks.
- Sachet:Single-serve 10-50ml foil pouches. Penetration accelerates in Indian tier-2 cities and Indonesian traditional trade where cash-flow constraints shape purchase behavior.
- Drum:Industrial 200-liter formats for food manufacturing. Direct sales relationships with Yangtze River Delta processors dominate this channel.
Bottle formats retain volume leadership across retail channels, while Sachet is gaining share fastest through South Asian modern trade penetration.
Distribution Channel:
Customer type fragmentation—urban wellness seekers versus rural price-sensitive households—forces parallel channel strategies with minimal overlap.
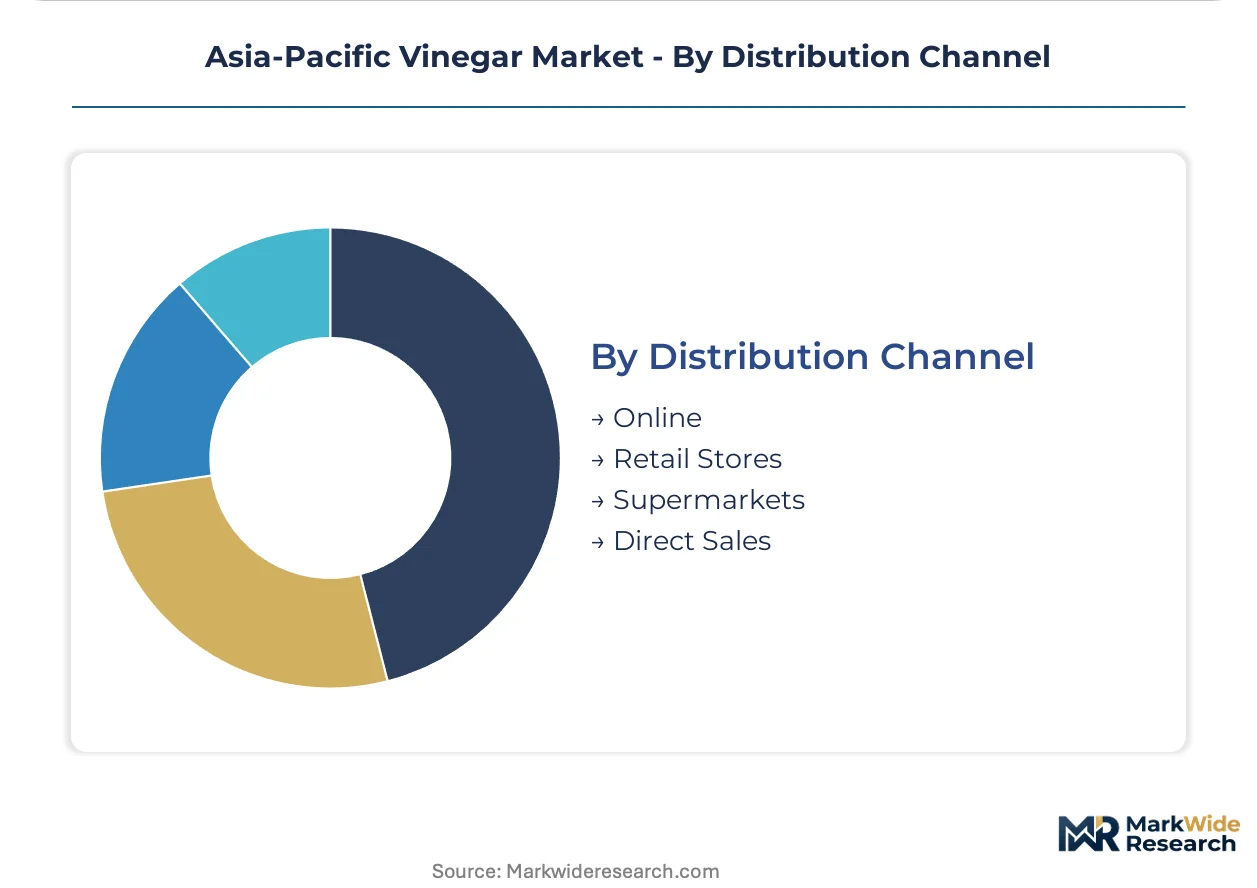
- Online:E-commerce platforms and direct-to-consumer wellness portals. Australian pharmacy chains and Indian urban platforms expand apple cider SKUs through this channel.
- Retail Stores:Traditional trade and kirana networks. Indonesia and Philippines prioritize sachet SKUs here for household affordability.
- Supermarkets:Modern trade formats with FSSAI-mandated labeling integrity. India's organized retail consolidation favors branded packagers with compliance infrastructure.
- Direct Sales:Bulk contracts with food manufacturers and restaurant chains. Southeast Asian fermentation-cuisine expansion pulls volume through centralized distributors.
Supermarkets dominate branded vinegar turnover, with Online showing the steepest expansion trajectory through health-positioned SKU proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions with lower compliance burdens, as China's SAMR GB standard revisions extend audit timelines and elevate formulation costs for heritage-process producers.
China
Shanxi Province's protected geographical indication producers command aged-stock inventory premiums, while Yangtze River Delta processors face grain input cost volatility from sorghum and rice price swings. SAMR enforces tightening GB standards on acetic acid thresholds and additive disclosure down to 0.01% thresholds. Jiangsu Hengshun anchors vertically integrated grain-to-bottle operations across the delta corridor.
Japan
Mizkan Holdings leverages rice vinegar heritage to dominate premium condiment shelf space in Tokyo and Osaka metropolitan markets. METI coordinates with JIS standards bodies to preserve traditional brewing nomenclature against diluted imports. Automated temperature-controlled fermentation with IoT sensor arrays enables real-time acetic acid monitoring at mid-scale Nagoya-area facilities.
India
Urban retail corridors in Delhi, Mumbai, and Bangalore displace traditional loose-vinegar channels as modern trade formats consolidate branded purchase behavior. FSSAI mandates labeling integrity for fermented condiments sold through organized retail. Tier-2 cities favor sachet formats where monthly condiment budgeting prioritizes unitized affordability.
Australia
Pharmacy and wellness retail chains expand apple cider vinegar SKUs, bypassing conventional grocery gatekeepers with functional health claims. TGA calibration of import parity rules shapes Pacific trade flow intensity. Specialty grocers in Sydney and Melbourne concentrate demand for aged balsamic variants.
Vietnam
Northern Vietnamese urban households show rising condiment premiumization, with modern trade vinegar SKUs below 15% penetration. Restaurant chains expand fermentation-based cuisine menus, pulling bulk contracts from centralized distributors. Ho Chi Minh City and Hanoi corridors represent underexploited expansion terrain for branded packagers.
Asia-Pacific Vinegar Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wellness-positioned channel innovation and geographic white-space capture. The market structure bifurcates between heritage-process artisans with protected geographical indication status and industrial-scale fermenters optimized for rapid-turn output. Three archetypes dominate: vertically integrated grain-to-bottle operators, JIS-certified traditional brewers, and pharmacy-channel wellness marketers. Competitive moves concentrate on certification timeline navigation and sachet format penetration for South Asian household segments.
Within the heritage-process tier, Shanxi Shuita Vinegar and Jiangsu Hengshun exemplify Chinese geographical indication defenders, while Mizkan Holdings Co. Ltd. anchors Japanese JIS-certified brewing nomenclature. These three occupy positions that merge origin-story preservation with quality-assurance infrastructure, representing how traditional fermentation expertise converges with modern compliance requirements. Their market presence illustrates the tension between aging-protocol scarcity and volume responsiveness constraints.
| Leading Market Players |
|---|
| Australian Vinegar |
| Carl Kühne KG |
| Mizkan Holdings Co. Ltd. |
| HPMC |
| Borges International Group S.L. |
| Shanxi Shuita Vinegar |
| Jiangsu Hengshun |
| St. Botanica |
| The Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals are tightening energy-intensity standards for fermentation facilities, gating both qualified supply access and premium-tier pricing power for heritage-process producers who can demonstrate compliant aging infrastructure.
Pricing Analysis
Distributor margin layers in Southeast Asian food service channels compress as centralized procurement scales consolidate contract leverage. Three-tier pricing structure across aged heritage, standard barrel-matured, and rapid-turn industrial grades separates Shanxi PGI-certified stock from Yangtze Delta mass output. Cost compression in white vinegar tiers is intensifying because sorghum input volatility erodes processor buffers. Household segments in South Asian tier-2 cities show highest price sensitivity, while Japanese premium retailers absorb JIS-certified rice vinegar premiums with minimal volume elasticity.
Supply Chain Analysis
Master brewer availability in Shanxi Province and the Yangtze River Delta constrains output scaling for traditional solid-state fermentation operations. Supply concentrates in China, Japan, and Vietnam, with grain substrate sourcing drawing from domestic sorghum reserves and imported rice consignments. Single-source vulnerability around Shanxi's protected geographical indication aged-stock inventory creates procurement bottlenecks for premium-positioned brands. Distribution runs through modern trade consolidators in India and Australia, regional distributors across Southeast Asian food service networks, and kirana store intermediaries in Indonesian and Philippine household channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific vinegar market compounds steadily as urban retail corridor expansion across India and Southeast Asia displaces loose-vinegar channels with branded purchase behavior.
For Market Incumbents: Extend heritage-process certification investments to defend JIS and PGI positioning against industrial-scale fermenters entering premium tiers through automated temperature-controlled systems. Deepen backward integration into grain cultivation in the Yangtze River Delta to buffer sorghum price volatility. Capture sachet format shelf space in Indonesian and Philippine kirana stores before regional packagers consolidate modern trade access. For New Entrants and Emerging Players: Automated fermentation monitoring systems offer a technology-first wedge into mid-scale Japanese production where IoT-enabled quality consistency meets heritage branding requirements. Target Vietnam's northern urban corridors where modern trade vinegar penetration sits below fifteen percent and restaurant chain procurement scales rapidly. Bypass conventional grocery gatekeepers through Australian pharmacy and wellness retail channels with functional health-claim positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale heritage producers with protected geographical indication status because certification timeline compression and master brewer scarcity create durable moats against rapid industrial replication. Five-to-ten year viability hinges on origin-linked scarcity preservation rather than volume responsiveness. Watch SAMR audit timeline extensions as an inflection signal for distressed acquisition opportunities among non-compliant domestic packagers.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Process Certification Investment | JIS and PGI credentials defend margin pools against automated industrial entrants in Japanese and Chinese premium tiers. |
| Sachet Format Manufacturing Scale-Up | Unitized affordability unlocks Indonesian and Philippine kirana store penetration where cash-flow constraints shape purchase behavior. |
| Backward Integration into Grain Supply | Captive sorghum and rice sourcing buffers Yangtze River Delta processors against input cost volatility compressing heritage margins. |
| Pharmacy Channel Partnership Development | Australian wellness retail placement bypasses conventional grocery gatekeepers with functional health-claim SKUs. |
| IoT-Enabled Fermentation Infrastructure Deployment | Real-time acetic acid monitoring reduces batch-to-batch variation without abandoning JIS-certified process nomenclature. |
Study Parameters
Multiple input streams — fermentation facility audits, regulatory filing analysis, and trade flow reconciliation — were reconciled across primary interviews with heritage master brewers, modern trade category buyers, food service procurement directors, and SAMR compliance officers, validated against secondary sources including FSSAI labeling directives, METI-JIS certification databases, customs import records, and Yangtze River Delta grain price indices. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Historical consumption patterns were cross-referenced against panel input from distribution channel partners to construct analytical frameworks across product type, end user, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segment-specific growth trajectory reconciliation. Forecast inputs incorporated SAMR GB standard revision timelines, urban retail corridor expansion rates, and food service chain procurement scaling assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual carbon goal enforcement intensity, master brewer pipeline replenishment rates, and grain input price volatility. Forecasts reflect documented assumptions about regulatory implementation pacing and channel migration velocity. Material deviation in SAMR audit timeline compression or Shanxi PGI stock release patterns warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
US and Canada Premium Bottled Water Market
Beverages
India Bottled Water Market
Beverages
North America Kombucha Market
Beverages
GCC Bottled Water Market
Beverages
Europe Coconut Water Market
Beverages
Sports Drink Market
Beverages
Global Beverage Emulsion Market
Beverages
Botanical Infused Beverages Market
Beverages
Rose Floral Water Market
Beverages
Oat Based Beverages Market
Beverages
Blenders Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Vegetable Juice Market
Beverages
Japan Kombucha Market
Beverages
Fermented Foods and Beverages Market
Beverages
Aloe Vera Drinks Market