
 Herb Infused Water Market | 2026-2036
Herb Infused Water Market Size, Share, and Industry Trends Forecast 2026-2036
Herb Infused Water Market Foresight
The café and hospitality vertical is repositioning herb infused water from a niche menu item to a signature wellness offering. Nestlé Waters leverages its bottling infrastructure to secure shelf space in premium foodservice channels. PepsiCo competes through flavor innovation pipelines that blend botanical extracts with mainstream palatability. Hint Inc. specializes in clean-label positioning that anchors its brand identity among ingredient-conscious consumers.
Herb infused water consists of still or carbonated water blended with botanical extracts, essential oils, or dried plant matter at concentrations typically ranging from 0.1% to 2% by volume, yielding functional beverages positioned for hydration, digestion support, or stress relief. The product serves commercial foodservice, retail packaged goods, and workplace wellness programs seeking alternatives to sugary drinks. Citrus Infused and Herbal Blend categories dominate current volume, while Spiced Water represents the fastest-growing flavor frontier as consumers explore warming botanical profiles. Distribution through Health Stores captures the highest margin pools due to educated consumer willingness to pay premium prices for certified organic formulations.
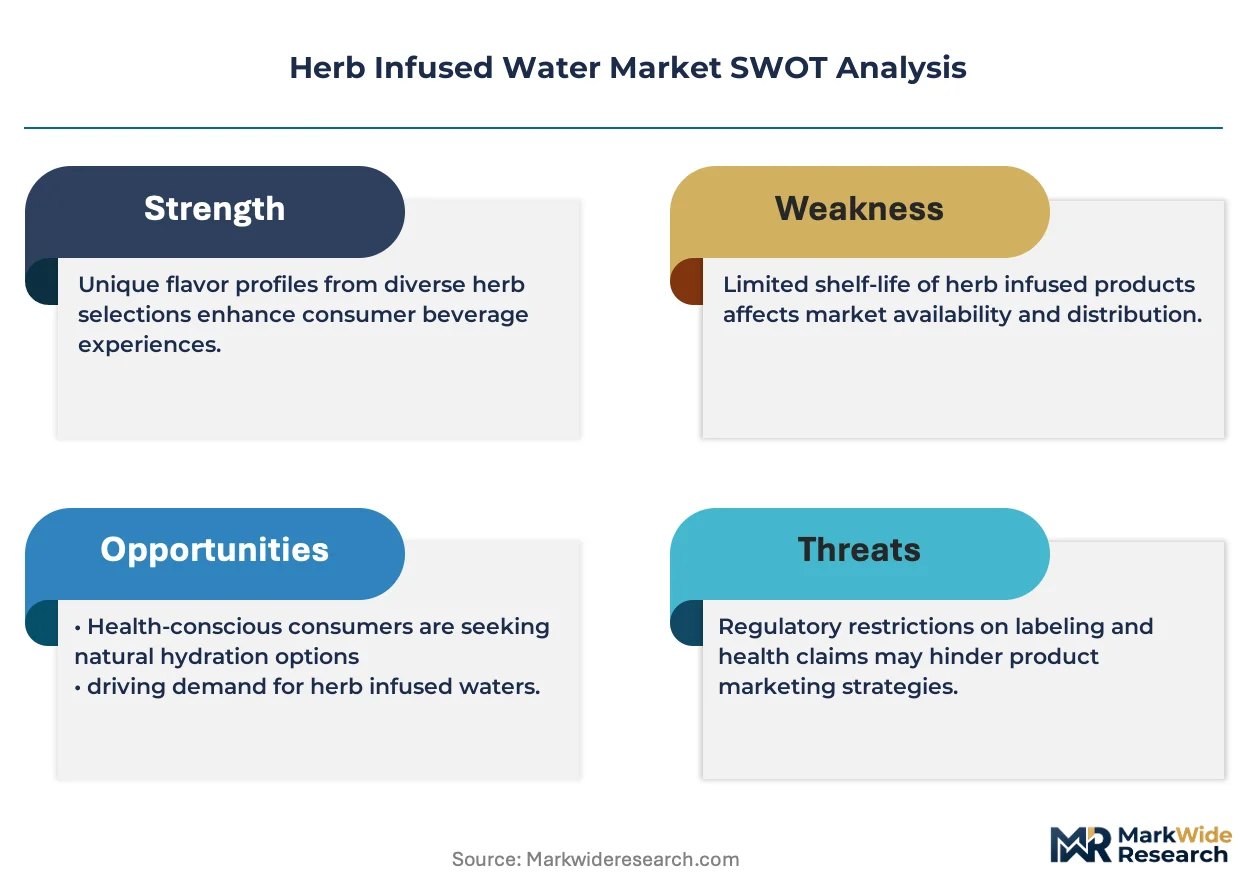
The FDA governs bottled water safety and botanical additive thresholds under 21 CFR standards, while the USDA Organic certification shapes premium pricing eligibility for herb sourced ingredients. The EU Green Deal and F-Gas Regulation indirectly influence carbonation supply chains and packaging sustainability requirements for European exporters. Stakeholders must monitor evolving botanical novel food classifications in multiple jurisdictions, as regulatory reclassification of traditional herbs could abruptly expand or constrain permissible ingredient lists.
Market Dynamics
Corporate wellness procurement contracts are compressing supplier qualification timelines while tightening botanical traceability requirements, forcing co-manufacturers to retrofit batch-level extraction documentation systems.
Growth Catalysts
- EU Green Deal packaging mandates:The EU Green Deal's 2030 recyclability targets are accelerating rPET adoption in premium herb water bottles, creating first-mover advantages for certified sustainable suppliers.
- Workplace hydration programs:Fortune 500 campus facilities are replacing soda fountains with botanical beverage stations, driving institutional volume commitments.
- Cold-press extraction equipment:New low-temperature botanical processing lines preserve volatile terpene profiles that heat-based methods degrade, unlocking flavor differentiation.
Market Restraints
- Organic herb input cost volatility:Certified organic mint and chamomile harvests in Egypt and Morocco face climate-driven yield fluctuations that compress blender margins.
- Carbonation equipment supply concentration:Precision carbonation systems for small-batch production concentrate among German and Italian equipment specialists, creating 14-16 week lead time bottlenecks.
- FDA novel food classification uncertainty:Botanical ingredients like ashwagandha and adaptogenic mushrooms lack clear GRAS status pathways, freezing formulation pipelines.
Strategic Opportunities
- Saudi Arabia wellness tourism:The Saudi Vision 2030 hospitality buildout imports premium beverage concepts for luxury resort contracts, creating white-space distribution.
- Direct-to-office subscription channels:Workplace micro-kitchen operators are bypassing traditional foodservice distributors to source branded herb water directly.
- USDA Organic plus Non-GMO Project dual certification:Stacked certification protocols command 22-35% shelf price premiums in natural retail channels.
Industry Challenges
- Flavor stability formulation expertise:Botanical extract oxidation during six-month shelf life targets requires specialized food chemistry talent that mid-size brands struggle to recruit.
- Co-packer line changeover complexity:Multi-SKU herb water portfolios force contract manufacturers to absorb 4-6 hour sanitation cycles between botanical and conventional runs, eroding throughput economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herb Infused Water Market |
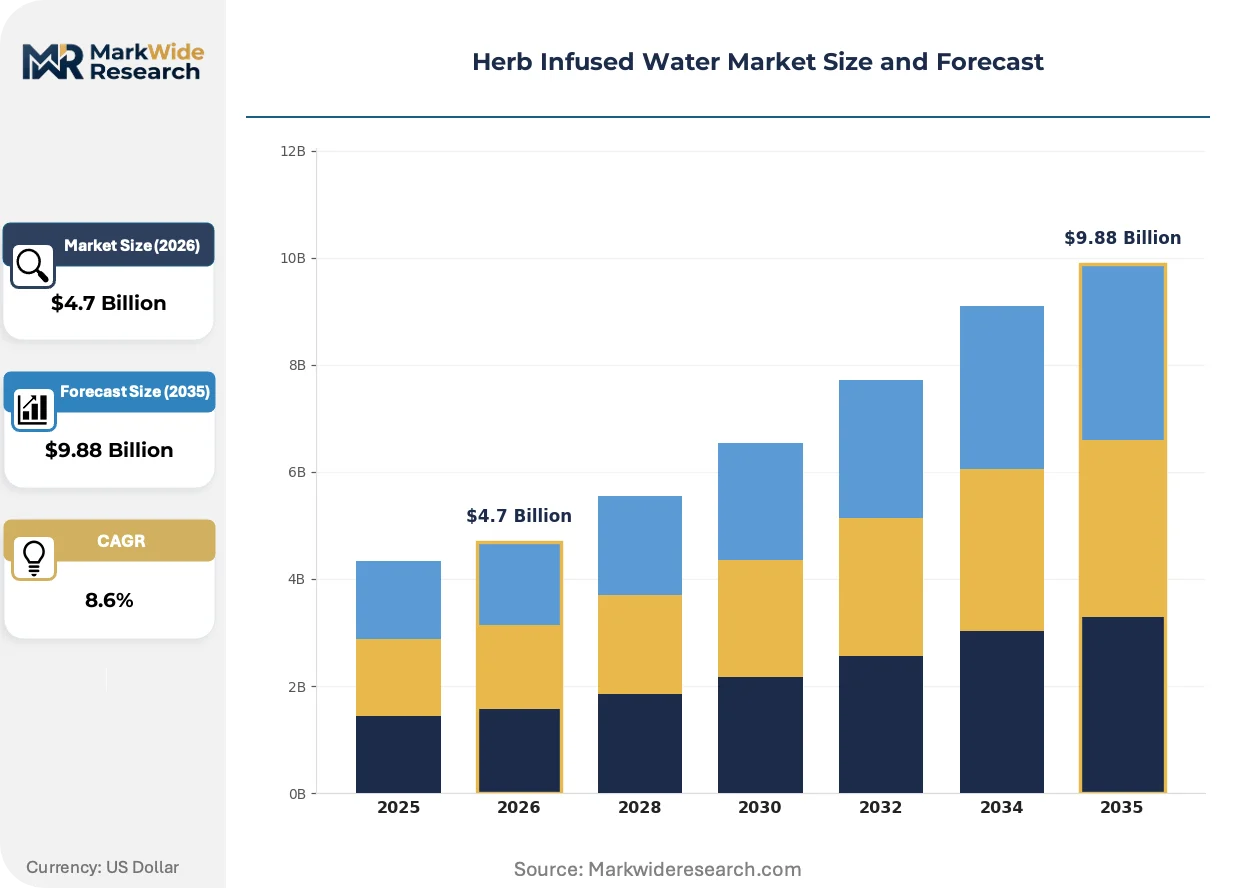
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Infused, Herbal Blend, Fruit Infused, Spiced Water Flavor Profile: Mint, Basil, Lavender, Rosemary Distribution Channel: Online Retail, Supermarkets, Health Stores, Cafés Target Consumer: Health Enthusiasts, Fitness Buffs, Diet Conscious, General Consumers |
| Companies Covered | Nestlé Waters, Coca-Cola Company, PepsiCo, Danone, Hint Inc., Spindrift Beverage Co., Treo Brands, Fiji Water, Voss of Norway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herb Infused Water Market Shifts & Advancements
Extraction technology maturation and regulatory clarity around novel botanicals are converging to expand permissible ingredient palettes while compression-molding advances reduce packaging cost structures.
High-pressure processing (HPP) technology is integrating into herb water production lines to extend shelf life without thermal degradation of heat-sensitive botanical compounds. Premium organic brands in California and Pacific Northwest natural retail channels are adopting HPP at 600 MPa pressures. This technology is integrating cold-chain distribution capabilities that previously constrained regional brands to local markets.
The FDA's updated guidance on plant extract labeling under 21 CFR 101.22 is forcing reformulation of "natural flavor" claims for multi-botanical blends. The rule requires quantitative disclosure of top-three flavor contributors when exceeding 2% by weight. Sparkling herb water SKUs with complex botanical stacks face the steepest compliance costs, with several brands accelerating clean-label simplification to two-ingredient formulations.
Buyer concentration in corporate foodservice is consolidating procurement authority under national beverage management contracts. Aramark and Compass Group are replacing fragmented regional supplier relationships with single-source national agreements that bundle herb water with coffee and sparkling water programs. This shift concentrates volume with three to four approved suppliers per beverage category, squeezing mid-tier regional brands from institutional channels.
Herb Infused Water Market Segmentation
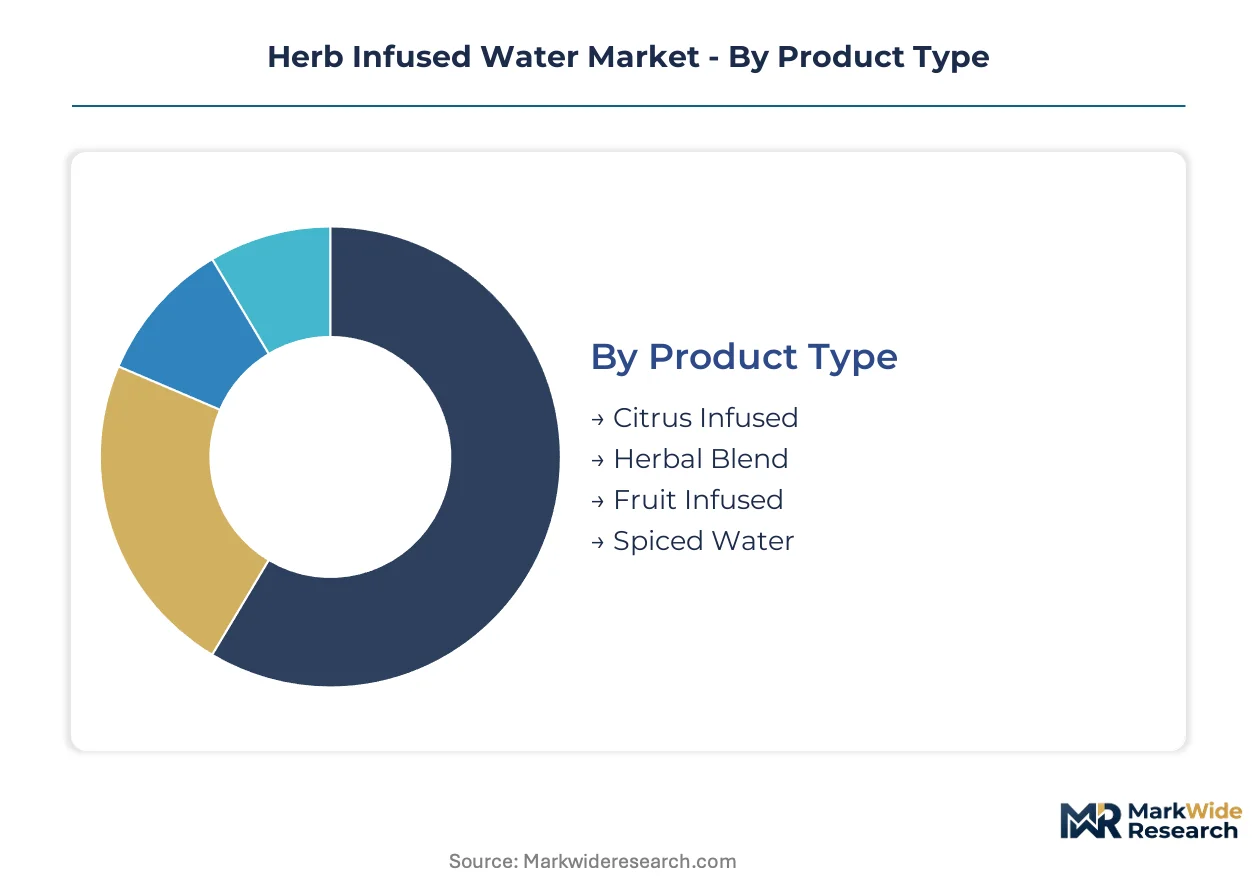
Herb infused water segmentation reveals distinct consumption contexts that reshape formulation priorities and channel economics. Product architecture and distribution pathways diverge sharply between wellness-oriented premium positioning and mainstream refreshment alternatives.
Product Type:
Standalone single-botanical formulations serve functional wellness protocols, while embedded multi-herb blends integrate into broader beverage portfolios targeting daily hydration rituals.
- Citrus Infused:Combines carbonated or still water with lemon, lime, or grapefruit extracts at 0.5% to 1.5% concentration. Demand clusters in German retail where sparkling citrus traditions merge with botanical wellness positioning.
- Herbal Blend:Multi-botanical formulations incorporating three or more plant extracts for synergistic functional claims. Corporate wellness programs in US Fortune 500 campuses are standardizing procurement around certified organic herbal blends for employee hydration stations.
- Fruit Infused:Berry and stone fruit extracts blended with subtle herbaceous notes for mainstream palatability. Supermarket channel buyers favor these SKUs for their broader demographic appeal.
- Spiced Water:Warming botanicals including cinnamon, cardamom, and ginger at higher extract concentrations. Health Stores capture margin premiums for these formulations during seasonal demand peaks.
Volume placements concentrate in Citrus Infused; the faster expansion belongs to Spiced Water.
Flavor Profile:
Cost tier stratification separates commodity mint and basil extracts from premium lavender and rosemary sourcing that commands certification-driven price premiums.
- Mint:Peppermint and spearmint extracts dominate mass-market SKUs due to established supply chains from Egyptian and Moroccan organic cultivation. Input cost volatility compresses blender margins during drought cycles.
- Basil:Sweet and holy basil variants anchor Mediterranean-inspired product lines. Italian and Greek extraction facilities supply European co-manufacturers with cold-pressed essential oil fractions.
- Lavender:Provence-sourced floral extracts require precise terpene preservation through low-temperature processing. USDA Organic certification eligibility shapes premium pricing in natural retail channels.
- Rosemary:Spanish and Portuguese cultivation regions supply antioxidant-rich extracts positioned for cognitive function claims. Dual USDA Organic plus Non-GMO Project certification commands 22-35% shelf price premiums.
Customer procurement concentrates in Mint for institutional contracts; Lavender climbs the fastest among premium direct-to-consumer subscriptions.
Distribution Channel:
Application context separates immediate-consumption foodservice placement from stock-up retail purchasing that demands extended shelf stability.
- Online Retail:Direct-to-consumer subscriptions and marketplace listings enable flavor customization and replenishment automation. Cold-chain logistics requirements previously constrained regional brands to local markets.
- Supermarkets:Mass-market shelf placement requires 6-month shelf life targets and simplified two-ingredient formulations to meet FDA labeling clarity under 21 CFR 101.22.
- Health Stores:Educated consumer bases pay premium prices for certified organic formulations with complex botanical stacks. This channel captures the highest margin pools in the category.
- Cafés:Foodservice fountain and bottled programs reposition herb infused water from niche menu item to signature wellness offering. National beverage management contracts are consolidating procurement authority under Aramark and Compass Group agreements.
Revenue concentration sits with Health Stores; Online Retail gains share fastest through subscription model adoption.
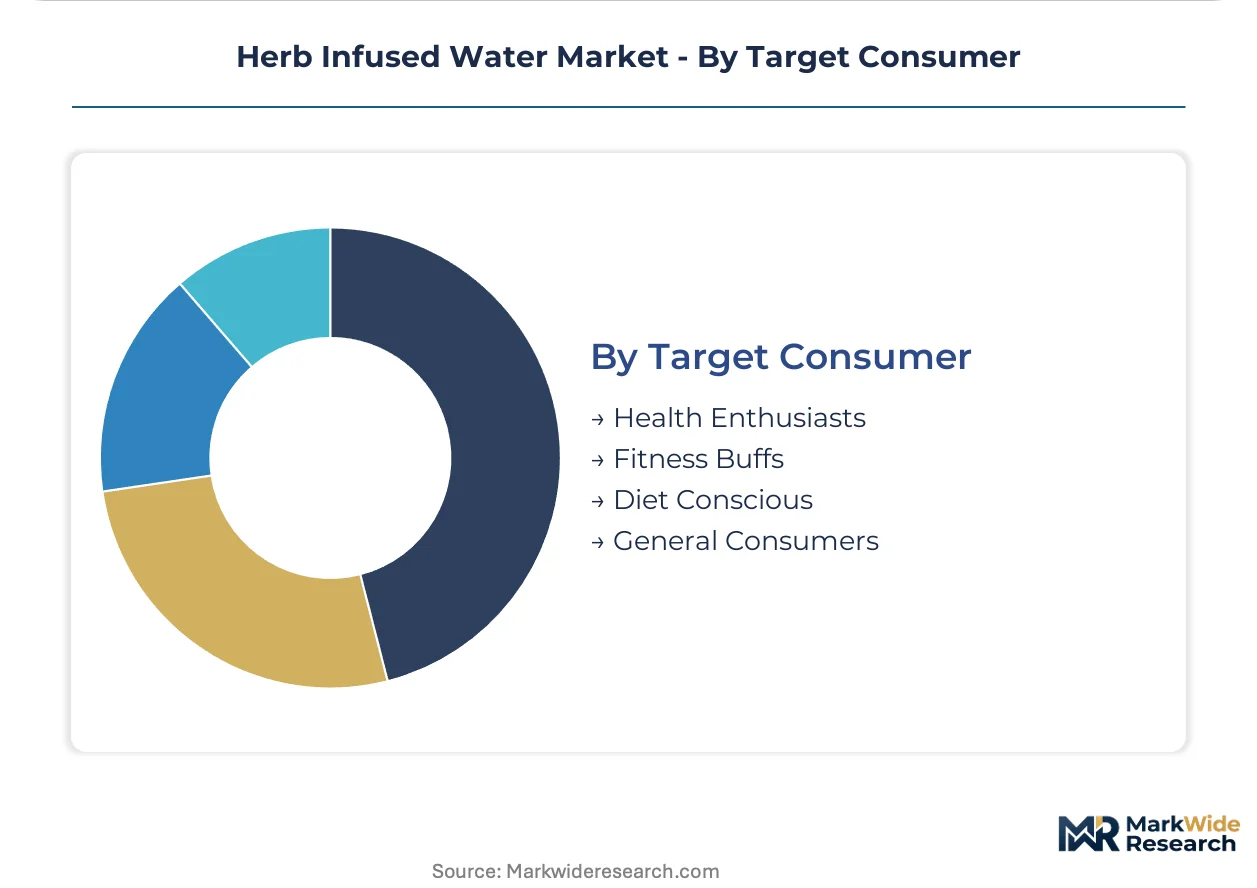
Target Consumer:
Maturity differentiation separates established health-conscious segments from emerging general consumer adoption that requires mainstream flavor accessibility.
- Health Enthusiasts:Early adopters seeking functional benefits including digestion support and stress relief. These buyers prioritize clean-label positioning and traceable botanical sourcing above price sensitivity.
- Fitness Buffs:Post-workout hydration seekers favoring electrolyte-enhanced herb water variants. Gym and studio micro-kitchen operators source directly from brands bypassing traditional distributors.
- Diet Conscious:Sugar-avoidant consumers replacing soda and juice with zero-calorie botanical alternatives. PepsiCo flavor innovation pipelines target this segment with mainstream palatability blends.
- General Consumers:Casual refreshment purchasers entering the category through familiar citrus and mint profiles. Supermarket promotional placement drives trial conversion among this demographic.
Volume leadership belongs to Health Enthusiasts; General Consumers show the steepest expansion trajectory as category awareness penetrates mainstream markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage clusters anchor European herb water production, with the EU Green Deal's packaging mandates concentrating sustainable manufacturing investments in Bavaria and Baden-Württemberg.
Germany
Sparkling herb water traditions merge with modern functional positioning in Munich and Stuttgart retail corridors. The EU F-Gas Regulation compresses carbonation equipment supply timelines for regional bottlers. Organic extraction facilities cluster along the Upper Rhine Valley, where cold-press processing lines serve premium export contracts.
United States
Corporate wellness procurement from Fortune 500 campuses drives institutional volume commitments in California and New York Metro markets. FDA 21 CFR standards govern botanical additive thresholds and plant extract labeling requirements. Pacific Northwest natural retail channels adopt high-pressure processing technology at 600 MPa pressures, extending shelf life without thermal degradation.
Saudi Arabia
Vision 2030 hospitality buildouts import premium beverage concepts for luxury resort contracts in Riyadh and the Western Region. The Saudi Food and Drug Authority regulates bottled water safety and novel botanical classifications. NEOM Northwest development zones attract international co-manufacturers seeking white-space distribution agreements.
France
Provence-sourced lavender extracts supply premium organic formulations through Parisian natural retail networks. EFSA novel food classifications shape permissible ingredient palettes for adaptogenic botanicals. Auvergne-Rhône-Alpes extraction facilities specialize in low-temperature terpene preservation for floral water variants.
United Kingdom
Health-conscious millennials in London's corporate wellness programs shift procurement toward botanical beverage stations. The Food Standards Agency monitors botanical novel food status for emerging adaptogenic ingredients. Southeast England co-manufacturers retrofit batch-level extraction documentation systems to meet compressed supplier qualification timelines.
Herb Infused Water Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational beverage conglomerates leveraging bottling infrastructure against clean-label independents. The vendor base concentrates around three strategic archetypes: diversified conglomerates with flavor innovation pipelines, premium organic specialists with dual certification protocols, and regional co-manufacturers serving private-label programs. Dominant competitive moves include strategic partnerships with corporate foodservice management companies and portfolio diversification into spiced water variants.
Among diversified beverage conglomerates, Nestlé Waters and PepsiCo occupy positions as scale-driven anchors with established foodservice distribution networks. Hint Inc. exemplifies the clean-label specialist archetype, representing ingredient-conscious positioning that commands premium shelf pricing in natural retail channels. These three companies collectively illustrate the competitive tension between mainstream palatability and botanical authenticity that defines current market positioning.
| Leading Market Players |
|---|
| Nestlé Waters |
| Coca-Cola Company |
| PepsiCo |
| Danone |
| Hint Inc. |
| Spindrift Beverage Co. |
| Treo Brands |
| Fiji Water |
| Voss of Norway |
| Others |
Supply & Pricing Matrix
Cold-press extraction equipment adoption is simultaneously compressing production costs for volatile terpene preservation and concentrating supplier power among German and Italian equipment specialists. This technology transition reshapes cost economics for mid-tier brands while creating 14-16 week lead time bottlenecks that premium producers exploit for margin expansion.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with spot inventory from Egyptian and Moroccan organic herb harvests trading at discounts during drought-induced oversupply windows. Three-tier pricing structure across premium dual-certified, standard organic, and economy conventional levels separates Health Store shelf placement from supermarket promotional slots. Cost compression in the standard tier is intensifying because climate-driven yield fluctuations in North African cultivation regions are squeezing blender margins. Corporate wellness procurement teams show the least price sensitivity, while supermarket buyers for general consumer segments drive the hardest volume-discount negotiations.
Supply Chain Analysis
Return flows of expired inventory and damaged packaging from Health Store channels feed into rPET reprocessing circuits that certified sustainable suppliers leverage for EU Green Deal compliance credits. Raw material sourcing draws from Egyptian organic mint cultivation, Moroccan chamomile harvesting, and Provence lavender extraction for premium floral variants. Single-source vulnerability concentrates in precision carbonation equipment from German and Italian specialists, creating procurement chokepoints for small-batch producers. Distribution runs through co-manufacturer networks that absorb 4-6 hour sanitation cycles between botanical and conventional production runs, eroding throughput economics for multi-SKU portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herb infused water market functions as a vertical-integration race where upstream control over certified organic extraction facilities and downstream capture of corporate wellness procurement contracts determines competitive survival. Players are pursuing backward integration into cold-press processing lines to secure terpene preservation capabilities that differentiate premium positioning.
For Market Incumbents: Hedge against novel botanical regulatory freezes by accelerating clean-label simplification to two-ingredient formulations that bypass FDA 21 CFR 101.22 disclosure thresholds. Secure capacity addition in Upper Rhine Valley extraction clusters to lock in Provence lavender supply chains before competitor offtake agreements consolidate. Channel control through direct-to-office subscription platforms insulates against Aramark and Compass Group procurement consolidation squeezing mid-tier brands from institutional channels.
For New Entrants and Emerging Players: Workplace micro-kitchen operators represent the most penetrable buyer archetype, bypassing traditional foodservice distributors to source branded herb water directly through replenishment automation platforms. Saudi Vision 2030 hospitality buildouts in NEOM Northwest development zones offer white-space distribution for luxury resort contracts importing premium beverage concepts. Spiced Water variants targeting seasonal demand peaks in Health Store channels provide the fastest path to margin-positive shelf placement without competing against established Citrus Infused volume leaders.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified beverage conglomerates seeking flavor innovation pipelines and premium organic positioning. Long-term viability over the mid-term projection horizon rests on dual certification protocol adoption rates in natural retail channels. The signal to watch is FDA GRAS status pathway clarity for adaptogenic botanicals like ashwagandha, which would unlock formulation pipeline expansion and revalue acquisition targets with pre-approved ingredient portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | USDA Organic plus Non-GMO Project stacking commands shelf price premiums in natural retail channels. |
| Cold-Press Processing Scale-Up | Low-temperature terpene preservation unlocks flavor differentiation against heat-degraded competitor offerings. |
| Direct-to-Office Subscription Launch | Workplace micro-kitchen bypass eliminates foodservice distributor margin capture and builds recurring revenue. |
| rPET Packaging Transition | EU Green Deal 2030 recyclability targets create first-mover advantages for certified sustainable suppliers. |
| Corporate Wellness Contract Capture | Fortune 500 campus standardization around botanical beverage stations drives institutional volume commitments. |
Research Methodology
Independent corroboration across beverage brand managers, co-manufacturer operations directors, and Health Store category buyers underwrites the qualitative findings in this study. Primary interviews with corporate wellness procurement leads at Fortune 500 facilities, cold-press equipment specialists in Bavaria, and organic herb cultivation cooperatives in Egypt and Morocco combined with secondary validation from FDA 21 CFR filings, EU F-Gas Regulation implementation reports, and USDA Organic certification databases. Bottom-up SKU-level volume modeling and top-down category spend analysis triangulate market sizing across the projection horizon.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-shift intervals anchored the forecast window to observable demand inflection points. The analytical framework segments volume and value outputs across product type, distribution channel, flavor profile, and target consumer archetype throughout the forecast period. CAGRs derive from regression-adjusted trend extrapolation incorporating organic herb input cost volatility indices and carbonation equipment lead time fluctuations as industry-specific forecast inputs.
Revisions become necessary when FDA novel food reclassification of adaptogenic botanicals materializes or when EU Green Deal packaging mandate enforcement timelines accelerate beyond current compliance trajectories. Practitioners should monitor EFSA botanical novel food classification proceedings and North African climate-driven harvest yield reports for early signals of forecast deviation triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Japan Energy Drink Market
Beverages
Vegetable Juice Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
CBD-Infused Beverages Market
Beverages
Root Beer Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
North America Fruit Juice Market
Beverages
Bottled Deep Ocean Water Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
GCC Bottled Water Market
Beverages
United States Soy Beverages Market
Beverages
Growlers Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
United States Sports and Energy Drinks Market