
 Drinking Bottled Mineral Water Market | 2026-2036
Drinking Bottled Mineral Water Market Size, Share, and Industry Trends Forecast 2026-2036
Drinking Bottled Mineral Water Market Insights
Asset-light franchising and third-party co-packing agreements is rewriting competitive economics in bottled mineral water, allowing regional challengers to scale without heavy capital deployment. Nestlé leverages its extensive spring source portfolio to sustain premium positioning across multiple continents. DANONE anchors European market share through deep well ownership and controlled distribution networks. Nongfu Spring dominates China's domestic trade with vertically controlled spring-to-shelf logistics.
Drinking bottled mineral water comprises naturally sourced water containing dissolved mineral salts and trace elements, typically bottled at origin with total dissolved solids exceeding 250 parts per million, serving consumer hydration needs and perceived wellness benefits. Still water occupies the volume core of the product type split due to universal daily consumption patterns, while functional variants infused with electrolytes or vitamins capture expanding margin pools from fitness-oriented buyers. Plastic bottles retain structural dominance in packaging type due to logistics efficiency, though glass bottles command premium positioning in hospitality channels where HoReCa distribution generates outsized per-unit returns.
FDA standards under 21 CFR 165.110 govern mineral content claims and source labeling in the United States, while the EU's Drinking Water Directive and F-Gas Regulation constrain processing methods and packaging materials across member states. China's SAMR enforces GB standards for bottled drinking natural mineral water that mandate specific geological source verification and compositional thresholds. Stakeholders must monitor regulatory divergence on plastic packaging restrictions and carbon labeling requirements as these frameworks harden in major consumption markets.
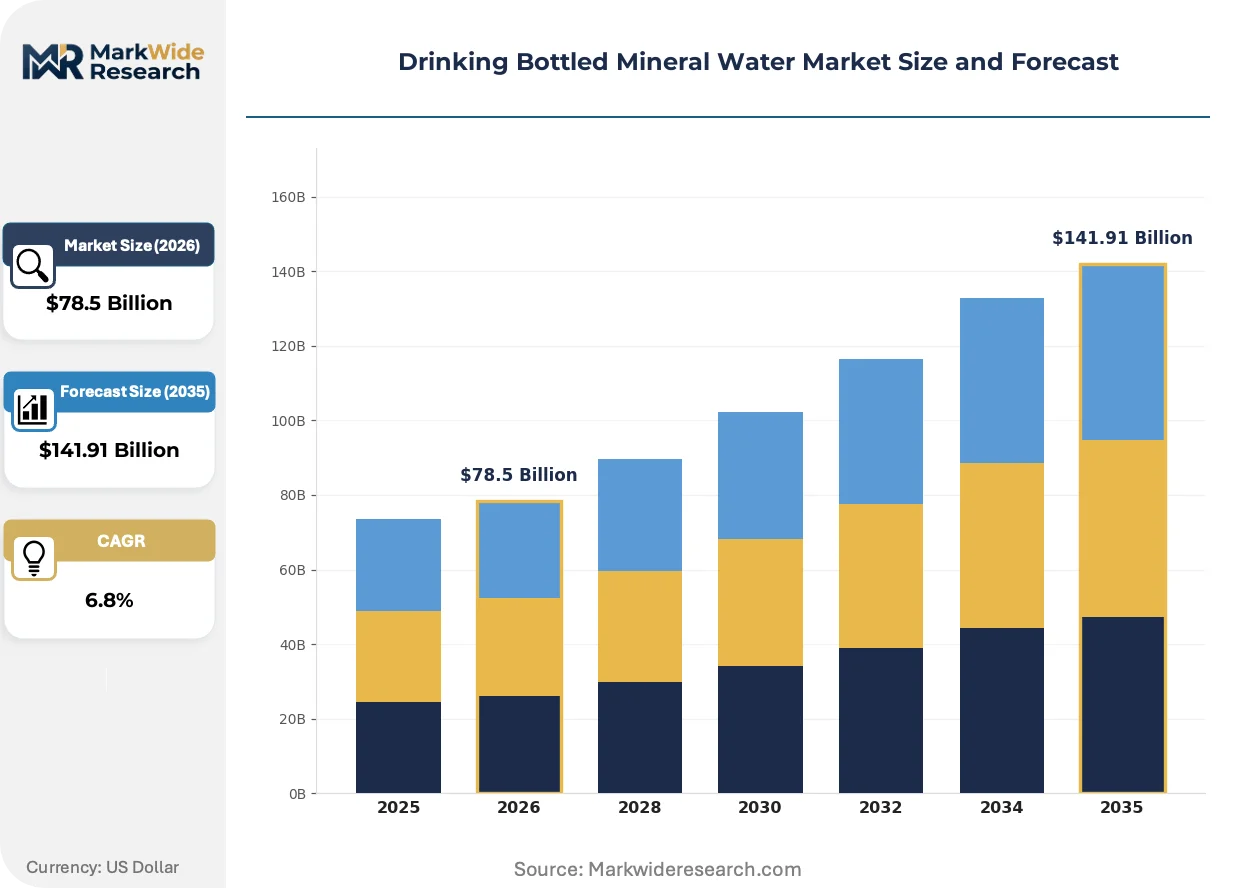
Market Dynamics
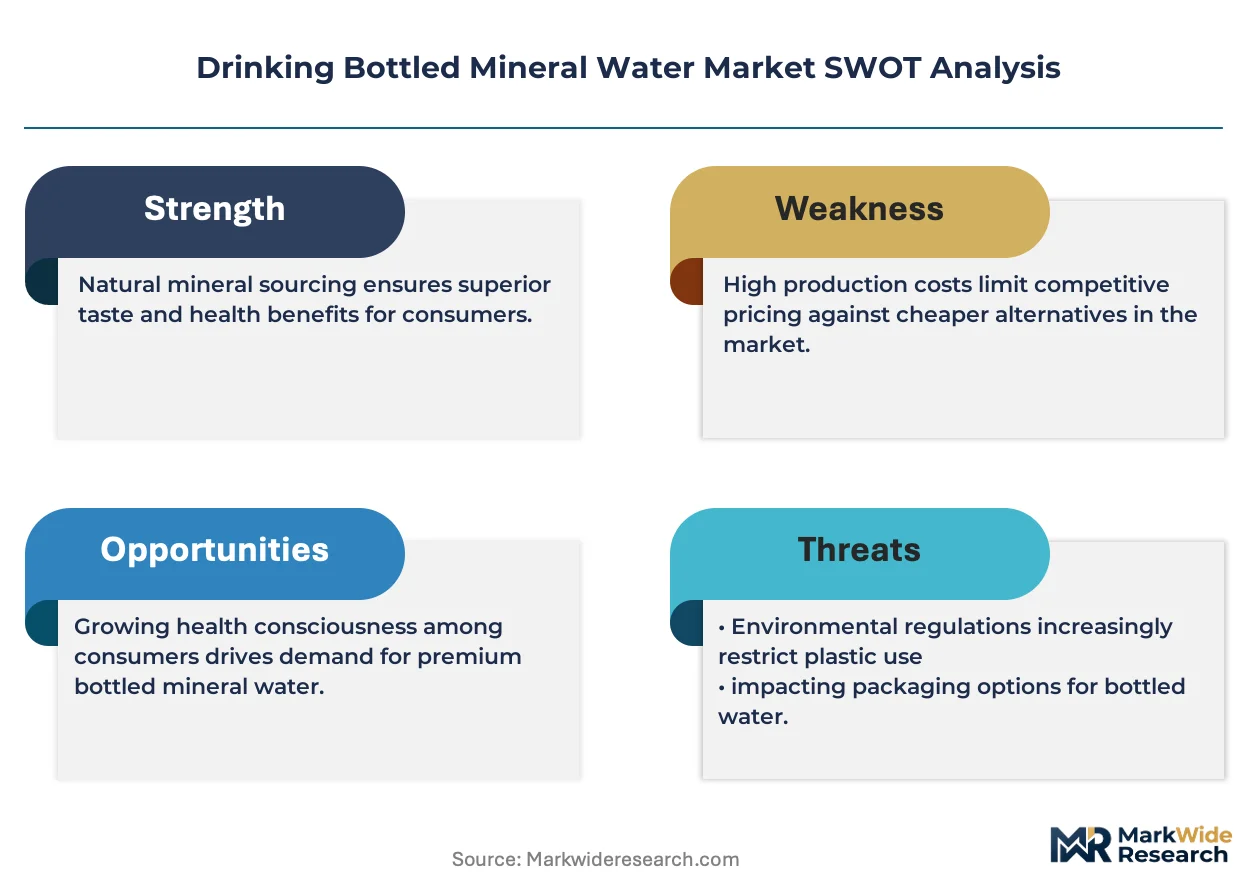
The EU's Single-Use Plastics Directive is forcing a fundamental packaging redesign across European markets, compressing profit margins for legacy PET-dependent operators while opening entry paths for aluminum and glass innovators. This regulatory pressure cascades into raw material sourcing, logistics reconfiguration, and brand repositioning decisions that define competitive survival.
Growth Catalysts
- Functional Infusion Technology:Electrolyte and vitamin fortification processes are capturing fitness-oriented residential consumers who pay premium multiples for hydration with perceived performance benefits.
- China's SAMR GB Standards:Mandatory geological source verification creates barriers against counterfeit mineral water, protecting certified domestic producers and elevating consumer trust in verified origin claims.
- HoReCa Channel Premiumization:Glass bottle formats command outsized per-unit returns in hospitality distribution networks where provenance storytelling drives menu placement decisions.
Market Restraints
- PET Resin Cost Volatility:Crude oil-linked feedstock pricing exposes bottlers to margin compression when polymer costs spike without corresponding pricing power.
- Spring Source Concentration:Premium aquifer access concentrates in specific geological formations, limiting new entrant capacity and entrenching incumbents with grandfathered extraction rights.
- Tap Water Substitution:Municipal filtration improvements and home carbonation systems erode daily consumption occasions among cost-sensitive urban households.
Strategic Opportunities
- India's Underpenetrated Tier-2 Cities:Distribution infrastructure gaps in secondary urban centers allow first-movers to establish brand preference before organized retail consolidation.
- Refill Station Networks:Reverse vending and bulk dispensing formats align with EU packaging reduction mandates while capturing recurring revenue from container deposit systems.
- Carbon Labeling Compliance:Early adoption of lifecycle emissions disclosure positions premium brands for procurement preference from corporate sustainability officers.
Industry Challenges
- Geological Survey Talent Scarcity:Hydrogeologist recruitment lags behind source verification demands, delaying new spring certification timelines.
- Legacy PET Line Stranded Assets:Conversion to aluminum or paper-based packaging requires capital redeployment that mid-tier bottlers cannot finance without dilutive raises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinking Bottled Mineral Water Market |
| Market Size in 2026 | $78.5 Billion |
| Market Size in 2035 | $141.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sparkling, Still, Functional, Flavored Packaging Type: Plastic Bottles, Glass Bottles, Cartons, Pouches Distribution Channel: Retail, Online, Vending Machines, HoReCa End Use: Residential, Commercial, Sports, Outdoor Activities |
| Companies Covered | Nestlé, The Coca-Cola Company, DANONE, PepsiCo, Primo Water Corporation, Gerolsteiner Brunnen GmbH & Co. KG, FIJI Water Company LLC, VOSS WATER, Nongfu Spring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinking Bottled Mineral Water Market Trends and Innovations
Active packaging material experimentation and source transparency protocols are collapsing traditional cost structures while elevating sustainability credentials from marketing veneer to procurement prerequisite. These shifts reconfigure where value accumulates across the value chain.
Aseptic bottling technology paired with lightweight aluminum formats is collapsing the cost gap between premium mineral water and mass-market alternatives. HoReCa buyers in Germany and France are accelerating adoption, compressing the timeline for glass-to-aluminum transition from decade-long replacement cycles to three-year procurement horizons. This collapse enables regional challengers to enter premium positioning without captive glass furnace investments.
The EU F-Gas Regulation constrains refrigeration-dependent distribution networks, forcing cold-chain bottlers to reformulate around ambient-stable packaging or absorb compliance penalties. Industrial consequence includes accelerated migration from hydrocarbon-blown PET to nitrogen dosing systems. Spring-sourced still water in Southern Europe faces the steepest reconfiguration costs as ambient distribution networks remain underdeveloped.
Direct-to-subscription replenishment models are displacing impulse retail purchases among residential buyers with predictable consumption patterns. E-commerce fulfillment centers in China's eastern provinces now originate one in five liters sold to urban households, bypassing traditional distributor markups. This channel shift concentrates demand forecasting risk with platform algorithms rather than regional sales teams.
Drinking Bottled Mineral Water Market Segmentation
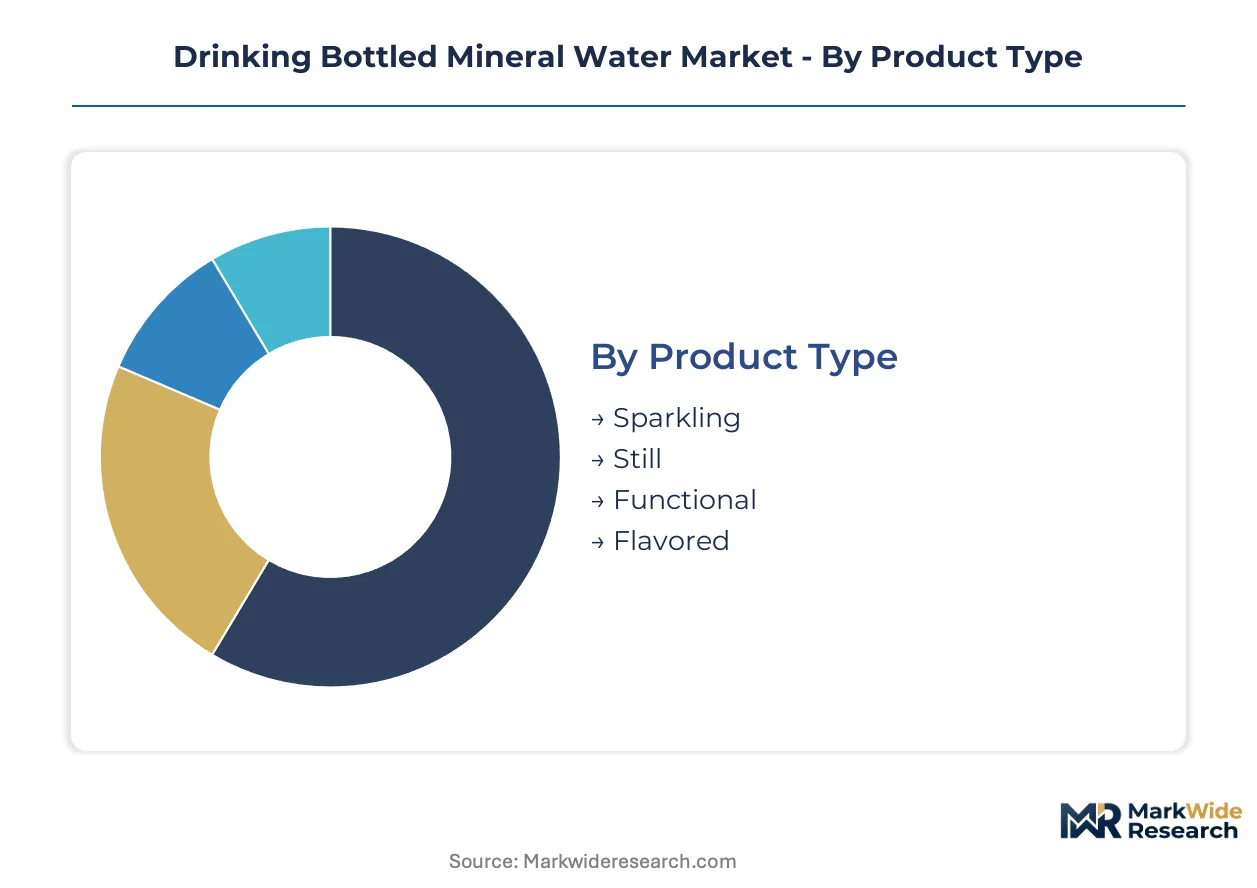
Segmentation in bottled mineral water separates volume-driven daily hydration from occasion-specific premium capture. Distinct packaging, channel, and end-use configurations create divergent margin profiles that reward targeted positioning over undifferentiated scale.
Product Type:
Maturity varies sharply across this spectrum, with legacy formats defending share against functional challengers engineered for specific wellness occasions.
- Still:Un-carbonated water with dissolved mineral content serves as the default hydration choice for daily consumption across households and workplaces. Demand concentrates in China's residential segment where Nongfu Spring and domestic brands have built dense urban distribution networks around this core format. Still water retains volume leadership; Functional water holds the steepest expansion curve.
- Functional:Electrolyte-fortified and vitamin-infused variants target fitness-oriented consumers seeking hydration with perceived performance benefits. Demand is climbing fastest in North American and European residential markets where gym culture and athletic lifestyle branding command premium pricing multiples over standard still water.
- Sparkling:Carbonated mineral water with natural or added CO2 serves dining occasions and palate-cleansing functions in hospitality settings. Italian and French spring sources dominate provenance positioning in HoReCa channels.
- Flavored:Fruit-essenced or botanical-infused offerings attract younger demographics seeking alternatives to sugary beverages. European markets under EU Single-Use Plastics Directive pressure show accelerated flavor innovation as brands differentiate beyond packaging.
Still water dominates unit economics through scale; Functional variants gain share fastest among premium-seeking demographics.
Packaging Type:
Cost tier separation is pronounced, with material choices directly determining channel access and margin capture potential.
- Plastic Bottles:PET and rPET formats deliver logistics efficiency and cost containment for high-volume retail distribution. Demand concentrates in mass-market retail across India and Southeast Asia where price sensitivity and infrastructure constraints favor lightweight, shatter-resistant formats.
- Glass Bottles:Premium positioning vehicle for hospitality and gifting channels where provenance storytelling justifies per-unit returns. HoReCa buyers in Germany and France are accelerating adoption despite higher freight costs.
- Cartons:Paper-based alternatives align with EU packaging reduction mandates and corporate sustainability procurement criteria. Nordic markets show earliest mainstream adoption.
- Pouches:Flexible formats target outdoor and sports occasions where weight reduction matters. Limited penetration outside Asian convenience retail.
Plastic bottles retain volume leadership; Glass bottles hold the steepest expansion curve in premium channels.
Distribution Channel:
Customer type fragmentation separates impulse purchasers from planned replenishment behaviors with divergent loyalty economics.
- Retail:Supermarkets, hypermarkets, and convenience stores remain the dominant volume channel for residential stock-up and immediate consumption needs. China's eastern provinces show accelerating consolidation into chain retail with centralized procurement.
- Online:Direct-to-subscription models and platform-based fulfillment capture predictable consumption patterns among urban households. E-commerce centers in China's eastern provinces now originate substantial share of residential volume.
- Vending Machines:Automated dispensing captures impulse occasions in transit hubs, offices, and recreational facilities. Japan and South Korea maintain highest machine density per capita.
- HoReCa:Hotels, restaurants, and cafés command outsized per-unit returns through menu placement and provenance premiums. Glass and aluminum formats are displacing traditional PET in European hospitality procurement.
Retail retains volume leadership; Online channels hold the steepest expansion curve.
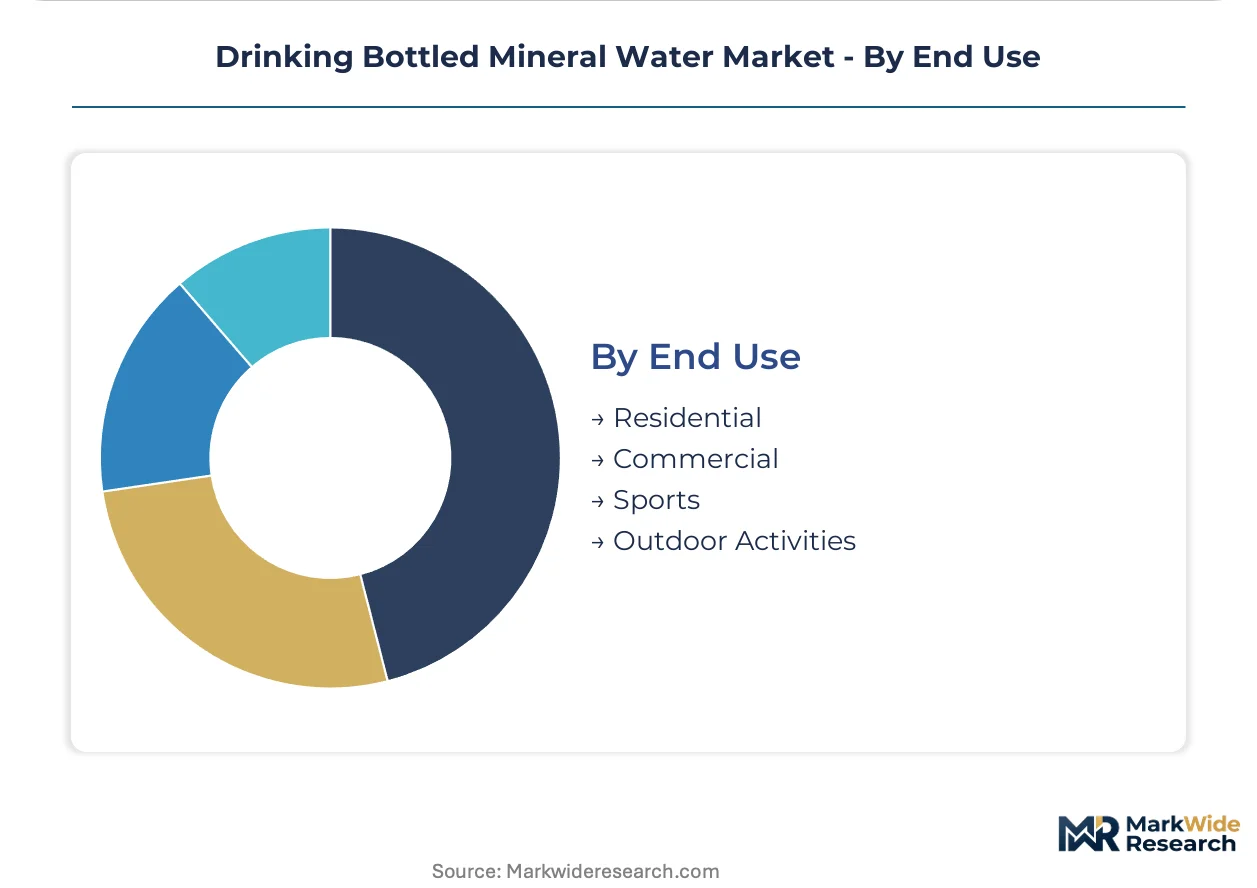
End Use:
Application context determines packaging specification, purchase frequency, and price elasticity across divergent consumption moments.
- Residential:Daily household consumption drives the core volume base with recurring purchase patterns and brand loyalty formation. China's urban households represent the largest concentrated demand pool globally.
- Commercial:Workplace and institutional hydration services prioritize cost containment and delivery reliability over brand differentiation. Corporate sustainability officers increasingly mandate carbon labeling compliance.
- Sports:Athletic occasion consumption favors functional fortification and portable formats. Fitness center distribution and event sponsorship drive brand trial.
- Outdoor Activities:Hiking, camping, and travel occasions demand durability and weight efficiency. Pouch and lightweight bottle formats compete for share in specialty retail.
Residential use retains volume leadership; Sports applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Single-Use Plastics Directive is accelerating packaging redesign across European markets while China's SAMR enforcement of GB standards elevates domestic certification barriers. These policy drivers are compressing margins for legacy PET-dependent operators and elevating verified-origin producers in concentrated urban demand clusters.
China
Residential consumption in tier-1 cities drives volume concentration as health-conscious households shift toward functional and still variants. SAMR's geological source verification mandates under GB standards protect certified domestic producers from counterfeit competition. Nongfu Spring anchors distribution density in the Yangtze River Delta where vertically controlled spring-to-shelf logistics dominate urban retail networks.
Germany
HoReCa channel premiumization favors glass and aluminum formats as hospitality procurement accelerates adoption timelines. The EU F-Gas Regulation constrains refrigeration-dependent distribution, forcing ambient-stable packaging reformulation. Industrial clusters in Bavaria and North Rhine-Westphalia host concentrated bottling capacity serving premium export markets.
United States
Fitness-oriented residential consumers command premium multiples for electrolyte-fortified functional water in coastal metropolitan markets. FDA standards under 21 CFR 165.110 govern mineral content claims and source labeling compliance. Distribution infrastructure concentrates in California and Texas where direct-to-subscription models capture predictable household replenishment patterns.
France
Sparkling mineral water from protected spring sources maintains provenance dominance in European hospitality procurement. The EU Drinking Water Directive and packaging reduction mandates constrain processing methods and materials selection. Production gravity in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur supplies heritage brands with grandfathered extraction rights.
India
Tier-2 city distribution gaps allow first-movers to establish brand preference before organized retail consolidation accelerates. FSSAI labeling requirements and state-level plastic waste management rules create compliance heterogeneity across sub-national jurisdictions. Maharashtra and Gujarat industrial corridors concentrate co-packing capacity serving mass-market PET formats.
Drinking Bottled Mineral Water Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: multinational beverage conglomerates with diversified hydration portfolios, regional spring-source specialists with vertically controlled extraction rights, and asset-light challengers leveraging third-party co-packing to scale without capital-heavy infrastructure. Competitive moves center on M&A-driven source acquisition and aluminum packaging line conversion to preempt EU regulatory compliance deadlines.
Among diversified multinational operators, Nestlé and DANONE exemplify contrasting spring-source strategies—Nestlé leverages extensive portfolio breadth across multiple continents while DANONE anchors European positioning through deep well ownership. Nongfu Spring occupies a distinct tier as a domestic Chinese operator with captive distribution density. These three represent the dominant competitive archetypes: global portfolio diversifier, regional source-integrated incumbent, and vertically controlled national champion.
| Leading Market Players |
|---|
| Nestlé |
| The Coca-Cola Company |
| DANONE |
| PepsiCo |
| Primo Water Corporation |
| Gerolsteiner Brunnen GmbH & Co. KG |
| FIJI Water Company LLC |
| VOSS WATER |
| Nongfu Spring |
| Others |
Pricing and Supply Chain Analysis
Auvergne-Rhône-Alpes in France anchors premium spring source capacity, where grandfathered extraction rights concentrate supply among heritage producers and translate directly into pricing power over hospitality procurement networks.
Pricing Analysis
Certification level under SAMR GB standards and FDA 21 CFR 165.110 creates the primary spread between premium verified-origin and unverified mass-market tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with geological source verification and glass packaging driving top-tier multiples. Pricing pressure stems from PET resin cost volatility linked to crude oil feedstocks. Residential buyers in China's tier-1 cities show lowest price sensitivity, while mass-market retail consumers in India exhibit highest elasticity.
Supply Chain Analysis
Third-party co-packing agreements with regional bottlers in China, Germany, and the United States hold dominant contract-manufacturing capacity for asset-light brands. Spring source extraction, PET resin production, and aluminum can forming constitute critical input dependencies. Supply chain risk centers on single-source aquifer concentration in specific geological formations. Distribution runs through vertically controlled spring-to-shelf logistics in China and HoReCa wholesale networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-subscription replenishment models represent a service-attach opportunity expanding faster than core product volume, as platform algorithms capture recurring revenue from predictable household consumption patterns.
For Market Incumbents: Pre-empt aluminum packaging line conversion ahead of EU Single-Use Plastics Directive enforcement deadlines. Secure grandfathered spring source extraction rights through regulatory certification investments. Deepen backward integration into captive aquifer control to defend margin position against asset-light challengers leveraging third-party co-packing.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 cities where distribution infrastructure gaps allow brand preference formation before organized retail consolidation. Target functional water segments in North American fitness-oriented residential markets. Deploy refill station networks aligned with EU packaging reduction mandates as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically controlled national champions with captive spring-to-shelf logistics over pure-brand marketing plays. Long-term viability across the analysis window hinges on regulatory compliance infrastructure and source verification capabilities. Acquisition target archetype: regional bottlers with certified geological sources and underutilized aluminum line capacity. Monitor SAMR enforcement intensity as the signal to watch for certification barrier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Packaging Conversion | Preempts EU Single-Use Plastics Directive compliance costs while capturing HoReCa premium positioning. |
| Spring Source Certification Investment | GB standards verification under SAMR protects against counterfeit competition in China's concentrated urban markets. |
| Direct-to-Subscription Platform Launch | Bypasses traditional distributor markups by capturing predictable replenishment patterns through e-commerce fulfillment. |
| Refill Station Network Expansion | Aligns with EU packaging reduction mandates while generating recurring revenue from container deposit systems. |
| Functional Water R&D Pipeline | Electrolyte fortification technology captures fitness-oriented consumers commanding premium pricing multiples. |
Research Methodology
Desk research of customs trade records, spring source regulatory filings, and beverage industry association datasets preceded structured interviews with bottling plant managers, HoReCa procurement directors, hydrogeological survey specialists, and e-commerce platform category leads. Primary fieldwork across China, Germany, France, and the United States validated secondary data on spring source concentration and packaging transition timelines. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Assumptions around EU regulatory enforcement timelines, PET resin price band stability, and China's e-commerce penetration curves were held fixed across the projection horizon, while spring source discovery rates and aluminum can capacity expansion were varied. Segmentation dimensions modeled include product type, packaging material, distribution channel, and end-use application. CAGRs were derived from historical volume trajectories adjusted for structural shifts in consumer channel preferences.
Stress conditions across crude oil price volatility, EU packaging mandate acceleration, and China's SAMR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of spring source certification timelines, aluminum line conversion announcements, and platform-based subscription growth rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hot Beverages Market
Beverages
Solid Beverages Market
Beverages
US and Canada Tonic Water Market
Beverages
United Kingdom Energy Drink Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Pineapple Juice Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Victorian Jars Market
Beverages
Superfood Infused Beverages Market
Beverages
Birch Water Market
Beverages
Wellness Water Market
Beverages
Apple Juice Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Chocolate Malt Drink Market
Beverages
Bottled Air Market