
 Collagen-Infused Water Market | 2026-2036
Collagen-Infused Water Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen-Infused Water Market Analytics
Health enthusiasts is reorganizing demand away from casual retail consumers as collagen-infused water shifts from novelty beverage to regimen-based wellness product. Vital Proteins leverages its scale in grass-fed bovine sourcing to anchor North American supply. Shiseido dominates Asia-Pacific beauty positioning through decades of ingestible skincare credibility. NeoCell specializes in hydrolyzed peptide formulations that compete on bioavailability claims.
Collagen-infused water denotes purified or mineral water enhanced with hydrolyzed collagen peptides, typically at concentrations of 2,000 to 10,000 milligrams per serving, designed to deliver amino acid substrates for dermal matrix maintenance and joint tissue support. The functional product type commands premium positioning through added adaptogens and vitamins, while unflavored variants sustain broader ingredient versatility for stackable nutrition routines. Bottles remain the default packaging format for gym and commute occasions, though pouches are gaining traction in subscription and travel channels where portability determines repeat purchase.
FDA oversight of dietary supplement labeling and EFSA novel food assessments govern collagen source transparency and permissible health claims across the United States and European Union, compelling brands to invest in clinical substantiation or risk channel exclusion. Japan's FOSHU framework and METI guidance on functional food labeling create additional compliance thresholds for brands targeting East Asian wellness consumers. Stakeholders must monitor evolving peptide bioavailability standards and regional claim permissibility to determine where formulation investment converts to shelf access versus regulatory delay.
Market Dynamics
Health enthusiast migration toward regimen-based consumption is compressing novelty-driven trial purchases while elevating clinical substantiation requirements for shelf placement in premium hydration channels.
Growth Catalysts
- FOSHU Framework (Japan):Japan's functional food labeling system rewards clinical validation with permitted beauty-from-within claims, incentivizing peptide bioavailability investment.
- Hydrolyzed Peptide Concentration:Advances in enzymatic hydrolysis enable 5,000-10,000 mg serving densities that satisfy efficacy thresholds for joint and dermal matrix support.
- Germany Beauty-From-Within Cluster:Munich and Berlin retail networks prioritize ingestible skincare adjacencies, creating premium placement velocity for collagen-enhanced formats.
Market Restraints
- Grass-Fed Bovine Supply Concentration:North American pasture-raised collagen sourcing faces capacity constraints during drought cycles, elevating input cost volatility.
- EFSA Novel Food Assessments:European Union safety evaluations for marine-derived collagen peptides extend commercialization timelines by 18-24 months.
- Plant-Based Collagen Substitutes:Fermented amino acid complexes and algae-derived alternatives capture vegan-adjacent consumers in coastal metropolitan markets.
Strategic Opportunities
- Subscription Channel Penetration:Pouch-format collagen waters bypass traditional retail slotting fees while capturing recurring revenue in direct-to-consumer wellness bundles.
- Adaptogen Convergence:Formulations combining collagen with ashwagandha or lion's mane target stress-skin axis positioning in urban professional segments.
- India Functional Beverage Liberalization:FSSAI evolving standards for protein-fortified beverages open regulatory pathways for hydrolyzed peptide import and local co-manufacturing.
Industry Challenges
- Peptide Stability Expertise Gap:Formulation chemists capable of maintaining collagen integrity across ambient-temperature shelf life remain concentrated in Japanese and German R&D clusters.
- Cross-Border Label Harmonization:Divergent permissible claims between FDA dietary supplement guidance and EFSA health claim regulations force SKU fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen-Infused Water Market |
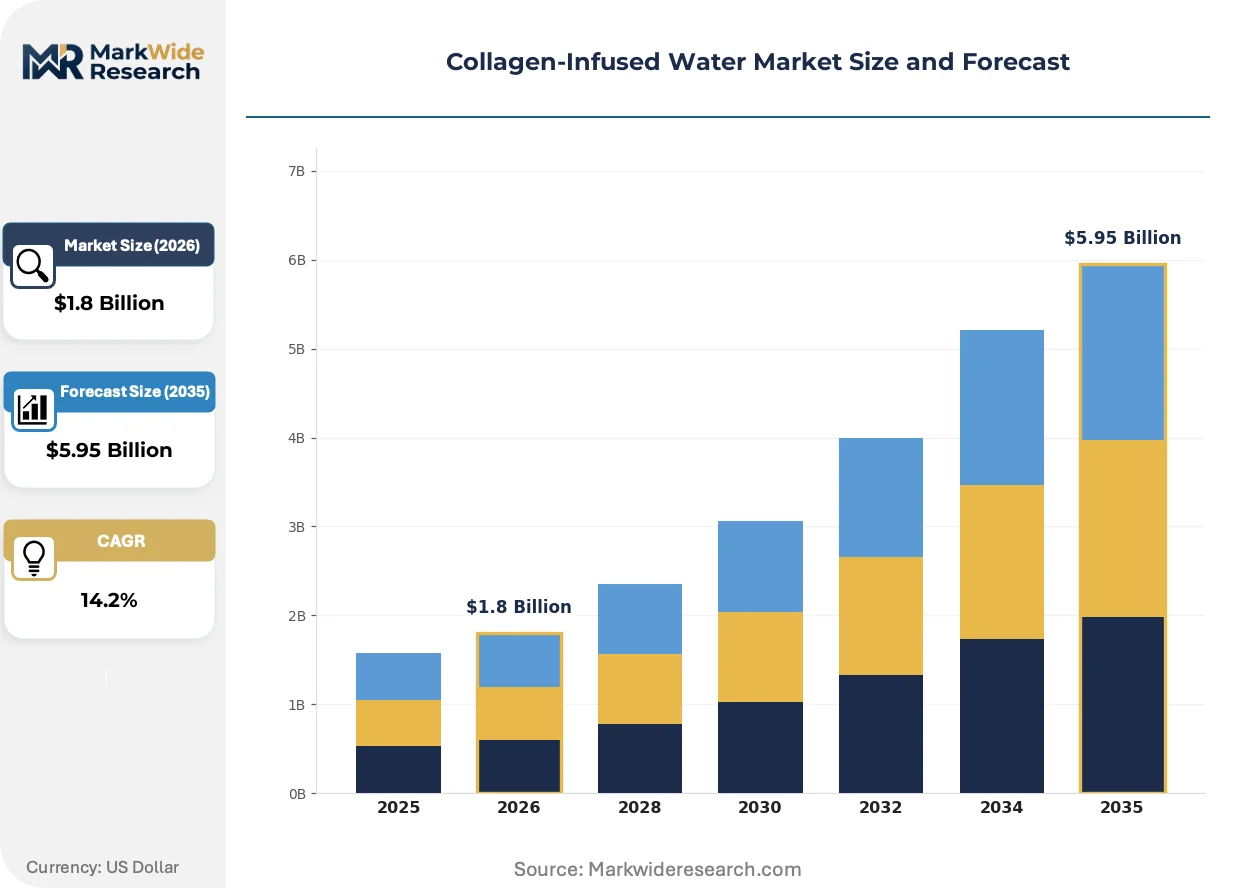
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Organic, Functional Customer Type: Retail Consumers, Health Enthusiasts, Gym-goers, Elderly Packaging Type: Bottles, Cans, Tetra Packs, Pouches Distribution Channel: Online Stores, Supermarkets, Health Shops, Convenience Stores |
| Companies Covered | Vital Proteins, NeoCell, Skinade, Shiseido, Gold Collagen, Vieve, Primal Kitchen, SkinnyFit, Zint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen-Infused Water Market Evolving Landscape
Peptide delivery science and regulatory claim frameworks are actively reconfiguring competitive differentiation, separating clinically substantiated players from commodity-positioned entrants.
Microencapsulation technology is bifurcating the stability-performance frontier for ambient collagen beverages. Japanese beverage laboratories pioneered lipid-shell peptide protection that extends unopened shelf life to 18 months. Health enthusiast segments in Tokyo and Osaka now treat these formats as pantry staples rather than refrigerated impulse purchases.
EFSA's evolving guidance on beauty-related health claims is compressing permissible marketing language for dermal benefit assertions. Brands must now reference specific collagen peptide molecular weights and clinical trial endpoints to avoid enforcement actions. German and French market entrants face the steepest compliance recalibration as national regulators align with Brussels-standard substantiation thresholds.
Wellness subscription bundling is displacing single-SKU trial purchases in direct channels. Consumers in United States metropolitan markets increasingly procure collagen waters within personalized nutrition stacks that rotate quarterly. This behavioral shift concentrates lifetime value with platforms capable of algorithmic flavor and formulation curation rather than conventional retail velocity.
Collagen-Infused Water Market Segmentation
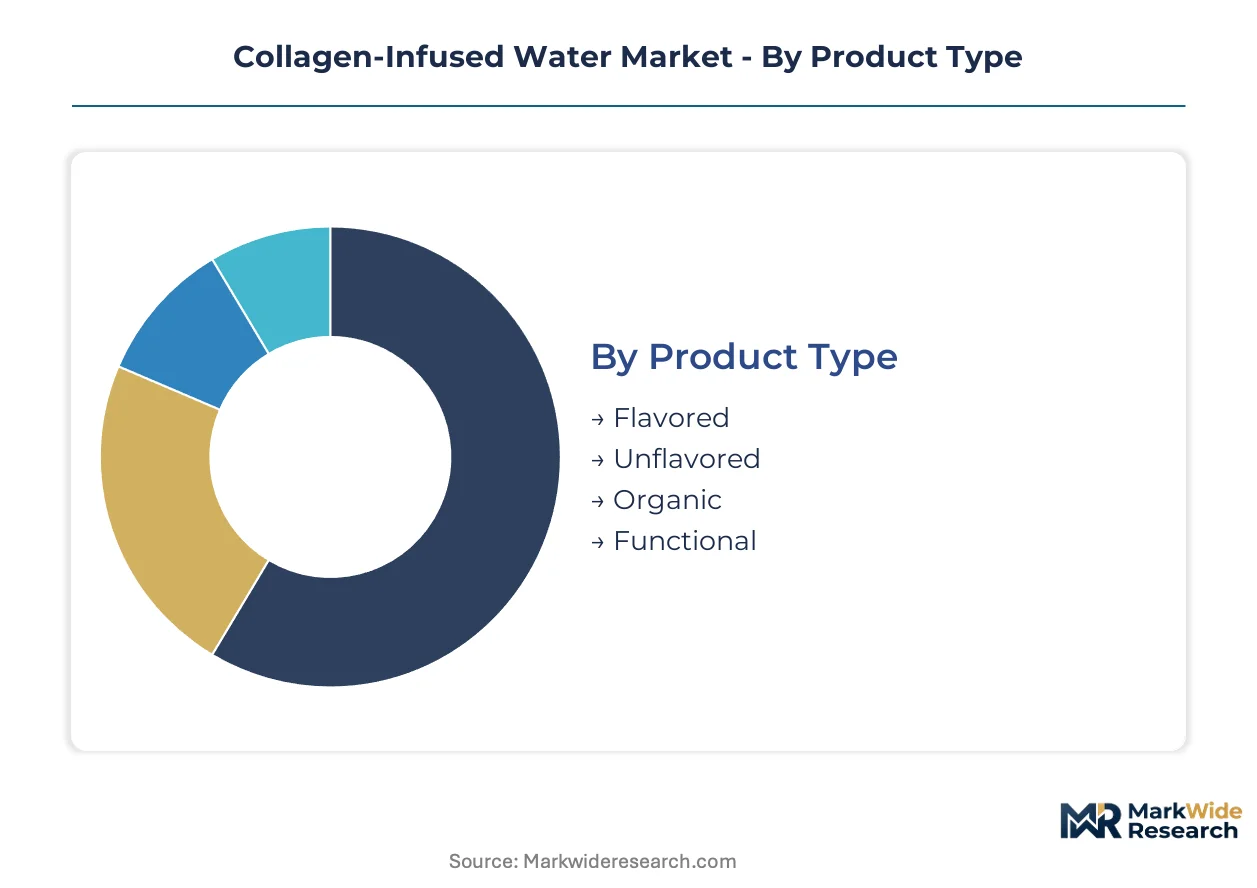
Collagen-infused water segments fracture across incompatible channel economics. Premium functional variants command health shop placement with clinical substantiation requirements, while mass-market flavored formats compete for supermarket velocity through price-per-milligram efficiency.
Product Type:
Channel-mix logic separates clinical-positioned SKUs from impulse formats. Functional and organic variants flow through health shops and subscription platforms where ingredient transparency justifies premium shelf fees. Flavored and unflavored formats distribute through supermarkets and convenience stores where turnover velocity determines listing survival.
- Flavored:Fruit-forward and botanical taste profiles mask peptide bitterness at 2,000-5,000 mg concentrations. United States metropolitan supermarkets prioritize these SKUs for grab-and-go hydration sets where palatability drives trial conversion among casual retail consumers.
- Unflavored:Neutral taste profiles enable stackable nutrition routines at 5,000-10,000 mg peptide densities. Health enthusiasts in Germany and Japan blend these into coffee and smoothies, concentrating demand in direct-to-consumer channels where ingredient purity claims command subscription loyalty.
- Organic:Certified grass-fed bovine or wild-caught marine sourcing satisfies clean-label procurement standards in premium health shops.
- Functional:Adaptogen and vitamin fortification targets stress-skin axis positioning in urban professional segments across subscription platforms.
Unflavored dominates installed base among regimen-adherent consumers. Functional is where expansion concentrates as adaptogen convergence accelerates.
Customer Type:
Cost tier stratification separates occasional purchasers from committed subscribers. Health enthusiasts and gym-goers absorb premium pricing for bioavailability-optimized formulations. Retail consumers and elderly segments gravitate toward entry-price points in mass retail channels where education costs constrain conversion rates.
- Health Enthusiasts:Regimen-based consumers prioritize peptide molecular weight specifications and clinical trial citations over taste optimization. These buyers concentrate in Japan's FOSHU-validated channels and Germany's beauty-from-within retail networks where substantiation depth determines wallet share.
- Gym-goers:Post-workout recovery positioning emphasizes joint tissue support and rapid amino acid absorption. Demand clusters in United States fitness club micro-markets and Tokyo sports specialty retailers where portability and protein-adjacent branding drive repeat purchase.
- Retail Consumers:Impulse-driven trial purchases respond to flavor innovation and promotional pricing in supermarket beverage aisles.
- Elderly:Joint mobility claims resonate in pharmacy-adjacent channels where trust in established health brands reduces perceived purchase risk.
Health enthusiasts dominate installed base. Gym-goers is where expansion concentrates.
Packaging Type:
Volume economics and occasion specificity determine format viability. Bottles sustain gym and commute rituals with resealability. Pouches and cans optimize for travel and subscription bundling where shipping weight and storage efficiency matter.
- Bottles:PET and glass formats at 500-750 mL dominate refrigerated sets in supermarkets and health shops. These SKUs anchor United States and German retail presence where single-serve convenience justifies per-unit premiums over multi-serve alternatives.
- Pouches:Flexible film formats at 200-350 mL reduce shipping cube and enable subscription box integration. Japanese laboratories pioneered ambient-stable pouch technology that extends shelf life without cold chain dependency, concentrating growth in direct-to-consumer wellness bundles.
- Cans:Aluminum formats appeal to sparkling collagen water variants in convenience store cold vaults.
- Tetra Packs:Aseptic carton technology supports ambient distribution in emerging markets where refrigeration infrastructure remains limited.
Bottles dominate installed base. Pouches is where expansion concentrates.
Distribution Channel:
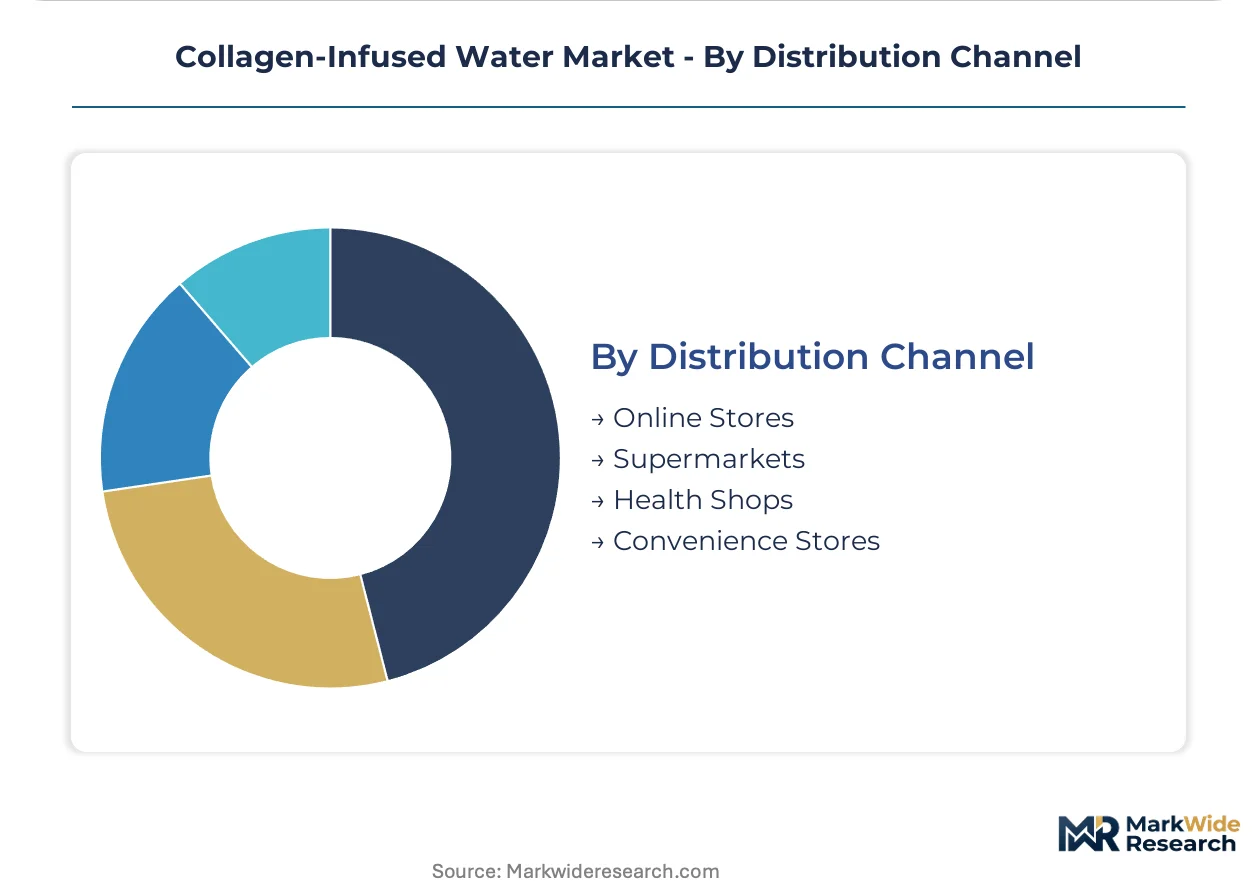
Margin structure and customer acquisition cost separate viable channels from marginal ones. Online stores capture lifetime value through subscription mechanics. Supermarkets demand slotting fees that exclude sub-scale entrants. Health shops and convenience stores occupy intermediate positions on education burden and inventory risk.
- Online Stores:Direct-to-consumer platforms enable algorithmic flavor curation and quarterly subscription rotation. United States metropolitan consumers increasingly procure collagen waters within personalized nutrition stacks, concentrating highest lifetime value with platforms capable of peptide bioavailability storytelling.
- Health Shops:Staff-assisted education justifies premium positioning for functional and organic variants. Germany's Munich and Berlin retail networks prioritize ingestible skincare adjacencies, creating placement velocity for clinically substantiated entrants.
- Supermarkets:Mass-market penetration requires trade spend efficiency and velocity guarantees that favor scaled beverage conglomerates.
- Convenience Stores:Impulse occasion capture depends on cold vault placement and single-serve price points accessible to casual trial.
Online stores dominate installed base. Health shops is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles cold chain infrastructure underwrites United States distribution velocity for ambient-stable collagen formats, while Japan's Kansai International Airport perishables hub enables FOSHU-certified peptide imports across East Asian wellness corridors.
United States
FDA dietary supplement labeling requirements and health enthusiast regimen adherence drive peptide bioavailability investment. The agency's structure-function claim oversight compels clinical substantiation for dermal benefit assertions. Los Angeles and New York metropolitan retail networks concentrate beauty-from-within placement velocity in premium hydration sets.
Germany
EFSA novel food assessments and Munich-Berlin ingestible skincare retail clusters elevate substantiation thresholds for shelf access. The European regulator's beauty-related health claim compression forces molecular weight specificity in marketing language. Bavarian and North Rhine-Westphalia health shops prioritize clinically validated entrants over commodity-positioned alternatives.
Japan
METI functional food labeling guidance and FOSHU framework rewards validate peptide concentration claims for beauty-from-within positioning. The Ministry's standards create compliant pathways for hydrolyzed collagen imports. Tokyo and Osaka consumer segments treat microencapsulated ambient formats as pantry staples rather than refrigerated impulse purchases.
United Kingdom
Post-Brexit divergence from EFSA assessments and London metropolitan wellness subscription penetration reshape import compliance timelines. The Medicines and Healthcare products Regulatory Agency's evolving novel food determinations extend marine-derived peptide commercialization schedules. Greater Manchester and Birmingham direct-to-consumer platforms concentrate algorithmic flavor curation capabilities.
India
FSSAI protein-fortified beverage standards liberalization and Mumbai-Delhi functional beverage adoption create regulatory pathways for hydrolyzed peptide import. The Food Safety and Standards Authority's evolving standards open co-manufacturing partnerships with domestic bottlers. Maharashtra and Karnataka urban professional segments demonstrate rising adaptogen-convergence readiness.
Collagen-Infused Water Market Competitive Landscape
Listed leaders compete with private specialists across clinical substantiation depth, creating a tiered structure where scale advantages in grass-fed bovine sourcing confront peptide bioavailability expertise concentration. The vendor base separates into three archetypes: multinational wellness conglomerates with ingestible skincare credibility, hydrolyzed peptide specialists competing on molecular weight specifications, and private-label contract manufacturers serving subscription channel entrants. M&A activity targets Japanese and German R&D clusters for microencapsulation capabilities, while capacity expansion concentrates in pasture-raised collagen sourcing regions.
Within the multinational wellness tier, Shiseido and Vital Proteins exemplify divergent geographic anchoring strategies. The Japanese conglomerate occupies a position built on decades of FOSHU-validated functional food credibility, while the North American entity represents scale-driven grass-fed bovine supply control. NeoCell sits within the peptide specialist archetype, with its hydrolyzed formulation focus competing on bioavailability claims in regimen-adherent consumer segments.
| Leading Market Players |
|---|
| Vital Proteins |
| NeoCell |
| Skinade |
| Shiseido |
| Gold Collagen |
| Vieve |
| Primal Kitchen |
| SkinnyFit |
| Zint |
| Others |
Value Network & Pricing Analysis
FOSHU certification in Japan gates both raw material qualification and premium shelf placement, compelling brands to absorb peptide bioavailability testing costs that separate clinically validated entrants from commodity-positioned alternatives across United States and European Union channels.
Pricing Analysis
Volume-discount tiering structures stratify collagen-infused water across subscription, health shop, and mass retail channels. Premium functional variants command three-tier pricing structure across premium, standard, and economy levels based on peptide concentration density and organic certification status. Price differentiation hinges on molecular weight specifications and clinical trial substantiation depth. Cost compression in mass-market flavored tiers is intensifying because supermarket slotting fee burdens concentrate procurement power with scaled beverage conglomerates. Retail consumers exhibit highest price sensitivity, while health enthusiasts absorb premiums for FOSHU-validated formulations.
Supply Chain Analysis
Brazil and Argentina anchor grass-fed bovine collagen sourcing for North American hydrolyzed peptide production. Enzymatic processing capacity draws from Japanese and German R&D clusters where microencapsulation expertise remains concentrated. Raw material dependencies include pasture-raised bovine hides, wild-caught marine biomass, and enzymatic hydrolysis reagents. Single-source vulnerability runs through drought-exposed South American cattle regions where climate volatility elevates input cost uncertainty. Distribution runs through cold chain-dependent supermarket networks in United States and Germany, ambient-stable direct-to-consumer subscription platforms, and pharmacy-adjacent channels targeting elderly joint mobility segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collagen-infused water functions as a service-attach opportunity where subscription algorithm curation and quarterly formulation rotation expand faster than single-SKU hardware velocity in direct-to-consumer wellness bundles.
For Market Incumbents: Shield peptide bioavailability credibility through captive supply partnerships with Japanese microencapsulation laboratories. Deepen backward integration into grass-fed bovine sourcing regions to mitigate drought-cycle input volatility. Secure FOSHU validation pathways ahead of EFSA claim compression to defend shelf access against marine-derived peptide entrants facing extended novel food timelines. For New Entrants and Emerging Players: Subscription personalization gaps in algorithmic flavor curation present white-space entry points where incumbents under-serve regimen-adherent consumers. Target India's FSSAI-liberalized functional beverage corridors through local co-manufacturing partnerships. Penetrate German beauty-from-within retail clusters via staff-assisted education models that justify premium positioning without mass-market slotting fee burdens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microencapsulation R&D and ambient-stable pouch production lines. Five-to-ten year viability favors platforms combining peptide stability expertise with direct-to-consumer subscription infrastructure. Prioritize acquisition targets possessing Japanese or German formulation laboratory relationships and established FOSHU compliance track records. Monitor EFSA beauty-claim enforcement actions as inflection signal for regulatory-driven market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Algorithmic curation captures lifetime value from United States metropolitan wellness consumers. |
| FOSHU Certification Investment | Japanese regulatory validation unlocks permitted beauty-from-within claims in East Asian corridors. |
| Backward Integration into Sourcing | Pasture-raised bovine supply control mitigates drought-driven input cost volatility in South America. |
| Microencapsulation R&D Partnership | Japanese laboratory alliances extend ambient shelf life beyond refrigerated dependency constraints. |
| Direct-to-Consumer Channel Expansion | Pouch-format bypass of supermarket slotting fees enables margin recovery in recurring revenue models. |
Research Methodology
Desk research of FOSHU registration databases, EFSA novel food assessments, and FDA dietary supplement guidance documents preceded structured interviews with peptide formulation chemists, health shop category buyers, subscription platform merchandising directors, and grass-fed bovine procurement leads. Primary fieldwork combined with secondary validation across customs import records, retail audit data, and clinical trial registries. Bottom-up volume modeling triangulated against top-down category spend estimates to reconcile channel-specific penetration assumptions.
Variance-decomposition framing isolated peptide concentration tiers, packaging format economics, and regional regulatory cluster effects across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, packaging technology, and distribution channel structure. CAGRs derived from install-base growth rates and expansion-cohort adoption curves. Industry-specific forecast inputs incorporated FOSHU approval timelines and EFSA claim substantiation thresholds.
Underlying assumptions cover stable FSSAI liberalization trajectories in India and sustained drought-frequency patterns in South American cattle regions, with deviation risk concentrated in EFSA beauty-claim enforcement severity and marine-derived peptide novel food assessment durations. Recalibration cycles align with material shifts in regional regulatory guidance and microencapsulation technology shelf-life breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Reconstituted Juice Market
Beverages
South America Bottled Water Market
Beverages
Morocco Bottled Water Market
Beverages
Sparkling Water Machine Market
Beverages
Canned Beverages Market
Beverages
US Bubble Tea Market
Beverages
Carbonated Soft Drinks Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Asia Pacific Dairy Based Beverages Market
Beverages
Drinking Water Market
Beverages
North America Energy Drink Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Juice Market
Beverages
CBD-Infused Beverages Market
Beverages
Juice Concentrates Market