
 Canned Beverages Market | 2026-2036
Canned Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Beverages Market Analysis
Convenience store networks across emerging economies is reconfiguring how beverage brands reach fragmented retail landscapes. The Coca-Cola Company leverages its bottling partnerships to sustain refrigerated point-of-sale presence in high-traffic urban locations. PepsiCo anchors volume through exclusive fountain and cooler contracts with regional convenience chains. Anheuser-Busch InBev competes by dominating beer-centric canning capacity and controlling aluminum procurement at scale.
Canned beverages are non-alcoholic and alcoholic drinks packaged in sealed, pressurized metal containers, typically aluminum or steel, with internal lacquer coatings preventing flavor contamination and extending shelf stability to 12–24 months. Their primary commercial purpose is to deliver portion-controlled, portable refreshment with minimal spoilage risk across ambient and chilled supply chains. Soda and beer categories occupy mature, high-volume positions where margin compression has intensified, while energy drinks lead growth trajectory as functional formulations command premium pricing. Aluminum can packaging dominates capital investment flows due to its superior recyclability and lightweight logistics profile compared to glass or plastic alternatives.
Regulators including the FDA, EPA, and EU REACH framework govern food-contact material safety, aluminum alloy composition limits, and endocrine-disrupting chemical restrictions in can linings. These standards directly shape formulation choices, coating technology R&D priorities, and market access requirements for imported canned products. Stakeholders must monitor evolving extended producer responsibility legislation and deposit-return expansion as these mechanisms increasingly determine packaging economics and regional competitive viability.
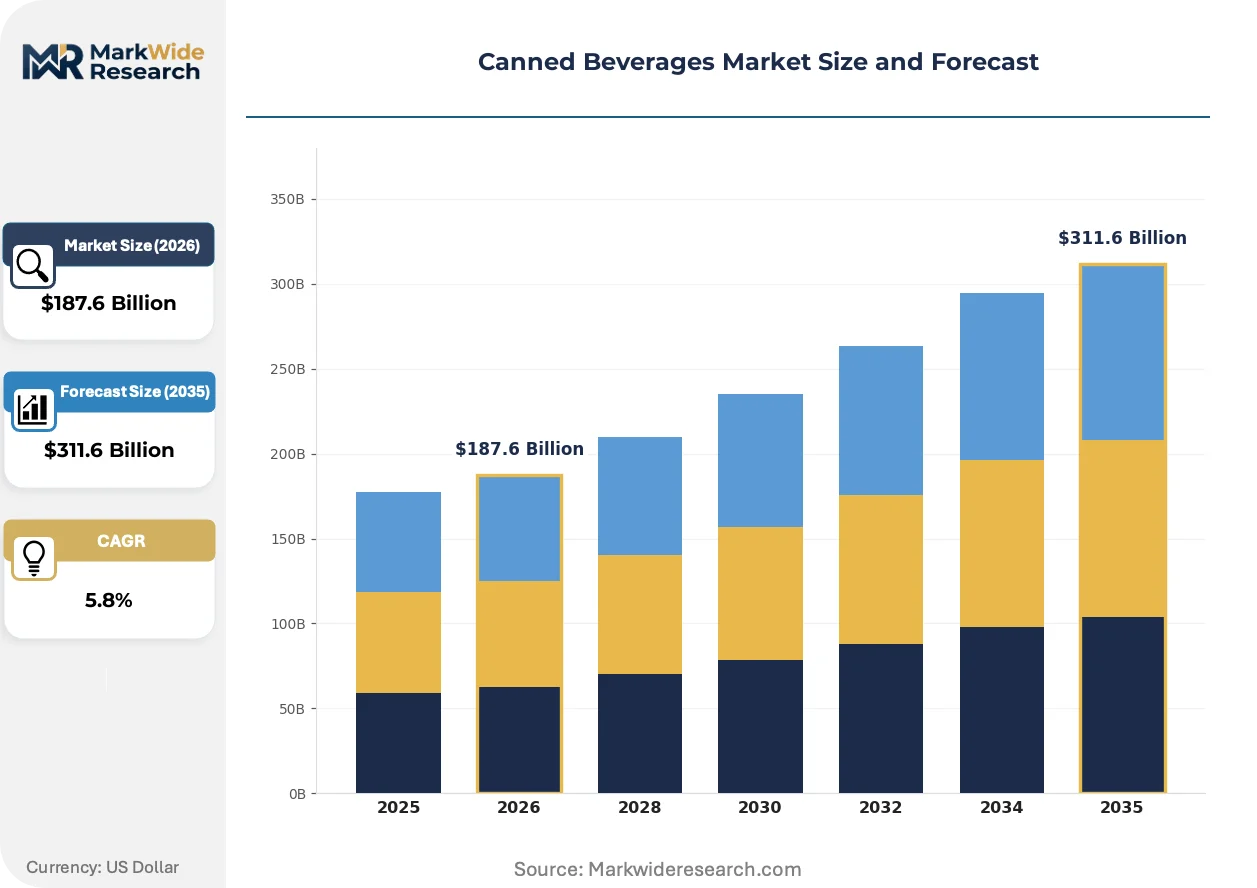
Market Dynamics
Aluminum procurement concentration among integrated smelters is compressing margin structures for independent can manufacturers, while EU recycling mandates and Southeast Asian demand surges are redrawing logistics networks. The structural tension between sustainability compliance and cost efficiency now dictates capacity placement decisions.
Growth Catalysts
- EU REACH coating standards:BPA-free epoxy alternatives are unlocking premium shelf positioning for compliant brands. Reformulation investments are accelerating as major retailers enforce chemical disclosure requirements.
- Indonesia convenience store expansion:Urban corridor penetration by minimart chains is creating dedicated cooler infrastructure for single-serve formats. Young consumer preference for portability is concentrating volume in 250ml and 330ml SKUs.
- Steel can lightweighting:Two-piece DWI (drawn and wall-ironed) technology is reducing material input per unit by 15-20%. Food-contact applications are adopting these specifications to offset aluminum price volatility.
Market Restraints
- Aluminum ingot price volatility:LME price swings and energy cost pass-through from smelters are destabilizing can manufacturing economics. Long-term supply agreements now carry indexed adjustment clauses.
- Deposit-return scheme fragmentation:Germany's DRS compliance costs diverge from Netherlands' operational models, complicating pan-European packaging standardization. Reverse logistics infrastructure requirements vary by jurisdiction.
- Glass bottle substitution in premium beer:Craft breweries in North American and European markets are reverting to amber glass for perceived quality differentiation. This limits aluminum can penetration in high-margin specialty segments.
Strategic Opportunities
- Vietnam urban corridor underpenetration:Ho Chi Minh City and Hanoi retail modernization is outpacing domestic canning capacity. Import substitution through local production joint ventures offers first-mover positioning.
- Asean cross-border e-commerce channels:Platform-integrated beverage subscriptions are bypassing traditional distributor markups. Direct-to-consumer aluminum multipacks are capturing trial-driven category switching.
- EU Green Deal circular packaging mandates:Recycled content minimums are creating preferential offtake terms for closed-loop aluminum suppliers. Vertical integration into scrap collection and re-melting is securing margin capture.
Industry Challenges
- Lacquer chemist talent scarcity:Food-contact coating formulation expertise is concentrating among retiring specialists. Knowledge transfer gaps are delaying BPA-NI (non-intent) certification timelines for new product lines.
- Line conversion capex intensity:Retrofitting steel lines for aluminum or upgrading to handle lighter-gauge specifications requires 18-24 month payback periods. Smaller canmakers are deferring modernization investments.
- Multi-jurisdiction compliance synchronization:FDA, EFSA, and emerging market food-contact notifications operate on divergent review cycles. Simultaneous launch strategies are fragmenting into sequential market entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Beverages Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda, Beer, Energy Drink, Juice Packaging Type: Aluminum Can, Steel Can, Plastic Bottle, Glass Bottle Customer Type: Retail Consumers, Events, Food Service, Vending Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Distributors |
| Companies Covered | RED BULL, Diageo, The Coca-Cola Company, Suntory Holdings Limited, Constellation Brands, PepsiCo, Anheuser-Busch InBev, Asahi Group Holdings, Ltd., Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Beverages Market Emerging Trajectories
Digital printing and smart packaging integration are compressing batch minimums and enabling hyper-localized marketing. These technologies are virtualizing traditional economies of scale in aluminum decoration.
Thermal inkjet and UV-cured digital printing is eliminating mechanical plate costs and reducing changeover downtime from hours to minutes. Craft beverage producers and regional brands are adopting this for limited-run seasonal designs. This technology is virtualizing the volume threshold that previously locked small brands out of custom aluminum aesthetics.
The EU Packaging and Packaging Waste Regulation (PPWR) is mandating recyclability-by-design assessments and recycled content tracking across all member states. Aluminum can producers must now maintain mass-balance documentation from smelter to shelf. Premium beverage categories are responding by marketing verified recycled content percentages as point-of-sale differentiators.
Young consumers in Jakarta, Bangkok, and Manila are shifting from at-home multi-pack purchasing to on-the-go single-serve acquisition. Convenience store cooler placement and mobile payment integration are displacing traditional supermarket bulk buying. This behavioral pivot is most visible in energy drink and ready-to-drink coffee segments, where impulse velocity now outweighs per-unit price sensitivity.
Canned Beverages Market Segmentation
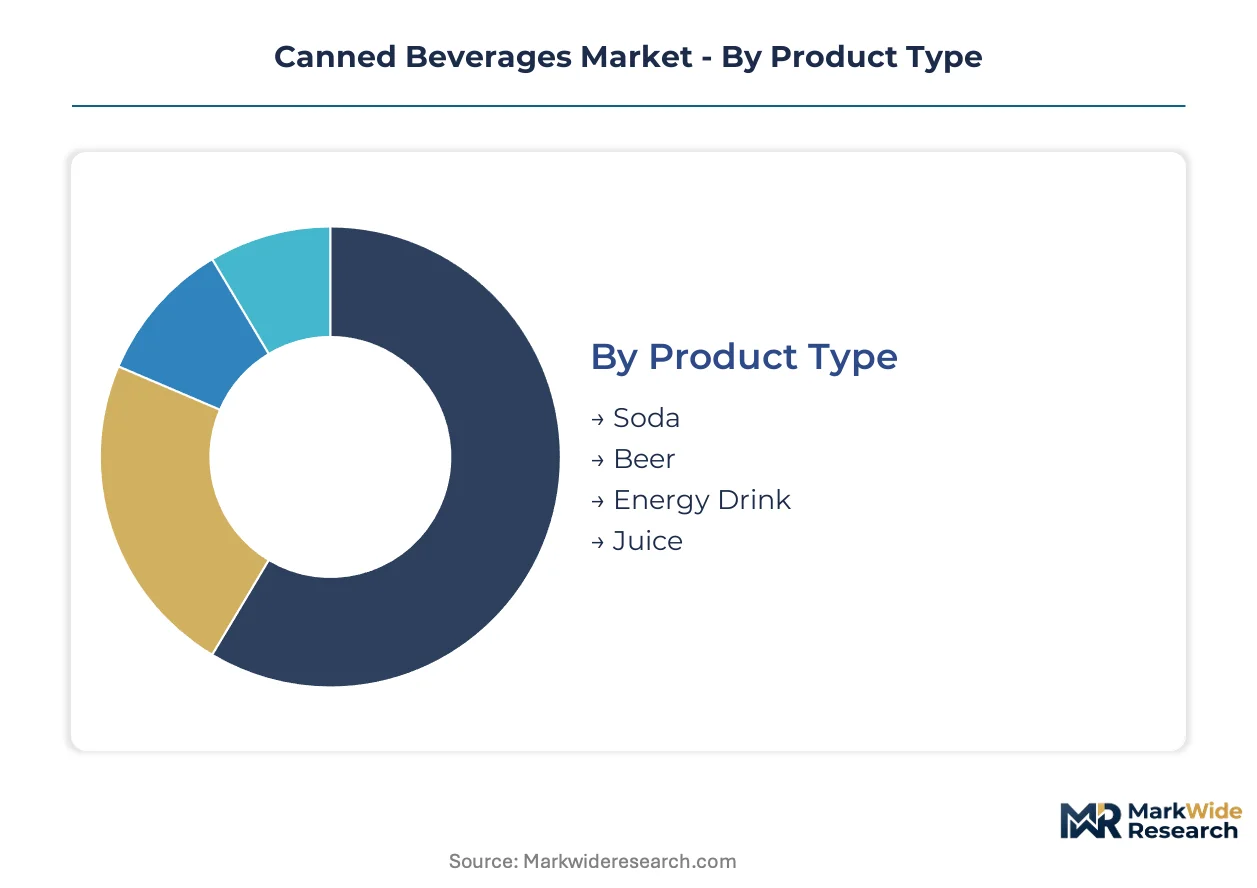
Canned beverages segment along four intersecting dimensions that determine margin capture and capital allocation. Product and packaging choices lock in 12-24 month formulation cycles, while distribution and customer type dictate working capital intensity and price realization.
Product Type:
Soda and beer rotate inventory fastest through established retail infrastructure, while energy drinks and juice operate on longer innovation-to-shelf timelines with higher promotional spend.
- Beer:Two-piece aluminum DWI cans with internal epoxy lacquer coatings dominate volume. Demand clusters in Germany, Brazil, and Vietnam where AB InBev and Heineken control refrigerated point-of-sale placement. Deposit-return scheme compliance adds per-unit cost in European markets.
- Energy Drink:Functional formulations with taurine, caffeine, and B-vitamin complexes command premium pricing. Southeast Asian urban corridors in Indonesia and Vietnam are absorbing capacity fastest as Red Bull and Monster localize production. Shelf stability requirements favor aluminum over glass for gym and convenience store distribution.
- Soda:Carbonated soft drinks in standard 330ml and 355ml formats represent mature volume with compressed margins. Coca-Cola and PepsiCo bottling partnerships sustain cooler exclusivity contracts across fragmented retail landscapes.
- Juice:Pasteurized and aseptically filled cans extend shelf life for ambient distribution. Niche positioning in school and institutional channels faces substitution pressure from refrigerated cartons.
Beer dominates installed base. Energy drink is where expansion concentrates.
Packaging Type:
Material selection trades off recyclability credentials against line conversion costs and supply security, with aluminum capturing sustainability-driven investment flows.
- Aluminum Can:Lightweight alloy with superior recyclability and 60-day closed-loop potential in EU markets. Indonesia and Vietnam import dependency is driving local smelter joint ventures. EU Green Deal recycled content minimums are reshaping procurement contracts.
- Steel Can:Two-piece DWI technology reduces material input 15-20% versus three-piece alternatives. Food-contact applications adopt steel specifications to hedge aluminum LME volatility. Tinplate sourcing concentrates among integrated European and Asian producers.
- Plastic Bottle:PET formats with barrier coatings compete in multi-serve and family-pack segments. Extended producer responsibility fees in EU markets disadvantage plastic versus aluminum on total cost.
- Glass Bottle:Amber and flint glass retains premium beer positioning in craft and specialty segments. North American and European microbreweries revert to glass for perceived quality differentiation, limiting can penetration in high-margin niches.
Aluminum can dominates installed base. Steel can lightweighting is where expansion concentrates.
Customer Type:
Retail and food service operate on contrasting payment terms and volume predictability, while events and vending demand surge capacity with minimal inventory buffers.
- Retail Consumers:Individual and household purchasing through supermarket and convenience channels. Impulse velocity in Jakarta, Bangkok, and Manila convenience stores is displacing at-home multi-pack buying for energy drinks and ready-to-drink coffee.
- Food Service:Restaurants, cafeterias, and quick-service outlets requiring fountain and cooler integration. Exclusive pouring contracts with regional chains anchor volume for PepsiCo and Coca-Cola bottling systems.
- Events:Stadiums, festivals, and concerts demanding single-serve formats with deposit-return compatibility. Seasonal demand spikes require flexible canning capacity and regional logistics pre-positioning.
- Vending:Automated retail requiring 250ml and 330ml SKUs with anti-vandal packaging specifications. Mobile payment integration in Southeast Asian urban corridors is modernizing machine infrastructure.
Retail consumers dominate installed base. Food service fountain contracts are where expansion concentrates.
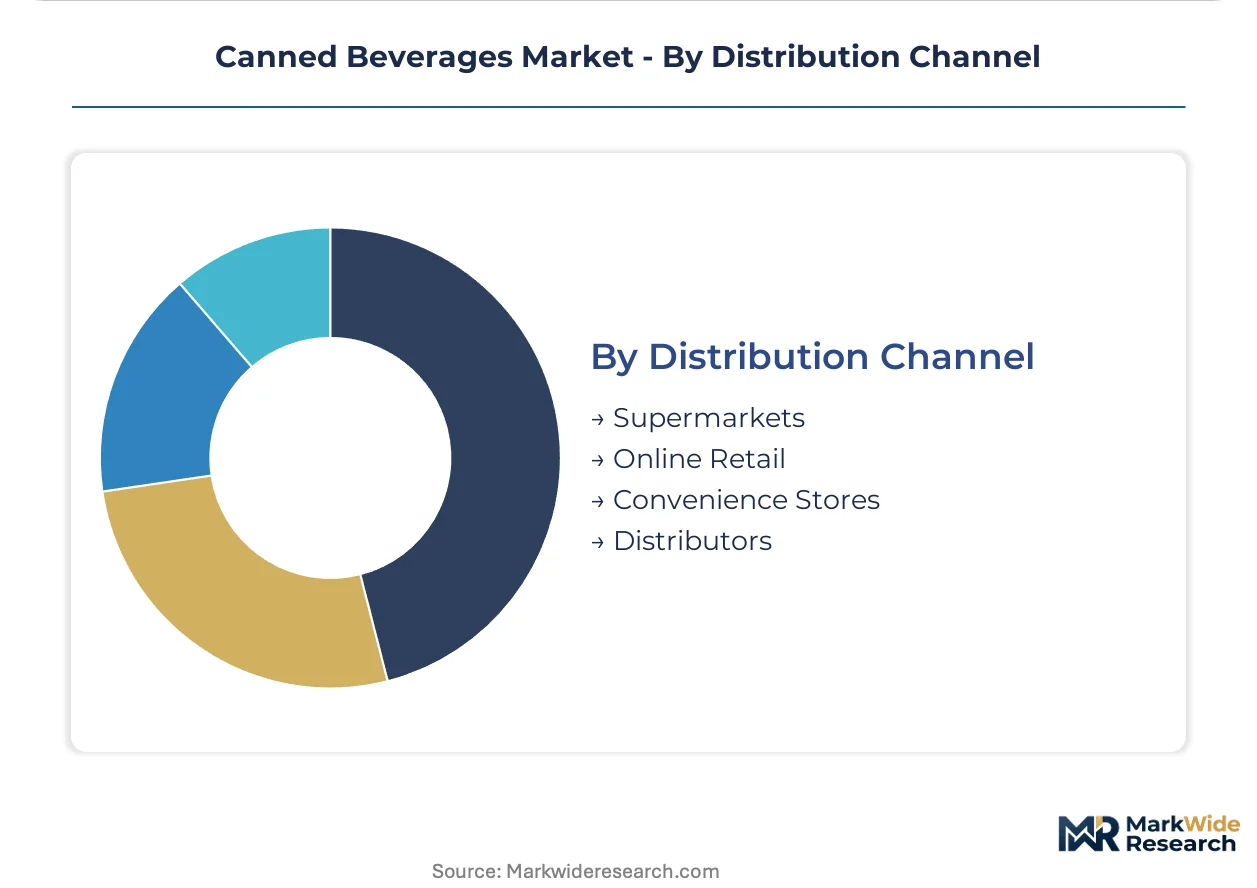
Distribution Channel:
Channel selection determines margin capture through markup stacking, with direct retail relationships compressing distributor layers in urban corridors.
- Convenience Stores:Minimart chains in Indonesia and Vietnam are expanding dedicated cooler infrastructure for single-serve formats. Young consumer preference for portability concentrates volume in 250ml and 330ml SKUs with mobile payment integration.
- Supermarkets:Hypermarket and grocery chains with multi-pack and promotional display capacity. Traditional bulk buying is losing share to convenience and online fragmentation in Southeast Asian markets.
- Online Retail:Platform-integrated subscriptions and direct-to-consumer multipacks bypass traditional distributor markups. ASEAN cross-border e-commerce enables trial-driven category switching without import intermediary layers.
- Distributors:Wholesale and route-to-market intermediaries serving fragmented rural and independent retail. Margin compression from retail and online disintermediation is forcing consolidation among regional distributors.
Supermarkets dominate installed base. Convenience store cooler placement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European aluminum can import flows, while Vietnam's Cai Mep-Thi Vai deepwater port complex anchors Southeast Asian distribution networks for beverage packaging materials.
United States
Convenience store cooler infrastructure expansion in Texas and Florida corridors drives single-serve aluminum can absorption. The FDA governs food-contact coating safety under 21 CFR regulations, mandating BPA-free epoxy alternatives for domestic production. Chicago and Milwaukee industrial clusters concentrate two-piece DWI can manufacturing capacity serving Midwest beverage bottlers.
Germany
Deposit-return scheme compliance costs reshape aluminum procurement economics for beer and soft drink canners. The country's national packaging regulator enforces EU Green Deal circularity mandates through extended producer responsibility frameworks. Bavaria's beverage production belt around Munich anchors Heineken and AB InBev canning joint ventures with localized aluminum sourcing.
Indonesia
Minimart chain penetration in Jakarta and Surabaya urban corridors concentrates demand for 250ml energy drink formats. The country's national food and drug regulator oversees food-contact material notifications for imported can linings. Java's manufacturing corridor is attracting aluminum smelter joint ventures to reduce import dependency for beverage packaging.
Vietnam
Ho Chi Minh City retail modernization outpaces domestic canning capacity, creating import substitution opportunities. The Ministry of Industry and Trade implements ASEAN harmonized standards for food-contact materials in cross-border trade. The Hanoi-Haiphong industrial zone is emerging as a production hub for two-piece aluminum cans serving northern ASEAN markets.
Brazil
São Paulo state beverage bottlers are expanding aluminum can lines to serve carnival and football event seasonal demand spikes. ANVISA regulates epoxy resin migration limits in can linings under Mercosur technical standards. The Campinas industrial cluster concentrates Crown Holdings and Ball Corporation can manufacturing for South American export.
Canned Beverages Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The canned beverages market exhibits consolidated platform control alongside fragmented specialty production. Three archetypes dominate: multinational beverage conglomerates with captive canning capacity, independent aluminum can manufacturers with scale-driven cost positions, and regional craft producers outsourcing to toll canners. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with aluminum procurement alliances and cooler exclusivity contracts locking in route-to-market access.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo exemplify platform integrators leveraging bottling partnerships to secure refrigerated point-of-sale placement across fragmented retail landscapes. Anheuser-Busch InBev occupies a position representing beer-centric canning capacity concentration and aluminum procurement scale advantages. These three anchors illustrate how beverage platform control translates into packaging specification influence and supply chain prioritization.
| Leading Market Players |
|---|
| RED BULL |
| Diageo |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Constellation Brands |
| PepsiCo |
| Anheuser-Busch InBev |
| Asahi Group Holdings, Ltd. |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
Aluminum LME price volatility between integrated smelters and independent can manufacturers determines both three-tier pricing spreads across premium, standard, and economy beverage segments and the geographic distribution of canning capacity toward Southeast Asian demand corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the canned beverages market. Premium functional beverages command price realization through BPA-free epoxy certification and verified recycled content claims, while standard soda and beer segments compete on volume scale and cooler exclusivity contracts. Cost compression in economy tiers is intensifying because aluminum ingot pass-through clauses and energy surcharges from smelters compress manufacturing margins. Food service buyers with fountain pouring contracts exhibit lowest price sensitivity, whereas retail consumers in Southeast Asian minimart channels demonstrate highest elasticity to per-unit pricing.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk assessment for aluminum can manufacturers. Primary aluminum production concentrates in China, Indonesia, and Australia, while can sheet rolling capacity clusters in Germany, Brazil, and Japan. The industry draws from bauxite ore, alumina refining, and primary smelting as sequential input dependencies. Single-source vulnerability in epoxy resin lacquer formulations for food-contact coatings creates regulatory chokepoint exposure. Distribution runs through port-centric logistics networks anchored at Rotterdam, Cai Mep-Thi Vai, and Santos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned beverages market functions as a defensive-moat industry where cooler exclusivity contracts and bottling partnership networks create switching costs that entrench incumbents against new capacity entrants.
For Market Incumbents: Build regulatory moats through preemptive BPA-NI certification investment and EU Green Deal mass-balance documentation capabilities. Deepen backward integration into aluminum scrap collection and re-melting to secure closed-loop supply advantages. Anchor capacity in Vietnam and Indonesia ahead of domestic smelter joint venture completion to lock in route-to-market positioning before import substitution accelerates. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underpenetrated northern corridor around the Hanoi-Haiphong industrial zone where retail modernization outpaces domestic canning capacity. Target ASEAN cross-border e-commerce channels for direct-to-consumer aluminum multipack trials that bypass traditional distributor markups. Lead with digital printing-enabled seasonal customization to differentiate against multinational scale economies in limited-run craft and functional beverage segments. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation recycled content mandates reshape the acquisition landscape toward closed-loop aluminum suppliers with verified mass-balance systems. Long-term viability centers on five-to-ten-year circular packaging compliance trajectories rather than spot commodity exposure. Monitor smelter joint venture announcements in Indonesia and Vietnam as inflection signals for regional supply security repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Vietnam | Ho Chi Minh City retail modernization outpaces domestic canning infrastructure, creating first-mover positioning. |
| Backward Integration into Scrap Collection | EU Green Deal recycled content minimums secure preferential offtake terms and margin capture for closed-loop suppliers. |
| Digital Printing Technology Adoption | Thermal inkjet and UV-cured systems compress batch minimums and enable hyper-localized craft beverage marketing. |
| BPA-NI Certification Investment | EU REACH coating standards and retailer chemical disclosure requirements accelerate reformulation R&D prioritization. |
| Convenience Store Cooler Contracts | Indonesia minimart chain expansion creates dedicated infrastructure for 250ml and 330ml single-serve formats. |
Methodological Framework
Cross-validation between primary interviews with beverage industry stakeholders and secondary regulatory filings anchors the qualitative findings. Can manufacturing executives, aluminum procurement leads at integrated smelters, convenience store category buyers, and food-contact coating chemists provided operational perspectives. Secondary sources include FDA 21 CFR food-contact notifications, EU EFSA scientific opinions on epoxy resins, ASEAN harmonized standards documentation, and customs trade flow records. Bottom-up volume modeling triangulates against top-down category spend analysis.
Calibration against historical aluminum LME price cycles and can manufacturing capacity utilization rates informs the projection framework. Segmentation dimensions span product type, packaging material, distribution channel, and customer archetype across the modeling period. CAGRs derive from trend extrapolation moderated by regulatory inflection points and raw material cost pass-through elasticity. Industry-specific inputs include deposit-return scheme compliance cost trajectories and digital printing adoption curves in craft beverage segments.
Sensitivities concentrate around aluminum price volatility, EU recycled content mandate enforcement timing, and Southeast Asian retail infrastructure buildout pace. Forecasts reflect assumptions on smelter joint venture completion and BPA-NI certification pipeline throughput. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
United States and Australia Coconut Water Market
Beverages
Adaptogenic Beverages Market
Beverages
Breakfast Drink Market
Beverages
Whole Grain Drinks Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Electrolyte Mixes Market
Beverages
North America Cold Pressed Juices Market
Beverages
Powdered Soft Drinks Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Tonic Water Market
Beverages
Premium Water Market
Beverages
Blackstrap Molasses Market
Beverages
North America Fruit Juice Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
India Soy Beverages Market
Beverages
Superfood Infused Beverages Market