
 Sports Drink Market | 2026-2036
Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Drink Market Analysis
Fitness enthusiasts are unwinding the historical dominance of casual drinkers in sports drink procurement. PepsiCo anchors its position through massive manufacturing scale and shelf-space control across mass retail channels. The Coca-Cola Company leverages its Powerade portfolio to sustain presence in institutional sports settings and collegiate athletics. Abbott Nutrition differentiates with clinically positioned electrolyte formulations targeting endurance athletes and medical hydration protocols.
Sports drinks are aqueous beverages containing dissolved electrolytes—primarily sodium, potassium, and magnesium—along with carbohydrates in specific osmolarity ranges designed to accelerate gastric emptying and fluid absorption during physical exertion. Manufacturers blend these formulations through hot-fill or aseptic processing to achieve shelf stability without compromising mineral bioavailability. Electrolyte drinks dominate current volume due to established athlete demand and universal gym-channel penetration, while protein drinks represent the fastest-expanding category as resistance training culture spreads beyond competitive sports into mainstream fitness. Vegan options command premium positioning and higher margins, though they occupy a narrower addressable base constrained by ingredient cost structures and taste formulation complexity.
The FDA governs sports drink labeling and nutrient content claims in the United States, while EFSA establishes permissible health claims and additive thresholds across European markets. Both frameworks are tightening scrutiny on sugar content and natural versus artificial ingredient ratios, forcing reformulation investments that favor established players with dedicated R&D infrastructure. Stakeholders must monitor evolving clean-label standards and emerging state-level sugar tax proposals that could reshape regional profitability profiles and channel strategies.
Market Dynamics
Fitness enthusiasts now drive faster volume expansion than casual consumers, while FDA and EFSA disclosure mandates force simultaneous reformulation across sugar content and electrolyte labeling standards.
Growth Catalysts
- Resistance training proliferation:Gym memberships and home workout equipment adoption are expanding protein drink demand beyond competitive athletics into mainstream fitness routines.
- Clean-label mandates:EFSA tightening on natural versus artificial ingredient ratios creates competitive separation for manufacturers with dedicated formulation infrastructure.
- Endurance event expansion:Marathon and triathlon participation in Germany, Brazil, and the United States sustains institutional demand for clinically positioned electrolyte protocols.
Market Restraints
- Plant protein cost volatility:Pea and rice protein isolate prices constrain vegan formulation margins and limit mass-market penetration.
- Supply concentration risk:Aseptic processing equipment and specialized mineral suppliers cluster in Germany and the United States, creating geographic vulnerability.
- Sugar tax exposure:State-level proposals in multiple US jurisdictions threaten profitability in conventional sports drink segments without reformulation investment.
Strategic Opportunities
- Medical hydration protocols:Abbott Nutrition's clinical positioning demonstrates white space for electrolyte formulations targeting post-surgical and geriatric hydration.
- Direct-to-athlete channels:Subscription models bypassing mass retail capture higher lifetime value from committed endurance participants.
- EU Green Deal alignment:Packaging sustainability requirements favor early movers in biodegradable bottle and recycled content certification.
Industry Challenges
- Flavor formulation complexity:Vegan protein sources require specialized masking technologies that extend R&D timelines and increase sensory testing costs.
- Certification backlog:FDA electrolyte labeling compliance deadlines compress reformulation windows for mid-tier manufacturers without in-house regulatory teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Drink Market |
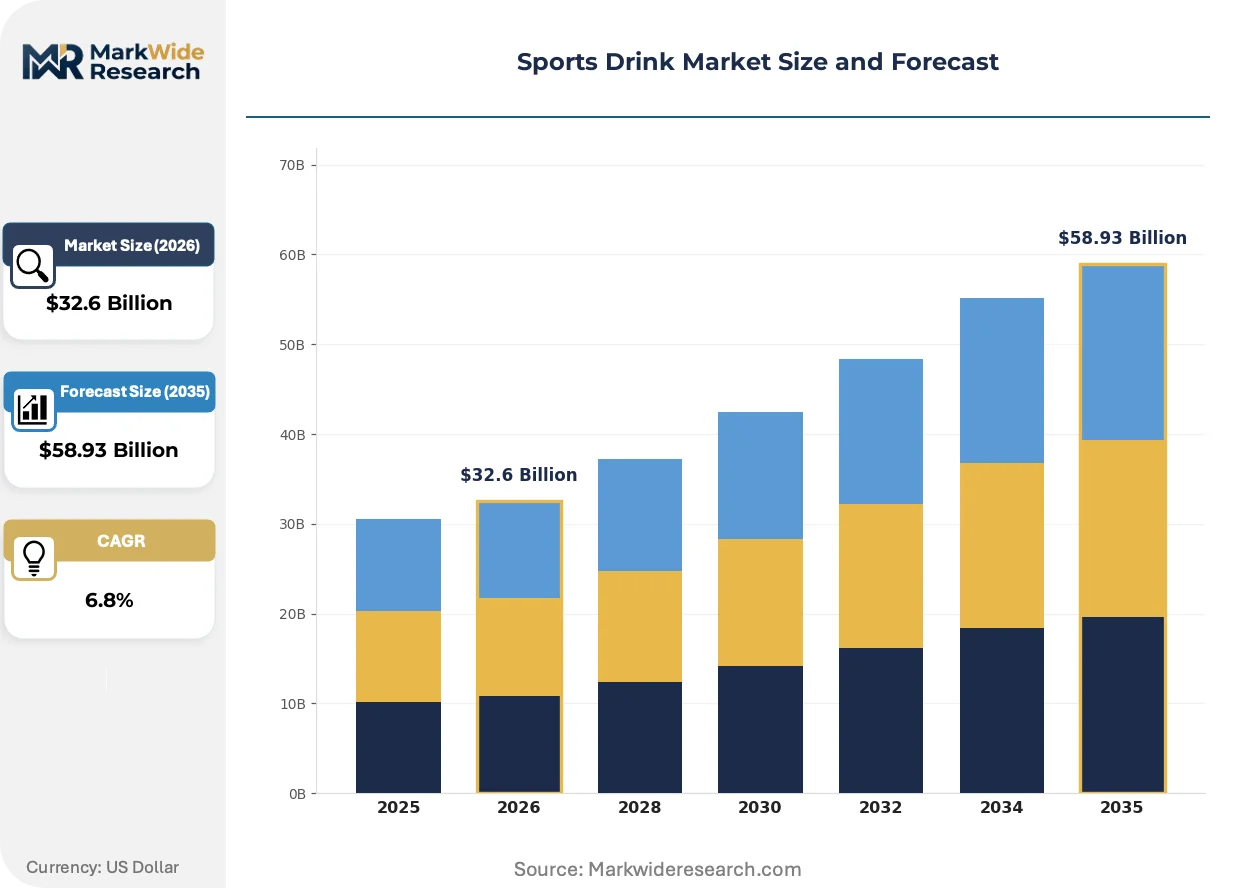
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $58.93 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Drinks, Protein Drinks, Carbohydrate Drinks, Vegan Options Distribution Channel: Supermarkets, Health Stores, Online Retail, Gyms End User: Athletes, Fitness Enthusiasts, Casual Drinkers, Health-Conscious Consumers Flavor Profile: Citrus, Berry, Tropical, Herbal |
| Companies Covered | Abbott Nutrition, Red Bull GmbH, PepsiCo, Otsuka Pharmaceutical Co., Ltd., Suntory Holdings, The Coca-Cola Company, Monster Beverage Corporation, AJE Group, BodyArmor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Drink Market Emerging Trajectories
Formulation science and distribution architecture are converging to compress product development cycles while fragmenting channel control away from traditional mass retail gatekeepers.
Precision electrolyte dosing technology is miniaturizing. Microencapsulation systems now enable customizable sodium and potassium release profiles tailored to individual sweat-rate data. Endurance athletes and collegiate sports programs are adopting these personalized hydration protocols fastest. This capability is miniaturizing the addressable market for one-size-fits-all formulations while creating subscription-based revenue pools.
EFSA's evolving health claims framework is tightening permissible language around performance benefits and mineral bioavailability. Manufacturers must now substantiate gastric emptying claims through clinical validation. Protein drink segments face the steepest compliance costs as they navigate the boundary between sports nutrition and medical food classification.
Gym-channel procurement is consolidating around private-label and exclusive co-manufactured lines. Boutique fitness chains and CrossFit affiliates are displacing supermarket dominance for core electrolyte volume. Brazil and Germany exhibit the fastest channel shift as independent gym networks expand faster than mass retail shelf space.
Sports Drink Market Segmentation
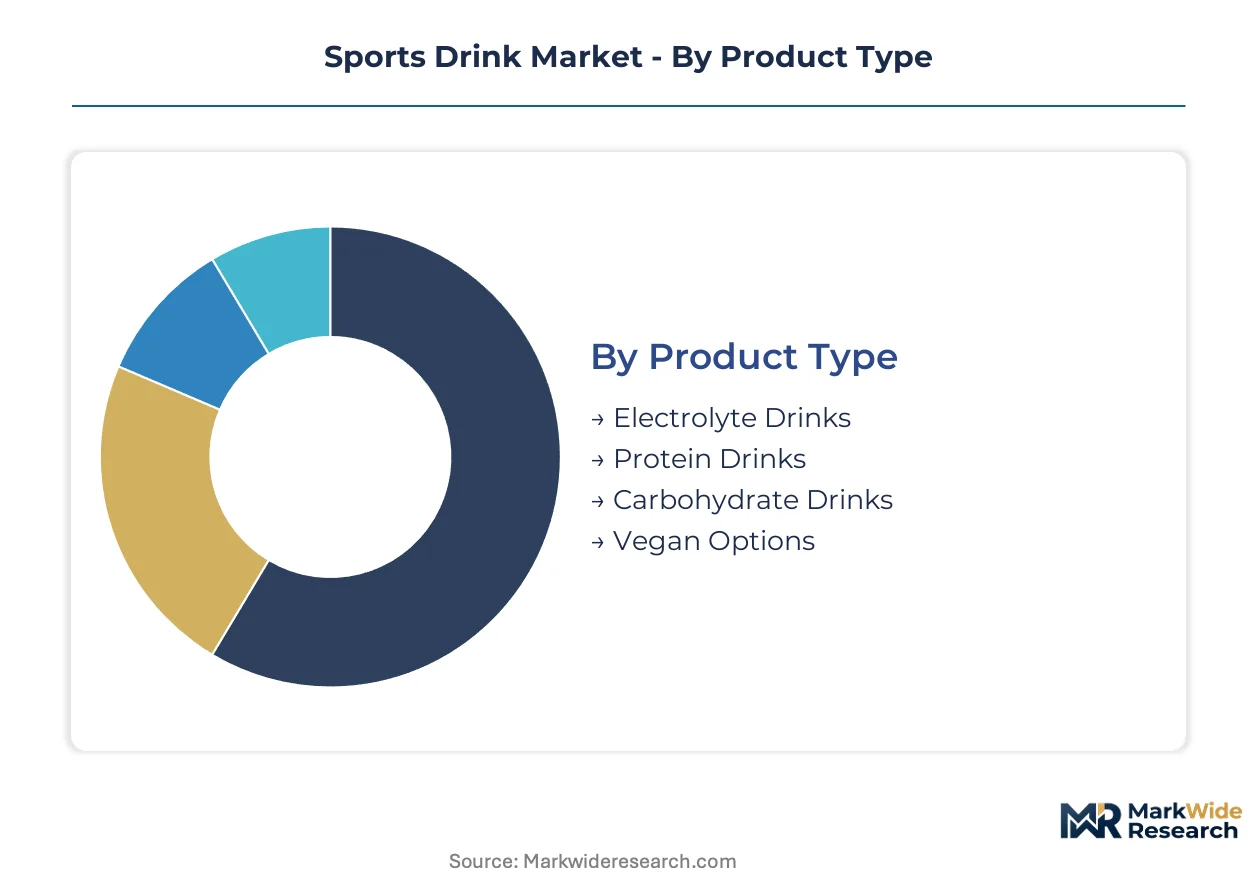
Sports drink manufacturers configure their portfolios across four distinct category axes. Each axis reveals divergent margin structures and channel control dynamics that reshape competitive positioning.
Product Type:
Margin pools concentrate in clinically validated formulations with premium positioning authority.
- Electrolyte Drinks:Aqueous solutions with dissolved sodium, potassium, and magnesium in specific osmolarity ranges accelerate gastric emptying during exertion. Demand clusters in Germany, Brazil, and the United States where marathon and triathlon participation sustains institutional procurement. FDA and EFSA tightening on electrolyte labeling creates compliance separation favoring established R&D infrastructure.
- Protein Drinks:Ready-to-drink formulations containing whey, casein, or plant isolates target muscle protein synthesis windows. Resistance training culture in Brazil and the United States drives fastest volume expansion beyond competitive athletics into mainstream fitness routines. Pea and rice protein cost volatility constrains vegan-adjacent positioning.
- Carbohydrate Drinks:High-glycemic maltodextrin or sucrose solutions deliver rapid energy substrate replacement. Collegiate athletics programs in the United States anchor institutional demand.
- Vegan Options:Plant-based protein and electrolyte formulations command premium shelf positioning. Ingredient cost structures and flavor masking complexity limit mass-market penetration.
The dominant share belongs to Electrolyte Drinks, while Protein Drinks are gaining share fastest.
Distribution Channel:
Channel control is fragmenting away from traditional mass retail gatekeepers toward fitness-embedded procurement.
- Supermarkets:Mass retail shelf space controlled by PepsiCo and The Coca-Cola Company anchors volume for casual consumption. State-level sugar tax proposals in multiple US jurisdictions threaten profitability in conventional segments.
- Health Stores:Specialized retail captures premium positioning for clean-label and organic formulations. EFSA natural versus artificial ingredient scrutiny drives assortment differentiation.
- Online Retail:Direct-to-consumer subscription models bypass mass retail gatekeepers. Endurance athletes in Germany and the United States generate highest lifetime value through personalized hydration protocols.
- Gyms:Boutique fitness chains and CrossFit affiliates displace supermarket dominance for core electrolyte volume. Brazil and Germany exhibit fastest channel shift as independent gym networks expand.
Gyms are expanding most quickly as a procurement channel, though supermarkets retain the largest volume base.
End User:
Customer archetypes are reordering around exertion intensity and purchase frequency rather than demographic segmentation.
- Athletes:Competitive and collegiate participants demand clinically validated electrolyte protocols with precise mineral dosing. Marathon and triathlon expansion in Germany, Brazil, and the United States sustains institutional demand.
- Fitness Enthusiasts:Regular gym-goers and home workout adopters drive protein drink expansion beyond competitive sports. This segment now outpaces casual drinkers in volume growth velocity.
- Casual Drinkers:General consumers seeking refreshment or mild hydration represent historical volume anchor. Share erosion accelerates as fitness culture mainstreams.
- Health-Conscious Consumers:Buyers prioritizing clean-label, low-sugar, or functional ingredients align with EFSA and FDA disclosure mandates. Abbott Nutrition's clinical positioning demonstrates white space capture.
Fitness Enthusiasts show the steepest expansion trajectory, while Athletes maintain the highest per-capita spend.
Flavor Profile:
Taste formulation complexity varies significantly across botanical and synthetic ingredient pathways.
- Citrus:Lemon, lime, and orange profiles dominate electrolyte formulations with established palatability across athlete demographics. Masking technologies for mineral bitterness are most advanced here.
- Berry:Strawberry, raspberry, and mixed berry variants capture health-conscious positioning. Natural flavor cost premiums align with clean-label mandate compliance.
- Tropical:Mango, pineapple, and coconut profiles target Brazil and southern United States regional preferences. Seasonal demand fluctuation exceeds temperate flavor categories.
- Herbal:Botanical infusions with adaptogenic or functional positioning command niche premium. Sensory testing costs and FDA health claims substantiation create barrier to scale.
Citrus holds the established volume base, though Berry is climbing fastest on clean-label alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in Brazil anchors South American beverage export capacity, while Rotterdam's liquid bulk terminals handle European concentrate flows. These logistics nodes underwrite regional manufacturing placement for sports drink formulation and packaging.
United States
Collegiate athletics procurement and marathon participation in California and Texas sustain institutional electrolyte demand. FDA labeling mandates on sugar disclosure and electrolyte content tighten compliance windows for mid-tier manufacturers. Greater Boston clusters sports nutrition R&D facilities alongside Abbott Nutrition's clinical formulation operations.
Germany
Triathlon expansion in Bavaria and North Rhine-Westphalia drives precision hydration protocol adoption. EFSA health claims substantiation requirements force clinical validation investments for gastric emptying assertions. Hamburg's beverage co-manufacturing corridor concentrates aseptic processing capacity serving Nordic export markets.
Brazil
Independent gym network expansion in São Paulo and Rio de Janeiro outpaces mass retail shelf growth. ANVISA tightening on nutritional supplement classification creates boundary uncertainty between sports drinks and medical foods. The Port of Santos corridor anchors concentrate import and finished goods export logistics for Mercosur distribution.
Japan
Aging demographics and geriatric hydration protocols expand medical-adjacent electrolyte positioning beyond athletic use. METI standards on functional food claims require mineral bioavailability documentation. Kansai region manufacturing clusters serve domestic precision dosing demand and Southeast Asian export markets.
United Kingdom
CrossFit affiliate density in London and Manchester displaces supermarket dominance for core electrolyte procurement. FSA alignment with EFSA natural ingredient ratios drives clean-label reformulation timelines. Midlands co-manufacturing hubs process private-label volumes for boutique fitness chain exclusive lines.
Sports Drink Market Vendor Landscape
Concentration sits with multinational beverage conglomerates controlling mass retail shelf space and institutional sports procurement channels. The vendor base stratifies across three tiers: scale-driven mass-market operators, clinically positioned nutrition specialists, and emerging functional beverage disruptors. Dominant competitive moves include exclusive distribution partnerships with collegiate athletics programs and backward integration into aseptic processing equipment.
Among diversified beverage conglomerates, PepsiCo and The Coca-Cola Company exemplify scale-driven archetypes with mass retail channel control. Abbott Nutrition occupies the clinical-specialist position with medical hydration protocol positioning. Red Bull GmbH represents the functional beverage disruptor archetype with energy-adjacent brand extension into sports hydration. These three anchors illustrate divergent margin capture strategies across institutional, retail, and direct-to-consumer vectors.
| Leading Market Players |
|---|
| Abbott Nutrition |
| Red Bull GmbH |
| PepsiCo |
| Otsuka Pharmaceutical Co., Ltd. |
| Suntory Holdings |
| The Coca-Cola Company |
| Monster Beverage Corporation |
| AJE Group |
| BodyArmor |
| Others |
Supply Flow & Price Mechanics
FDA electrolyte labeling compliance deadlines gate both supplier qualification and price differentiation simultaneously, compressing reformulation windows for mid-tier manufacturers while rewarding established players with dedicated regulatory infrastructure.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with collegiate athletics programs and gym chains extracting scale concessions unavailable to individual consumers. Price differentiation rests on clean-label certification status and electrolyte precision dosing capabilities, with EFSA natural-ingredient tiers commanding shelf-space premiums. Cost compression in conventional sugar-based formulations is intensifying because of state-level sugar tax proposals across multiple US jurisdictions. Casual drinkers exhibit highest price sensitivity, while endurance athletes demonstrate lowest elasticity due to protocol adherence requirements.
Supply Chain Analysis
Inbound logistics costs through the Port of Santos and Rotterdam liquid bulk terminals concentrate formulation input flows, with container availability fluctuations rippling through concentrate pricing. Aseptic processing equipment and specialized mineral suppliers cluster in Germany and the United States, creating geographic vulnerability for mid-tier manufacturers. Raw material dependencies center on maltodextrin, pea protein isolate, and potassium chloride sourcing. Single-source vulnerability in aseptic filling machinery creates procurement risk. Distribution runs through mass retail gatekeepers, boutique fitness chain private-label networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports drink market sits in early-cycle expansion as fitness enthusiasts displace casual drinkers, with resistance training culture penetration still below saturation thresholds in Brazil and Germany.
For Market Incumbents: Consolidate formulation infrastructure around precision electrolyte dosing capabilities to defend against functional beverage disruptors entering through personalized hydration protocols. Deepen backward integration into aseptic processing equipment to reduce supplier concentration exposure. Capture exclusive distribution partnerships with expanding independent gym networks before shelf-space fragmentation accelerates.
For New Entrants and Emerging Players: Anchor in medical hydration protocols targeting post-surgical and geriatric segments, where Abbott Nutrition's clinical positioning demonstrates white-space viability. Brazil's independent gym network expansion outpaces mass retail shelf growth, offering the most penetrable geography. Deploy direct-to-athlete subscription models to bypass incumbent-controlled retail gatekeepers.
For Investors and Strategic Acquirers: EFSA health claims substantiation deadlines reshape the acquisition landscape by elevating regulatory infrastructure value in target screening. Five-to-ten-year viability favors clinically positioned nutrition specialists with FDA-validated electrolyte protocols over commodity formulation players. Acquisition target archetypes include aseptic co-manufacturers with gym-channel relationships and precision-dosing technology holders. Watch FDA enforcement patterns on electrolyte labeling as the inflection indicator for compliance-cost acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Electrolyte Dosing Technology Deployment | Microencapsulation capabilities enable personalized hydration protocols for endurance athletes in Germany and the United States. |
| Gym-Channel Exclusive Partnership | Boutique fitness chain procurement displaces supermarket dominance in Brazil and Germany volume expansion. |
| Clean-Label Reformulation Investment | EFSA natural-ingredient ratio compliance creates competitive separation for manufacturers with dedicated R&D infrastructure. |
| Direct-to-Consumer Subscription Launch | Bypassing mass retail gatekeepers captures higher lifetime value from committed endurance participants. |
| Medical Hydration Protocol Extension | Abbott Nutrition's clinical positioning demonstrates white space for post-surgical and geriatric electrolyte applications. |
Methodological Framework
Desk research of FDA enforcement patterns, EFSA health claims registers, and gym-chain procurement databases preceded structured interviews with sports nutrition formulators, regulatory affairs directors, boutique fitness chain procurement managers, and aseptic co-manufacturing executives. Secondary validation drew from ANVISA nutritional supplement classifications, customs trade data on concentrate flows through Santos and Rotterdam, and Nielsen retail audit information. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, distribution channel, end-user archetype, and flavor profile segmentation dimensions informed CAGR derivation through regression-based trend extrapolation and adoption-curve analysis. Input variables included sports participation rate trajectories, health club membership expansion, and regulatory compliance cost indices. Throughout the forecast period, the analytical framework weighted gym-channel shift velocity and clean-label mandate penetration as primary demand modifiers.
Decision-makers should treat outputs as directional under assumptions of continued EFSA disclosure tightening and steady Brazil gym network expansion; material deviation in sugar tax enactment timing or protein isolate cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as FDA electrolyte labeling enforcement intensity and ANVISA medical-food boundary clarity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Italy Bottled Water Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Grab and Go Bottles Market
Beverages
Beverages Market
Beverages
Global Electrolyte Drinks Market
Beverages
Baby Drinks Market
Beverages
BBQ Charcoal Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Flavored Powder Drinks Market
Beverages
Canned Beverages Market
Beverages
Sparkling Soda Market
Beverages
Milk Tea Powder Market
Beverages
Ginger Ale Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market