
 Juice Concentrates Market | 2026-2036
Juice Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Juice Concentrates Market Intelligence
Asset-light processing models, which reduce upfront capital expenditure on facilities, is rewriting the competitive landscape for new entrants. Archer Daniels Midland Company leverages its extensive global sourcing network to manage input cost volatility. Döhler GmbH differentiates through its integrated portfolio of natural ingredients and application-specific solutions for the beverage industry. Südzucker AG sustains its market position through large-scale production capabilities in key fruit-growing regions.
Juice concentrates are fruit juices from which a significant portion of water content has been removed, typically through evaporation or reverse osmosis. These products are standardized to a specific Brix level, ensuring consistent sweetness and flavor intensity for reconstitution or use in food manufacturing. Within the market's structure, frozen and liquid forms dominate logistical chains due to their stability, while powder forms are gaining traction in nutraceutical applications. The beverages segment remains the largest application, but demand from bakery and confectionery producers for natural sweeteners is expanding.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) mandate strict controls on pesticide residues and contaminant levels. In countries like India, the FSSAI's labeling rules for fruit content in beverages directly influence concentrate usage by manufacturers. Future success depends on a supplier's ability to provide traceable, sustainably sourced concentrates that meet evolving clean-label consumer expectations.
Market Dynamics
The central force shaping the market is the consumer-led shift towards clean-label products, compelling food and beverage manufacturers to reformulate with natural ingredients. Stricter food labeling regulations from bodies like the FDA and EFSA amplify this pressure.
Growth Catalysts
- Nutraceutical Sector Demand:The nutraceutical industry requires functional ingredients for supplements, providing a consistent demand stream for vitamin-rich fruit concentrates.
- Regulatory Push for Transparency:Labeling mandates from the FDA and EFSA compel companies to use natural concentrates instead of artificial flavors and sweeteners.
- Beverage Production in China:Concentrated procurement by Chinese beverage manufacturers for premium fruit drinks anchors significant regional demand for specific fruit types.
Market Restraints
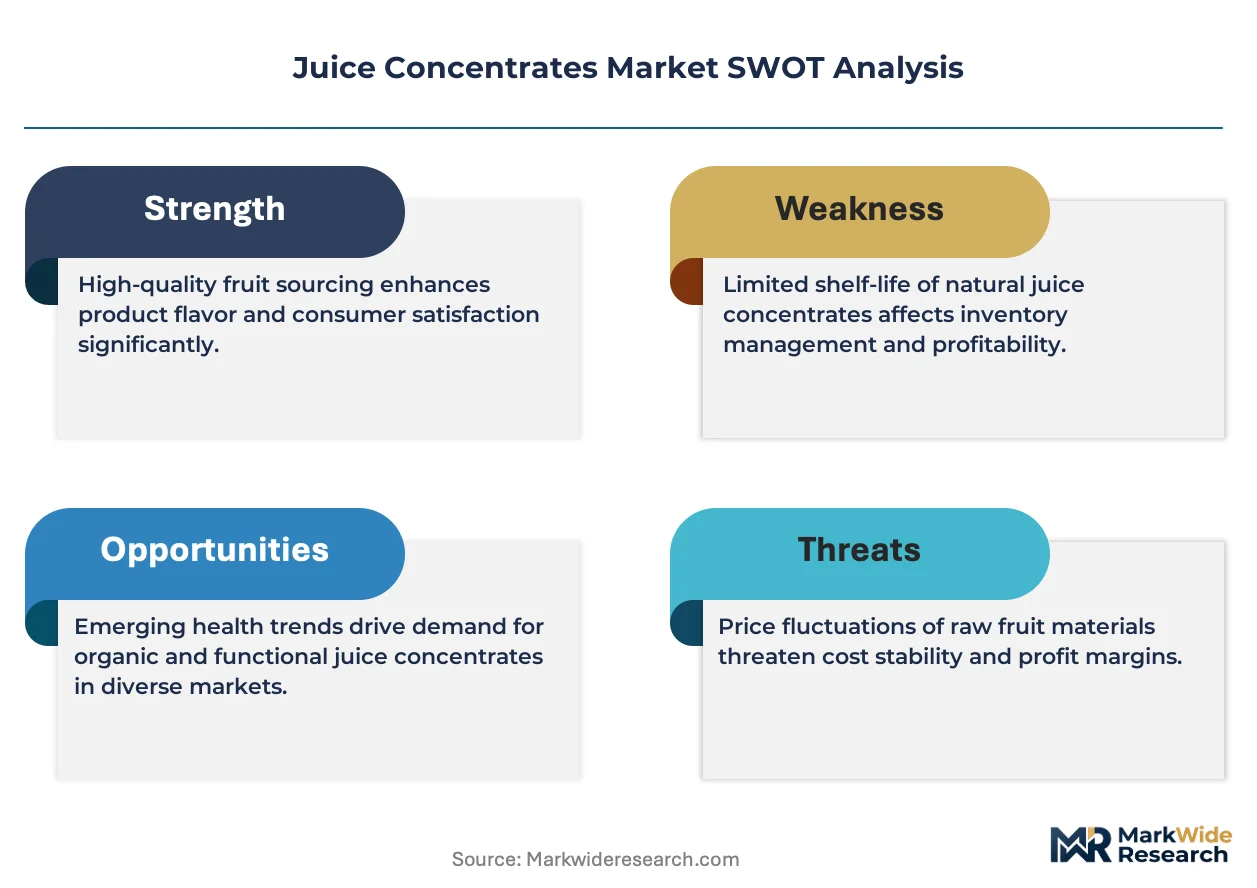
- Input Cost Volatility:Dependence on agricultural harvests makes concentrate pricing susceptible to weather-related crop failures and unpredictable yields for key fruits.
- Geographic Supply Concentration:Reliance on specific fruit-growing regions creates vulnerability to localized climate events, pests, and logistical disruptions affecting the supply chain.
- Threat from Lower-Cost Alternatives:High-fructose corn syrup and artificial flavors present a persistent, lower-cost substitution threat in price-sensitive beverage segments.
Strategic Opportunities
- Plant-Based Product Formulation:The plant-based food category requires natural sweeteners and flavors, creating a new application for concentrates in non-dairy yogurts and milks.
- Growth in Southeast Asian Markets:Rising incomes in countries like Vietnam and Indonesia create new demand for beverages and foods using fruit concentrates.
- Upcycled Ingredient Development:Processing surplus fruit into concentrates meets sustainability demands and creates a value stream from previously wasted agricultural output.
Industry Challenges
- Cold Chain Logistics Complexity:Ensuring the integrity of frozen and liquid concentrates requires significant investment and management of temperature-controlled logistics, especially across international supply routes.
- Certification and Traceability Demands:Meeting diverse customer requirements for certifications like organic or Fair Trade, and providing farm-to-factory traceability, adds significant operational complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juice Concentrates Market |
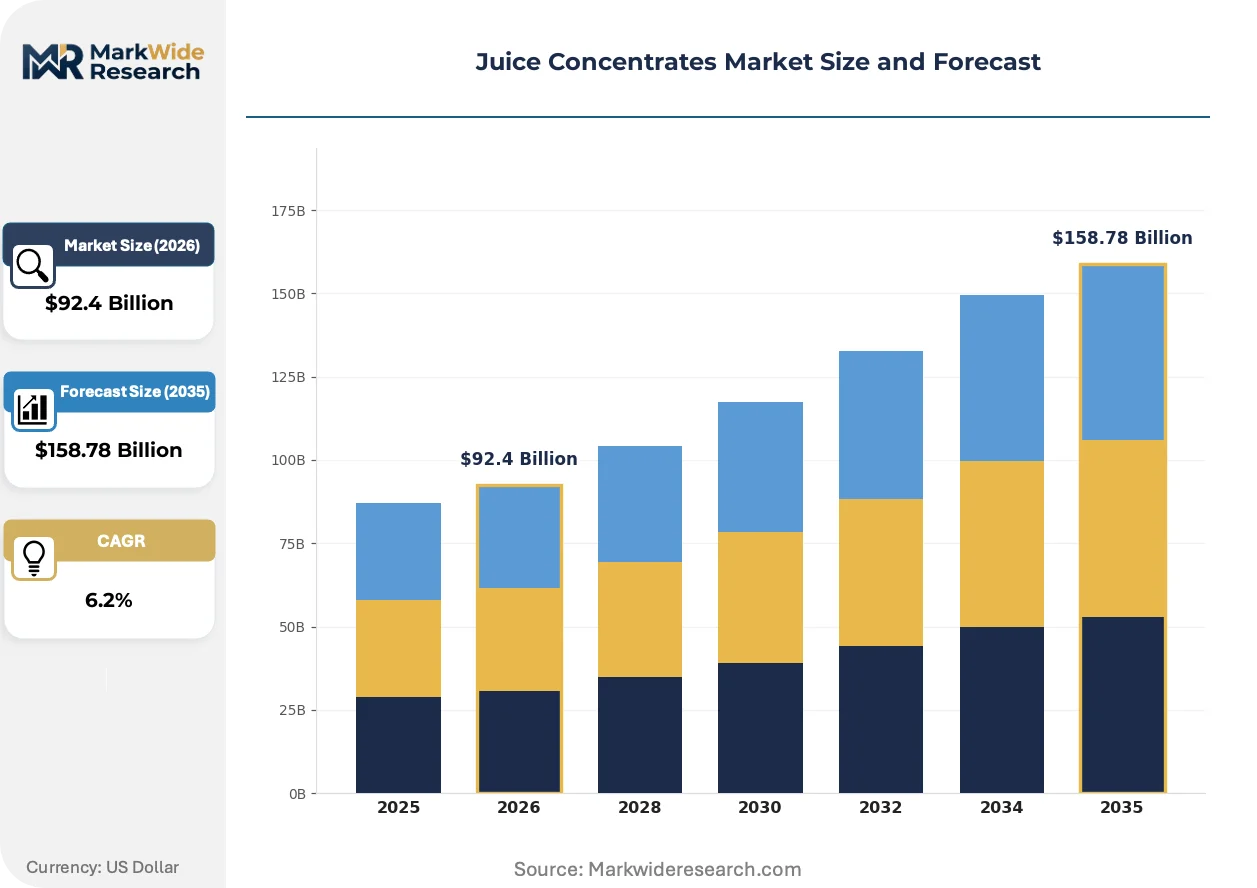
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $158.78 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange, Apple, Grape, Pineapple, Mango, Mixed Fruit Form: Frozen, Liquid, Powder, Syrup, Paste Application: Beverages, Bakery, Dairy Alternatives, Confectionery, Nutraceuticals Customer Type: Food & Beverage Manufacturers, Hospitality Chains, Catering Services, Retailers |
| Companies Covered | Kerry Group plc, Südzucker AG, Archer Daniels Midland Company, SVZ International B.V., SunOpta Inc., Döhler GmbH, Ingredion Incorporated, Symrise AG, AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juice Concentrates Market Strategic Shifts & Innovations
Technological advancements and sustainability mandates are converging to redefine processing efficiency and supply chain transparency. These forces are compelling producers to adopt innovative methods for quality assurance, waste reduction, and meeting stringent consumer expectations for ingredient provenance.
Blockchain technology is emerging as a critical tool for ensuring food safety and origin verification. Food and beverage manufacturers are piloting these systems to create immutable records of fruit sourcing, processing, and transportation. This adoption is digitizing the entire supply chain, providing verifiable proof of provenance and compliance with sustainability standards demanded by retailers and consumers.
The European Union’s Green Deal, particularly its Farm to Fork strategy, is setting new benchmarks for sustainable food production. This policy framework pressures suppliers to reduce pesticide usage and improve resource efficiency in fruit cultivation. Consequently, European concentrate processors are intensifying their focus on sourcing from certified sustainable farms and documenting their environmental footprint to maintain market access.
A notable demand-side shift involves manufacturers moving away from generic bulk purchasing toward sourcing application-specific concentrates. This trend disintermediates traditional commodity brokers in favor of direct partnerships with suppliers offering tailored solutions, such as specific Brix levels or unique flavor profiles. This strategic procurement is most prominent in the premium beverage and specialty bakery segments, where ingredient differentiation is a key competitive advantage.
Juice Concentrates Market Segmentation
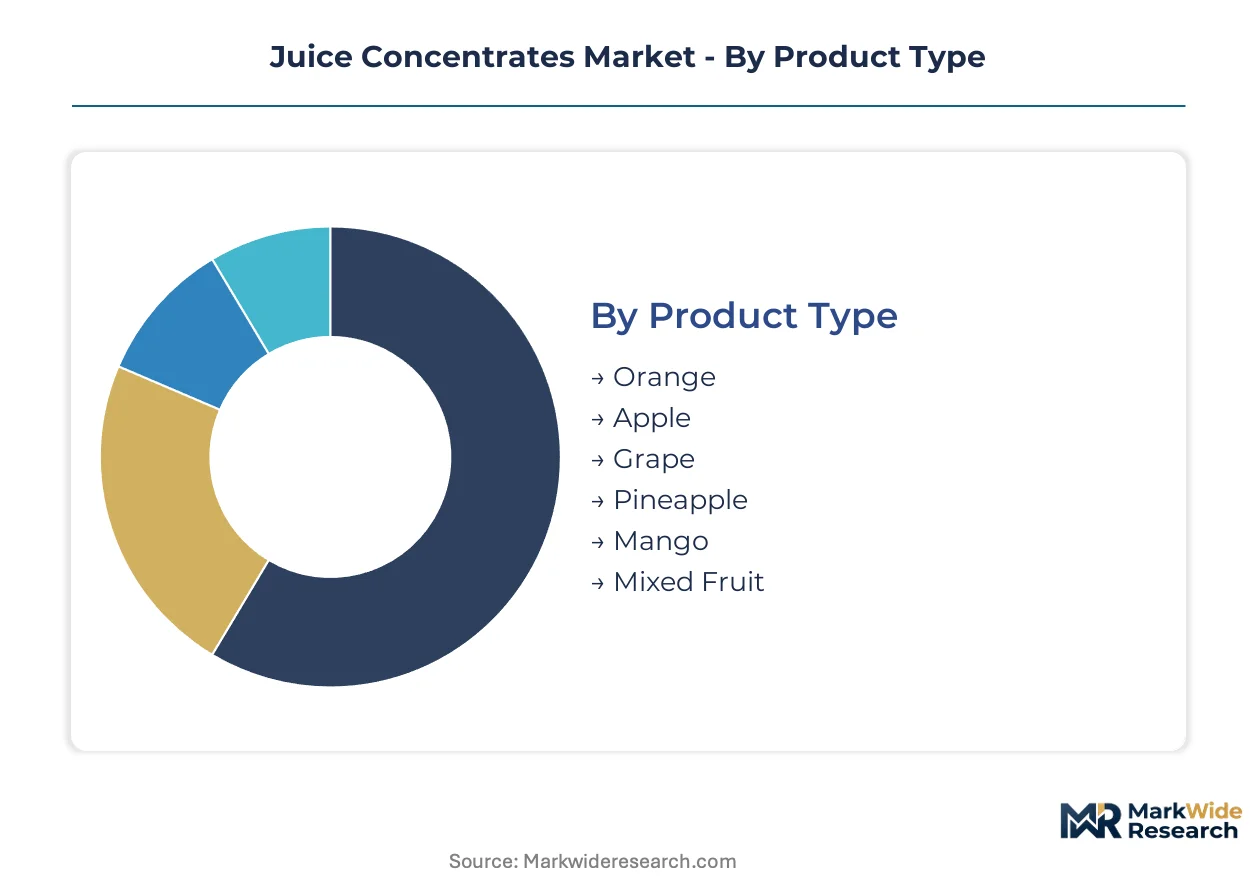
The Juice Concentrates Market exhibits diverse characteristics across various product types, forms, applications, and customer segments. Understanding these distinctions is crucial for manufacturers and suppliers to align product offerings with specific demand patterns and regulatory requirements across different end-use industries.
Product Type:
The diverse range of fruit varieties defines distinct market segments based on their intrinsic properties and processing requirements.
- Orange:Derived from sweet or sour oranges, these concentrates are standardized for Brix levels and acidity, primarily serving the global beverage industry for juice production and flavor enhancement. Demand remains high in North American and European markets for breakfast beverages.
- Apple:Produced from various apple cultivars, apple concentrates are valued for their natural sweetness and mild flavor profile, frequently used as a base in mixed fruit juices and as a natural sweetener in bakery products. The European Union sustains significant demand for its versatile applications.
- Grape:Grape concentrates provide rich color and tartness, making them suitable for juice blends and wine production.
- Pineapple:Known for its tropical flavor, pineapple concentrate sees application in exotic beverage formulations and dessert ingredients.
- Mango:Mango concentrates deliver intense flavor and aroma, popular in tropical juice drinks and confectioneries across Asian markets.
- Mixed Fruit:These concentrates combine several fruit juices, offering complex flavor profiles for multi-fruit beverages and food formulations.
Orange holds installed capacity. Mixed Fruit is rotating up the share rankings.
Form:
The physical state of juice concentrates dictates their storage, transportation, and application suitability for various industrial processes.
- Frozen:These concentrates maintain flavor integrity and nutritional value through low-temperature preservation, requiring a robust cold chain for distribution to food and beverage manufacturers. They are critical for seasonal fruit supply and long-distance transport.
- Liquid:Characterized by their ready-to-use nature and ease of blending, liquid concentrates are processed to specific Brix levels and pH, primarily utilized by beverage companies for direct reconstitution or as an ingredient in other liquid formulations. China's beverage production relies heavily on this form.
- Powder:Created through spray-drying or freeze-drying, powder concentrates offer extended shelf life and reduced shipping weight, gaining traction in nutraceutical supplements and instant beverage mixes.
- Syrup:Highly viscous and concentrated, syrup forms are often used as natural sweeteners or flavor bases in confectionery and dairy applications.
- Paste:Thick, semi-solid concentrates provide intense flavor and color, finding utility in bakery fillings and savory sauces.
Demand for Liquid remains strong in traditional beverage manufacturing, while Powder shows the steepest expansion trajectory in functional foods.
Application:
End-use sectors delineate specific requirements for juice concentrates, influencing product specifications and procurement volumes.
- Beverages:This segment represents the largest application for juice concentrates, ranging from 100% fruit juices to nectars, soft drinks, and flavored water, driven by consumer demand for natural ingredients. Manufacturers require consistent Brix levels and flavor profiles for large-scale production.
- Nutraceuticals:The nutraceutical industry increasingly uses vitamin-rich fruit concentrates as functional ingredients in dietary supplements, fortified foods, and health drinks, aligning with the clean-label consumer shift. Traceability and specific nutrient content are paramount for these products.
- Bakery:Concentrates provide natural sweetness, moisture, and fruit flavor to breads, pastries, and fillings for bakery producers.
- Dairy Alternatives:Plant-based yogurts and milks utilize fruit concentrates for flavor and natural sweetening, supporting the expansion of this category.
- Confectionery:Candies, jellies, and fruit snacks incorporate concentrates for authentic fruit taste and natural coloring.
The Beverages segment commands the largest share. Nutraceuticals is expanding most quickly.
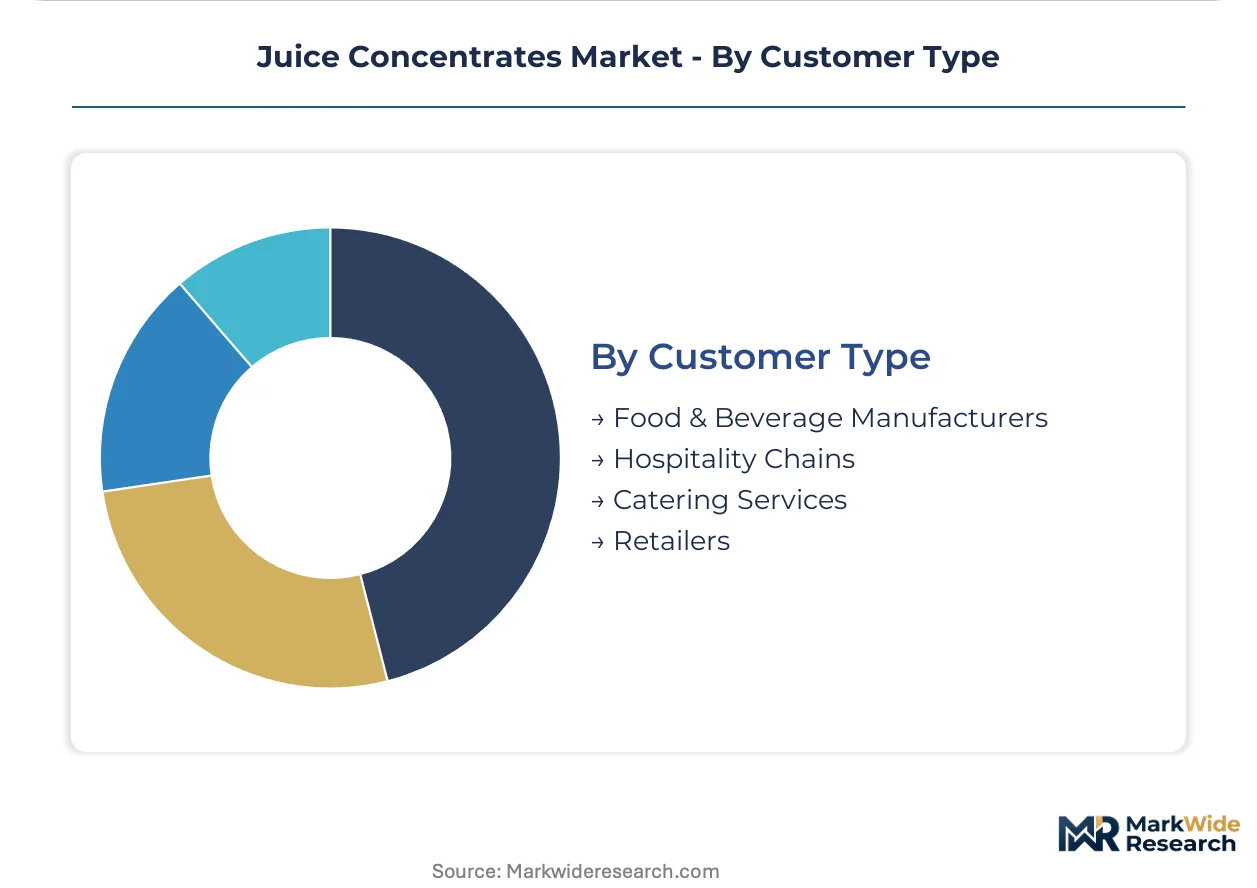
Customer Type:
The varied nature of procurement channels shapes the distribution strategies and service requirements for concentrate suppliers.
- Food & Beverage Manufacturers:These industrial clients purchase large volumes of concentrates for integration into their own branded products, requiring reliable supply chains, consistent quality, and adherence to stringent specifications. Long-term contracts and technical support are common.
- Retailers:Retailers procure concentrates for private label products or for sale as standalone ingredients to end consumers, emphasizing packaging, shelf stability, and marketing appeal. Clean-label certifications are important for consumer confidence.
- Hospitality Chains:Hotels, restaurants, and resorts use concentrates for beverages, desserts, and culinary preparations in their establishments.
- Catering Services:Event caterers and institutional food service providers utilize concentrates for efficiency and consistent flavor in large-scale meal production.
Food & Beverage Manufacturers represent the largest procurement volume. Hospitality Chains are demonstrating new procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pricing power asymmetry between major producing regions like Brazil and high-volume consuming markets such as China significantly influences global trade flows. This dynamic shapes procurement strategies and long-term supply agreements for key fruit varieties.
United States
United States consumers prioritize natural ingredients and functional foods, driving demand for fruit concentrates in beverages and supplements. The FDA mandates strict controls on pesticide residues and allergen labeling, influencing product formulations. Florida's extensive citrus processing infrastructure supports large-scale orange concentrate production.
China
China's robust beverage manufacturing sector demonstrates high procurement for quality fruit concentrates, particularly for premium juice blends. SAMR enforces stringent GB standards for food additives and ingredient traceability. Large-scale beverage producers in the Yangtze River Delta region drive significant demand for liquid concentrates.
Germany
German food manufacturers increasingly integrate fruit concentrates into bakery, confectionery, and dairy alternative products for natural sweetness. EFSA sets rigorous standards for contaminant levels, aligned with the EU Green Deal's sustainability goals. Bavaria's advanced food processing industry serves as a hub for concentrate utilization in diverse applications.
Brazil
Brazil stands as a dominant global supplier of orange juice concentrate, driven by its vast citrus production capabilities. ANVISA regulates food ingredient quality and export standards for fruit concentrates. The citrus belt within São Paulo state accounts for a substantial portion of the world's orange concentrate output.
India
India's expanding beverage market and food processing sector generate rising demand for fruit concentrates in juices and snacks. The FSSAI's labeling rules for fruit content in beverages directly influence concentrate usage by domestic manufacturers. Food processing zones in Maharashtra are becoming significant consumption centers for both imported and domestically produced concentrates.
Juice Concentrates Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the juice concentrates market. This tiered structure features global commodity traders operating at scale alongside specialized ingredient solution providers. Strategic archetypes include large-scale fruit processors, diversified food ingredient companies, and regional concentrate suppliers. Competitive moves frequently involve mergers and acquisitions to consolidate processing capacity, alongside portfolio diversification into value-added ingredients and geographic expansion to secure raw material sources.
Within the integrated solutions tier, Archer Daniels Midland Company exemplifies global sourcing capabilities, leveraging its extensive network to manage input cost volatility. Südzucker AG, a German public company, occupies a position anchored by its large-scale production capacities in key fruit-growing regions. Döhler GmbH, also a German-based entity, represents a focus on integrated natural ingredients and application-specific solutions for the beverage industry. These companies collectively demonstrate the market's emphasis on supply chain control, consistent quality, and tailored product offerings to meet diverse customer requirements.
| Leading Market Players |
|---|
| Kerry Group plc |
| Südzucker AG |
| Archer Daniels Midland Company |
| SVZ International B.V. |
| SunOpta Inc. |
| Döhler GmbH |
| Ingredion Incorporated |
| Symrise AG |
| AGRANA Beteiligungs-AG |
| Others |
Cost & Logistics Intelligence
Brazil's dominance in orange concentrate production influences global beverage manufacturer margins, particularly in North American and European markets. Input cost volatility from agricultural harvests significantly impacts pricing for fruit concentrates across the entire supply chain.
Pricing Analysis
Configured-to-order pricing for application-specific concentrates commands a premium over standard commodity spot pricing. The dominant pricing structure involves long-term contract-based offtake agreements, supplemented by transactional spot purchases. Price differentiation stems from quality grade and customization level, such as specific Brix levels or unique flavor profiles. Pricing softness reflects input cost volatility caused by weather-related crop failures. Price-sensitive beverage segments often consider lower-cost alternatives like high-fructose corn syrup, while premium beverage and nutraceutical manufacturers exhibit lower price sensitivity.
Supply Chain Analysis
Global commodity traders and specialized ingredient solution providers hold significant capacity in the juice concentrates market. Geographic supply concentration in Brazil for orange concentrates and Europe for apple concentrates creates a structural vulnerability. Raw material dependencies center on specific fruit harvests like citrus, apples, and grapes. Geographic supply concentration creates vulnerability to localized climate events, pests, and logistical disruptions. Distribution runs through a network of global traders and direct supplier-to-manufacturer partnerships, especially for tailored solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The juice concentrates market is experiencing a platform-economics inflection, driven by digital supply chain integration and traceability solutions like blockchain technology. This shift fosters greater interoperability between producers and end-use manufacturers.
For Market Incumbents:Pre-empt input cost volatility by deepening vertical integration into key fruit-growing regions. Secure long-term supply agreements with certified sustainable farms to mitigate regulatory shifts like the EU Green Deal. Diversify product portfolios with application-specific concentrates to counter the threat from lower-cost alternatives. Invest in advanced processing technologies to enhance quality and traceability across the supply chain.
For New Entrants and Emerging Players:Establish a beachhead in the nutraceuticals segment by offering highly traceable, functional fruit powders. Target Southeast Asian markets with tailored product formulations addressing local flavor preferences. Develop innovative upcycled ingredient solutions to meet sustainability demands and create new value streams. A direct-to-manufacturer sales model focusing on technical support can differentiate offerings.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with regional fruit processors lacking scale or advanced technology. Long-term viability hinges on consolidation of processing capacity and integration of digital traceability platforms. Target ingredient solution providers with strong R&D capabilities in natural sweeteners and functional food additives. The signal to watch is the increasing adoption of blockchain for origin verification by major food and beverage manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Sourcing Certification | Ensures compliance with clean-label demands and regulatory frameworks like the EU Green Deal. |
| Blockchain Integration | Provides immutable records for fruit sourcing and processing, enhancing transparency for food manufacturers. |
| Application-Specific R&D | Develops tailored concentrates for premium beverage and specialty bakery segments, driving differentiation. |
| Capacity Expansion in Emerging Markets | Captures new demand from rising incomes in Southeast Asian countries like Vietnam. |
| Upcycled Ingredient Development | Transforms agricultural waste into value-added concentrates, meeting sustainability goals. |
Research Approach
The analysis maps fruit concentrate types, forms, and applications, each validated through primary interviews with procurement managers, R&D directors, and supply chain logistics leads. Secondary research leveraged food industry reports, regulatory filings from the FDA and EFSA, and trade association publications. This approach triangulated quantitative market data with qualitative insights from industry experts. Both bottom-up sizing and top-down validation ensured comprehensive market coverage.
Assumptions regarding consumer preference shifts towards clean-label products were held fixed, while input cost volatility from agricultural yields varied across the analysis window. The analytical framework modeled growth across product type, form, application, and customer type segments, alongside regional consumption patterns. CAGRs were derived from historical data trends and projected future demand. Key forecast inputs included projected growth in the nutraceutical sector and evolving food labeling mandates.
Stress conditions across extreme weather events and major trade policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding stable regulatory environments and consistent consumer health trends. Quarterly review of agricultural commodity prices and new food labeling regulations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Ready to Drink Shakes Market
Beverages
Botanical Infused Beverages Market
Beverages
United Kingdom Energy Drink Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Breakfast Drink Market
Beverages
Blenders Market
Beverages
Fiber Fortified Beverages Market
Beverages
Canned Beverages Market
Beverages
Global Electrolyte Drinks Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
GCC Coconut Water Market
Beverages
Fruit Vinegar Market
Beverages
Detox Drinks Market
Beverages
Asia-Pacific Energy Bar Market