
 Extra Neutral Alcohol (ENA) Market | 2026-2036
Extra Neutral Alcohol (ENA) Market Size, Share, and Industry Trends Forecast 2026-2036
Extra Neutral Alcohol (ENA) Market Foresight
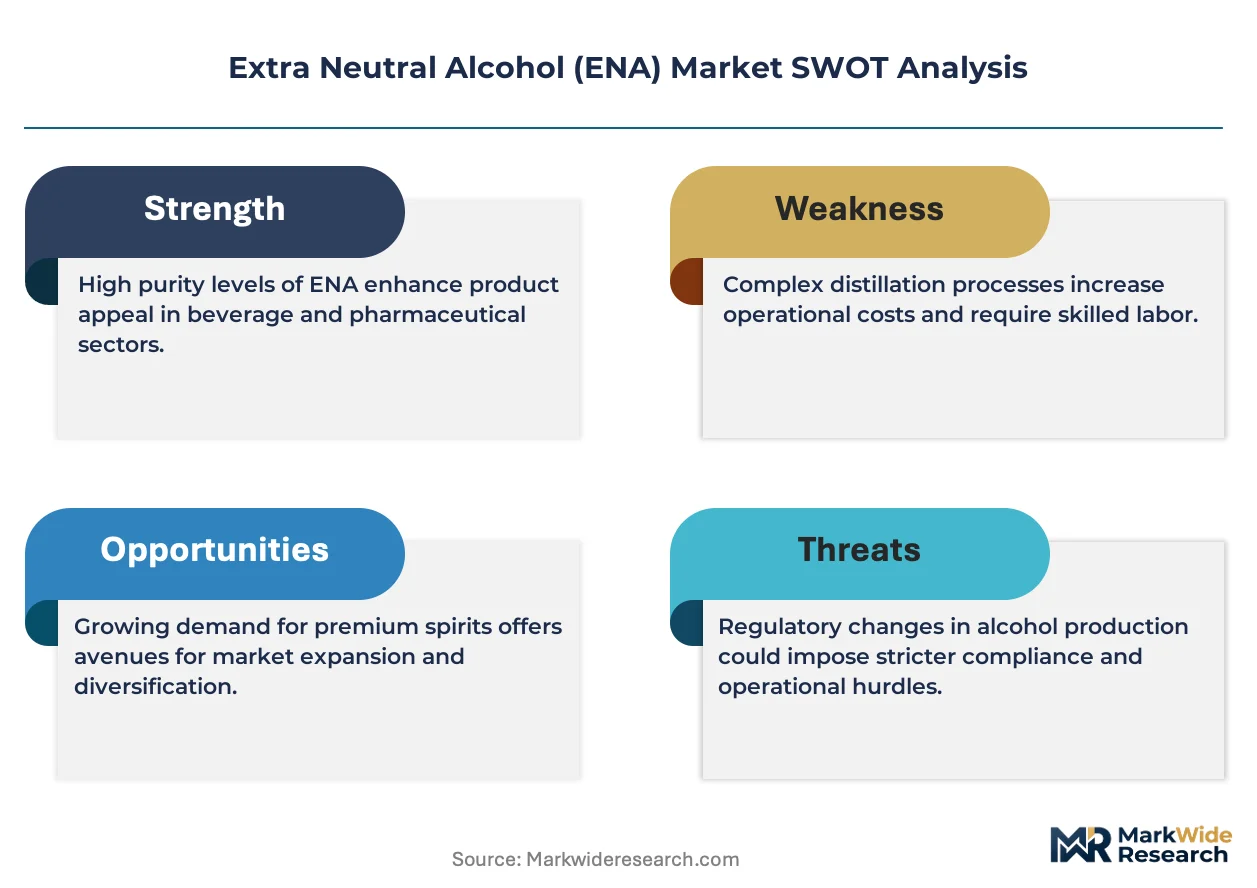
Modular tanker-to-tote packaging is restructuring how distilleries and blenders manage inventory cycles and cash flow. Radico Khaitan Limited leverages captive molasses supply chains to sustain margin stability across volatile harvest seasons. Sasol Solvents (Pty) Ltd anchors southern African distribution through dedicated bulk terminal access. Illovo Sugar Limited competes on integrated sugar-to-ethanol conversion economics that few standalone distillers replicate.
Extra Neutral Alcohol denotes a highly purified ethyl alcohol containing minimal congeners, typically distilled to exceed 96% ethanol by volume and filtered through activated carbon to achieve neutral odor and taste profiles. Manufacturers deploy multi-column continuous distillation followed by demineralization to meet pharmaceutical and beverage-grade specifications. Grain Neutral Spirits dominates volume throughput in North American and European supply chains where corn and wheat feedstocks prevail. Pharmaceutical application commands premium pricing due to USP and EP compliance burdens that sugarcane-derived ENA rarely satisfies without secondary processing. Sugarcane ENA occupies cost-sensitive beverage markets across tropical belt economies where cane crushing integrates directly with distillery operations.
FDA, EMA, and BIS frameworks govern permissible impurity thresholds, labeling protocols, and excise tax classifications that determine market access eligibility. REACH and F-Gas Regulation in Europe plus India's CEA labeling mandates are tightening traceability requirements from feedstock origin to finished batch certification. Stakeholders must monitor evolving biofuel quota policies that divert fermentation capacity away from neutral alcohol production during peak energy-crop pricing cycles.
Market Dynamics
Multi-column continuous distillation is compressing production cycles while FDA and EMA purity standards are tightening feedstock qualification requirements, forcing distillers to requalify supplier networks.
Growth Catalysts
- Pharmaceutical-grade demand:USP and EP compliance requirements in pharmaceutical formulations are pulling premium-grade ENA volumes away from beverage applications.
- REACH traceability mandates:European chemical registration protocols are accelerating certified supply chain investments among export-oriented distillers.
- Sugarcane integration:Tropical belt economies with captive cane crushing operations are achieving cost structures that grain-based competitors cannot replicate.
Market Restraints
- Molasses price volatility:Monsoon-dependent harvests in India and Brazil create input cost swings that destabilize margin planning for non-integrated producers.
- Pharmaceutical certification barriers:Secondary processing requirements to meet USP standards exclude sugarcane-derived ENA from premium segments without substantial capital investment.
- Biofuel quota diversion:Peak energy-crop pricing cycles pull fermentation capacity away from neutral alcohol production toward ethanol blending mandates.
Strategic Opportunities
- Modular packaging systems:Tanker-to-tote distribution models are opening inventory-light procurement channels for mid-sized beverage blenders.
- Indian pharmaceutical cluster expansion:CDSCO regulatory alignment with ICH standards is positioning domestic distillers for API solvent contract manufacturing.
- Activated carbon filtration advances:Converging membrane and adsorption technologies are reducing demineralization energy intensity for grain neutral spirits producers.
Industry Challenges
- Multi-standard compliance engineering:Simultaneous FDA, EMA, and BIS certification requirements demand dedicated quality teams that smaller distillers struggle to staff.
- Legacy column retrofitting:Continuous distillation upgrades require extended shutdown windows that disrupt contract fulfillment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extra Neutral Alcohol (ENA) Market |
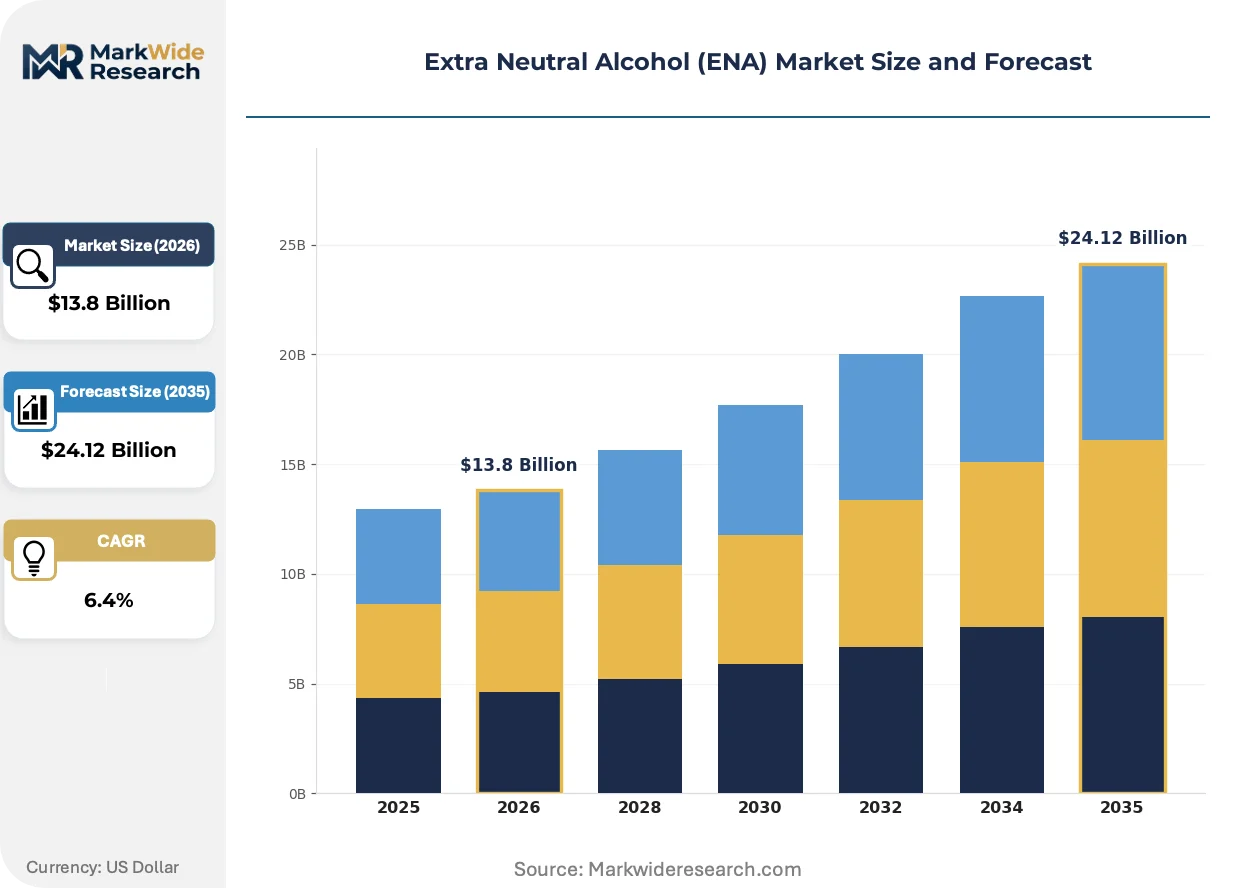
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grain Neutral Spirits, Sugarcane, Malt, Others Application: Beverage, Pharmaceutical, Personal Care, Food Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Industrial, Commercial, Household, Laboratories |
| Companies Covered | Illovo Sugar Limited, Radico Khaitan Limited, Agro Chemical and Food Company Limited, USA Distillers LLC, Sasol Solvents (Pty) Ltd, BCL Industries Ltd, NCP Alcohols (Pty) Ltd, Swift Chemicals Ltd, Enterprise Ethanol (Pty) Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extra Neutral Alcohol (ENA) Market Shifts & Advancements
Process intensification and regulatory digitization are compressing batch certification timelines while reshaping how distillers qualify and retain pharmaceutical contracts.
Membrane-assisted distillation is unifying dehydration and impurity removal stages into single-unit operations. Pharmaceutical manufacturers in Germany and Switzerland are adopting these systems to reduce energy costs per hectoliter. The technology is unifying process economics for mid-scale distillers previously locked out of premium certification tiers.
EMA's F-Gas Regulation and associated refrigerant phase-down mandates are forcing cooling system retrofits across European distillation facilities. Distillers face capital allocation decisions between compliance upgrades and capacity expansion. Sugarcane-based producers in Spain and Portugal are most affected due to energy-intensive multiple-effect evaporation requirements.
Bulk procurement consolidation among multinational pharmaceutical formulators is compressing supplier qualification cycles. Long-term supply agreements with embedded price adjustment clauses are displacing spot market transactions. This concentration is most visible in the Rhine-Ruhr and Basel pharmaceutical manufacturing corridors where three buyers account for majority ENA offtake.
Extra Neutral Alcohol (ENA) Market Segmentation
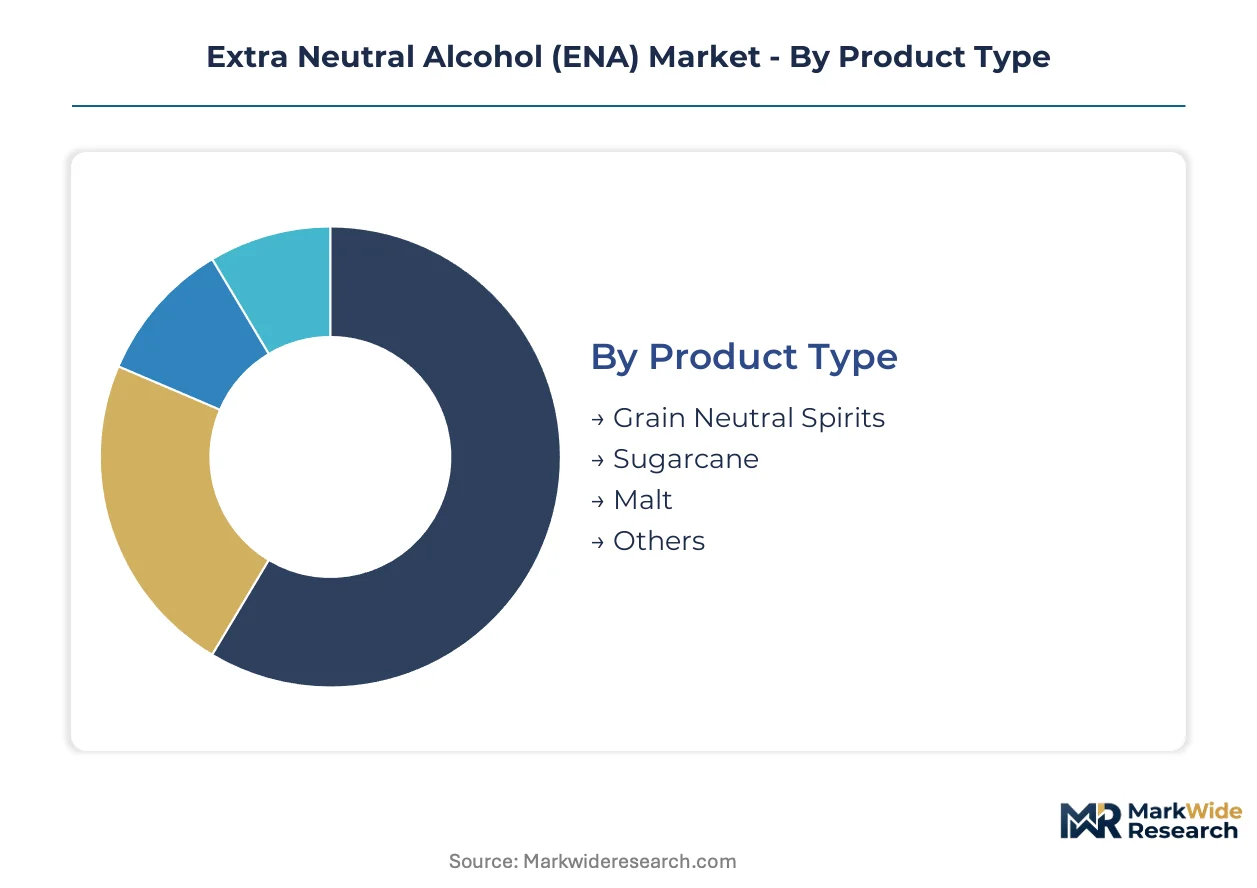
ENA procurement patterns diverge sharply between bulk pharmaceutical contracts and spot beverage purchases, with certification requirements dictating supplier eligibility across each segment. Distillers structure production campaigns around these demand profiles, optimizing feedstock selection and distillation intensity to match end-use specifications.
Product Type:
Customization intensity varies from standardized commodity grades to specification-locked pharmaceutical feedstocks, with feedstock chemistry determining downstream processing burden.
- Grain Neutral Spirits:Corn and wheat-derived ethanol dominates North American and European supply chains where starch conversion yields consistent fermentation economics. Pharmaceutical manufacturers in Germany and Switzerland specify grain-origin ENA for USP compliance due to lower congener baselines.
- Sugarcane:Molasses and cane juice fermentation delivers cost structures that tropical belt producers cannot match through grain alternatives. Indian and Brazilian integrated sugar-ethanol operations leverage captive crushing capacity to undercut standalone distillers during harvest peaks.
- Malt:Barley-based distillation preserves trace flavor congeners prized in premium beverage applications requiring subtle organoleptic character.
- Others:Cellulosic and synthetic ethanol sources occupy niche positions where regulatory arbitrage or carbon accounting creates temporary price advantages.
Leading the category by volume: Grain Neutral Spirits. Growing fastest: Sugarcane.
Application:
Margin architecture separates pharmaceutical solvent contracts from commodity beverage blending, with certification tier determining pricing power.
- Beverage:Potable alcohol applications span vodka, gin, and ready-to-drink formulations where neutral taste profiles allow flavor system dominance. Brazilian cachaça and Indian IMFL producers drive bulk procurement through integrated distillery networks.
- Pharmaceutical:USP and EP compliance requirements impose activated carbon filtration and demineralization steps that multiply production costs. CDSCO-aligned Indian distillers are capturing API solvent contracts as ICH regulatory convergence accelerates.
- Personal Care:Cosmetic-grade ENA serves fragrance dilution and preservative functions where residual odor thresholds exceed pharmaceutical stringency.
- Food:Extract solvent and flavor carrier applications in vanilla and citrus processing demand food-grade certification without pharmaceutical documentation burdens.
Pharmaceutical commands the steepest expansion trajectory. Beverage retains the largest volume position.
Distribution Channel:
Channel selection tracks buyer scale and inventory carrying capacity, with large formulators bypassing intermediaries entirely.
- Retail:Packaged ENA in denatured or duty-paid formats serves small-scale beverage producers and laboratory end users requiring sub-pallet quantities.
- Wholesale:Regional distributors aggregate tanker volumes for fractional resale to mid-sized blenders lacking direct terminal access.
- E-commerce:Specialty chemical platforms are emerging for certified pharmaceutical-grade procurement where documentation chains require digital traceability.
- Direct Sales:Multinational pharmaceutical formulators in the Rhine-Ruhr and Basel corridors negotiate long-term supply agreements with embedded price adjustment clauses.
Direct Sales dominates pharmaceutical offtake. Wholesale retains beverage market penetration.
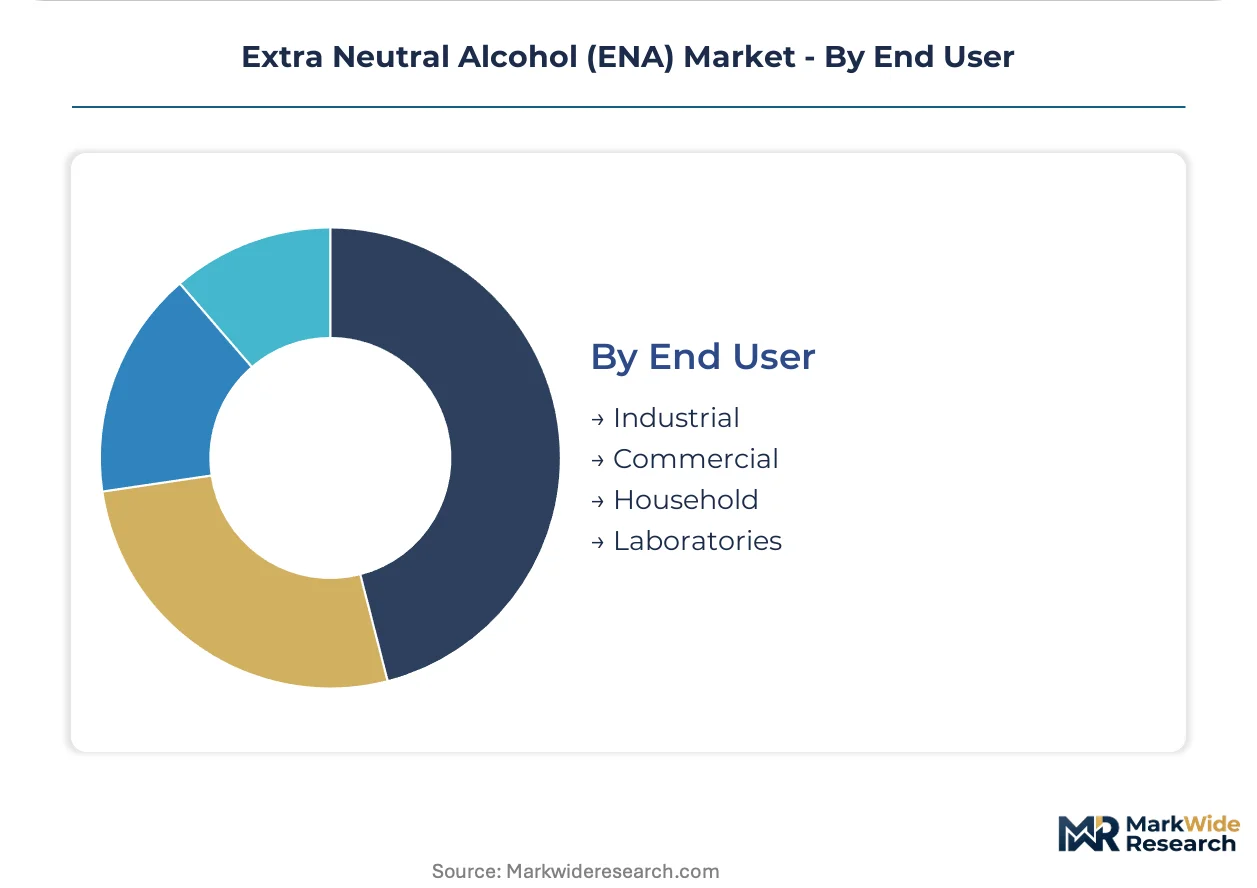
End User:
User sophistication determines specification negotiation intensity, with industrial buyers driving standardization and laboratories demanding batch-level documentation.
- Industrial:Large-scale beverage and pharmaceutical manufacturers specify continuous supply contracts with quality audit rights.
- Commercial:Mid-sized blenders and contract manufacturers balance spot purchasing flexibility against inventory cost minimization.
- Household:Denatured alcohol for cleaning and solvent applications represents price-sensitive demand with minimal specification requirements.
- Laboratories:Analytical and research institutions require ACS or reagent-grade certification with full batch traceability documentation.
Industrial users absorb the majority of volume. Laboratories exhibit the most rapid specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Brazil dominate ENA production through integrated sugar-ethanol operations, while pharmaceutical demand concentrates in Germany and Switzerland where USP-grade specifications prevail. The United States maintains substantial grain-based distillation capacity serving beverage and industrial solvent markets.
India
Molasses-based ENA production surges during October-March crushing seasons, with distillers in Uttar Pradesh and Maharashtra supplying bulk volumes to IMFL manufacturers. CDSCO alignment with ICH standards is opening API solvent contract opportunities for domestic producers. The Baddi-Barotiwala-Nalagarh pharmaceutical cluster in Himachal Pradesh is absorbing increasing certified ENA volumes for export-oriented formulation work.
Brazil
Integrated sugar-ethanol mills in São Paulo state leverage flexible fermentation capacity between anhydrous fuel ethanol and neutral alcohol production. ANVISA pharmaceutical-grade certification requirements are tightening traceability documentation for exporters. The São Paulo-Ribeirão Preto corridor hosts the densest concentration of distilleries serving both beverage and industrial chemical markets.
Germany
Grain neutral spirits producers in Bavaria and North Rhine-Westphalia command premium pricing through USP and EP compliance for pharmaceutical solvent contracts. EMA's F-Gas Regulation is forcing cooling system retrofits across distillation facilities, compressing operating margins. The Rhine-Ruhr pharmaceutical manufacturing corridor concentrates ENA offtake among three multinational formulators negotiating long-term supply agreements.
United States
Corn-based ethanol infrastructure in Iowa and Illinois supports substantial grain neutral spirits output for vodka and gin producers. FDA pharmaceutical-grade specifications limit sugarcane-derived ENA market access without secondary processing investments. The Kentucky-Tennessee beverage distillation belt sources neutral spirits from Midwest grain processors for blending operations.
South Africa
Sugarcane ENA from KwaZulu-Natal operations serves regional beverage markets and personal care manufacturing. Sasol Solvents anchors southern African distribution through dedicated bulk terminal access at Durban harbor. The country's pharmaceutical regulator maintains alignment with WHO prequalification standards for export-oriented solvent production.
Extra Neutral Alcohol (ENA) Market Competitive Landscape
The competitive structure tilts toward integrated agro-industrial conglomerates with captive feedstock supply. Distillers without upstream sugar or grain operations face persistent margin compression during commodity price spikes. Three archetypes dominate: integrated sugar-ethanol processors, standalone grain distillers with pharmaceutical certification, and diversified chemical solvents divisions of energy majors. Capacity expansion and backward integration into molasses or grain procurement represent the primary competitive vectors.
Among integrated sugar-ethanol processors, Illovo Sugar Limited and Radico Khaitan Limited exemplify the captive feedstock model that sustains margin stability across volatile harvest cycles. Sasol Solvents (Pty) Ltd occupies a position within the diversified energy-chemicals archetype, leveraging existing hydrocarbon infrastructure for distribution scale. These three entities represent distinct strategic approaches to securing regional market position without reliance on spot feedstock procurement.
| Leading Market Players |
|---|
| Illovo Sugar Limited |
| Radico Khaitan Limited |
| Agro Chemical and Food Company Limited |
| USA Distillers LLC |
| Sasol Solvents (Pty) Ltd |
| BCL Industries Ltd |
| NCP Alcohols (Pty) Ltd |
| Swift Chemicals Ltd |
| Enterprise Ethanol (Pty) Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between pharmaceutical USP/EP tiers and beverage-grade commodity ENA manifests in parallel supply chain configurations. Premium pharmaceutical contracts anchor long-term offtake agreements with embedded price adjustment clauses, while tropical belt beverage producers trade spot-indexed molasses supply against volatile harvest cycles.
Pricing Analysis
Cost-down pressure on commodity sugarcane ENA accelerates because Brazilian and Indian integrated mills flex fermentation capacity toward fuel ethanol during peak energy-crop pricing. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates USP-certified grain neutral spirits from molasses-derived beverage alcohol. Price differentiation hinges on activated carbon filtration intensity and demineralization energy inputs. Pharmaceutical formulators in the Rhine-Ruhr corridor exhibit lowest price sensitivity, while regional IMFL blenders in Uttar Pradesh face acute margin compression during monsoon-deficit years.
Supply Chain Analysis
Single-source vulnerability sits with Indian molasses supply during October-March crushing seasons, when Uttar Pradesh and Maharashtra distillers command global export pricing. Feedstock sourcing draws from Brazilian sugar-ethanol mills, Indian integrated crushing operations, and North American corn processors. Supply chain risk centers on monsoon-dependent harvest volatility that destabilizes input cost planning. Distribution runs through dedicated bulk terminals at Durban, Mumbai, and Rotterdam, with modular tanker-to-tote systems penetrating mid-sized beverage blender procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity constraints in tropical belt economies prop pricing across pharmaceutical and beverage segments. Distillers without captive molasses or grain supply face persistent margin compression.
For Market Incumbents: Deepen backward integration into cane crushing or grain procurement to insulate margin stability from harvest volatility. Defend pharmaceutical contract positions through CDSCO alignment investments that preempt API solvent qualification. Anchor long-term supply agreements with embedded price adjustment clauses to lock Basel and Rhine-Ruhr formulator relationships. For New Entrants and Emerging Players: Begin with modular packaging system deployment targeting mid-sized beverage blenders lacking direct terminal access. White-space opportunity concentrates in Indian pharmaceutical cluster expansion around Baddi-Barotiwala-Nalagarh, where CDSCO-ICH convergence accelerates API solvent demand. Pursue e-commerce channel certification for laboratory-grade procurement with digital traceability documentation. For Investors and Strategic Acquirers: Re-rating potential sits with integrated sugar-ethanol processors given biofuel quota diversion risk and pharmaceutical certification barriers. Long-term viability favors captive feedstock models over standalone distillers exposed to spot molasses markets. Monitor ANVISA and EMA traceability mandate tightening as inflection signals for certified supply chain investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive crushing capacity in Uttar Pradesh and São Paulo insulates margin volatility from monsoon cycles. |
| Pharmaceutical Certification Investment | USP and EP compliance opens API solvent contracts with Basel and Rhine-Ruhr formulators. |
| Modular Packaging System Deployment | Tanker-to-tote distribution reduces inventory carrying costs for mid-sized beverage blenders. |
| Membrane-Assisted Distillation Upgrade | Process intensification cuts demineralization energy intensity for grain neutral spirits producers. |
| Long-Term Supply Agreement Structuring | Embedded price adjustment clauses displace spot market exposure in pharmaceutical offtake. |
Research Methodology
Trade statistics from UN Comtrade, customs filings from India DGFT and Brazil SECEX, and pharmaceutical regulatory databases formed the secondary backbone. Primary interviews with distillery operations managers, pharmaceutical procurement leads at multinational formulators, molasses brokers, and CDSCO regulatory consultants combined with secondary validation. Bottom-up capacity modeling and top-down demand triangulation anchored segmentation outputs.
Historical trendline analysis across production volumes, trade flows, and pricing indices established baseline trajectories. Segmentation dimensions modeled include feedstock type, certification grade tier, end-use application, and regional production hub clustering. CAGRs derived from least-squares fitting of normalized growth rates against capacity expansion announcements and regulatory alignment timelines. Forecast inputs incorporated biofuel quota policy shifts and EMA F-Gas Regulation compliance cost burdens.
Underlying measurement precision varies by segment; pharmaceutical-grade volume carries tighter precision than commodity beverage estimates due to contract disclosure requirements. Forecasts reflect documented assumptions on regulatory convergence speed and harvest cycle normalization. Specific risk factors include monsoon pattern disruption, biofuel mandate expansion, and cooling system retrofit delays under EMA refrigerant phase-downs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Semillon Market
Beverages
Hot Chocolate Market
Beverages
Electrolyte Mixes Market
Beverages
Hot Cocoa Mix Market
Beverages
Bottled Air Market
Beverages
Nitro-Infused Cola Market
Beverages
North America Cold Pressed Juices Market
Beverages
Foaming Creamer Market
Beverages
Germany Probiotic Drinks Market
Beverages
Maple Water Market
Beverages
Chocolate Malt Drink Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Ready to Drink Shakes Market
Beverages
Ginger Beer Market
Beverages
GCC Coconut Water Market
Beverages
United States Sports and Energy Drinks Market