
 Japan Energy Drink Market | 2026-2036
Japan Energy Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Energy Drink Market Outlook
Office worker consumption is decoupling from the athletic core that historically defined Japan's energy drink category. Taisho Pharmaceutical Holdings leverages its Lipovitan D heritage to anchor the medicinal-tonic segment against Western-style entrants. Suntory Beverage & Food Ltd. competes through convenience store shelf dominance and localized flavor development. Monster Energy differentiates via gaming and extreme sports sponsorships that resonate with younger demographics.
An energy drink is a caffeinated functional beverage typically containing mg-level caffeine doses, B-vitamin complexes, taurine, and amino acids, formulated for mental alertness and physical stamina enhancement through carbonated or still liquid delivery. Sugar-Free formulations now lead volume growth as METI-backed health consciousness reshapes purchasing patterns across convenience stores and online retail channels. The Gamer target audience segment shows the fastest trajectory, while Working Professionals retains the deepest margin pool due to premium pricing tolerance and repeat purchase frequency.
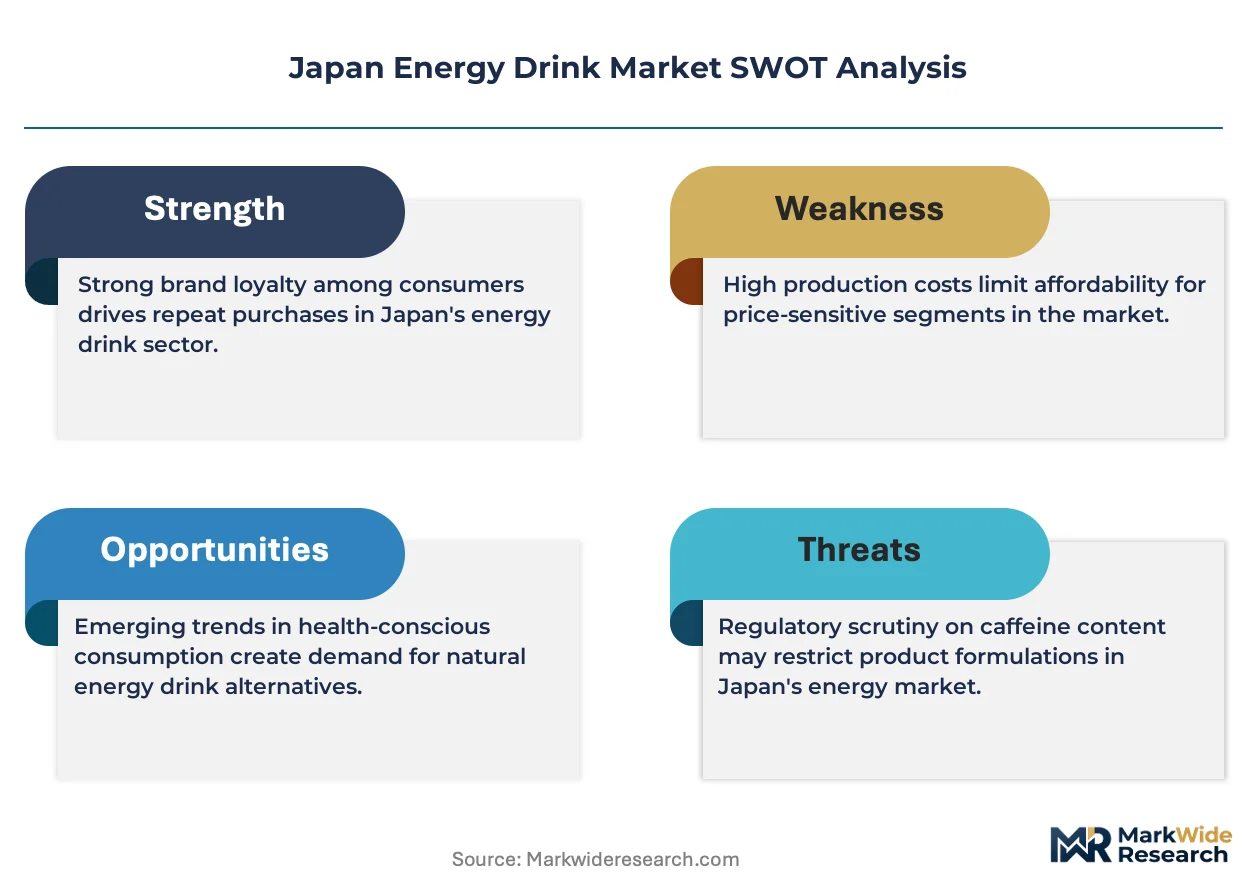
PMDA oversight of quasi-drug classifications and METI's Foods with Function Claims framework jointly determine which ingredients and efficacy statements reach Japanese consumers. JIS standards for food manufacturing and labeling compliance create baseline operational requirements that favor established domestic producers with integrated quality systems. Stakeholders must monitor whether METI expands caffeine concentration disclosure mandates and how PMDA reclassifies borderline functional ingredients.
Market Dynamics
Working professionals in Greater Tokyo's commuter corridors now outpace athletic users as the primary consumption engine, forcing reformulations away from sports-centric positioning toward sustained mental alertness and portable convenience formats.
Growth Catalysts
- METI's Foods with Function Claims framework:Legitimizes specific efficacy statements for caffeine and amino acid combinations, accelerating premium product launches with substantiated health positioning.
- Gaming district clusters in Osaka:Concentrated demand from esports participants and streaming culture creates localized volume spikes that justify dedicated distribution and flavor variants.
- Sugar-free formulation technology:Advances in non-nutritive sweetener masking enable palatable zero-calorie variants that align with health-conscious office worker preferences.
Market Restraints
- PMDA quasi-drug classification ambiguity:Borderline functional ingredients face unpredictable reclassification timelines that freeze product pipeline investments.
- Convenience store shelf concentration:Three retail chains control over seventy percent of impulse purchase points, extracting listing fees that compress margins for new entrants.
- Taurine import dependency:Domestic production capacity remains insufficient, exposing cost structures to petrochemical feedstock volatility and currency fluctuation.
Strategic Opportunities
- Fukuoka's emerging tech workforce:Underpenetrated relative to Tokyo and Osaka, this southern hub offers first-mover advantage among software developers and startup employees.
- Subscription direct-to-home channels:Bypassing convenience store gatekeepers enables margin recovery and personalized formulation based on consumption pattern data.
- Functional ingredient stacking:Converging nootropics with traditional energy bases addresses the productivity optimization demand from knowledge workers seeking cognitive enhancement.
Industry Challenges
- Flavor chemist talent scarcity:Formulating palatable sugar-free variants with complex active ingredient loads requires specialized expertise concentrated among a handful of domestic suppliers.
- JIS certification timeline compression:Accelerated product cycles strain quality system documentation, creating compliance bottlenecks that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Energy Drink Market |
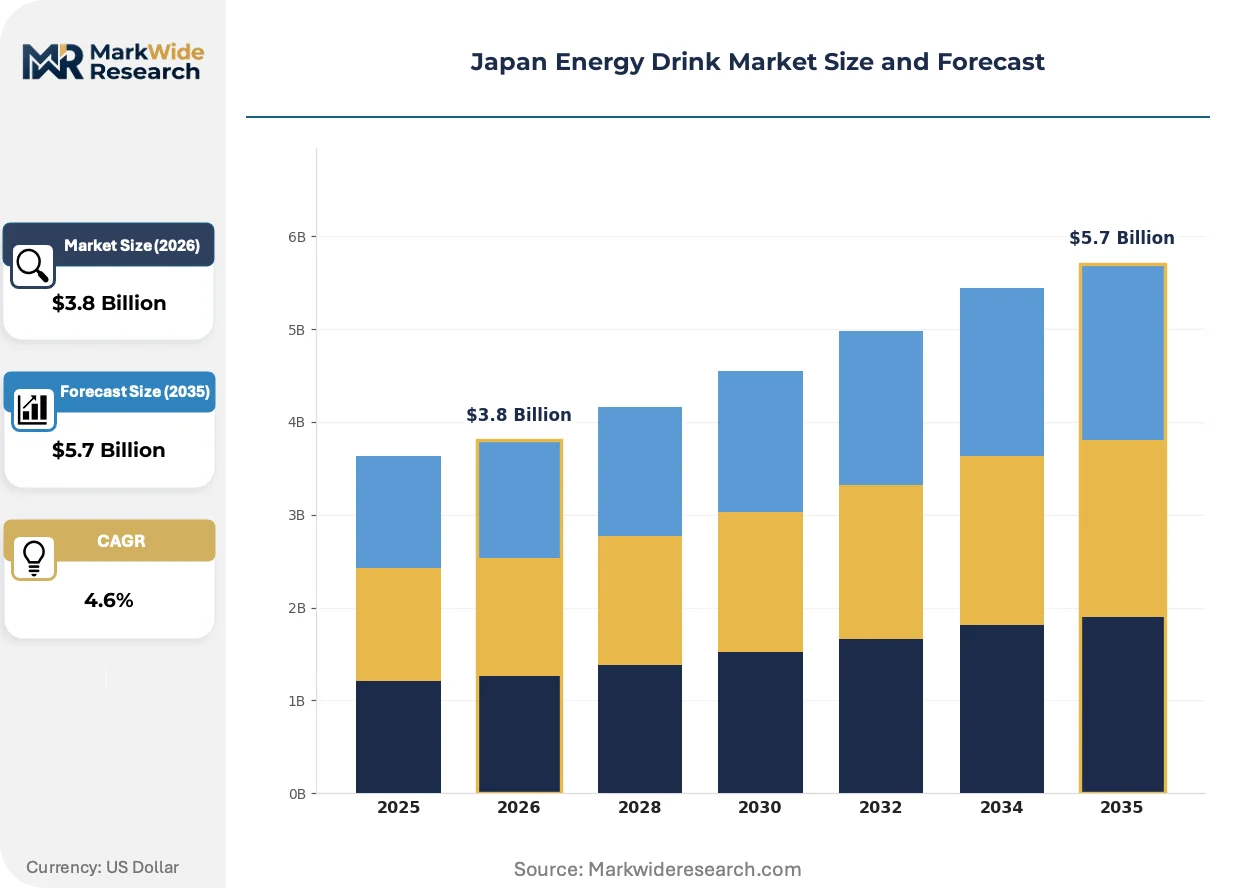
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Organic, Sugar-Free Target Audience: Students, Athletes, Working Professionals, Gamers Distribution Channel: Hypermarkets, Convenience Stores, Online Retail, Fitness Centers Flavor Profile: Citrus, Berry, Tropical, Cola |
| Companies Covered | Red Bull GmbH, Taisho Pharmaceutical Holdings, Otsuka Pharmaceutical, PepsiCo, Asahi Group Holdings, Monster Energy, Suntory Beverage & Food Ltd., Ajinomoto, The Coca-Cola Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Energy Drink Market Strategic Shifts
Formulation science and channel architecture are diverging from the carbonated, sugar-heavy legacy that defined Japan's energy drink origins, creating space for still, functional-positioned alternatives with precise dosing transparency.
Microencapsulation technology for caffeine and B-vitamin stabilization is rewriting the shelf-life and efficacy consistency expectations for ambient-stored functional beverages. Major beverage conglomerates are adopting this process at pilot scale for 2025 launches. The technology is compressing the gap between pharmaceutical-grade supplement delivery and conventional liquid refreshment.
METI's proposed expansion of caffeine concentration disclosure mandates is forcing label redesigns and reformulation decisions across the competitive set. Manufacturers must now balance transparency marketing against competitive concealment of proprietary dosing strategies. The gaming-focused segment faces the steepest compliance costs due to higher per-serving caffeine loads.
Office pantries and corporate vending contracts are displacing individual convenience store purchases as the dominant acquisition mode for working professionals. Employers negotiate bulk supply agreements that prioritize brand exclusivity and customized can sizing. This shift concentrates most visibly in Tokyo's Marunouchi and Otemachi financial districts where building management controls beverage provisioning.
Japan Energy Drink Market Segmentation
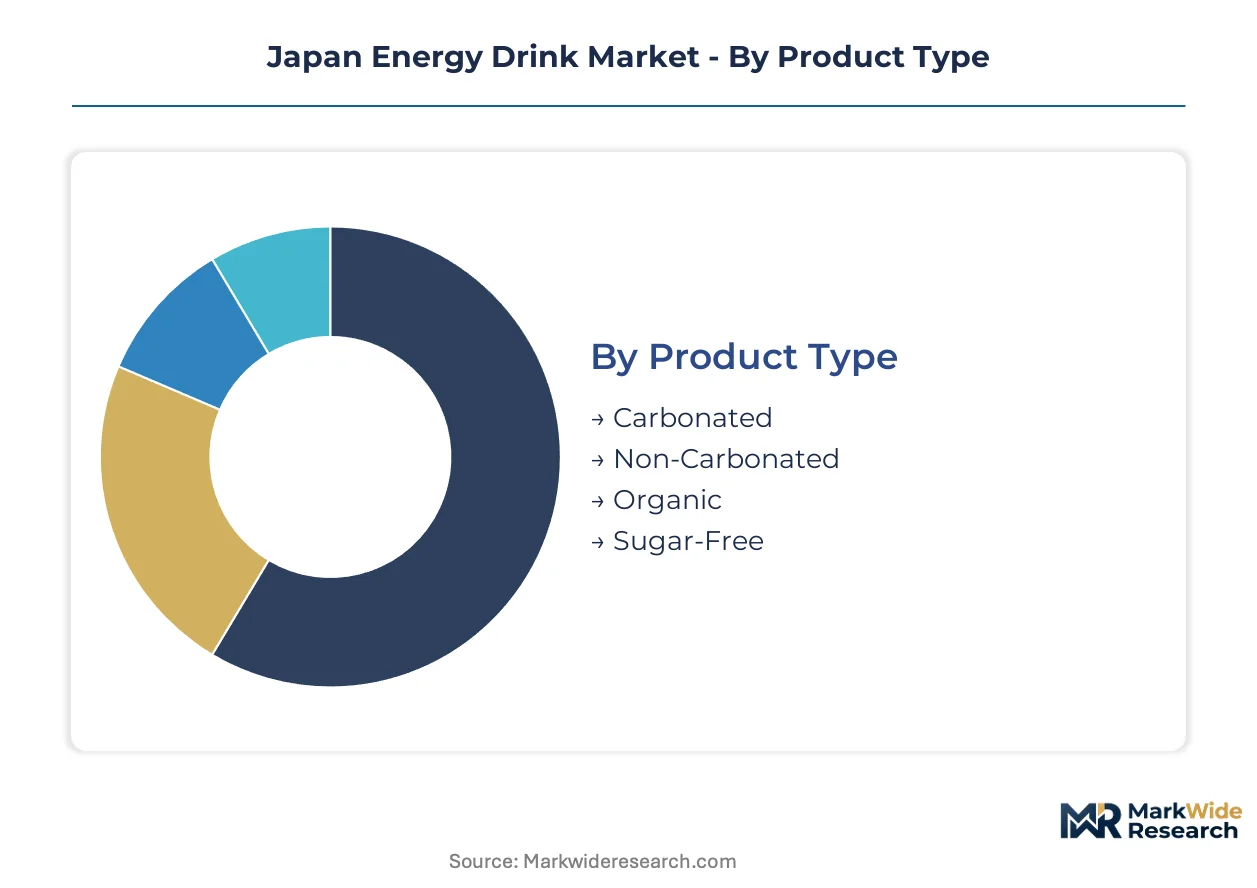
Japan's energy drink segmentation reveals how formulation technology and channel architecture determine competitive positioning. METI's functional claims framework and PMDA's quasi-drug classifications create distinct technical requirements across each axis, forcing manufacturers to align product specifications with precise regulatory boundaries.
Product Type:
Carbonation levels and sweetener systems define the technical specification spectrum, with each platform demanding distinct stabilization chemistry and shelf-life engineering.
- Sugar-Free:Non-nutritive sweetener masking technology enables palatable zero-calorie formulations. Greater Tokyo's commuter corridors concentrate demand as office workers prioritize metabolic health alongside mental alertness.
- Carbonated:Pressurized CO2 delivery systems provide rapid absorption kinetics and familiar sensory profiles. Convenience store impulse purchases in Osaka's gaming districts sustain volume leadership through established distribution infrastructure.
- Non-Carbonated:Still liquid formats suit extended consumption occasions and medicinal positioning aligned with Lipovitan D heritage.
- Organic:Certified ingredient sourcing and clean-label positioning target health-conscious segments with premium tolerance.
Mature deployment sits with Carbonated. Newer deployment is concentrated in Sugar-Free.
Target Audience:
Consumption occasion and pricing tolerance diverge sharply across demographic clusters, with knowledge workers commanding premium positioning and repeat purchase economics.
- Working Professionals:Sustained mental alertness requirements drive demand for moderate-caffeine, B-vitamin formulations in portable formats. Tokyo's Marunouchi and Otemachi financial districts concentrate corporate vending contracts and office pantry procurement.
- Gamers:Esports participants and streaming culture participants seek higher per-serving caffeine loads with rapid onset. Osaka's gaming district clusters justify dedicated flavor variants and localized distribution investment.
- Athletes:Traditional sports-centric positioning with electrolyte and amino acid stacking serves gym-adjacent consumption.
- Students:Price-sensitive examination-period demand concentrates in seasonal promotional cycles and bulk formats.
Volume leadership sits with Working Professionals. Steepest expansion trajectory is concentrated in Gamers.
Distribution Channel:
Channel concentration determines margin structure and brand access, with convenience store gatekeepers extracting significant listing fees from new entrants.
- Convenience Stores:Three retail chains control over seventy percent of impulse purchase points, favoring established domestic producers with integrated logistics and promotional budgets.
- Online Retail:Subscription direct-to-home models bypass shelf-fee compression and enable personalized formulation based on consumption pattern data.
- Hypermarkets:Bulk format and family-pack economics serve household stockpiling behavior with lower per-unit margins.
- Fitness Centers:Gym-adjacent vending and pro-shop placement targets immediate pre- and post-workout consumption with sports-specific positioning.
Established volume sits with Convenience Stores. Emerging deployment is concentrated in Online Retail.
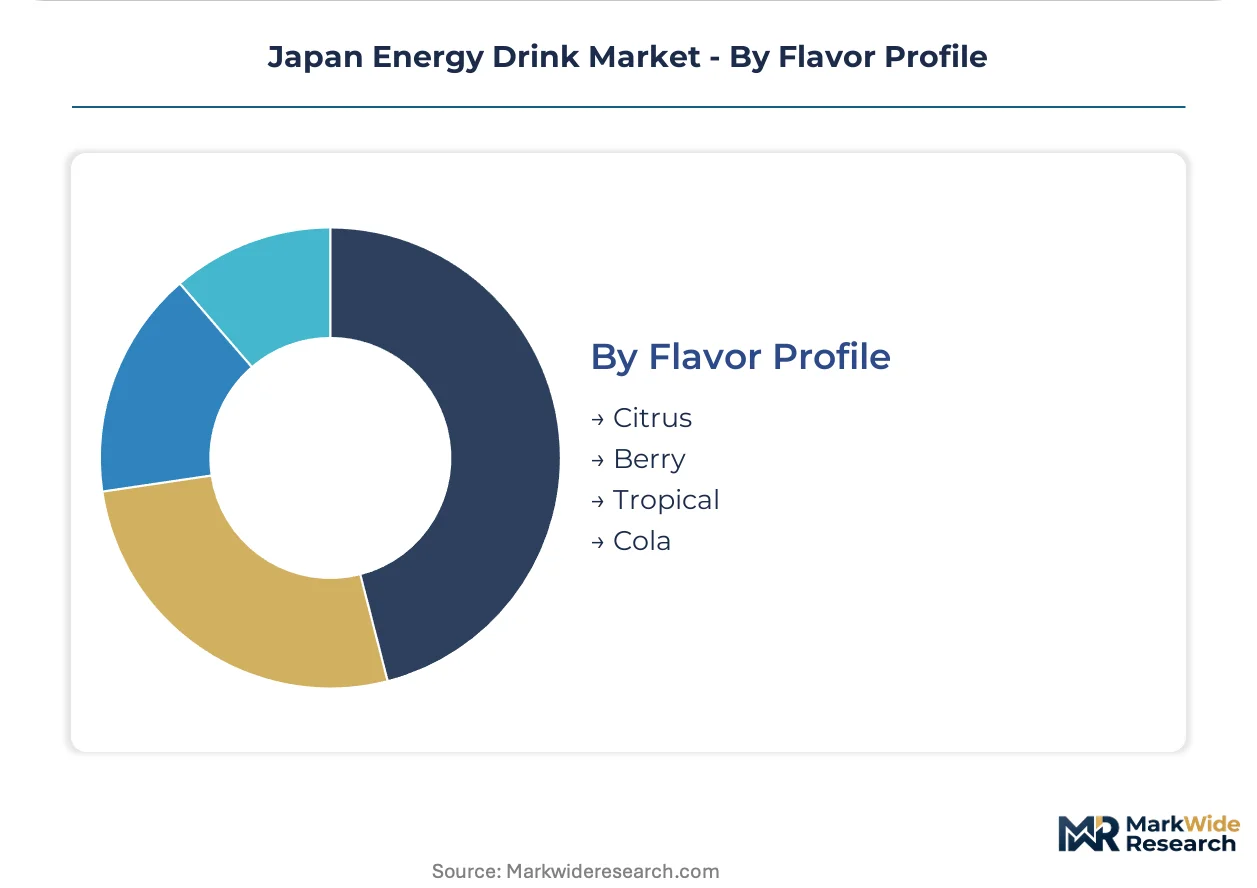
Flavor Profile:
Flavor chemistry investment separates premium positioning from commodity competition, with masking technology for active ingredients commanding specialized domestic expertise.
- Citrus:Yuzu and sudachi variants leverage indigenous fruit recognition for differentiated positioning against Western entrants.
- Berry:Acai and blueberry formulations align with antioxidant health claims permitted under METI's functional foods framework.
- Cola:Familiar taste profiles minimize trial risk for category newcomers and sustain volume in mass-market distribution.
- Tropical:Mango and passionfruit variants target younger demographics and seasonal limited-edition promotional cycles.
Stable deployment sits with Citrus. Experimental deployment is concentrated in Tropical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Special Zones for Global Startups and Foreign Investment in Tokyo and Osaka accelerate energy drink demand concentration through targeted corporate tax incentives and streamlined business establishment procedures.
Kanto/Tokyo
Marunouchi and Otemachi financial districts drive corporate vending contract proliferation as building management controls beverage provisioning. METI's Foods with Function Claims framework legitimizes efficacy statements for caffeine-based formulations. Greater Tokyo's commuter corridors concentrate sugar-free variant demand among office workers prioritizing metabolic health.
Kansai/Osaka
Osaka's gaming district clusters generate localized volume spikes from esports participants and streaming culture participants. PMDA quasi-drug classification oversight shapes borderline functional ingredient approval timelines. Dotonbori and Nipponbashi districts justify dedicated flavor variants and specialized distribution infrastructure investment.
Chubu/Nagoya
Automotive and aerospace manufacturing headquarters sustain working professional demand through shift-work patterns and precision-focused labor requirements. JIS standards for food manufacturing compliance create baseline operational requirements favoring established producers. Nagoya Station precincts concentrate convenience store impulse purchase points with integrated logistics networks.
Kyushu
Fukuoka's emerging technology workforce and startup ecosystem present underpenetrated demand relative to eastern hubs. METI regional revitalization initiatives support food and beverage sector expansion in designated special zones. Hakata district software developers and digital content creators drive trial adoption of nootropic-stacked formulations.
Hokkaido
Sapporo's winter tourism and outdoor recreation economy sustains seasonal athletic-positioned consumption. Cold-chain distribution challenges elevate operational costs for ambient-stable product formats. Susukino entertainment district concentrates late-night convenience store traffic supporting energy drink impulse purchases.
Japan Energy Drink Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with domestic pharmaceutical heritage brands commanding medicinal-tonic positioning against Western-style carbonated entrants. Market structure exhibits tiered concentration: established conglomerates with integrated beverage distribution occupy shelf-dominant positions, while mid-sized regional players compete through localized flavor development. Three strategic archetypes define competitive positioning: pharmaceutical-origin heritage brands, multinational beverage conglomerates with convenience store scale, and gaming-culture-focused lifestyle brands. Dominant competitive moves include portfolio diversification into sugar-free variants and strategic partnerships with esports tournament organizers.
Within the pharmaceutical-origin tier, Taisho Pharmaceutical Holdings and Otsuka Pharmaceutical exemplify heritage positioning through quasi-drug classification expertise and medicinal brand equity accumulated over decades. Among multinational beverage conglomerates, Suntory Beverage & Food Ltd. occupies a position reflecting integrated domestic production and convenience store channel dominance, while Red Bull GmbH represents the premium-priced international lifestyle brand archetype with extreme sports and gaming sponsorship infrastructure.
| Leading Market Players |
|---|
| Red Bull GmbH |
| Taisho Pharmaceutical Holdings |
| Otsuka Pharmaceutical |
| PepsiCo |
| Asahi Group Holdings |
| Monster Energy |
| Suntory Beverage & Food Ltd. |
| Ajinomoto |
| The Coca-Cola Company |
| Others |
Value Chain & Pricing Dynamics
Premium-mass bifurcation between METI-certified functional claims and commodity carbonated offerings manifests in divergent margin structures and sourcing strategies across Japan's energy drink landscape. Pharmaceutical-origin heritage brands command formulation premiums through PMDA quasi-drug pathways, while Western-style entrants absorb convenience store listing fees that compress net pricing power.
Pricing Analysis
Short-lead-time premiums for just-in-time convenience store replenishment contrast with subscription-model discounts for direct-to-home bulk commitments. Three-tier pricing structure across premium functional-positioned, standard carbonated, and economy private-label levels reflects certification investment and channel control differentiation. Cost compression in the standard tier is intensifying because taurine import dependency exposes formulations to petrochemical feedstock volatility. Students exhibit highest price sensitivity during examination-period seasonal demand spikes, while working professionals in Tokyo's financial districts demonstrate lowest elasticity for sustained-alertness formulations.
Supply Chain Analysis
JIS certification requirements for food manufacturing create qualification gating that favors established domestic producers with integrated quality documentation systems. Active ingredient sourcing concentrates in China for taurine synthesis, Southeast Asia for botanical extracts, and domestic fermentation facilities for amino acid production. Supply chain risk centers on single-source vulnerability for specialized flavor chemist expertise concentrated among a handful of domestic suppliers. Distribution runs through three retail chains controlling over seventy percent of convenience store impulse purchase points, with emerging subscription channels bypassing shelf-fee extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's energy drink market is consolidating around regulatory compliance capabilities and convenience store channel control, with METI disclosure mandate expansion pressuring sub-scale players lacking documentation infrastructure.
For Market Incumbents: Anchor shelf-dominant positions through backward integration into flavor chemist talent pools and accelerated JIS certification documentation systems. Defensive moves should prioritize corporate vending contract exclusivity in Tokyo's Marunouchi and Otemachi financial districts against subscription-channel disintermediation threats. Capacity addition in Fukuoka's emerging tech corridor offers geographic diversification from Kanto-Kansai concentration. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable route for bypassing convenience store gatekeeper economics and capturing margin recovery. White-space targets include Fukuoka's underpenetrated software developer workforce and nootropic-stacked formulation segments addressing knowledge worker productivity optimization. Gaming-culture positioning through esports tournament partnerships enables brand building without immediate shelf-fee burdens. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized regional players possessing METI functional claims certification and established convenience store relationships given pending disclosure mandate expansion. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than brand equity alone. The signal to watch is PMDA reclassification timelines for borderline functional ingredients that could freeze product pipelines and trigger distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Formulation Expansion | Aligns with METI-backed health consciousness reshaping Greater Tokyo commuter corridor purchasing patterns. |
| Direct-to-Consumer Subscription Launch | Bypasses convenience store listing fee extraction while enabling personalized formulation from consumption data. |
| Gaming-Culture Sponsorship Investment | Captures Osaka district cluster demand from esports participants and streaming culture participants. |
| Corporate Vending Contract Exclusivity | Secures building management-controlled provisioning in Tokyo's Marunouchi and Otemachi financial districts. |
| Nootropic Ingredient Stacking | Addresses productivity optimization demand from knowledge workers seeking cognitive enhancement beyond caffeine. |
Study Parameters
Multi-period observation of METI functional claims registrations, PMDA quasi-drug approval timelines, and convenience store distribution expansion anchored the trend analysis, supplemented by interviews with beverage brand managers, category buyers at retail chains, regulatory affairs specialists, and flavor chemistry R&D directors. Secondary validation drew from METI Foods with Function Claims database disclosures, customs import records for taurine and active ingredients, JIS standards documentation, and corporate filings from integrated beverage conglomerates. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit data.
Segment-weighting across product type, target audience, distribution channel, and flavor profile dimensions determined value allocation throughout the forecast period. CAGRs were derived from trend extrapolation moderated by regulatory timeline uncertainty and channel shift elasticity coefficients. Industry-specific inputs included METI disclosure mandate implementation schedules, PMDA reclassification precedent patterns, and convenience store shelf-space allocation algorithms.
Inputs from regulatory filing databases and retail channel partners were available through the study window; gaps in real-time subscription channel transaction data introduce uncertainty bands around direct-to-consumer growth trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Indonesia Bottled Water Market
Beverages
Morocco Bottled Water Market
Beverages
Apple Juice Concentrate Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Grab and Go Bottles Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Powdered Beverages Market
Beverages
Ready to Drink Premixes Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Fruit Vinegar Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Premium Bottled Water Market
Beverages
United States Recovery Drinks Market
Beverages
Caffeine-Based Drinks Market