
 North America Fruit Juice Market | 2026-2036
North America Fruit Juice Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fruit Juice Market Intelligence
Market Context with Strategic Players
Premium not-from-concentrate certification is rotating volume toward higher-margin shelf positions across North American retail. PepsiCo leverages its bottling network to sustain refrigerated distribution reach, while Tropicana Brands Group anchors Florida citrus sourcing for NFC supply security. The Coca-Cola Company competes through Simply Orange brand strength in the chilled premium segment. Keurig Dr Pepper differentiates via multi-format portfolio breadth spanning concentrates, ready-to-drink bottles, and food service fountain systems.
Technical Definition and Structural Segments
North America fruit juice comprises aqueous extracts from whole or processed fruits, typically standardized to specific Brix levels and pasteurized for shelf stability, serving as a beverage base, ingredient, or standalone refreshment product across retail and commercial channels. NFC juice commands the dominant value share due to consumer preference for minimal processing and clean-label positioning, while concentrated juice retains cost advantages in bulk beverage manufacturing and institutional food service procurement. Tetra Pak cartons lead packaging type margins in ambient retail, though pouches are gaining traction in convenience channel single-serve formats and children's lunchbox segments.
Regulatory Frame and Forward-Looking Close
The FDA governs juice safety through Hazard Analysis Critical Control Point mandates and pasteurization standards, while USDA organic certification shapes premium positioning and price architecture across the category. Health Canada enforces parallel juice labeling and safety protocols that govern cross-border product movement and harmonized North American supply chain operations. Stakeholders must monitor evolving added-sugar disclosure requirements and state-level sugar tax proposals that could reshape formulation strategies and channel profitability.
Market Dynamics
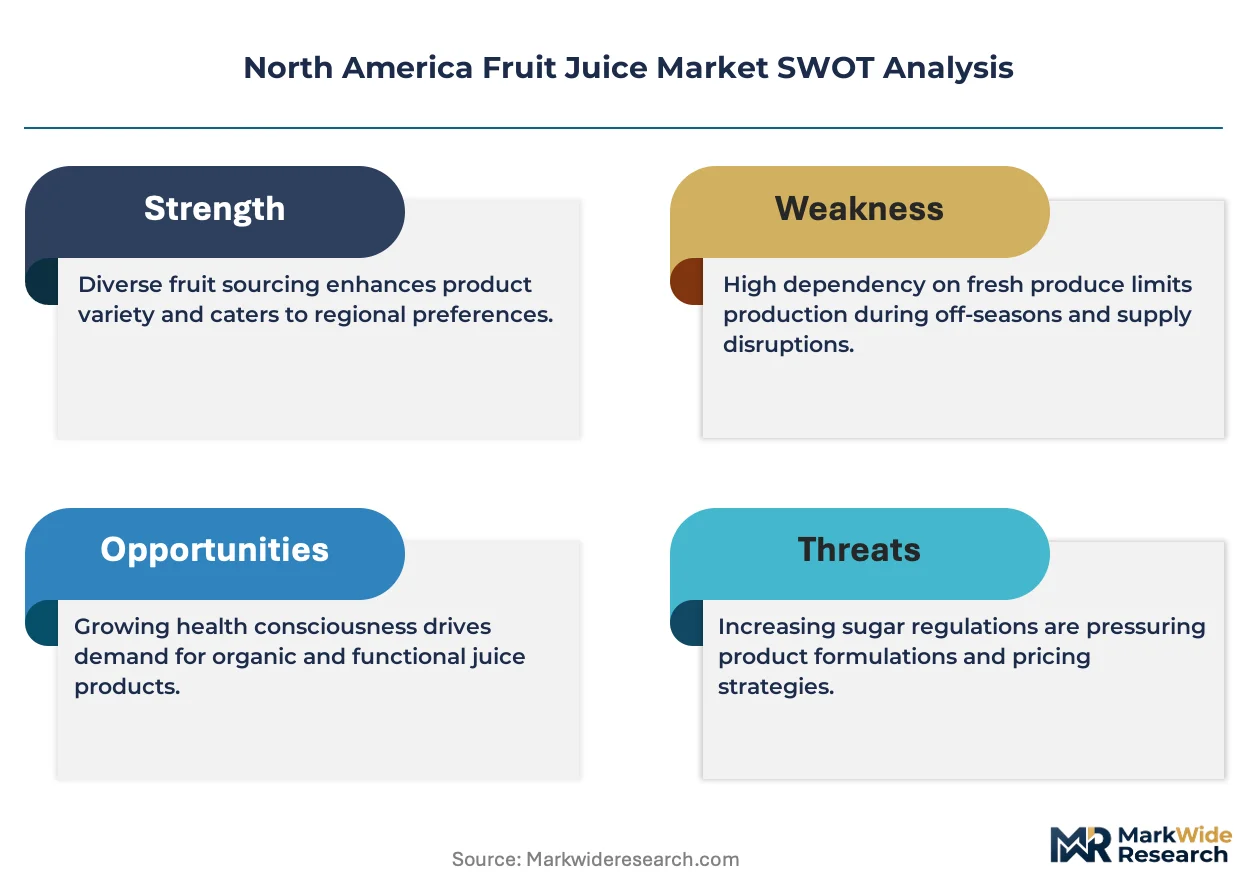
Reformulation pressure from the FDA's added-sugar disclosure mandate is compressing formulation pipelines and forcing portfolio restructuring across North American juice manufacturers.
Growth Catalysts
- Clean-label NFC preference:Consumer willingness to pay premium prices for not-from-concentrate certification is pulling volume toward higher-margin retail shelf positions in California and Florida.
- Food service menu expansion:Juice-forward placements at quick-service and fast-casual operators are creating new demand pull through fountain and grab-and-go formats.
- USDA organic certification premium:Organic juice segments command price architecture separation from conventional products, supporting margin defense amid input cost volatility.
Market Restraints
- Florida citrus greening disease:Huanglongbing infection rates are constraining domestic orange supply and forcing processors to source from Mexico and Brazil at elevated freight costs.
- Concentrate price volatility:Frozen concentrated orange juice futures on the Intercontinental Exchange expose bulk buyers to commodity swings that compress blending margins.
- Sugar-sweetened beverage taxes:Municipal-level excise taxes in Philadelphia, San Francisco, and Seattle are creating regulatory friction for reduced-juice blends and nectar formulations.
Strategic Opportunities
- Functional ingredient integration:Probiotic, collagen, and adaptogenic fortification is opening white space in the premium chilled segment beyond basic hydration.
- Pouch format penetration:Stand-up flexible packaging is gaining traction in convenience channel single-serve and children's lunchbox segments where portability drives repeat purchase.
- Direct-to-subscription models:Cold-pressed juice subscription services are bypassing traditional retail slotting fees and capturing lifetime value through recurring revenue.
Industry Challenges
- Pasteurization technician shortage:HACCP-certified operators are scarce in Florida and California processing corridors, constraining line speed and seasonal capacity expansion.
- Refrigerated distribution capex:Cold-chain infrastructure requirements for NFC juice limit new entrant participation and favor incumbent bottling network scale.
- Organic certification timeline:Three-year land conversion periods and documentation burdens are slowing supply response to organic price premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fruit Juice Market |
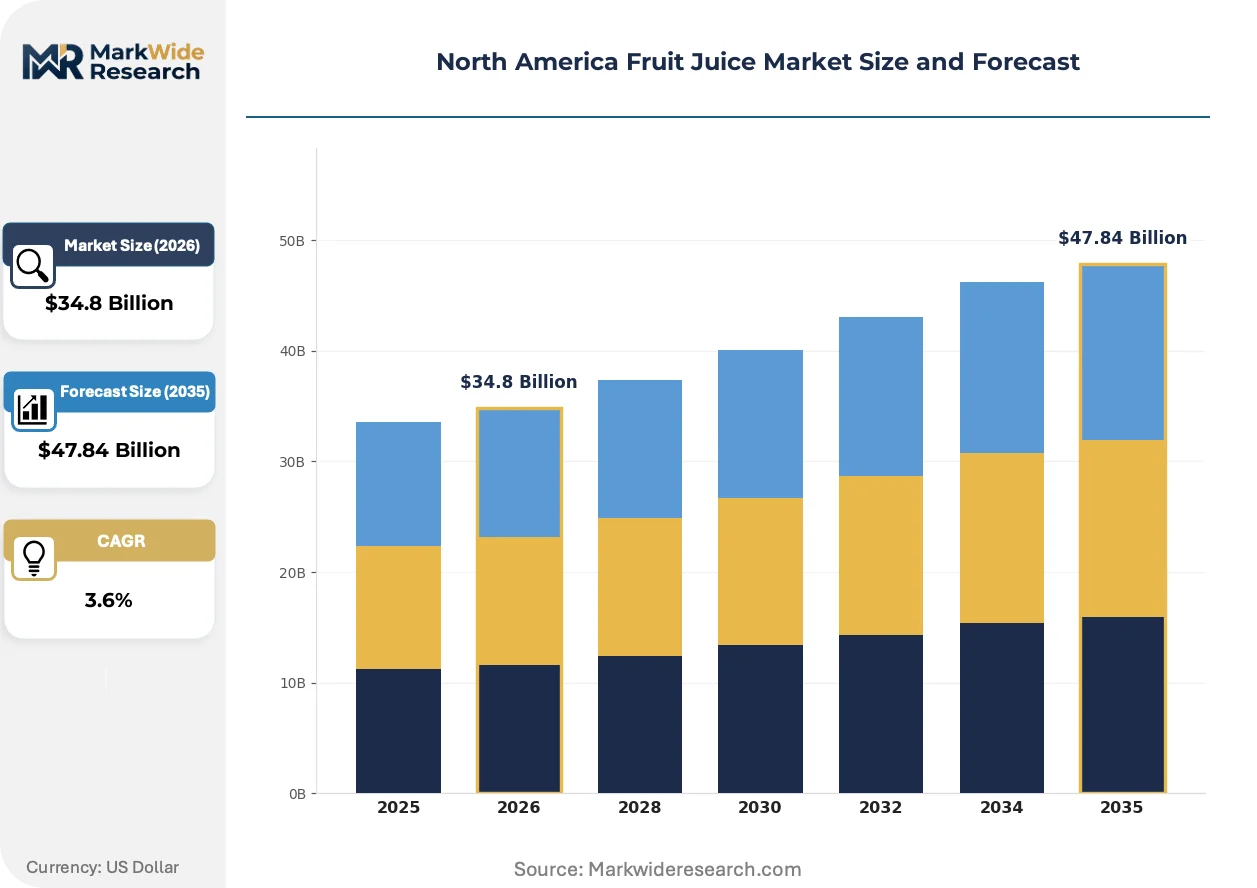
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $47.84 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Juice, NFC Juice, Puree, Fruit Drink Packaging Type: Bottles, Cartons, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Restaurants End User: Households, Food Service, Beverage Manufacturing, Catering Services |
| Companies Covered | Keurig Dr Pepper, Naked Juice, PepsiCo, Campbell's, Vita Coco, The Coca-Cola Company, Ocean Spray Cranberries, Mott's, Tropicana Brands Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fruit Juice Market Strategic Shifts & Innovations
High-pressure processing and aseptic bottling advances are collapsing the shelf-life gap between pasteurized and raw juice, reshaping competitive positioning across temperature-controlled channels.
Cold-pressed technology using hydraulic pressure rather than thermal pasteurization is fragmenting the premium juice segment into raw, HPP-treated, and lightly pasteurized sub-tiers. Wellness-focused consumers in Los Angeles, New York, and Toronto are driving adoption at double-digit velocity. This fragmentation is compressing the addressable market for conventional pasteurized chilled juices and forcing legacy brands to acquire or launch HPP sub-lines.
The FDA's updated Nutrition Facts label mandate for added sugars disclosure is forcing reformulation toward 100% juice and reduced-sugar blends. Manufacturers are responding by stripping added sweeteners from legacy recipes and repositioning products as "no sugar added." The chilled premium segment faces the steepest compliance burden, with Simply Orange and Tropicana Pure Premium requiring label and formulation synchronization across multiple stock-keeping units.
Consumer pantry loading has shifted toward multi-serve bottles and concentrate formats as post-pandemic hybrid work patterns reduce single-serve on-the-go consumption. Retailers are responding by expanding ambient shelf space for family-size Tetra Pak cartons and frozen concentrate cylinders. This rotation is most visible in suburban grocery channels across Texas, Georgia, and North Carolina where household size and commute distance correlate with bulk purchase preference.
North America Fruit Juice Market Segmentation
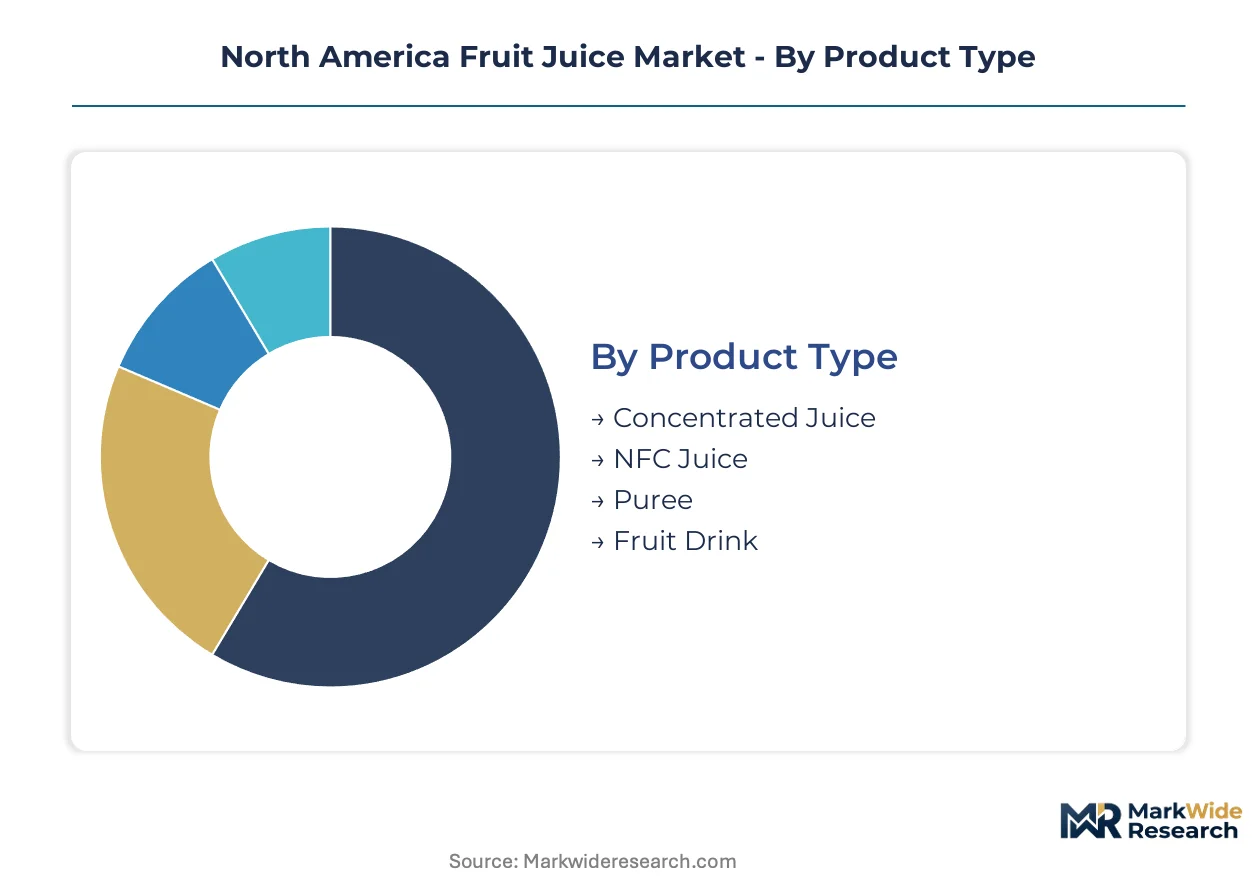
Segmentation in the North America fruit juice market reveals how processing methods, packaging formats, and channel strategies create distinct margin profiles. Each category reflects divergent capital requirements and regulatory exposure across the United States, Canada, and Mexico.
Product Type:
Domestic production concentrates in California and Florida for NFC and puree segments, while concentrated juice sourcing extends to Mexican and Brazilian supply bases.
- NFC Juice:Not-from-concentrate processing preserves volatile aromatic compounds through single-strength pasteurization without thermal concentration. Demand clusters in California and Florida retail corridors where clean-label premiums justify refrigerated logistics costs. HACCP compliance and cold-chain infrastructure create barriers that protect incumbent processor margins.
- Concentrated Juice:Thermal evaporation reduces water content to 65–72 Brix for ambient-stable bulk shipment. Export-led procurement from Mexico and Brazil exposes blenders to Intercontinental Exchange futures volatility and freight rate swings. Institutional food service and beverage manufacturing absorb volume through cost-driven procurement.
- Puree:High-viscosity fruit pulp with suspended solids serves smoothie manufacturing and infant food applications.
- Fruit Drink:Reduced-juice formulations with added water and sweeteners face municipal sugar-tax exposure in Philadelphia, San Francisco, and Seattle.
NFC Juice commands the established base. The steepest expansion runs through functional ingredient fortification in premium chilled NFC sub-lines.
Packaging Type:
Cost tier separation drives format selection, with ambient-stable cartons and Tetra Paks anchoring economy positioning while bottles and pouches capture premium mobility.
- Tetra Paks:Aseptic carton systems enable 12-month ambient shelf life without preservatives or refrigeration. Family-size multi-serve formats dominate suburban grocery channels across Texas, Georgia, and North Carolina where pantry loading behavior persists post-pandemic. Laminated paperboard structures face recycling infrastructure gaps in certain municipalities.
- Pouches:Stand-up flexible packaging with fitment closures targets single-serve convenience and children's lunchbox occasions. Los Angeles, New York, and Toronto convenience channels show fastest velocity for portable formats. Lower material weight reduces freight cost per unit versus rigid alternatives.
- Bottles:PET and glass containers dominate chilled premium shelf positioning.
- Cartons:Gable-top refrigerated cartons serve institutional food service and school nutrition programs.
Tetra Paks anchor volume throughput. Pouch formats are climbing the fastest as convenience channel penetration deepens.
Distribution Channel:
Customer type fragmentation separates household replenishment from commercial procurement, with distinct margin and service-level requirements.
- Supermarkets:Full-service grocery operators control slotting fee economics and temperature-zone shelf allocation. California and Florida retailers prioritize NFC placement in premium refrigerated sets while relegating concentrates to ambient aisles. Private-label expansion pressures branded manufacturer trade spending.
- E-Commerce:Direct-to-subscription cold-pressed services bypass traditional retail slotting structures and capture recurring revenue through membership models. Fulfillment complexity for chilled products limits participation to specialized operators with zone-skipping logistics.
- Convenience Stores:Grab-and-go single-serve velocity concentrates in urban and highway-adjacent locations.
- Restaurants:Fountain and pre-portioned formats serve quick-service and fast-casual juice-forward menu expansion.
Supermarkets retain the volume base. E-commerce subscription models are gaining share fastest in premium chilled segments.
End User:
Application maturity separates established household consumption from emerging functional beverage manufacturing demand.
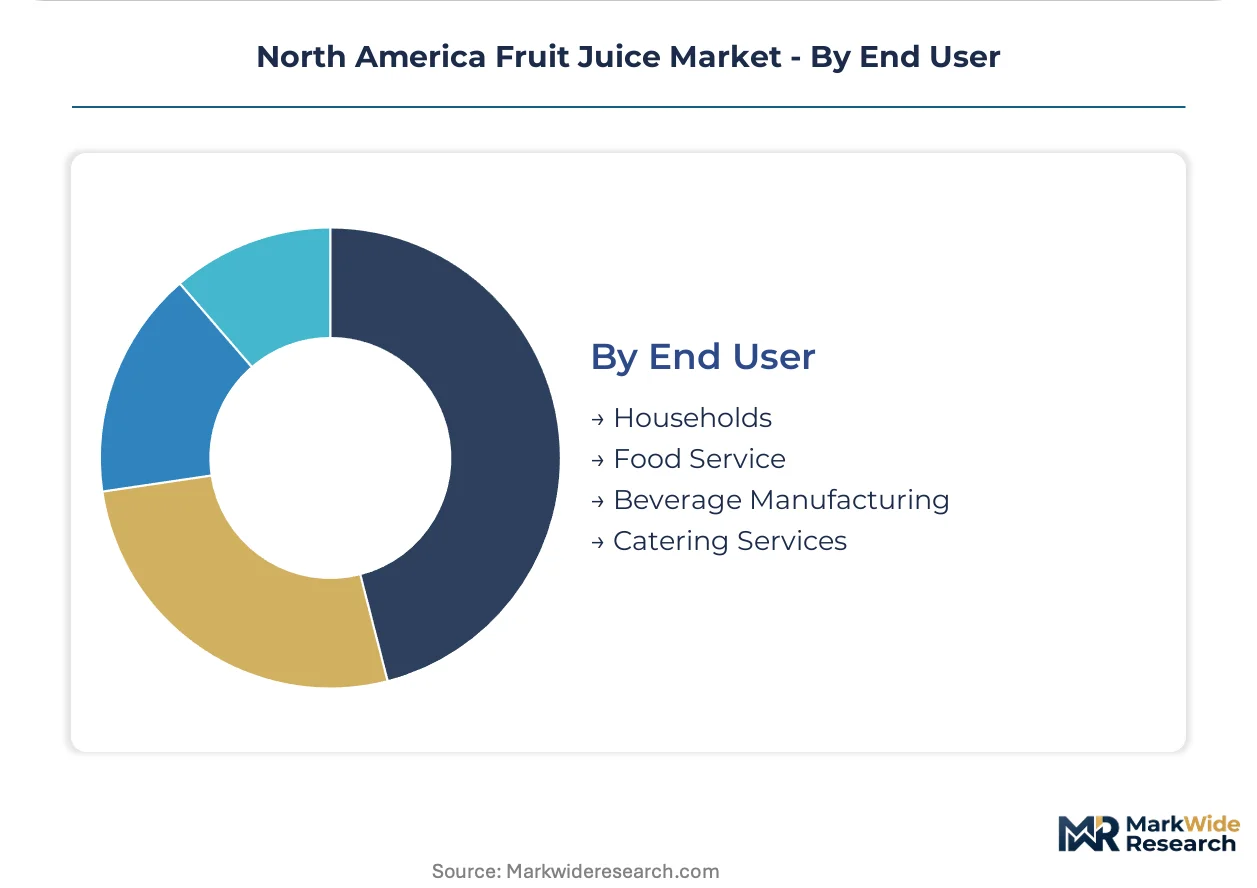
- Households:Direct consumer purchase spans breakfast occasion, hydration, and pediatric nutrition. Post-pandemic hybrid work patterns have shifted volume toward multi-serve bottles and concentrate formats as on-the-go single-serve occasions declined. Suburban household size correlates with bulk purchase preference.
- Beverage Manufacturing:Industrial procurement of concentrate and puree inputs serves ready-to-drink blenders, alcoholic mixed beverages, and functional drink formulations. Ingredient specification requirements for Brix, acidity, and microbiological standards exceed retail-grade thresholds.
- Food Service:Fountain systems and pre-portioned containers serve restaurant and institutional feeding operations.
- Catering Services:Event and corporate feeding demand concentrates in ambient-stable bulk formats.
Households anchor established demand. Beverage Manufacturing shows the steepest expansion trajectory as functional ingredient integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic processing infrastructure concentrates in California and Florida citrus belts, with Mexican and Brazilian supply bases extending concentrate sourcing. Canada and Mexico complete the regional demand triangle through divergent regulatory and consumption patterns.
United States
California and Florida anchor NFC production through established pasteurization corridors and cold-chain distribution networks. FDA HACCP mandates govern juice safety protocols and pasteurization standards across interstate commerce. Los Angeles and New York Metro drive premium chilled adoption where wellness-focused consumers pay clean-label premiums.
Canada
Health Canada enforces parallel labeling and safety protocols that harmonize cross-border product movement with US supply chains. The country's nutrition labeling requirements for added sugars mirror FDA disclosure mandates, simplifying manufacturer compliance. Ontario and Quebec retail channels concentrate volume in ambient-stable family formats aligned with suburban household purchasing patterns.
Mexico
Domestic citrus production in Veracruz and Tamaulipas supplies concentrate inputs to US blenders at freight-advantaged rates versus Brazilian alternatives. Mexican juice processors operate under COFEPRIS food safety oversight with evolving export certification alignment to FDA standards. The Bajío Region and Mexico City Metro absorb growing NFC demand as modern trade formats expand chilled distribution reach.
Florida
Huanglongbing infection rates constrain domestic orange supply and force processors toward imported concentrate blending. State agricultural extension services coordinate with USDA research programs on disease-resistant rootstock development. The Indian River citrus district maintains premium grapefruit processing capacity despite overall volume compression.
California
Central Valley stone fruit and grape processing infrastructure supports diversified NFC portfolios beyond traditional citrus. State-level Proposition 65 warning requirements add compliance layers for concentrate and reduced-juice formulations. Los Angeles cold-pressed juice subscription services bypass traditional retail slotting structures through direct-to-consumer logistics.
North America Fruit Juice Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the North American fruit juice market. Bottling network scale determines refrigerated distribution reach, while sourcing security separates premium NFC positioning from concentrate-dependent portfolios. Three archetypes dominate: multinational beverage conglomerates with integrated bottling infrastructure, specialized juice brands with regional sourcing advantages, and emerging functional beverage disruptors with cold-pressed or HPP technology. Competitive moves concentrate on portfolio diversification into reduced-sugar and functional ingredient sub-lines, alongside strategic partnerships for organic certification supply security.
Within the multinational tier, PepsiCo and The Coca-Cola Company anchor scale-driven refrigerated distribution across mass retail channels. Tropicana Brands Group exemplifies sourcing-integrated specialization through Florida citrus corridor control. Keurig Dr Pepper occupies a diversified position spanning concentrates, ready-to-drink formats, and food service fountain systems. These three represent distinct strategic postures: network scale, vertical sourcing control, and format breadth respectively.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Naked Juice |
| PepsiCo |
| Campbell's |
| Vita Coco |
| The Coca-Cola Company |
| Ocean Spray Cranberries |
| Mott's |
| Tropicana Brands Group |
| Others |
Cost & Logistics Intelligence
Sixty-day refrigerated inventory cycles in NFC juice create working capital intensity that separates scaled bottlers from undercapitalized entrants, concentrating pricing power with incumbents who command cold-chain throughput.
Pricing Analysis
The FDA's added-sugar disclosure mandate dictates the pricing tier structure across North American fruit juice. Three-tier pricing stratifies across premium chilled NFC, standard shelf-stable concentrates, and economy private-label offerings. Price differentiation rests on clean-label certification and refrigerated logistics capability rather than commodity input costs. Pricing pressure intensifies in reduced-juice formulations facing municipal sugar-tax exposure in Philadelphia, San Francisco, and Seattle. Food service buyers exhibit highest price sensitivity due to fountain system volume procurement, while direct-to-subscription consumers accept premium positioning for HPP-treated functional lines.
Supply Chain Analysis
Florida and California anchor domestic NFC pasteurization capacity, while Mexico and Brazil feed concentrate inputs through freight-advantaged corridors. Raw material sourcing draws from citrus groves, stone fruit orchards, and tropical fruit plantations with seasonal harvest windows. Supply chain risk centers on Huanglongbing disease constraining Florida orange supply and forcing elevated import dependency. Distribution runs through refrigerated trucking networks for chilled products and ambient rail-container systems for bulk concentrate shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fruit juice market is recovering from pandemic-era consumption pattern disruption as hybrid work normalization restores out-of-home breakfast occasions and food service velocity.
For Market Incumbents: Compound shelf position defense through HACCP-certified capacity expansion in California and Florida pasteurization corridors. Acquire or launch HPP sub-lines to counter cold-pressed subscription service encroachment in Los Angeles and New York Metro wellness segments. Deepen backward integration into organic citrus groves to secure three-year certification pipeline ahead of supply response lags. For New Entrants and Emerging Players: USDA organic certification fast-track offers margin separation from conventional price compression in suburban grocery channels across Texas and Georgia. Target pouch format penetration in convenience channel single-serve occasions where portability drives repeat purchase velocity. Bypass traditional retail slotting fees through direct-to-subscription cold-pressed models with zone-skipping logistics. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates seeking portfolio rationalization away from sugar-sweetened legacy formulations. Long-term viability favors operators with integrated bottling network scale and Florida citrus sourcing security. Watch cold-pressed juice subscription churn rates as inflection indicator for premium segment saturation.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Adoption | High-pressure processing collapses shelf-life gaps between pasteurized and raw juice in premium chilled segments. |
| Organic Certification Investment | Three-year land conversion timelines create supply moats for early movers in California citrus belt expansion. |
| Pouch Format Manufacturing Scale-Up | Stand-up flexible packaging captures convenience channel velocity in children's lunchbox and single-serve occasions. |
| Direct-to-Subscription Channel Launch | Recurring revenue models bypass retail slotting economics and capture lifetime value in wellness-focused metros. |
| Functional Ingredient Fortification | Probiotic and adaptogenic integration opens white space beyond basic hydration in premium chilled NFC sub-lines. |
Research Approach
A spread of perspectives from juice processing plant managers, retail category buyers, food service procurement directors, and cold-chain logistics operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA filing databases, USDA organic certification records, Nielsen retail audit data, and Intercontinental Exchange futures pricing. Bottom-up volume triangulation across product type, packaging format, and channel segments was cross-checked against top-down macroeconomic consumption indicators.
Segmentation dimensions modeled include processing method tier, packaging temperature requirement, distribution channel structure, and end-use application across the projection horizon. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and input cost volatility. Forecast inputs incorporated citrus greening disease progression, municipal sugar-tax expansion patterns, and cold-pressed technology adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable FDA labeling enforcement and no federal sugar-sweetened beverage tax implementation; material deviation would warrant model refresh. Specific risks include Huanglongbing acceleration compressing domestic supply, refrigerated distribution capacity constraints, and organic certification backlog extending supply response timelines. Recalibration cycles align with material shifts in regulatory disclosure requirements and disease-resistant rootstock commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Global Electrolyte Drinks Market
Beverages
Kvass Market
Beverages
Middle East Energy Drinks Market
Beverages
North America Cold Pressed Juices Market
Beverages
Fruit Vinegar Market
Beverages
Chocolate Malt Drink Market
Beverages
Apple Cider Vinegar Market
Beverages
Carbonated Soft Drinks Market
Beverages
Sports Drink Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Sparkling Soda Market
Beverages
Bottled Beverages Market
Beverages
Milk Tea Powder Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Victorian Jars Market