
 Blenders Market | 2026-2036
Blenders Market Size, Share, and Industry Trends Forecast 2026-2036
Blenders Market Analysis
China is fragmenting as the dominant blender manufacturing base, with new capacity spreading across Vietnam and Indonesia as brands diversify sourcing. SharkNinja Operating LLC leverages direct-to-consumer channel control to sustain premium pricing power in North America. Vitamix Corporation anchors its position through in-house motor and container production, while Breville Group Limited differentiates via design-led kitchen integration.
Blenders are motorized appliances that shear, puree, and emulsify food and beverages through rotating blades driven by electric motors typically rated between 300 and 2,000 watts. Countertop and professional blender categories carry the deepest margin pools, as stainless steel drive components and variable speed controls justify premium positioning. Immersion blenders compete on convenience and space efficiency, while portable units target single-serve demand among mobile consumers.
FCC certification governs electromagnetic emissions for US-bound units, while EU REACH compliance restricts hazardous substances in plastic housings and rubber seals. The US Department of Energy's appliance efficiency standards shape motor specifications, and California's Title 20 regulations impose standby power limits that influence control board design. Stakeholders must monitor how tightening efficiency mandates in multiple jurisdictions reshape component sourcing and product architecture decisions.
Market Dynamics
Menu diversification across quick-service restaurant chains is compressing equipment refresh cycles as operators seek multi-function appliances that reduce counter footprint and labor steps.
Growth Catalysts
- EU Ecodesign Directive:Mandatory motor efficiency standards are pulling manufacturers toward brushless DC architectures and permanent magnet designs that cut energy draw.
- Commercial kitchen automation:Quick-service restaurants in the United States are specifying programmable blenders with preset cycles to standardize beverage output across franchise locations.
- Stainless steel drive components:Premium countertop units now specify hardened steel couplings and sealed bearings that extend service intervals and justify replacement premiums.
Market Restraints
- Copper and rare earth magnet costs:Motor winding materials face price volatility that compresses margins on mid-tier units without pricing power.
- China supply concentration:Plastic housing and PCB assembly clusters in Guangdong and Zhejiang create single-source exposure for brands without dual-sourcing.
- Immersion blender ceiling:Handheld units lack the torque and thermal mass for commercial ice crushing, limiting their addressable market in foodservice.
Strategic Opportunities
- India commercial foodservice:Organized quick-service chains in Mumbai and Bangalore are underpenetrated for professional-grade blending equipment.
- California Title 20 standby limits:Tightening state-level efficiency mandates create first-mover advantage for control board designs with sub-watt idle draw.
- Voice-activated kitchen ecosystems:Integration with smart home platforms is digitizing the countertop blender as a connected appliance hub.
Industry Challenges
- FCC Part 15 certification timelines:Electromagnetic compliance testing for variable-speed motor controllers adds months to product launch schedules.
- Motor winding technician scarcity:Precision coil winding and magnet alignment skills are concentrated among aging workforces in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blenders Market |
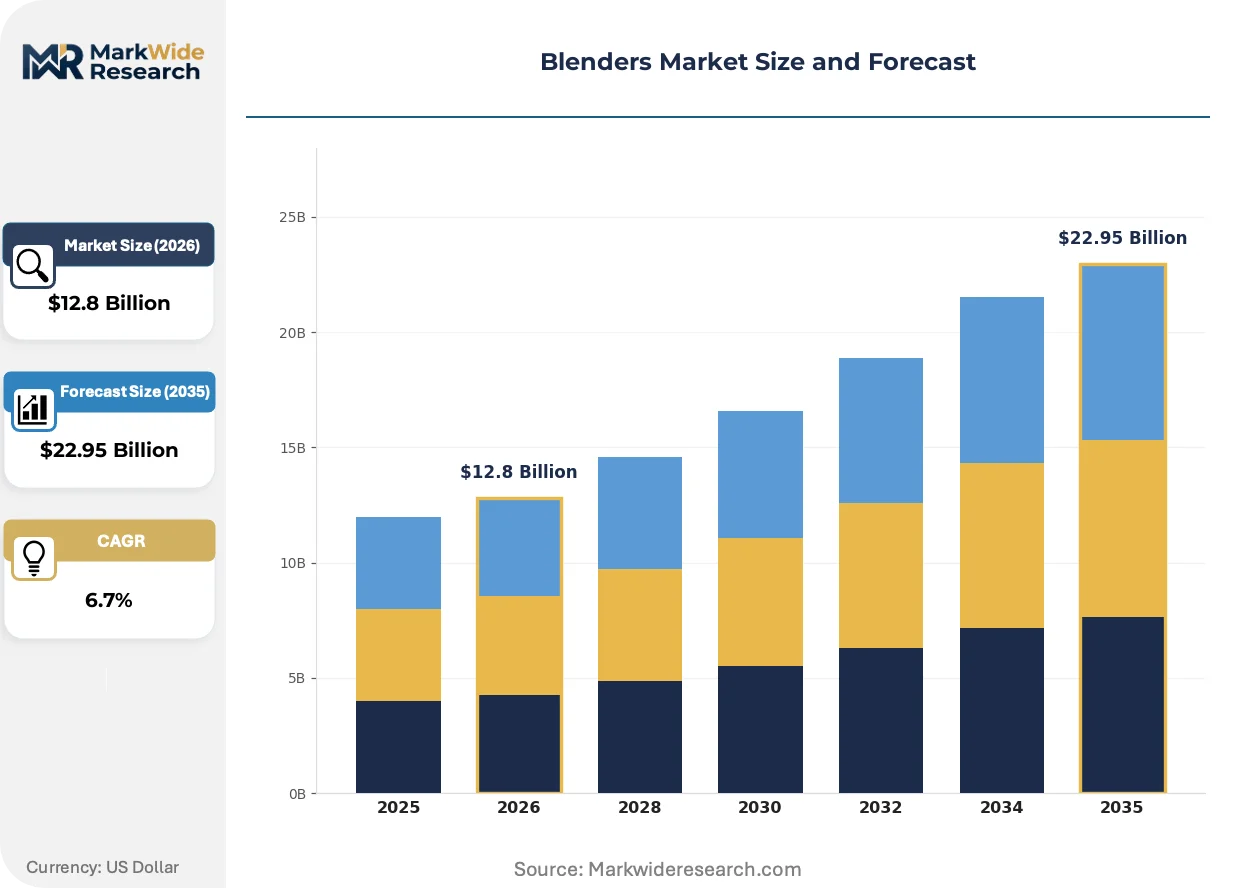
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Blenders, Immersion Blenders, Portable Blenders, Professional Blenders End User: Home Consumers, Restaurants, Cafés, Smoothie Bars Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Capacity: Single Serve, Small Batch, Large Capacity, Variable Capacity |
| Companies Covered | Smeg S.p.A., SharkNinja Operating LLC, Panasonic Corporation, Hamilton Beach Brands Holding Company, Breville Group Limited, Whirlpool Corporation, Groupe SEB, Vitamix Corporation, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blenders Market Emerging Trajectories
Intelligent motor control and material substitution are converging to redefine performance benchmarks and compliance architectures across blender categories.
Variable-frequency drive technology is digitizing speed modulation in professional-grade units. High-volume juice bar operators in California and Florida are specifying drives with 100+ distinct speed steps to achieve texture consistency for nut milks and frozen bases. This granularity is compressing the performance gap between premium countertop and full commercial equipment.
REACH substance restrictions on phthalates and brominated flame retardants are forcing housing material transitions. European manufacturers are validating glass-filled polypropylene and bio-based thermoplastics to maintain impact resistance without restricted additives. Small appliance brands serving Germany and France are responding fastest, with redesigned seals and gaskets already in certification.
Direct-to-consumer subscription attachments are altering replacement economics. Vitamix and SharkNinja now offer blade assembly and container replacement programs through owned digital channels, bypassing traditional retail parts distribution. This pattern is most visible in United States metropolitan markets where same-day delivery infrastructure supports consumable replenishment models.
Blenders Market Segmentation
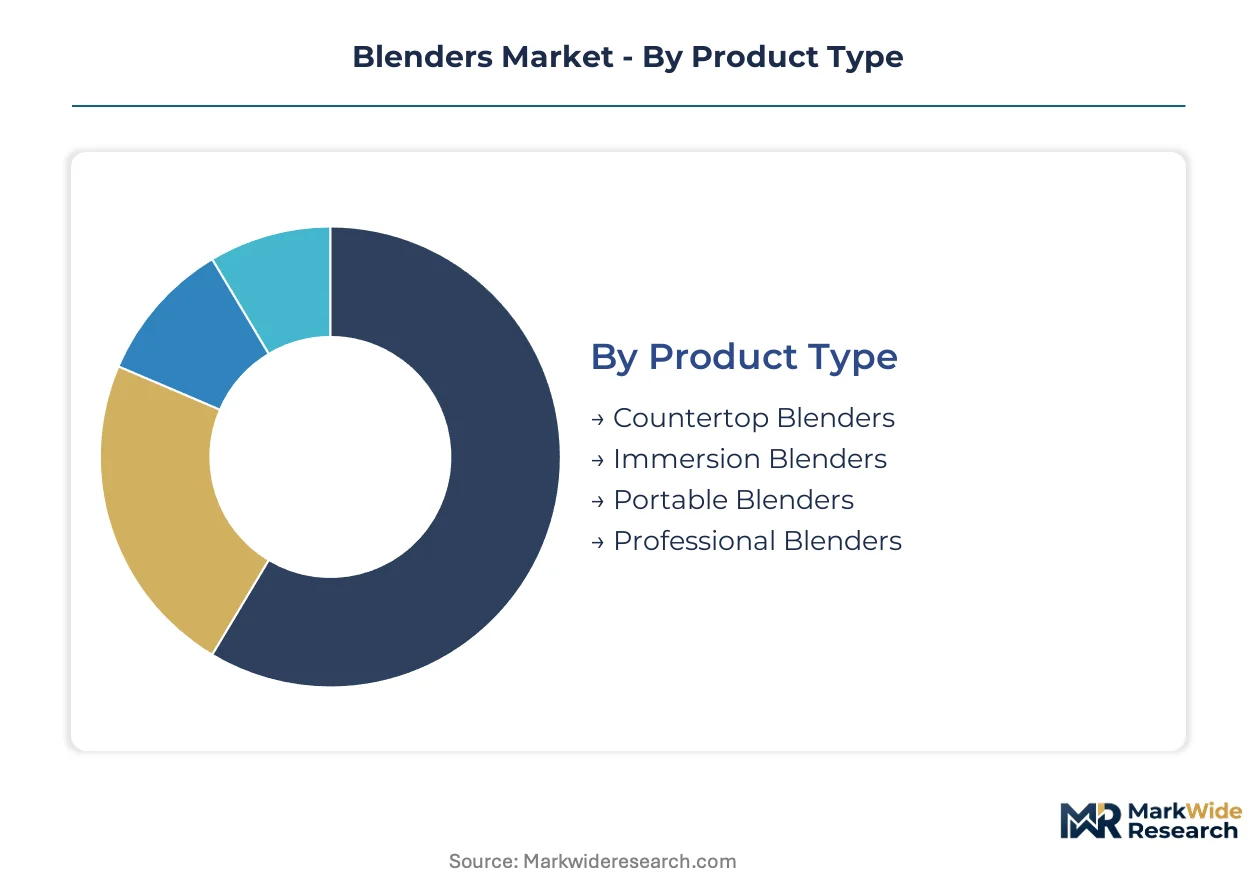
Segmentation in the Blenders Market reveals how motor wattage, container geometry, and control interfaces map to distinct margin structures and replacement cycles. Manufacturers calibrate component specifications and distribution strategies differently across each dimension, creating tiered competitive battlegrounds.
Product Type:
Cost tier differentiation separates hobbyist-grade units from equipment warrantied for continuous commercial duty cycles.
- Countertop Blenders:Stationary base units with 48-64 ounce containers and 1,000-1,500 watt motors dominate residential kitchen countertops. United States metropolitan households sustain premium pricing for variable-speed models with hardened steel drive couplings.
- Professional Blenders:Continuous-duty machines rated for 3+ horsepower and thermal overload protection anchor juice bar and commercial kitchen operations. California and Florida high-volume operators specify these for nut milk and frozen base production.
- Immersion Blenders:Handheld shaft design with 200-600 watt motors targets space-constrained food preparation. Restaurants in Mumbai and Bangalore adopt these for sauce emulsification where countertop footprint is limited.
- Portable Blenders:Battery-powered personal units with 6-16 ounce vessels serve single-serve mobility demand. USB-C charging compatibility is becoming standard specification across Asian manufacturing clusters.
Professional Blenders hold installed capacity. Portable Blenders is rotating up the share rankings.
End User:
Application intensity dictates motor thermal management requirements and warranty terms across customer categories.
- Restaurants:Full-service and quick-service operators specify programmable cycle presets to standardize output across franchise locations. United States chains are compressing equipment refresh cycles as menu diversification accelerates.
- Smoothie Bars:Dedicated beverage operators run equipment through 100+ daily cycles, demanding sealed bearings and brushless DC architectures for energy compliance under EU Ecodesign Directive mandates.
- Home Consumers:Residential purchasers prioritize aesthetic integration and storage efficiency over continuous-duty ratings. Direct-to-consumer channels capture premium pricing in North American metropolitan markets.
- Cafés:Coffee-focused operators with limited food menus select mid-tier units for intermittent blending tasks. These buyers show price sensitivity relative to dedicated smoothie operations.
Restaurants command specification authority. Smoothie Bars is climbing the fastest in absolute volume terms.
Distribution Channel:
Channel control determines margin capture and replacement part attach rates for manufacturers and retailers.
- Direct Sales:Manufacturer-owned digital channels enable subscription blade and container replacement programs. Vitamix and SharkNinja leverage this model to bypass traditional retail parts distribution in United States markets.
- Online Retail:E-commerce platforms aggregate comparison shopping and same-day delivery infrastructure. This channel is expanding fastest for portable and immersion categories among mobile consumers.
- Specialty Stores:Kitchenware retailers provide tactile evaluation and staff consultation for premium countertop purchases. These outlets sustain higher average selling prices through demonstration and education.
- Supermarkets:Mass merchandisers compete on price for entry-level countertop and immersion units. Limited sales associate expertise constrains upselling to premium tiers.
Direct Sales commands replacement economics. Online Retail is gaining share fastest through logistics infrastructure investment.
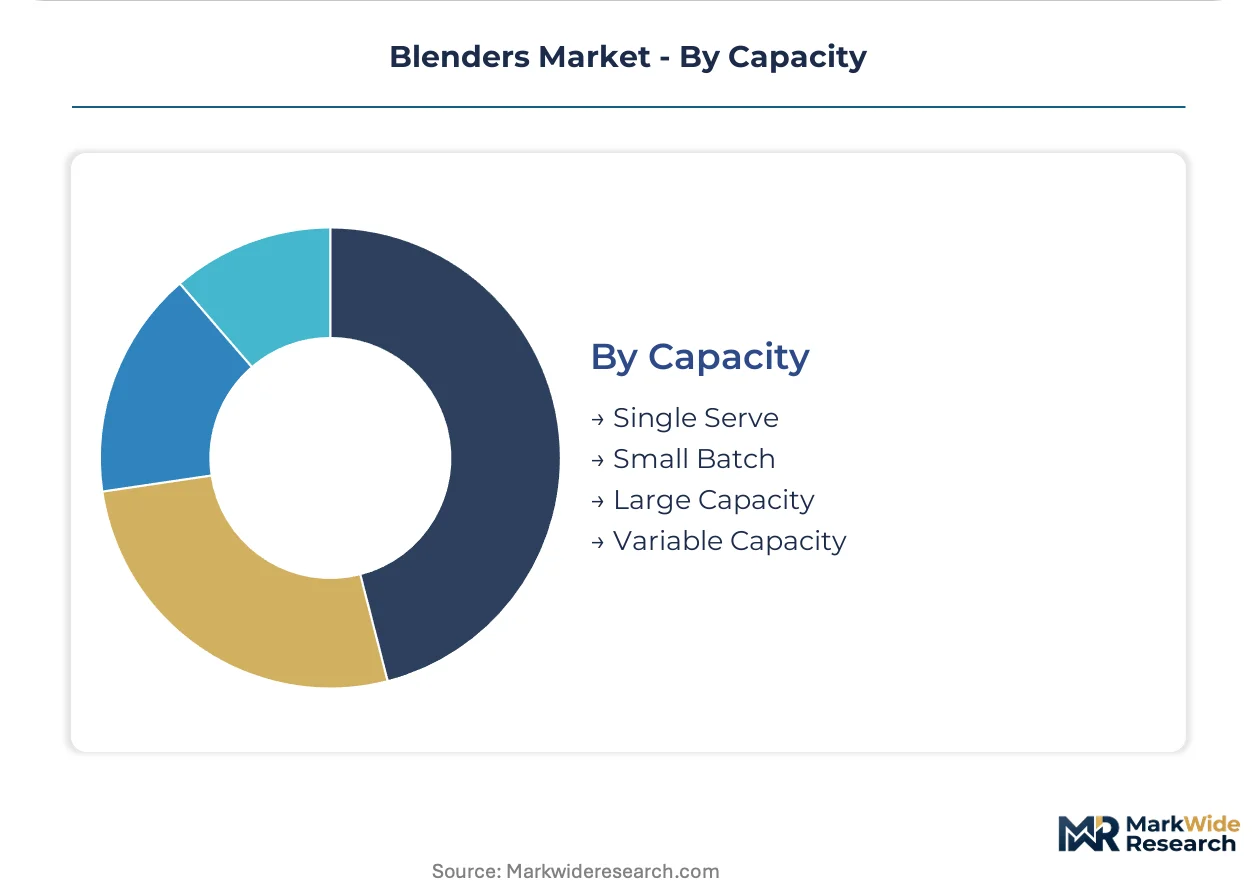
Capacity:
Volume specification aligns container geometry with batch size requirements and storage constraints.
- Large Capacity:64+ ounce containers serve commercial batch production and family-sized residential use. Quick-service restaurant chains in the United States specify these for back-of-house efficiency.
- Variable Capacity:Modular container systems with interchangeable vessels adapt to task requirements. Premium countertop manufacturers are expanding these configurations for kitchen versatility.
- Single Serve:12-20 ounce vessels match individual consumption patterns and support portability. Battery-powered units in this category target gym and office use cases.
- Small Batch:32-48 ounce containers bridge residential and light commercial applications. These units face margin pressure from adjacent category competition.
Large Capacity anchors foodservice procurement. Variable Capacity is expanding most quickly through premium residential positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blender manufacturing capacity concentrates in Guangdong and Zhejiang provinces, though Vietnam and Indonesia are absorbing incremental assembly as brands diversify sourcing footprints. Demand patterns diverge sharply across regulatory environments and foodservice development stages.
United States
Quick-service restaurant chains in California and Florida compress equipment refresh cycles as menu diversification accelerates. The Department of Energy's appliance efficiency standards and California's Title 20 standby power limits reshape motor and control board specifications. SharkNinja and Vitamix anchor premium countertop demand through direct-to-consumer channels in metropolitan markets.
China
Guangdong plastic housing and PCB assembly clusters supply global OEM demand despite single-source exposure risks. MIIT motor efficiency guidelines and dual carbon goals push manufacturers toward brushless DC architectures. Zhejiang and Jiangsu provinces host expanding capacity for stainless steel drive components serving professional-grade export orders.
Germany
EU Ecodesign Directive mandates pull manufacturers toward permanent magnet motor designs that cut energy draw. REACH substance restrictions on phthalates and brominated flame retardants force housing material transitions to glass-filled polypropylene. Bavaria and Baden-Württemberg industrial zones concentrate precision coil winding capabilities among aging technical workforces.
India
Organized quick-service chains in Mumbai and Bangalore remain underpenetrated for professional-grade blending equipment. BIS appliance safety standards and FSSAI food contact material regulations govern import specifications. Maharashtra and Karnataka commercial kitchen operators increasingly specify programmable units for beverage standardization across franchise locations.
Vietnam
New assembly capacity serves brands diversifying beyond China concentration. General functional descriptors for national trade and industry guidance shape local content requirements. Ho Chi Minh City and Hanoi industrial parks absorb portable and immersion blender production previously concentrated in Pearl River Delta facilities.
Blenders Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on motors and sealed bearings. The vendor base stratifies across three performance tiers: premium countertop, professional continuous-duty, and mass-market convenience. Two strategic archetypes dominate: vertically integrated manufacturers with in-house motor production, and design-led brands outsourcing assembly while controlling distribution. Competitive moves concentrate on direct-to-consumer channel capture and subscription-based replacement part programs.
Within the premium-tier vector, Vitamix Corporation and SharkNinja Operating LLC exemplify divergent channel strategies—one anchored in specialty retail demonstration, the other in owned digital infrastructure. Breville Group Limited occupies a position among design-led kitchen integrators. Panasonic Corporation and Koninklijke Philips N.V. represent diversified electronics conglomerates leveraging appliance portfolio breadth. Smeg S.p.A., Hamilton Beach Brands Holding Company, Whirlpool Corporation, and Groupe SEB each sit within distinct archetypes spanning luxury positioning, mass-market penetration, white-label supply, and multi-brand portfolio management.
| Leading Market Players |
|---|
| Smeg S.p.A. |
| SharkNinja Operating LLC |
| Panasonic Corporation |
| Hamilton Beach Brands Holding Company |
| Breville Group Limited |
| Whirlpool Corporation |
| Groupe SEB |
| Vitamix Corporation |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Vietnam's portable blender assembly sector is pulling component suppliers toward extended payment terms and volume commitments, compressing margins for mid-tier brands while reinforcing pricing power for vertically integrated manufacturers with captive motor production.
Pricing Analysis
EU Ecodesign Directive dictates the pricing tier structure across the blender market, separating brushless DC motor configurations from conventional induction motor units. Premium-mid-economy pricing differentiation rests on certification grade and thermal overload protection specifications. Cost compression in mid-tier countertop units is intensifying because copper winding and rare earth magnet inputs face commodity volatility. Home consumers in North American metropolitan markets show lowest price sensitivity, while cafés with intermittent blending tasks exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Guangdong PCB assemblers are tightening working capital requirements for brands without supply-chain finance facilities. Manufacturing capacity concentrates in China, Vietnam, and Indonesia, with Zhejiang stainless steel drive component clusters feeding professional-grade export demand. Raw material dependencies center on copper motor windings, neodymium permanent magnets, and glass-filled polypropylene housings. Single-source vulnerability in Guangdong plastic injection molding creates tariff exposure for brands lacking dual-sourcing. Distribution runs through manufacturer-owned digital channels, specialty kitchenware retailers, and mass merchandisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blender market sits in early-cycle expansion as quick-service restaurant menu diversification accelerates equipment refresh frequency and pulls programmable units into underpenetrated commercial kitchens.
For Market Incumbents: Entrench position through backward integration into brushless DC motor production and permanent magnet supply chains. Acquire precision coil winding capabilities in Germany or Japan before technical workforce attrition accelerates. Defend against emerging design-led entrants by locking exclusive container geometry patents and expanding subscription blade replacement programs.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's organized quick-service chains, where professional-grade equipment penetration lags Mumbai and Bangalore expansion rates. Target voice-activated kitchen ecosystem integration as a go-to-market angle, partnering with smart home platform providers to bypass established retail channel barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because motor control IP and direct-to-consumer channel infrastructure are concentrating among a narrowing set of platform owners. Acquisition targets should display in-house permanent magnet motor production or captive sealed bearing supply. Monitor California Title 20 standby power compliance timelines as the signal for which control board designs will capture next-generation specification authority.
| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Transition | EU Ecodesign Directive compliance locks in energy efficiency positioning for premium tiers. |
| Direct-to-Consumer Channel Expansion | Owned digital infrastructure captures replacement part economics bypassing retail distribution. |
| Voice-Activated Platform Integration | Smart home ecosystem partnerships digitize countertop appliances as connected kitchen hubs. |
| Dual-Sourcing Supply Chain Diversification | Vietnam and Indonesia capacity absorption reduces Guangdong single-source concentration risk. |
| Subscription Replacement Program Launch | Blade assembly and container replenishment models lock in recurring revenue from installed base. |
Methodological Framework
Initial hypotheses were tested against primary input from quick-service restaurant equipment procurement managers, commercial kitchen operators, appliance brand product development executives, and motor component suppliers and refined through secondary validation against SEC filings, customs trade records, EU Ecodesign Directive implementation documents, and DOE appliance efficiency standard dockets. Bottom-up demand modeling triangulated with top-down market sizing across motor wattage tiers and end-use intensity segments.
Demand-supply-balance dynamics anchored the analytical framework throughout the projection horizon. Segmentation dimensions included product type, end user category, distribution channel, and container capacity configuration. CAGRs were derived from equipment refresh cycle compression rates and menu diversification penetration curves. Industry-specific inputs incorporated FCC Part 15 certification timelines and REACH substance restriction phase-in schedules.
Sensitivities concentrate around copper and rare earth magnet price volatility, China tariff regime adjustments, and California Title 20 standby power limit enforcement timing. Forecasts reflect assumptions on quick-service chain expansion rates and smart home platform adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Carbonated Beverages Market
Beverages
Plant Based Protein Beverages Market
Beverages
Chill Block Market
Beverages
Kombucha Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Hydration Infusers Market
Beverages
Extra Neutral Alcohol (ENA) Market
Beverages
Extra Virgin Olive Oil Market
Beverages
Packaged Milkshake Market
Beverages
Europe Bottled Water Market
Beverages
Caffeinated Beverage Market
Beverages
Bottled Air Market
Beverages
Fruit Juice Market
Beverages
Collagen Drinks Market
Beverages
Sports and Energy Drinks Market
Beverages
Caffeine Mint Market